
 AI As a Service (Aiaas) Market | 2026-2036
AI As a Service (Aiaas) Market Size, Share, and Industry Trends Forecast 2026-2036
AI As a Service (Aiaas) Market Outlook
The EU AI Act is realigning procurement priorities across European enterprises by mandating risk-classification documentation for high-stakes AI deployments. Microsoft leverages its Azure OpenAI Service to anchor enterprise workloads with built-in compliance tooling. NVIDIA competes through vertical specialization in GPU-accelerated inference clusters that sustain performance benchmarks for regulated industries. Google differentiates via its Vertex AI platform, which controls the full model lifecycle from training to monitored production endpoints.
AI As a Service delivers machine learning, natural language processing, computer vision, and predictive analytics through cloud-hosted APIs and managed infrastructure, eliminating capital expenditure on specialized hardware while enabling elastic scaling of inference workloads. The primary commercial purpose is to democratize access to frontier AI capabilities for organizations lacking internal data-science teams or GPU clusters. Public cloud deployment dominates current revenue volumes due to pay-per-use economics and rapid provisioning, though hybrid cloud configurations are capturing faster growth as financial and healthcare institutions enforce data-residency requirements. Natural language processing solutions command premium pricing within the solution-type matrix, reflecting concentrated demand for generative text applications across customer service and legal review functions.
The US Federal Trade Commission scrutinizes deceptive AI claims under Section 5 authority, while the EU AI Act imposes conformity assessments and CE marking obligations on providers of high-risk systems. China's SAMR enforces algorithmic recommendation provisions that restrict opaque automated decision-making in consumer-facing platforms. Stakeholders must monitor divergence between Brussels-style ex-ante risk frameworks and Washington's enforcement-driven posture, as this regulatory fragmentation will determine which service architectures achieve cross-border portability without costly jurisdictional customization.
Market Dynamics
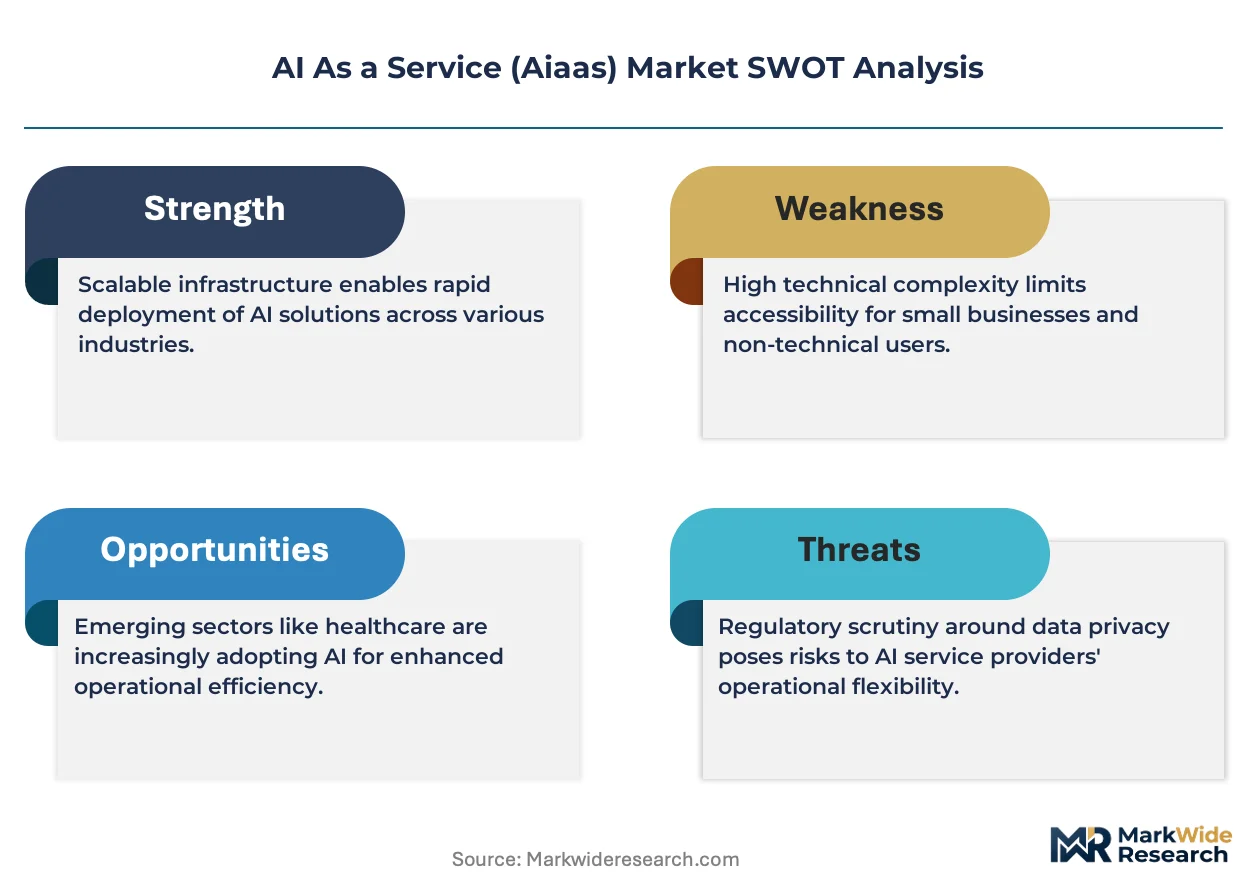
Cloud hyperscalers are consolidating inference infrastructure around sovereign AI requirements, forcing mid-market providers to specialize vertically or exit. The EU AI Act's risk-classification mandates are redrawing procurement checklists before contracts close.
Growth Catalysts
- EU AI Act compliance tooling:Enterprises in France and Germany now require documented conformity assessments for high-risk deployments, creating pull for managed services with built-in audit trails.
- Healthcare diagnostic APIs:Radiology departments across the United States are integrating computer vision models directly into PACS workflows without on-premise GPU investment.
- Edge-to-cloud orchestration:Manufacturing facilities in Japan are deploying hybrid inference architectures that route sensitive quality-control data locally while aggregating training workloads centrally.
Market Restraints
- NVIDIA GPU supply concentration:Inference cluster procurement remains bottlenecked by single-source dependency for H100 and Blackwell accelerators, extending deployment timelines.
- Cross-border data friction:China's SAMR algorithmic recommendation provisions restrict model training on consumer behavioral data, fragmenting dataset availability.
- Energy input cost volatility:Training-run electricity consumption at hyperscale datacenters faces pricing pressure from grid decarbonization mandates in Germany and California.
Strategic Opportunities
- India's PLI scheme for AI:Domestic cloud infrastructure incentives are attracting foreign providers to establish sovereign inference nodes for financial services compliance.
- Federated learning convergence:Privacy-preserving model training across hospital networks without centralizing patient records is opening regulated healthcare verticals previously closed to cloud AI.
- Outcome-based API pricing:Customer service platforms are shifting from per-call fees to resolution-rate guarantees, aligning vendor incentives with operational KPIs.
Industry Challenges
- MLOps talent scarcity:Production-grade model monitoring and drift detection require skill sets concentrated at AWS, Google, and Microsoft, leaving mid-tier providers understaffed.
- CE marking timeline compression:EU AI Act high-risk system certifications demand documentation workflows that most SaaS vendors have not operationalized, delaying market entry.
- Legacy ERP integration complexity:SAP and Oracle environments in industrial enterprises resist standard API connectors, forcing costly custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI As a Service (Aiaas) Market |
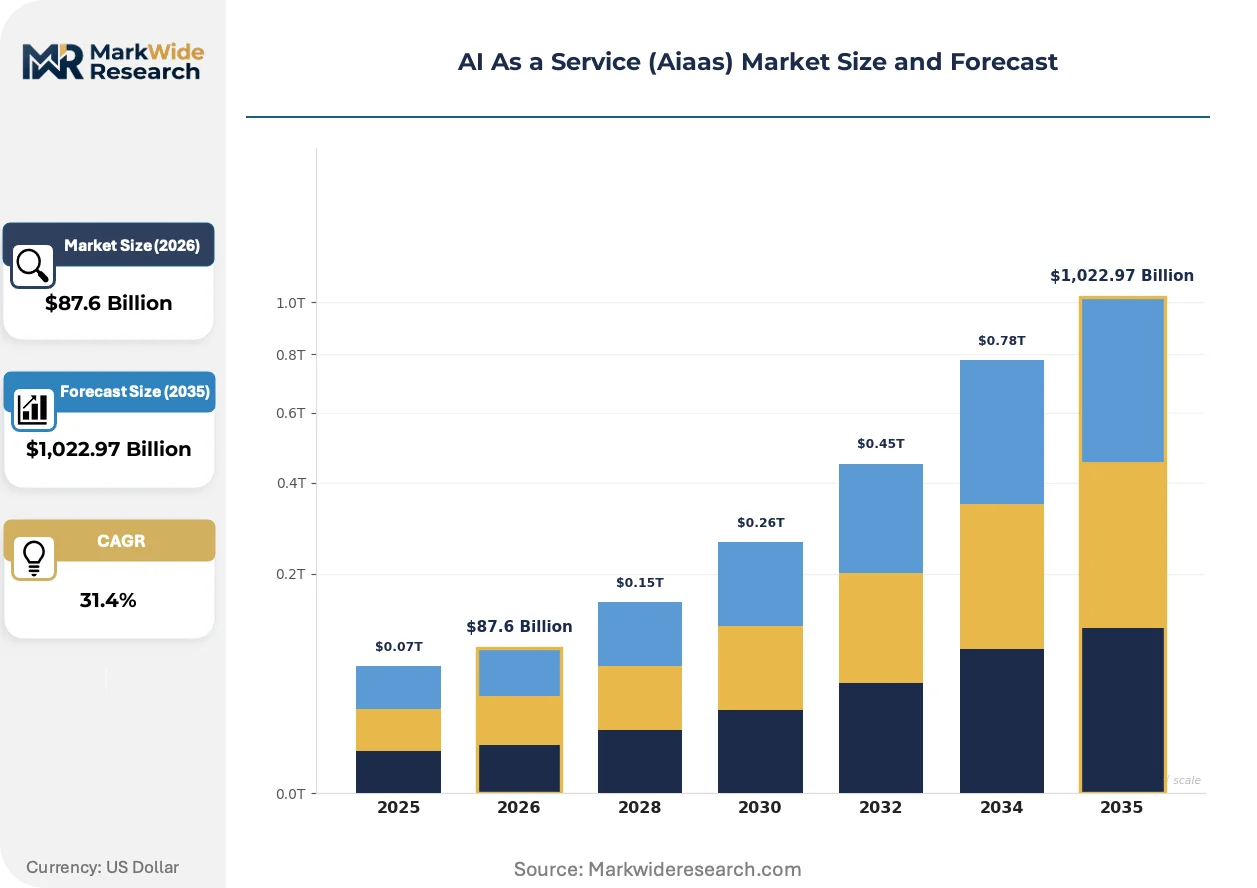
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $1,022.97 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Solution Type: Machine Learning, Natural Language Processing, Computer Vision, Predictive Analytics End User: Healthcare, Retail, BFSI, Manufacturing Service Model: Model Development, Data Analysis, API Integration, Consultancy |
| Companies Covered | Amazon Web Services, Microsoft, Google, IBM, Salesforce, Oracle, SAP, NVIDIA, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI As a Service (Aiaas) Market Strategic Shifts
Foundation model commoditization is compressing differentiation timelines, pushing providers toward vertical-specific fine-tuning and proprietary dataset moats. The competitive center is shifting from raw capability to controlled deployment environments.
Small language models optimized for domain-specific tasks are expanding into legal document review and pharmaceutical regulatory submission drafting. Enterprise legal departments at firms in London and New York are piloting these systems for contract clause extraction. The technology is compressing billable-hour models while expanding addressable matter volume.
REACH-style chemical safety documentation is expanding into algorithmic impact assessments under the EU AI Act's conformity framework. High-risk system providers must now maintain technical documentation equivalent to medical device dossiers. Financial services deployments in Frankfurt and Paris are restructuring vendor qualification processes around these requirements.
Buyer committees are consolidating AI procurement authority under Chief Data Officers, displacing decentralized experimentation budgets. Healthcare systems in the United States are centralizing model governance under single oversight offices. This concentration is visible most acutely in hospital networks across Texas and Florida, where standardization mandates now precede any cloud AI contract execution.
AI As a Service (Aiaas) Market Segmentation
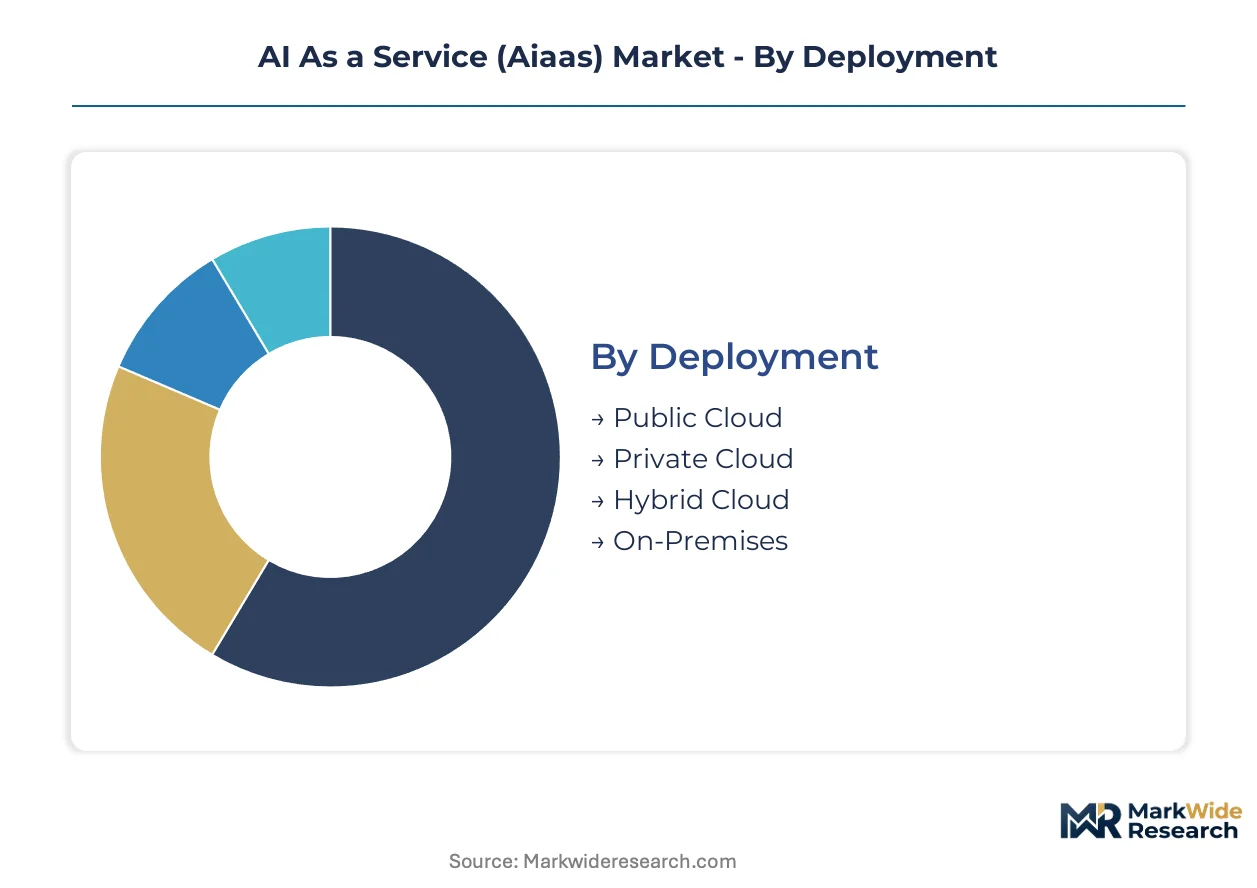
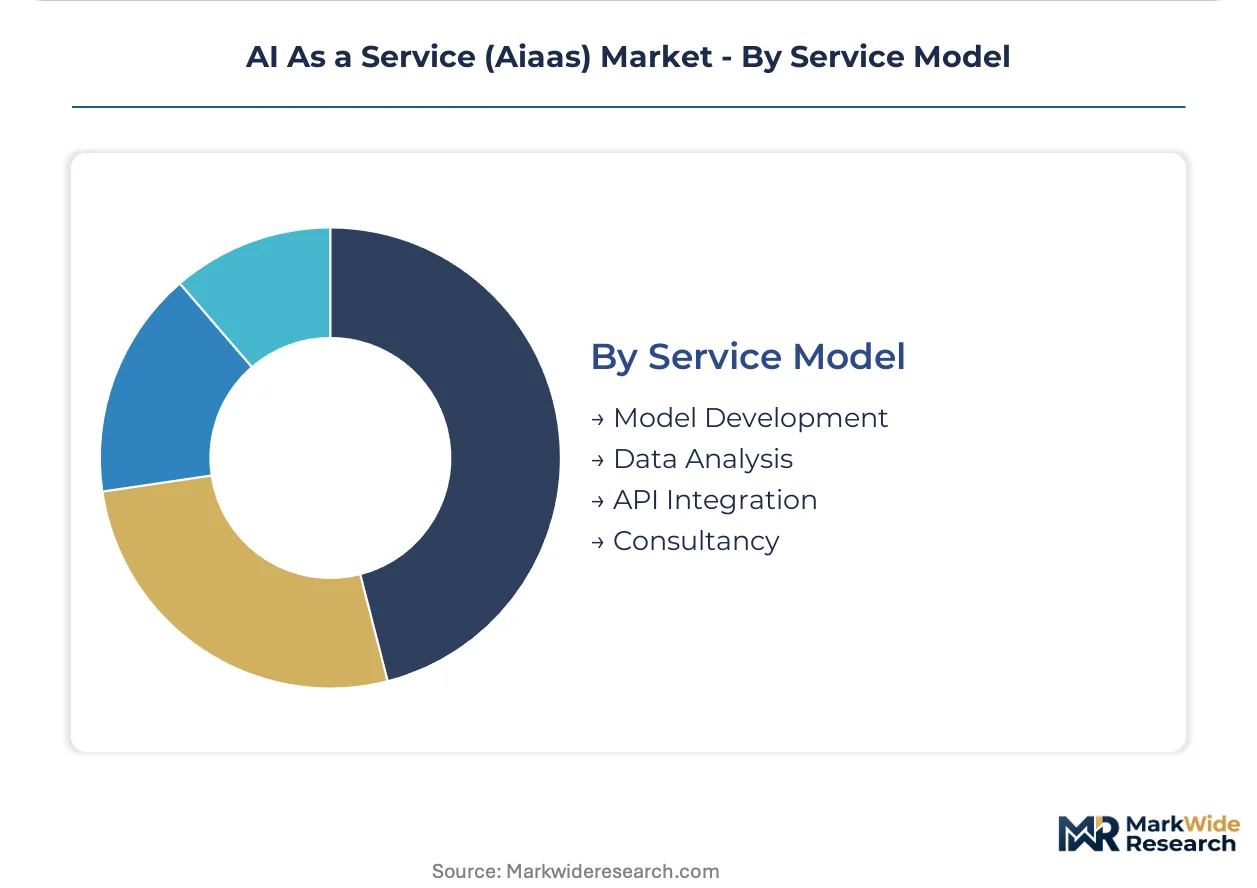
Deployment architecture determines compliance posture and cost structure for AI service procurement. Solution type differentiation reflects diverging technical requirements across enterprise verticals. Service model selection correlates directly with in-house data science maturity and regulatory exposure.
Deployment:
Technical architecture choices balance elasticity against data sovereignty mandates.
- Public Cloud:Multi-tenant infrastructure delivers pay-per-use GPU access without capital commitment. Healthcare systems in Texas and Florida route non-sensitive workloads through these environments to bypass on-premise hardware procurement cycles.
- Hybrid Cloud:Orchestrated architectures partition inference between edge nodes and central clusters. Manufacturing facilities in Japan deploy this configuration for quality-control pipelines that keep proprietary sensor data local while aggregating training workloads centrally.
- Private Cloud:Single-tenant deployments satisfy financial services data-residency requirements in Frankfurt and Paris.
- On-Premises:Air-gapped installations serve defense and classified government contracts with zero external connectivity.
Mature deployment sits with Public Cloud. Newer deployment is concentrated in Hybrid Cloud.
Solution Type:
Functional capability segments align with specific enterprise transformation priorities and technical readiness thresholds.
- Natural Language Processing:Generative text APIs power contract review and customer service automation. Legal departments in London and New York pilot these systems for clause extraction, compressing billable-hour structures while expanding matter volume.
- Computer Vision:Image classification and object detection models integrate directly into radiology PACS workflows. United States hospital networks deploy these APIs without on-premise GPU investment, accelerating diagnostic throughput.
- Machine Learning:General-purpose predictive modeling serves demand forecasting and fraud detection across BFSI verticals.
- Predictive Analytics:Time-series forecasting tools optimize inventory and maintenance scheduling for industrial operations.
Established commercial traction centers on Natural Language Processing. Steepest expansion trajectory belongs to Computer Vision.
End User:
Vertical-specific compliance requirements and workflow integration complexity shape adoption patterns.
- Healthcare:Diagnostic imaging and clinical decision support drive cloud API integration. Radiology departments across the United States embed computer vision directly into existing infrastructure, bypassing capital expenditure on specialized hardware.
- BFSI:Algorithmic trading, credit risk scoring, and anti-money laundering systems demand explainable model outputs. Frankfurt and Paris institutions restructure vendor qualification around EU AI Act conformity documentation.
- Retail:Recommendation engines and demand forecasting optimize inventory positioning and personalization.
- Manufacturing:Predictive maintenance and defect detection improve yield rates and reduce downtime.
Healthcare represents the most mature regulated deployment. BFSI is gaining share fastest as compliance tooling matures.
Service Model:
Engagement depth reflects client technical sophistication and risk tolerance for model governance.
- API Integration:Pre-trained model endpoints enable rapid deployment without internal ML expertise. Customer service platforms shift from per-call fees to resolution-rate guarantees, aligning vendor incentives with operational KPIs.
- Consultancy:Advisory services navigate EU AI Act risk classification and CE marking timelines. Most SaaS vendors have not operationalized required documentation workflows, creating demand for specialized compliance support.
- Model Development:Custom training pipelines serve enterprises with proprietary datasets and domain-specific requirements.
- Data Analysis:Managed analytics services extract insights without building internal data science teams.
API Integration commands the largest transaction volume. Consultancy is expanding most quickly as regulatory complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates enterprise AI consumption while manufacturing and compliance infrastructure clusters across Germany, Japan, and India. Cloud hyperscalers route inference workloads toward jurisdictions with favorable data-residency frameworks.
United States
Hospital networks in Texas and Florida embed computer vision APIs directly into radiology PACS workflows, bypassing capital expenditure on GPU hardware. The FTC enforces Section 5 authority against deceptive AI claims, tightening marketing compliance for service providers. Healthcare systems across the Southeast centralize model governance under single oversight offices before executing cloud contracts.
Germany
Frankfurt financial institutions restructure vendor qualification around EU AI Act conformity documentation and CE marking timelines. The country's national data protection authority enforces GDPR-aligned algorithmic accountability requirements for automated decision systems. Industrial manufacturers in Bavaria deploy hybrid cloud architectures to keep proprietary sensor data local while aggregating training workloads centrally.
Japan
Manufacturing facilities in the Chubu region around Nagoya deploy edge-to-cloud orchestration for quality-control pipelines that route sensitive data locally. METI promotes sovereign AI infrastructure development through public-private partnerships for domestic cloud capacity. Automotive suppliers in Kansai integrate predictive maintenance APIs without centralized data pooling.
India
Domestic cloud infrastructure incentives under the PLI scheme attract foreign providers to establish sovereign inference nodes for financial services compliance. The central bank imposes data localization requirements on algorithmic credit scoring systems deployed by non-bank financial companies. Technology clusters in Karnataka and Telangana host development centers for API-first AI service architectures.
United Kingdom
Enterprise legal departments in London pilot small language models for contract clause extraction, compressing billable-hour structures while expanding matter volume. The national data regulator issues guidance on automated decision-making transparency for financial services deployments. Fintech clusters in the Southeast integrate NLP APIs into customer service workflows under outcome-based pricing arrangements.
AI As a Service (Aiaas) Market Competitive Environment
The competitive structure tilts toward hyperscale cloud providers with integrated compliance tooling. Market concentration reflects capital intensity in GPU cluster deployment and the operational complexity of maintaining low-latency inference endpoints. Three archetypes dominate: full-stack cloud platforms, specialized hardware-accelerated inference providers, and vertical-specific API vendors. Competitive moves center on sovereign infrastructure partnerships and pre-certified compliance module development.
Within the full-stack tier, Amazon Web Services, Microsoft, and Google occupy positions defined by model lifecycle control and built-in regulatory tooling. These entities exemplify the hyperscale archetype through elastic provisioning economics and rapid API deployment capabilities. NVIDIA represents the hardware-specialist vector, anchoring inference performance benchmarks for regulated industries through GPU-accelerated cluster architectures.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM |
| Salesforce |
| Oracle |
| SAP |
| NVIDIA |
| Intel Corporation |
| Others |
Value Chain & Pricing Dynamics
MLOps engineering talent concentration in the San Francisco Bay Area and Bengaluru creates labor-cost differentials that widen pricing-tier spreads between premium managed services and standardized API offerings. Cloud hyperscalers leverage these geographic arbitrages to maintain margin structures while mid-market providers absorb compression through automation investments.
Pricing Analysis
Margin tightening in standard API tiers reflects NVIDIA GPU supply constraints and extended procurement timelines for H100 and Blackwell accelerators. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance certification depth and model customization scope. Pricing pressure stems from hyperscaler volume discounts that commoditize baseline inference workloads. Healthcare systems in Texas and Florida exhibit highest price sensitivity due to capital expenditure constraints, while Frankfurt financial institutions accept premium tiers for EU AI Act conformity documentation.
Supply Chain Analysis
Regional distribution centers in Taiwan, South Korea, and the United States anchor GPU accelerator fulfillment networks for inference cluster deployment. The hardware layer draws from TSMC foundry capacity, high-bandwidth memory from SK Hynix and Micron, and substrate packaging from Japanese specialists. Single-source vulnerability concentrates in NVIDIA's architectural dominance for training and inference silicon. Distribution runs through direct hyperscaler procurement channels and authorized reseller networks serving regulated verticals with sovereign deployment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary dataset curation and compliance tooling represents the decisive competitive race as foundation model capabilities commoditize. Players capturing upstream control over specialized training data and downstream control over audit-ready deployment environments will secure durable positioning.
For Market Incumbents: Deepen integration of EU AI Act conformity documentation into managed service offerings to preempt procurement disqualification. Establish captive GPU allocation agreements with NVIDIA to defend inference capacity commitments against supply bottlenecks. Acquire specialized MLOps talent pools in India and Eastern Europe to offset Bay Area compensation inflation.
For New Entrants and Emerging Players: Mid-market manufacturing enterprises in Japan's Chubu region present underserved demand for hybrid edge-to-cloud orchestration with local data residency. Federated learning implementations across hospital networks offer white-space entry with privacy-preserving architectures that hyperscalers have not productized. Lead with outcome-based API pricing tied to resolution-rate guarantees rather than per-call fees.
For Investors and Strategic Acquirers: The window for entry favors vertical-specific API vendors with proprietary dataset moats in regulated healthcare and financial services segments. Long-term viability hinges on compliance tooling integration that accelerates CE marking timelines for EU AI Act high-risk deployments. Monitor divergence between Brussels-style ex-ante risk frameworks and Washington's enforcement-driven posture as the inflection signal for cross-border service architecture portability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Vertex AI and Azure OpenAI Service consolidate model lifecycle control for enterprise procurement committees. |
| Strategic Partnership | Sovereign AI infrastructure alliances with India's PLI scheme attract foreign providers to domestic cloud nodes. |
| Acquisition of Specialist Firm | Vertical API vendors with proprietary radiology datasets in Texas hospital networks command defensive premiums. |
| Geographic Expansion | Frankfurt and Paris financial services deployments restructure around EU AI Act conformity documentation requirements. |
| Product Launch | Small language models optimized for legal clause extraction compress billable-hour structures in London and New York. |
Study Parameters
Document review covered hyperscaler capex disclosures, EU AI Act implementation guidance, and FDA algorithmic device submissions, complemented by interviews with CTOs at enterprise healthcare systems, platform engineers at cloud providers, procurement officers at Frankfurt financial institutions, and compliance leads at AI service vendors. Secondary validation drew from SEC filings, hospital procurement databases, and GPO contracts. Bottom-up deployment volume estimates triangulated against top-down market sizing from infrastructure spend analysis.
Cross-reference between historical GPU shipment patterns and panel input from datacenter operators informed the analytical framework across the modeling period. Segmentation dimensions included deployment architecture, solution type, end-user vertical, and service model engagement depth. CAGRs were derived from elasticity-adjusted adoption curves and regulatory timeline compression effects. Industry-specific forecast inputs incorporated EU AI Act high-risk system certification deadlines and India's PLI scheme infrastructure buildout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NVIDIA supply allocation decisions, cross-border data friction from China's SAMR provisions, and grid decarbonization mandates affecting datacenter electricity costs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global AI in Social Media Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Global Insight Engines Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Conversation Intelligence Software Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
Global AI Training Dataset Market
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
Intelligent Personal Assistant Market
Artificial Intelligence (AI)
Content Automation AI Tools Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Pharmaceutical Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Drug Discovery Market