
 Global Insight Engines Market | 2026-2036
Global Insight Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insight Engines Market Foresight
Healthcare and life sciences is realigning as a priority vertical for insight engine vendors as patient data interoperability rules tighten. Microsoft Corporation leverages its Azure cloud footprint to anchor enterprise search deployments across regulated industries. IBM Corporation competes through Watson Discovery's specialized NLP pipelines for legal and research workloads. Elasticsearch B.V. differentiates with open-source flexibility that appeals to DevOps-centric buyers.
Insight engines are software platforms that ingest structured and unstructured enterprise data, apply semantic analysis and machine learning models to extract meaning, and deliver contextual answers to natural language queries with sub-second response times. Cloud-based deployment is capturing the fastest expansion as organizations retire on-premise search appliances and adopt elastic consumption models. Enterprise search solutions sustain the largest revenue pool currently, though machine learning modules are where margin accretion concentrates as buyers pay premiums for automated relevance tuning.
The EU AI Act, GDPR, and SEC disclosure rules are collectively forcing vendors to embed explainability logs and data lineage tracking into platform architectures. FDA guidance on clinical decision support software is extending compliance burdens to healthcare deployments in the United States. Buyers must evaluate whether vendor roadmaps prioritize federated query capabilities that preserve data residency under divergent national AI regulations.
Market Dynamics
Semantic retrieval architectures are compressing query response latency below 500 milliseconds, forcing vendors to re-engineer indexing pipelines or lose procurement cycles to faster competitors. This performance threshold is reshaping R&D allocation across the competitive set.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic explainability requirements in Europe are accelerating replacement of black-box search systems with auditable insight engines in banking and insurance workflows.
- Healthcare interoperability rules:Patient data exchange standards in the United States are expanding addressable demand for engines that federate queries across EHR silos without centralizing sensitive records.
- Japan's METI digital transformation incentives:Enterprise modernization subsidies are concentrating procurement activity among Tokyo-based manufacturers modernizing knowledge management infrastructure.
Market Restraints
- GPU cluster cost volatility:Training and inference workloads for large language models depend on NVIDIA H100 supply concentrated in Taiwan and South Korea, creating input cost unpredictability.
- GDPR data residency friction:Cross-border query routing faces structural barriers as French CNIL and German KBA interpretations diverge on lawful transfer mechanisms.
- Keyword search substitution:Mature Boolean retrieval systems retain incumbency in cost-sensitive municipal and education sectors, delaying platform upgrades.
Strategic Opportunities
- India's PLI scheme for AI:Production-linked incentives for data center infrastructure are creating localized deployment demand among Mumbai and Bangalore headquartered conglomerates.
- Convergence of vector databases and knowledge graphs:Hybrid architectures that combine embedding-based retrieval with structured relationship mapping are opening new workload categories in pharmaceutical research.
- Swissmedic clinical trial data requirements:Switzerland's tightening documentation standards for investigational products are generating specialized demand for traceable insight engines in Basel's life sciences cluster.
Industry Challenges
- MLOps talent scarcity:Production deployment of relevance tuning pipelines requires scarce practitioners who bridge data engineering and linguistics, compressing implementation timelines.
- Legacy ECM integration complexity:Decades-old document management systems from OpenText and SharePoint variants resist API-based connectivity, extending professional services engagements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insight Engines Market |
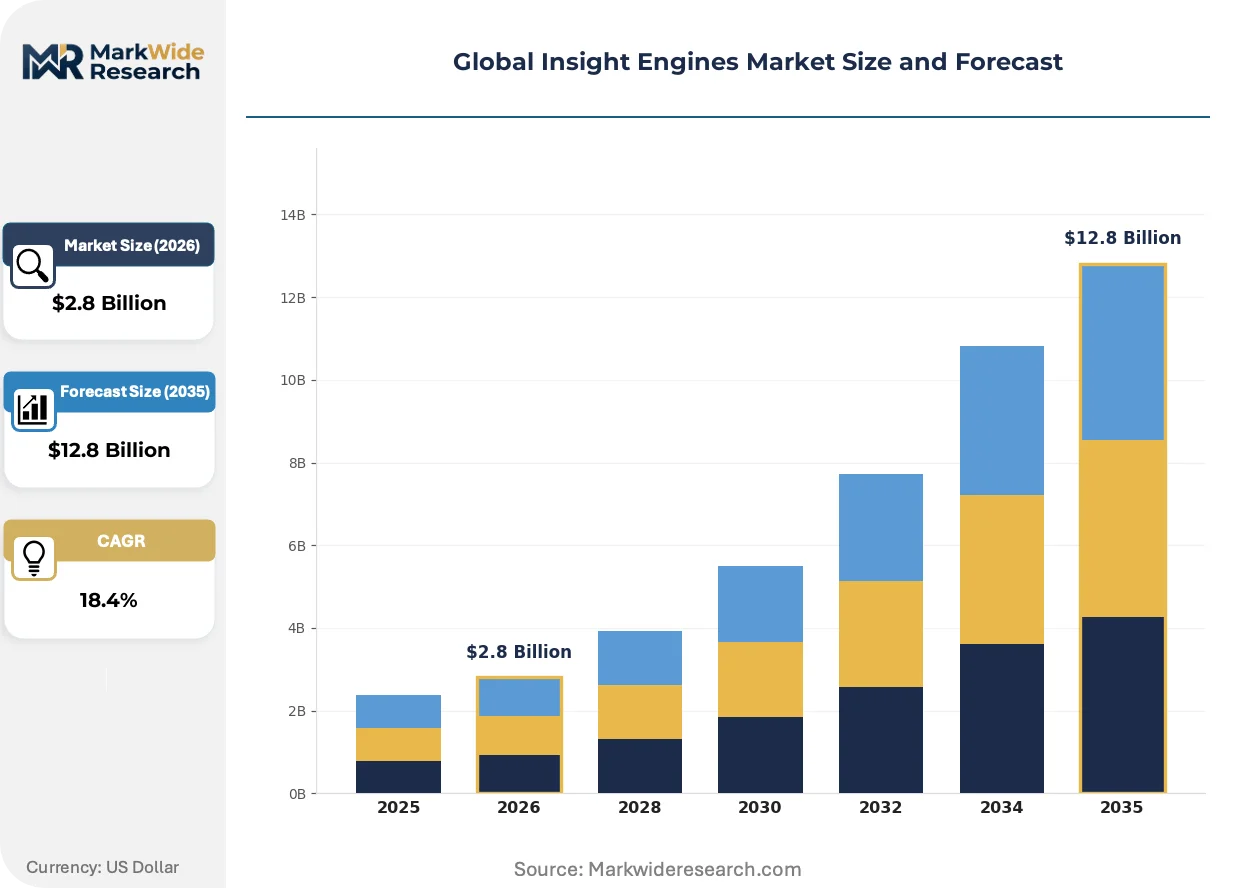
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Private Cloud, Public Cloud Solution Offering: Enterprise Search, Data Analytics, Semantic Search, Natural Language Processing, Machine Learning Use Case: Customer Experience Management, Risk Analysis, Sales Enablement, Competitive Intelligence, Compliance Monitoring End User Industry: Telecommunications, Manufacturing, Financial Services, Education, Government Organizations |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, Coveo Solutions Inc., Mindbreeze GmbH, Sinequa SAS, Elasticsearch B.V., OpenText Corporation, Expert.AI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insight Engines Market Shifts & Advancements
Neural ranking models are restructuring how relevance scores are computed, compressing the gap between experimental accuracy and production deployment. This shift is redrawing competitive boundaries between specialized NLP vendors and generalist cloud providers.
Vector-native indexing is overtaking inverted-index architectures as the default substrate for semantic search. Financial services compliance teams in Frankfurt and Singapore are adopting these engines to surface material disclosures across unstructured regulatory filings. The structural consequence is collapsing differentiation between enterprise search and question-answering product categories.
REACH chemical substance database integration requirements in Europe are mandating traceable provenance for AI-generated research summaries. Pharmaceutical safety teams must now reconstruct which source documents contributed to each synthesized output. Germany's KBA and France's ANSM are enforcing these standards most stringently, forcing vendors to embed audit trails by default.
Subscription-to-consumption model rotation is disrupting traditional enterprise software procurement. Buyers in Japan's manufacturing sector are unbundling annual licenses in favor of per-query metering that aligns costs with actual usage intensity. This behavioral shift is most visible among Osaka-based automotive suppliers modernizing technical documentation access patterns.
Global Insight Engines Market Segmentation
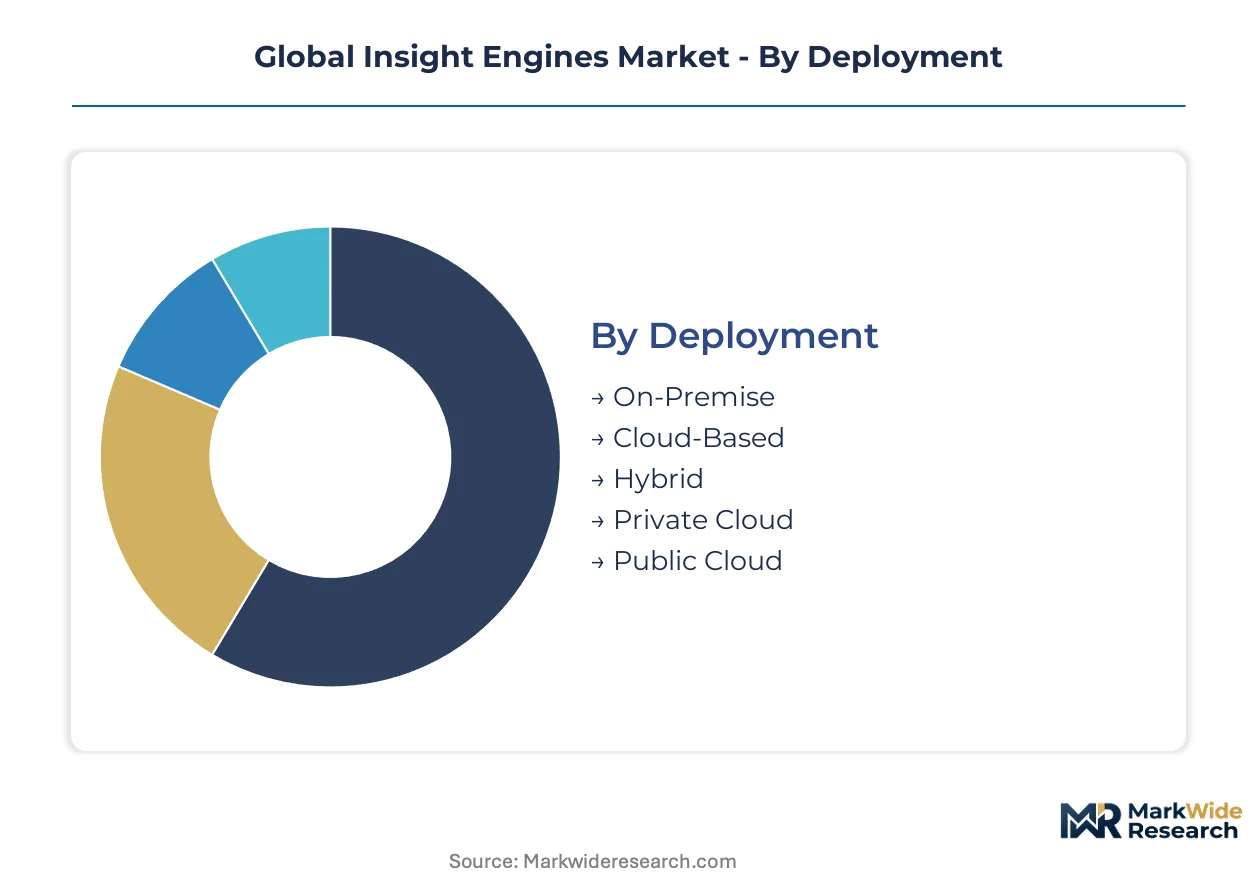
Deployment architecture determines compliance posture and total cost of ownership for insight engine procurement. Solution differentiation concentrates where semantic retrieval intersects with explainability mandates. Use case prioritization reflects sector-specific regulatory pressures rather than generic productivity gains.
Deployment:
Cloud-based configurations demand the heaviest upfront infrastructure investment in GPU clusters and distributed indexing nodes.
- On-Premise:Hardware appliances deployed within customer data centers retain favor among German automotive manufacturers subject to KBA data localization rulings. Frankfurt-based financial institutions maintain these installations to satisfy ECB audit requirements for algorithmic decision logs.
- Cloud-Based:Elastic consumption models eliminate capital expenditure for vector database infrastructure. Osaka manufacturing conglomerates under METI digital transformation subsidies are migrating technical documentation workloads to these environments fastest.
- Hybrid:Federated architectures partition sensitive indexing operations on-premise while routing anonymized queries to public cloud inference endpoints. Swiss pharmaceutical safety teams in Basel deploy this pattern to meet Swissmedic clinical trial data requirements.
- Private Cloud:Single-tenant deployments within managed data centers address French CNIL interpretations of GDPR lawful transfer mechanisms. Parisian insurance groups procure these configurations for cross-border policy documentation search.
- Public Cloud:Shared infrastructure delivers lowest per-query economics for non-regulated workloads. Bangalore-headquartered IT services firms leverage India's PLI scheme for AI data centers to localize these deployments.
Most installed capacity flows through Cloud-Based configurations. Expansion is steepest in Hybrid architectures as data residency rules proliferate.
Solution Offering:
Revenue concentration tracks where automated relevance tuning commands premium pricing over commodity search functionality.
- Enterprise Search:Unified indexing of document repositories, email systems, and collaboration platforms sustains the largest revenue pool. United States healthcare networks deploy these systems to federate queries across Epic and Cerner EHR silos under FDA clinical decision support guidance.
- Machine Learning:Automated ranking optimization and query intent classification capture the highest margins. Tokyo-based securities firms pay premiums for these modules to detect material disclosures in unstructured regulatory filings.
- Data Analytics:Structured query interfaces for business intelligence pipelines. Singaporean commodity trading houses integrate these capabilities for real-time supply chain risk monitoring.
- Semantic Search:Embedding-based retrieval replacing Boolean keyword matching. Research-intensive pharmaceutical clusters in Cambridge, Massachusetts and Basel adopt these engines for literature discovery workloads.
- Natural Language Processing:Named entity extraction and relationship parsing pipelines. Legal services firms in London deploy these for contract analysis under Solicitors Regulation Authority technology competence mandates.
Enterprise Search dominates current procurement volumes. Machine Learning modules are climbing the fastest as explainability requirements tighten.
Use Case:
Sector procurement patterns reveal which compliance verticals absorb platform investment most readily.
- Risk Analysis:Real-time correlation of internal data with external threat intelligence feeds. Frankfurt banking supervisors mandate these capabilities under EU AI Act algorithmic transparency requirements.
- Compliance Monitoring:Automated surveillance of communications and transactions against regulatory rule sets. United States broker-dealers deploy these engines to satisfy SEC disclosure and record-keeping obligations.
- Customer Experience Management:Unified interaction history across voice, chat, and email channels. Australian telecommunications providers under TGA consumer protection frameworks prioritize these deployments.
- Sales Enablement:Technical documentation retrieval for field engineering teams. Japanese automotive suppliers in Nagoya modernize these access patterns under METI productivity incentives.
- Competitive Intelligence:Aggregated monitoring of patent filings, earnings calls, and regulatory submissions. Basel life sciences clusters leverage these for pharmaceutical pipeline tracking.
Compliance Monitoring absorbs the most platform investment currently. Risk Analysis is gaining share fastest as EU AI Act enforcement accelerates.
End User Industry:
Regulatory intensity and data volume jointly determine sector-specific deployment velocity.
- Financial Services:Trading surveillance, credit risk modeling, and anti-money laundering query workloads. German insurers replace black-box systems with auditable engines to satisfy BaFin algorithmic governance circulars.
- Government Organizations:Freedom of information response automation and inter-agency knowledge sharing. United States federal agencies deploy these under NARA electronic records management mandates.
- Telecommunications:Network operations documentation and customer complaint resolution. South Korean carriers under MFDS data protection guidelines prioritize on-premise semantic retrieval.
- Manufacturing:Technical specification search and supplier quality documentation access. Osaka-based precision engineering groups modernize these systems under METI supply chain resilience programs.
- Education:Research repository discovery and administrative record retrieval. Cost-sensitive procurement in this sector delays upgrades from legacy Boolean systems.
Financial Services commands the deepest platform penetration. Government Organizations are expanding most quickly as public sector digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing insight engine procurement toward jurisdictions with clearer algorithmic governance frameworks. Enterprises in high-compliance-cost environments are selectively migrating workloads to regions offering operational certainty.
United States
Healthcare interoperability mandates and SEC disclosure rules are accelerating platform adoption. FDA clinical decision support guidance forces auditability into EHR-integrated deployments. Boston's life sciences cluster concentrates procurement for federated query systems that preserve data residency.
Germany
BaFin algorithmic governance circulars and KBA data localization rulings sustain on-premise infrastructure preference. Frankfurt banking supervisors mandate explainable retrieval for credit risk workflows. Munich automotive manufacturers deploy hybrid architectures to satisfy ECB audit requirements.
Japan
METI digital transformation subsidies concentrate procurement among Tokyo-headquartered manufacturers modernizing knowledge management. Osaka-based automotive suppliers unbundle annual licenses for per-query consumption models. Nagoya precision engineering groups prioritize technical documentation access modernization.
Switzerland
Swissmedic clinical trial data requirements generate specialized demand for traceable provenance in pharmaceutical research. Basel's life sciences cluster deploys hybrid architectures partitioning sensitive indexing on-premise while routing anonymized queries to cloud endpoints. Zurich insurance groups evaluate federated capabilities under divergent national AI regulations.
India
PLI scheme incentives for AI data center infrastructure create localized deployment demand. Mumbai and Bangalore-headquartered conglomerates leverage domestic cloud capacity for non-regulated workloads. Hyderabad IT services firms adopt public cloud configurations for cost-optimized semantic retrieval.
Global Insight Engines Market Competitive Landscape
Portfolio diversification dominates the current landscape as vendors unbundle monolithic search platforms into modular, consumption-metered components. The vendor base stratifies across three tiers: hyperscale cloud providers with integrated AI stacks, specialized NLP vendors with vertical-specific pipelines, and open-source-centric challengers with DevOps-aligned deployment models. Strategic archetypes include compliance-first specialists embedding audit trails by default, performance-optimized vendors compressing query latency below 500 milliseconds, and flexibility-focused players emphasizing API-native architectures. Technology licensing and geographic expansion represent the dominant competitive moves.
Within the hyperscale tier, Microsoft Corporation and IBM Corporation exemplify divergent positioning strategies. Microsoft leverages Azure cloud footprint to anchor enterprise search across regulated industries. IBM competes through Watson Discovery's specialized NLP pipelines for legal and research workloads. Elasticsearch B.V. occupies a distinct position among open-source-centric challengers, appealing to DevOps-centric buyers with deployment flexibility. These three anchors illustrate how competitive differentiation concentrates at the intersection of semantic retrieval and explainability mandates.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| Coveo Solutions Inc. |
| Mindbreeze GmbH |
| Sinequa SAS |
| Elasticsearch B.V. |
| OpenText Corporation |
| Expert.AI |
| Others |
Supply & Pricing Matrix
Cloud-hyperscaler-backed platform vendors anchor pricing discipline through consumption-metered SaaS tiers that compress distributor margins while capturing GPU infrastructure economics. Their balance-sheet capacity to absorb NVIDIA H100 cluster volatility insulates enterprise buyers from spot-price exposure in Taiwan and South Korea.
Pricing Analysis
Distributor margins in enterprise software channels compress as hyperscalers deploy direct-to-OEM licensing that bypasses traditional VAR markups. Three-tier pricing structure across premium explainability modules, standard semantic retrieval, and economy keyword search reflects certification grade differentiation under EU AI Act audit requirements. Pricing pressure stems from open-source Elasticsearch alternatives commoditizing core indexing functionality. Municipal education buyers exhibit highest price sensitivity, while Frankfurt banking supervisors under BaFin mandates absorb premiums for auditable decision logs.
Supply Chain Analysis
GPU cluster supply rests on NVIDIA H100 fabrication concentrated in Taiwan and South Korea, with assembly and testing distributed across Malaysia and Vietnam. Vector database infrastructure draws from specialized memory component producers in Japan and high-bandwidth interconnect suppliers in the United States. Single-source vulnerability in TSMC advanced-node allocation creates procurement queue risk for training workload capacity. Distribution runs through hyperscaler marketplaces and direct enterprise field sales, with systems integrators capturing implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Insight Engines Market compounds as a regulatory necessity, with EU AI Act enforcement deadlines forcing replacement cycles in European banking and insurance workflows.
For Market Incumbents: Hedge against open-source displacement by embedding audit-trail functionality as default architecture rather than premium add-on. Capture vertical integration into GPU cluster provisioning through cloud marketplace partnerships that lock in consumption commitments. Prioritize federated query R&D to defend against emerging specialists targeting Swissmedic and FDA compliance verticals. For New Entrants and Emerging Players: Begin with hybrid deployment architectures serving Basel pharmaceutical clusters and Munich automotive manufacturers where data residency rules create incumbent blind spots. Target India's PLI-subsidized data center infrastructure for localized cloud capacity that bypasses hyperscaler incumbency. Lead with per-query consumption models that align with Osaka manufacturing procurement patterns. For Investors and Strategic Acquirers: Valuations sit cheapest among DevOps-aligned open-source challengers with established Elasticsearch plugin ecosystems but undermonetized enterprise sales capacity. Long-term viability hinges on explainability feature depth as algorithmic transparency mandates proliferate across jurisdictions. Watch Swissmedic and FDA guidance evolution as inflection signals for healthcare-specific platform premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Query Architecture Development | Preserves data residency under divergent EU AI Act and GDPR interpretations across Frankfurt and Paris. |
| Explainability Module Launch | Captures BaFin-mandated audit requirements in German credit risk workflows. |
| GPU Cluster Partnership | Secures NVIDIA H100 allocation priority for training workload capacity in Taiwan supply queues. |
| Vertical Specialist Acquisition | Absorbs Swissmedic compliance expertise from Basel life sciences cluster incumbents. |
| Consumption Model Unbundling | Aligns with METI-subsidized Osaka manufacturing procurement modernization patterns. |
Research Methodology
Coverage spans the United States, Germany, Japan, Switzerland, and India, with primary inputs from each market's regulatory and procurement environment. Primary interviews incorporated CTOs at financial services institutions, IT procurement officers in pharmaceutical clusters, platform engineers at hyperscaler partners, and integration specialists serving government digitization mandates. Secondary validation drew from SEC filings, EU AI Act implementation guidance, METI subsidy program disclosures, and Swissmedic documentation standards. Bottom-up deployment volume estimates triangulated against top-down software spend allocations.
Granularity-level modeling captured deployment architecture, solution offering tier, use case intensity, and end-user industry regulatory exposure across the projection horizon. Segmentation dimensions included on-premise versus cloud-native configurations, explainability feature depth, and cross-border data routing complexity. CAGRs derived from trend extrapolation of procurement cycle timing and compliance-driven replacement waves. Industry-specific inputs encompassed FDA clinical decision support guidance evolution and BaFin algorithmic governance circular enforcement patterns.
Caveats apply where GPU supply chain disruptions or divergent national AI regulation interpretations could materially shift the outlook. Forecasts reflect assumptions regarding subsidy program continuity and enforcement timeline adherence. A small set of named triggers—TSMC allocation policy shifts, CNIL-KBA transfer mechanism rulings, and Swissmedic audit standard updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Europe Generative AI Market
Artificial Intelligence (AI)
Robotic Vision Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Supply Chain Market
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
Global Enterprise Artificial Intelligence Market
Artificial Intelligence (AI)
AI Platform Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market