
 Content Automation AI Tools Market | 2026-2036
Content Automation AI Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Content Automation AI Tools Market Analysis
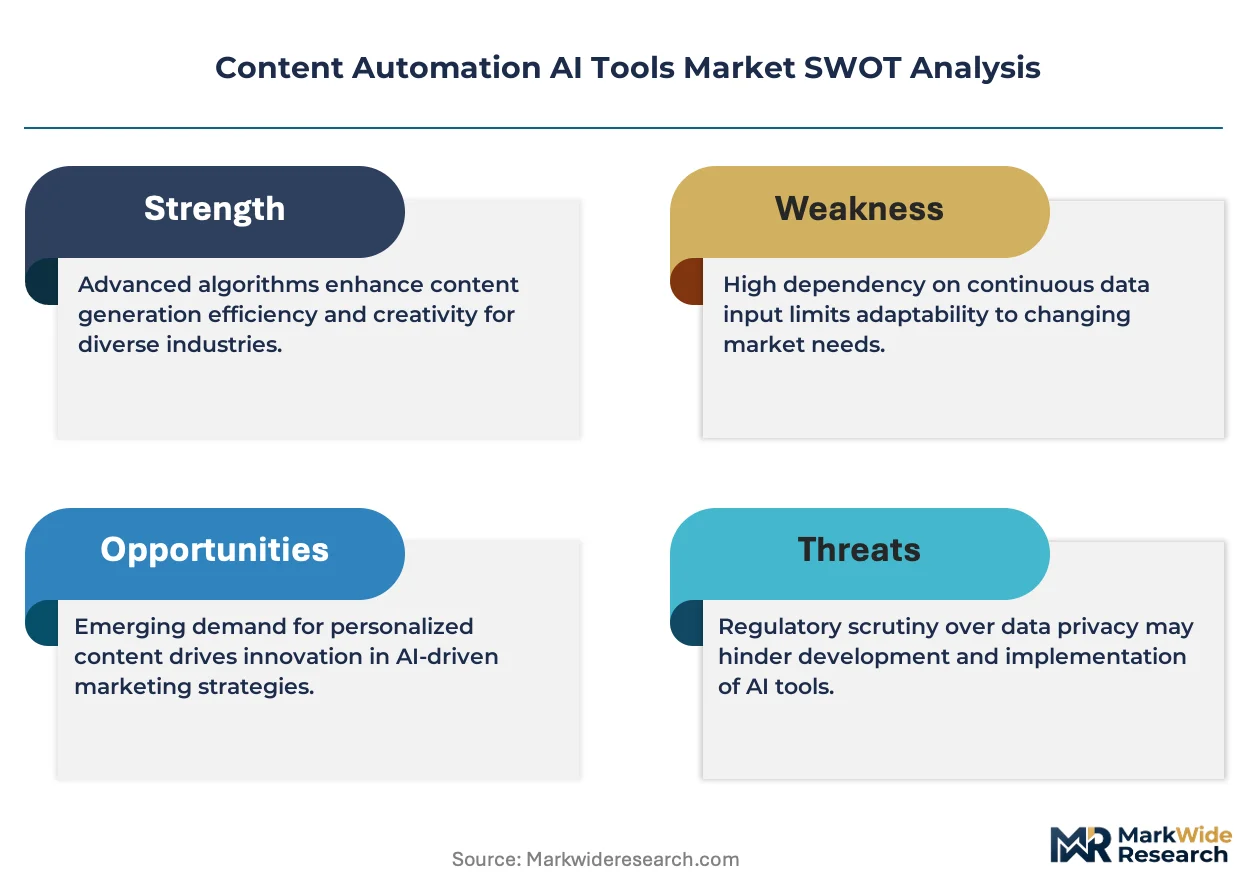
The enterprise software channel is fragmenting as AI-native vendors bypass traditional IT procurement gatekeepers and sell directly to functional buyers. Jasper AI leverages brand strength among creative teams to sustain premium positioning. Semrush anchors its competitive stance through SEO workflow integration that extends beyond standalone generation. ElevenLabs differentiates through voice synthesis specialization that controls a distinct modality layer.
Content automation AI tools comprise software systems that apply natural language processing, machine learning, and deep learning architectures to produce, refine, and distribute textual, audio, and visual content with minimal human intervention. These tools typically operate through cloud-based or SaaS deployment models that process prompts through transformer-based models to generate outputs aligned with brand voice parameters and channel specifications. Content Generation occupies the largest addressable revenue pool, while SEO Optimization commands disproportionate margin due to measurable ROI attribution. Social Media Management represents the fastest-expanding application segment as platform algorithms reward velocity and volume. Enterprises constitute the highest-spending end-user category, though Freelancers drive unit volume through low-friction subscription tiers.
The EU AI Act imposes transparency and risk-classification requirements on automated content systems deployed in European markets, compelling vendors to embed disclosure mechanisms and human oversight protocols. The US lacks unified federal AI legislation, yet the FTC applies Section 5 unfairness standards to deceptive automated content practices while state-level frameworks in California and New York introduce patchwork compliance burdens. Stakeholders must monitor whether emerging copyright rulings on training data reshape model licensing economics and vendor liability structures.
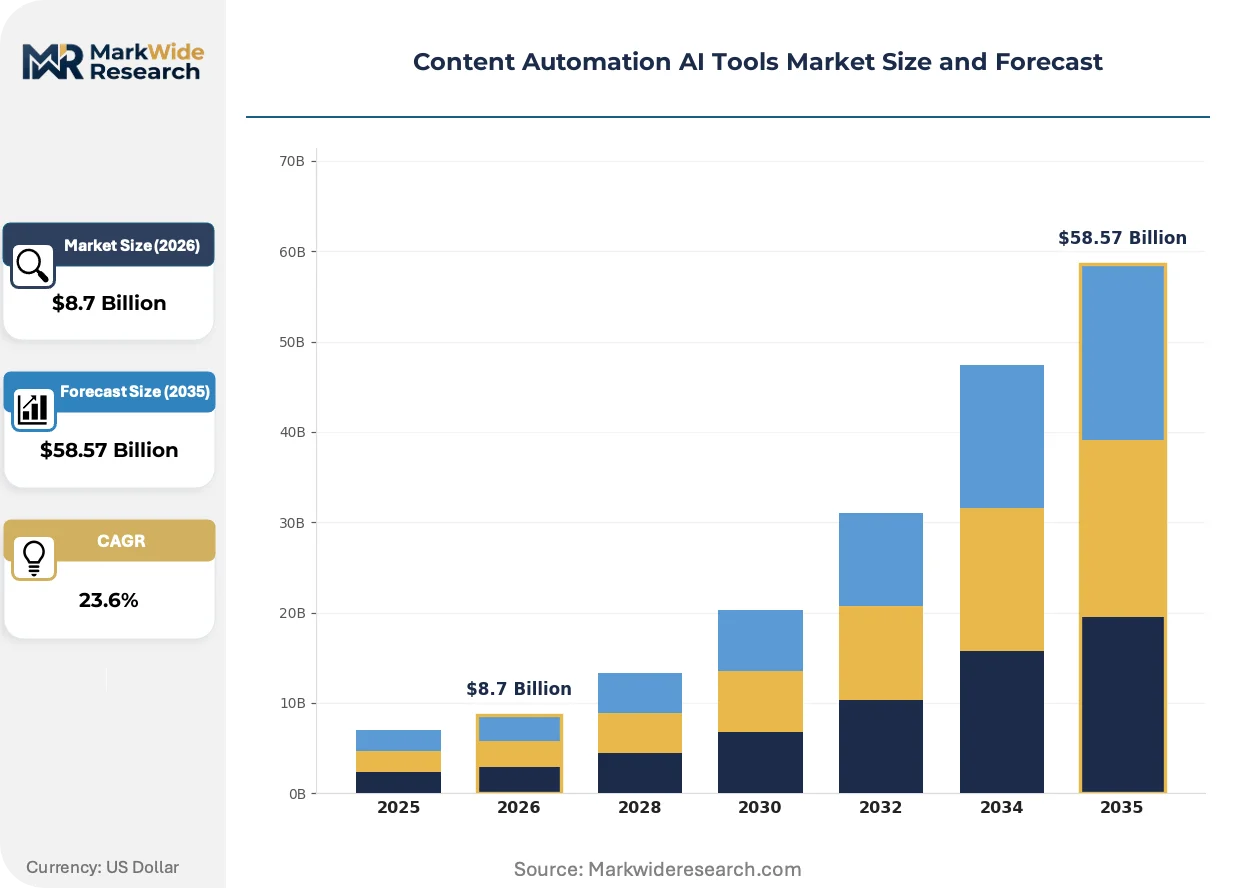
Market Dynamics
The Content Automation AI Tools Market is fracturing along functional buyer lines as marketing teams bypass traditional IT procurement channels and acquire SaaS tools directly through credit-card subscriptions and low-friction onboarding flows.
Growth Catalysts
- Transformer Architecture Maturation:Large language models trained on multimodal datasets now generate video scripts, audio narration, and visual assets from single text prompts, collapsing production timelines for retail marketing teams.
- EU AI Act Disclosure Mandates:Automated content systems deployed in European markets must embed transparency mechanisms and human oversight protocols, creating compliance-driven upgrade cycles among incumbent vendors.
- Social Platform Algorithm Velocity:TikTok, Instagram Reels, and YouTube Shorts reward posting frequency and engagement speed, forcing consumer brands to deploy AI tools that compress ideation-to-publication cycles from weeks to hours.
Market Restraints
- Training Data Licensing Uncertainty:Copyright litigation targeting model training datasets threatens vendor liability structures and may force costly re-licensing of foundational corpora.
- Inference Compute Cost Volatility:GPU cluster pricing swings and cloud provider concentration among three hyperscalers squeeze margins for AI-native vendors operating on thin SaaS economics.
- Transformer Model Homogenization:Commoditization of base architectures limits differentiation and pressures pricing power as technical moats erode across the vendor landscape.
Strategic Opportunities
- India Freelancer Tier Expansion:Low-friction subscription models targeting solo creators and boutique agencies in Mumbai, Bangalore, and Delhi represent underpenetrated unit volume pools.
- Voice-First Content Pipelines:Convergence of text-to-speech synthesis with automated video assembly enables podcast and short-form audio production at scale for media publishers.
- California Algorithmic Accountability Mandates:Emerging state-level transparency requirements create compliance productization opportunities for vendors embedding audit trails and bias detection modules.
Industry Challenges
- Prompt Engineering Talent Scarcity:Enterprises struggle to hire specialists capable of optimizing model outputs for brand voice consistency and factual accuracy at production scale.
- Legacy CMS Integration Friction:Connecting AI generation tools to entrenched content management systems at Fortune 500 companies requires expensive professional services and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Automation AI Tools Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $58.57 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Content Generation, Copy Editing, SEO Optimization, Social Media Management End User: Marketing Teams, Freelancers, Enterprises, Agencies Technology: Natural Language Processing, Machine Learning, Deep Learning, Automated Insights Deployment: Cloud-Based, On-Premise, Hybrid, SaaS |
| Companies Covered | ContentShake AI, Surfer SEO, Jasper AI, Copy.ai, Semrush, ElevenLabs, Frase, Notion AI, Brandwell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Automation AI Tools Market Emerging Trajectories
Multimodal generation capabilities are collapsing the boundaries between text, audio, and video production workflows, enabling single-platform orchestration that previously required fragmented toolchains.
Transformer-based generation is migrating from standalone text outputs to integrated asset pipelines where a single prompt spawns synchronized copy, voiceover, and visual elements. Mid-market marketing agencies in the United States are adopting these unified workflows fastest, replacing point solutions for each modality. This compression is eliminating handoff delays between copywriters, voice actors, and video editors, reducing campaign launch cycles from weeks to single-day sprints.
The EU AI Act risk-classification framework is forcing vendors to embed human-in-the-loop review gates and output labeling mechanisms for high-risk automated content applications. Systems generating product descriptions, financial promotions, and health-related material face elevated compliance burdens and documentation requirements. German and French enterprise buyers are now demanding audit-ready transparency reports as standard procurement criteria, filtering vendor shortlists before pilot phases begin.
Functional buyers in marketing departments are displacing centralized IT procurement as the primary decision-makers for AI tool acquisition, favoring self-service trials and month-to-month subscriptions over annual enterprise contracts. This shift fragments purchasing authority and accelerates vendor switching as individual teams test competing platforms simultaneously. The pattern is most pronounced among direct-to-consumer brands in California and New York, where marketing operations leaders hold independent budget authority and prioritize speed-to-deployment over security review depth.
Content Automation AI Tools Market Segmentation
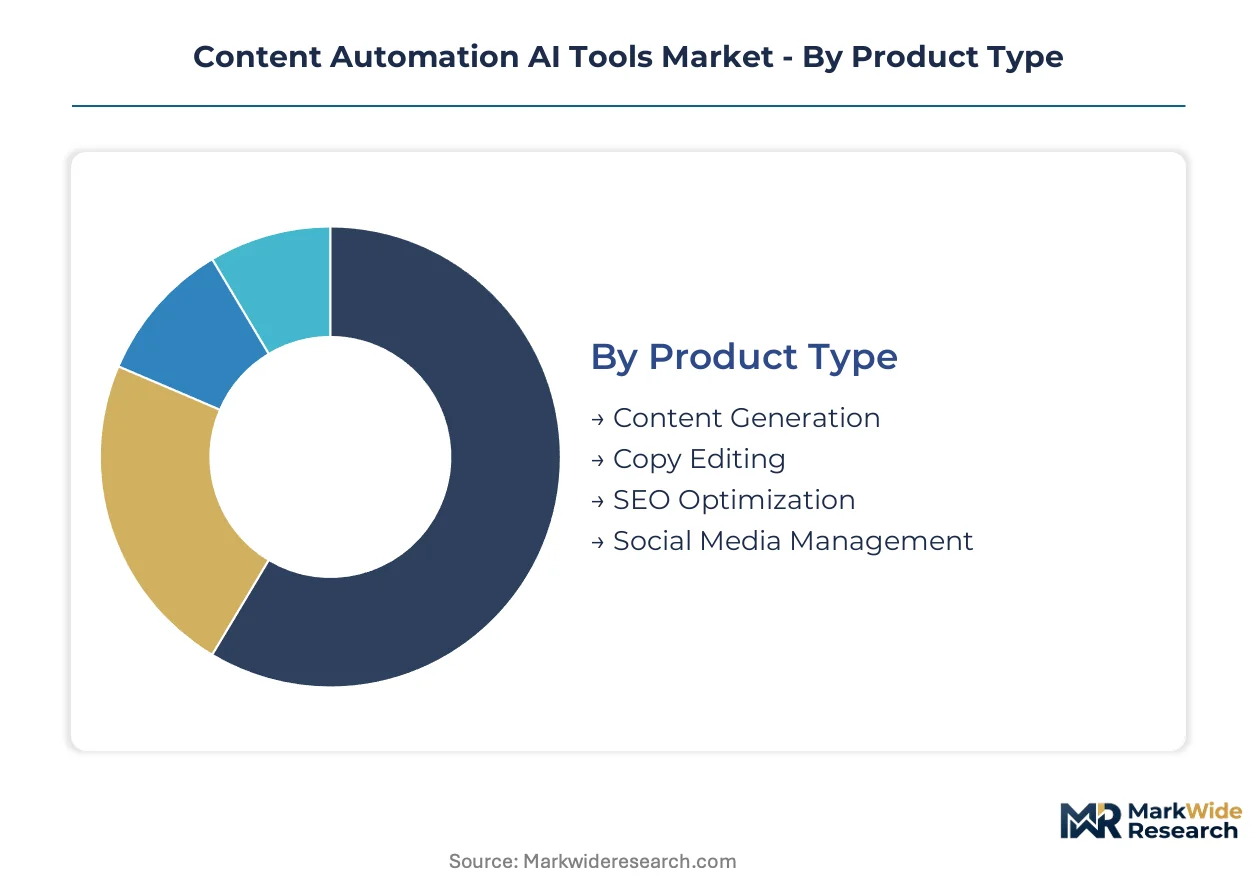
Content automation AI tools serve heterogeneous buyer workflows with divergent technical requirements and procurement rhythms. Segment boundaries reflect how transformer architectures compress production timelines differently across functional applications and deployment contexts.
Product Type:
Cycle times vary dramatically by output modality, with text-based tools iterating in hours while multimodal pipelines require days for quality assurance.
- Content Generation:Transformer models produce blog posts, product descriptions, and video scripts from single prompts. Marketing teams at direct-to-consumer brands in California deploy these tools to collapse ideation-to-publication cycles from weeks to single-day sprints.
- SEO Optimization:Systems analyze search intent signals and automate keyword clustering, meta description generation, and content gap identification. Semrush anchors competitive positioning through workflow integration that extends beyond standalone generation, capturing disproportionate margin through measurable ROI attribution.
- Copy Editing:Grammar correction and style alignment modules refine draft outputs for brand voice consistency.
- Social Media Management:Platform-native scheduling and algorithm-optimized caption generation reward velocity and volume.
Content Generation dominates installed base. Social Media Management is where expansion concentrates.
End User:
Procurement authority fragments as functional buyers displace centralized IT gatekeepers, creating divergent pricing tolerance and contract structures.
- Enterprises:Fortune 500 marketing operations demand audit trails, SSO integration, and human-in-the-loop review gates for compliance with EU AI Act transparency mandates. German and French buyers now require audit-ready transparency reports as standard procurement criteria.
- Marketing Teams:Direct functional acquisition through credit-card subscriptions accelerates deployment velocity.
- Agencies:Mid-market service providers in the United States adopt unified multimodal workflows fastest, replacing fragmented point solutions.
- Freelancers:Solo creators and boutique agencies in Mumbai, Bangalore, and Delhi drive unit volume through low-friction subscription tiers.
Enterprises command highest annual contract values. Freelancers represent the steepest expansion trajectory for vendor unit economics.
Technology:
Architecture maturity determines inference cost structures and output quality consistency at production scale.
- Natural Language Processing:Token prediction engines trained on multilingual corpora enable brand voice parameterization and channel-specific formatting.
- Machine Learning:Classification and recommendation layers optimize content distribution timing and audience targeting.
- Deep Learning:Multimodal architectures generate synchronized audio, visual, and textual assets from unified prompts.
- Automated Insights:Performance analytics modules feed engagement data back into generation parameters for iterative optimization.
Natural Language Processing anchors current vendor capabilities. Deep Learning is gaining share fastest as multimodal pipelines mature.
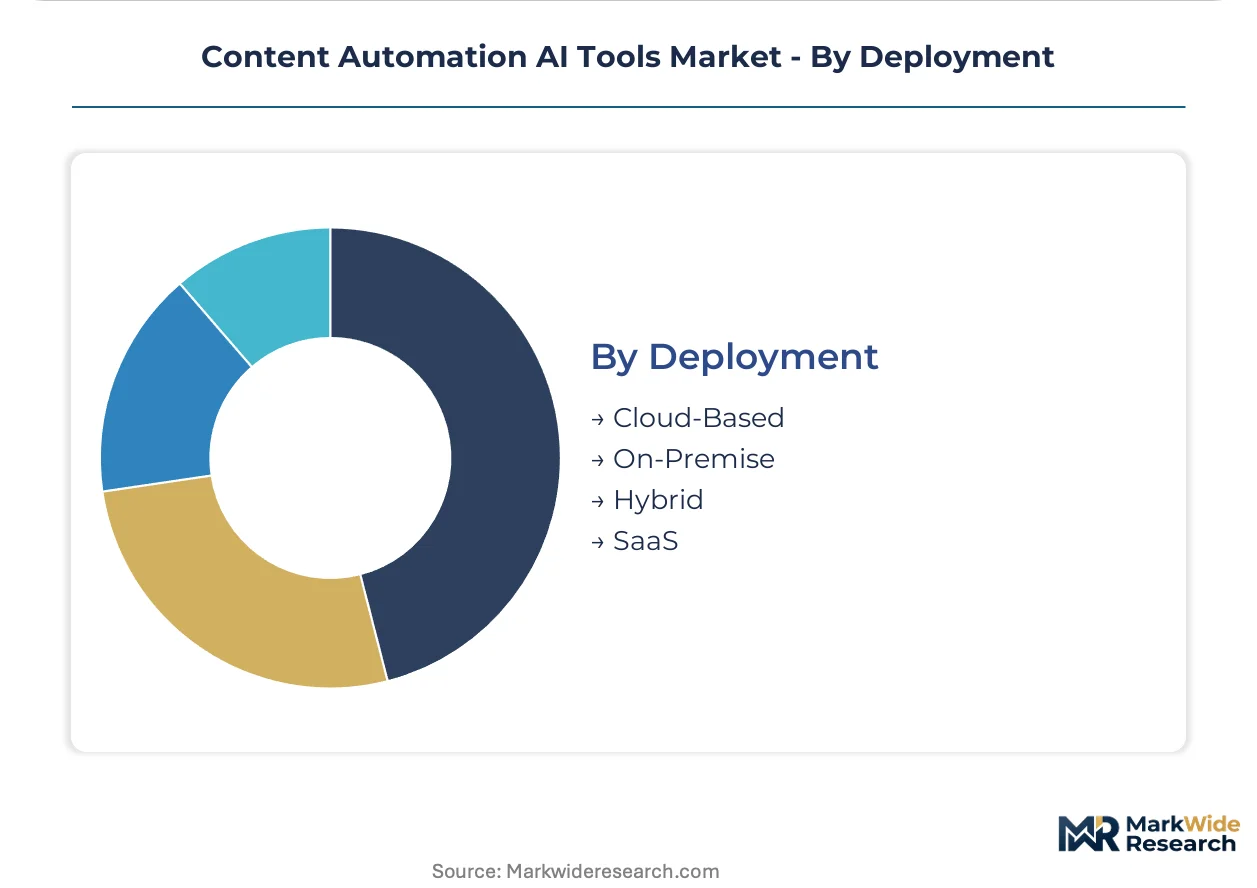
Deployment:
Data sovereignty requirements and latency sensitivity shape infrastructure choices across regulated and consumer-facing applications.
- Cloud-Based:Hyperscaler-hosted inference delivers elastic scaling for variable content production volumes.
- SaaS:Browser-native interfaces with pre-trained model access minimize onboarding friction for functional buyers.
- Hybrid:Sensitive draft generation on-premise with publication orchestration in cloud environments.
- On-Premise:Air-gapped deployments for financial services and healthcare sectors facing strict data residency mandates.
SaaS captures the majority of new subscriptions. Hybrid deployments are climbing fastest among regulated European enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable systems landing at Virginia Beach and Marseille underwrite the United States and France as twin hubs for content automation AI infrastructure, enabling sub-50ms latency for real-time inference serving across both continents.
United States
Venture-backed AI infrastructure spending concentrates in San Francisco and New York, where marketing operations leaders hold independent budget authority for direct SaaS procurement. The FTC applies Section 5 unfairness standards to deceptive automated content practices, creating compliance benchmarks that vendors must meet. California's emerging algorithmic accountability mandates are driving demand for audit trail modules among Los Angeles-based direct-to-consumer brands.
Germany
Industrial marketing departments at Stuttgart and Munich automotive suppliers deploy AI content tools for technical documentation localization at scale. The EU AI Act risk-classification framework imposes human-in-the-loop review gates for high-risk automated content applications. Frankfurt enterprise buyers now require audit-ready transparency reports as standard procurement criteria, filtering vendor shortlists before pilot phases begin.
United Kingdom
London's creative agency cluster adopts unified multimodal workflows fastest, replacing fragmented point solutions for synchronized copy, voiceover, and visual asset generation. The UK Information Commissioner's Office enforces GDPR-aligned transparency requirements for automated decision-making systems. Manchester and Birmingham mid-market service providers drive subscription volume through low-friction onboarding flows.
India
Solo creators and boutique agencies in Mumbai, Bangalore, and Delhi represent underpenetrated unit volume pools for low-friction subscription tiers. The country's central bank monitors cross-border data flows for SaaS platforms serving financial content automation use cases. Hyderabad's emerging tech corridor hosts localization specialists refining Indic-language model outputs for regional brand voice consistency.
Japan
Tokyo enterprise marketing teams prioritize brand voice parameterization tools that preserve keigo and hierarchical linguistic conventions in automated outputs. METI guidelines on AI utilization encourage human oversight protocols for customer-facing content generation. Osaka-based media publishers invest in voice-first content pipelines for podcast and short-form audio production at scale.
Content Automation AI Tools Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability layers as technical moats erode and differentiation shifts toward workflow integration depth. Transformer model commoditization pressures pricing power across base generation functions. Strategic archetypes include SEO-anchored platform vendors, voice synthesis specialists, and creative-team-focused brand builders. Dominant competitive moves center on strategic partnerships with hyperscaler cloud providers and portfolio diversification into multimodal output pipelines.
Within the creative-team-focused tier, Jasper AI exemplifies brand-driven positioning that sustains premium pricing among design-centric buyers. SEO-anchored platform representation includes Semrush, whose workflow integration extends beyond standalone generation into measurable attribution layers. ElevenLabs occupies the voice synthesis specialization vector, controlling a distinct modality layer that converges with automated video assembly for media publishers. These three anchors illustrate how vendor concentration follows functional buyer fragmentation rather than consolidated IT procurement channels.
| Leading Market Players |
|---|
| ContentShake AI |
| Surfer SEO |
| Jasper AI |
| Copy.ai |
| Semrush |
| ElevenLabs |
| Frase |
| Notion AI |
| Brandwell |
| Others |
Supply Flow & Price Mechanics
GPU cluster overcapacity in United States hyperscaler regions is compressing inference-as-a-service rates and forcing AI-native vendors to restructure SaaS subscription tiers while maintaining margin buffers against cloud provider pricing volatility.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise, mid-market, and freelancer segments with seat-count thresholds triggering 40-60% per-unit reductions. Pricing separates premium SSO-integrated deployments with EU AI Act compliance modules from standard browser-native tiers and economy single-user subscriptions. Cost compression in the freelancer tier is intensifying because ElevenLabs and Jasper AI are racing to capture Mumbai and Delhi unit volume through aggressive annual billing discounts. Enterprise buyers in Germany and France show lowest price sensitivity due to mandated audit trail requirements that bundle compliance consulting into contract values.
Supply Chain Analysis
Upstream feedstock dependencies in training data licensing and GPU compute provisioning concentrate vendor exposure across the United States, Taiwan, and South Korea. NVIDIA H100 clusters and annotated multilingual corpora draw from hyperscaler infrastructure concentrated in Virginia and California, with Taiwan Semiconductor Manufacturing anchoring chip fabrication. Single-source vulnerability in NVIDIA's datacenter GPU allocation creates supply chain risk for AI-native vendors scaling inference capacity. Distribution runs through direct self-service onboarding for functional buyers, bypassing traditional IT procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Content Automation AI Tools Market represents high-growth disruption as transformer architecture maturation collapses multimodal production timelines from weeks to hours, while the EU AI Act imposes compliance-driven upgrade cycles that filter vendor shortlists before pilot phases.
For Market Incumbents: Build workflow integration moats that embed generation tools into entrenched SEO and social media management platforms. Semrush anchors competitive positioning through measurable ROI attribution layers that resist point-solution displacement. Jasper AI must defend against voice-first pipeline convergence by deepening ElevenLabs API partnerships that control distinct modality layers. Certification investment in EU AI Act transparency modules filters German and French procurement shortlists.
For New Entrants and Emerging Players: Mid-market agencies in Manchester and Birmingham represent the most penetrable entry point for unified multimodal workflows replacing fragmented point solutions. Solo creators and boutique agencies in Hyderabad's emerging tech corridor offer underpenetrated unit volume pools for Indic-language model specialization. Go-to-market execution should leverage low-friction browser-native trials with credit-card subscriptions that bypass IT procurement gatekeepers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across deep learning multimodal pipelines as GPU cluster provisioning costs outpace SaaS pricing power. Long-term viability favors vendors with backward integration into proprietary training data corpora or captive cloud infrastructure partnerships. Acquisition targets should display workflow integration depth rather than standalone generation capabilities. The signal to watch is hyperscaler capex allocation shifts toward inference-optimized silicon that reshapes vendor cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding generation tools into Semrush SEO workflows captures measurable attribution layers. |
| Strategic Partnership | ElevenLabs voice synthesis APIs converge with automated video assembly for media publishers. |
| Geographic Expansion | Mumbai and Delhi freelancer tiers drive unit volume through low-friction subscription models. |
| Acquisition of Specialist Firm | Indic-language localization capabilities in Hyderabad refine regional brand voice consistency. |
| Product Launch | EU AI Act compliance modules with audit-ready transparency reports filter German procurement. |
Methodological Framework
Cross-validation between primary interviews with marketing operations leaders and secondary validation through hyperscaler capex disclosures anchors the qualitative findings. Conversations captured perspectives from CTOs at direct-to-consumer brands, IT procurement officers at Fortune 500 enterprises, platform engineers at AI-native vendors, and integration specialists at mid-market agencies. Secondary sources include SEC filings from public SaaS providers, App Annie mobile subscription data, NVIDIA datacenter revenue segment disclosures, and EU AI Act implementation guidance documents. Bottom-up segment sizing triangulates against top-down addressable market estimates.
Calibration against historical adoption curves in adjacent marketing technology categories informs the projection framework across the analysis window. Segmentation dimensions modeled include deployment model, organization size, output modality, integration complexity, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to disclosed vendor revenue ranges and subscription pricing tiers. Industry-specific inputs encompass transformer model inference cost trajectories and EU AI Act compliance module attach rates.
Macroeconomic conditions sit as an overlay; deviation in venture capital deployment rates and cloud provider pricing volatility would shift the trajectory. Forecasts reflect assumptions about GPU cluster supply expansion and training data licensing resolution that remain subject to revision. Cross-checking against hyperscaler infrastructure spending disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Conversational AI Platform Software Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Global Artificial Intelligence in E-Commerce Market
Artificial Intelligence (AI)
Smart Home Digital Assistant [Voice] Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
Cognitive Computing Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Pharmaceutical Market
Artificial Intelligence (AI)
Synthetic Data Generation Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
United States Artificial Intelligence Market
Artificial Intelligence (AI)
AI Demand Forecasting Software Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market