
 Wafer Inspection Market | 2026-2036
Wafer Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Wafer Inspection Market Outlook
Capital-intensity divergence between lithography-integrated inspection platforms and standalone optical tools is collapsing as EUV node transitions demand unified process control. KLA Corporation dominates reticle and wafer defect detection through captive supply of broadband plasma optical systems. Applied Materials, Inc. leverages its materials engineering heritage to anchor integrated metrology-inspection modules within deposition and etch clusters. Lasertec Corporation differentiates through specialized EUV mask blank inspection, a niche where Japanese precision optics sustain technical leadership against broader-platform competitors.
Wafer inspection encompasses non-destructive metrology techniques that detect particulate contamination, pattern defects, and film thickness variations on semiconductor substrates, typically resolving critical dimensions below 10nm using deep-ultraviolet or electron-beam probe technologies. Its primary purpose is to intercept yield-limiting defects before downstream processing commits additional capital to compromised wafers. Optical inspection retains the largest installed base among technology segments, yet e-beam inspection captures expanding share at sub-7nm nodes where optical resolution hits physical limits. Foundries represent the fastest-growing end-user category, as Samsung and Intel internalize advanced packaging inspection previously outsourced to OSATs.
ISO 14644 cleanroom standards, SEMI S2/S8 equipment safety guidelines, and FDA quality system regulations for medical-grade chip applications collectively tighten certification requirements for inspection tool vendors seeking multi-industry placement. EPA emissions rules on fluorinated greenhouse gases from etch and deposition processes indirectly pressure fabs to maximize yield-per-wafer, elevating inspection from cost center to strategic lever. Stakeholders must monitor whether China's GB standards on semiconductor self-sufficiency redirect procurement toward domestic inspection equipment, fragmenting what has been a US-Japan-Dutch supplier triad.
Market Dynamics
EUV lithography scaling at sub-3nm nodes is collapsing the historical separation between lithography and inspection equipment, forcing unified process control architectures that merge metrology with patterning systems.
Growth Catalysts
- ISO 14644-1 cleanroom standards:Tightened particulate limits for EUV resist processing are mandating inline defect detection at every lithography step, expanding inspection tool deployment density in advanced fabs.
- 3nm logic node ramp:Foundries in Taiwan and South Korea are commissioning multi-beam e-beam inspection platforms to resolve stochastic defects invisible to optical systems.
- EPA fluorinated gas regulations:Emissions controls on etch process gases are elevating yield-per-wafer economics, repositioning inspection from overhead to strategic yield protection.
Market Restraints
- EUV mask blank supply concentration:Japanese precision optics suppliers control mask substrate polishing and coating, creating single-source vulnerability for inspection tool calibration standards.
- Electron source lifetime limitations:Thermal field emission cathodes in multi-beam systems require replacement every 12-18 months, inflating total cost of ownership versus optical alternatives.
- China GB standards on equipment procurement:Domestic semiconductor self-sufficiency mandates are redirecting foundry capex toward local inspection vendors, fragmenting equipment interoperability.
Strategic Opportunities
- India PLI scheme for semiconductor manufacturing:Subsidies for domestic fab construction are creating greenfield demand for inspection infrastructure without legacy tool replacement constraints.
- Advanced packaging inspection:Hybrid bonding and chiplet integration are extending inspection requirements from front-end wafers to interposer and substrate metrology.
- AI-driven defect classification:Machine vision algorithms trained on fab-specific defect libraries are compressing classification latency from hours to minutes, enabling real-time process adjustment.
Industry Challenges
- EUV resist outgassing expertise:The intersection of photochemistry and vacuum physics required for contamination control exceeds the training depth of most field service engineers.
- SEMI S2/S8 safety certification timelines:Equipment safety validation for multi-beam systems with high-voltage electron optics extends qualification cycles by 6-9 months versus optical platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wafer Inspection Market |
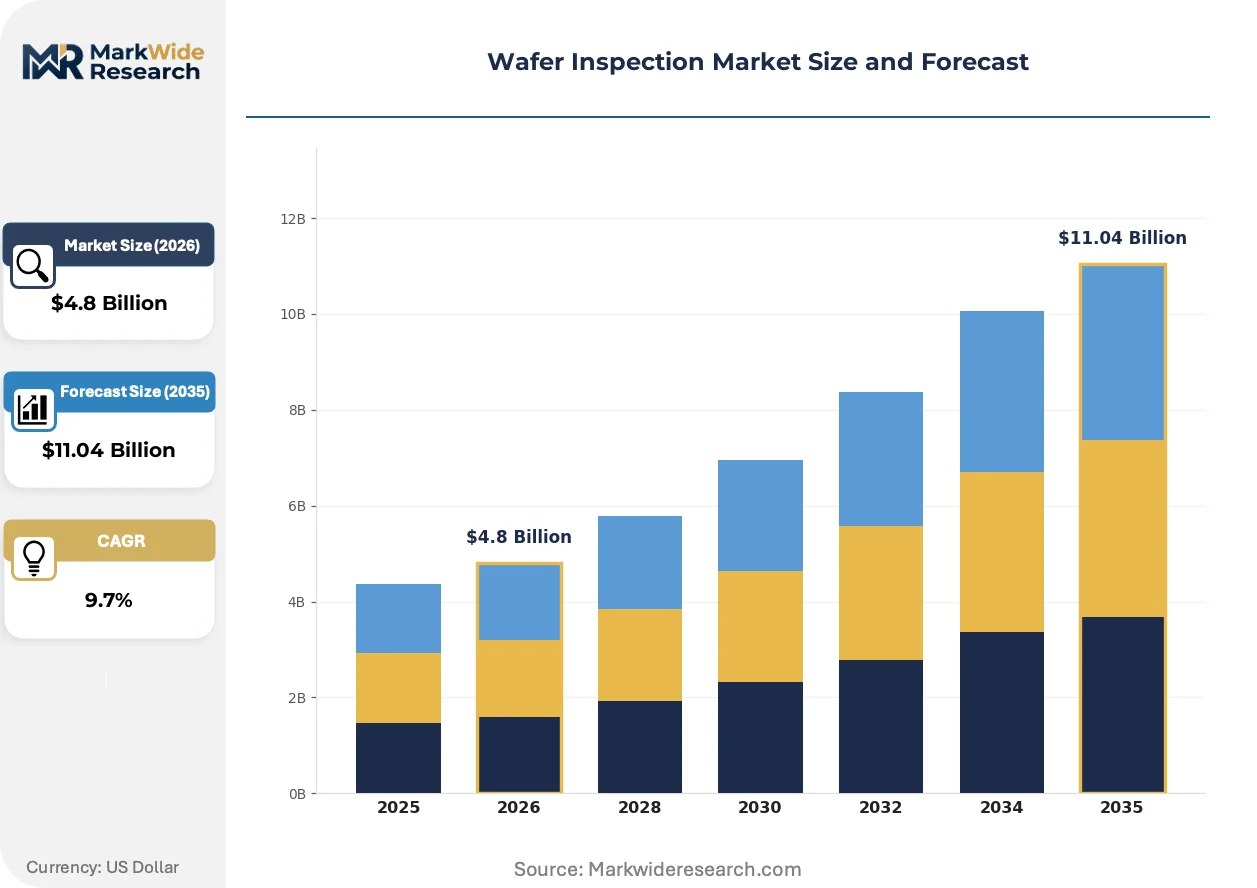
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical Inspection, X-ray Inspection, E-beam Inspection, Scanning Electron Microscopy Equipment Type: Automated Inspection Systems, Manual Inspection Tools, Integrated Test Systems, Metrology Equipment End User: Semiconductor Manufacturers, Research Institutions, Foundries, Microelectronics Companies Application: Quality Control, Process Development, Defect Analysis, Yield Improvement |
| Companies Covered | Hitachi High-Tech Corporation, Onto Innovation Inc., KLA Corporation, Camtek Ltd., Teradyne Inc., Applied Materials, Inc., Lam Research Corporation, Lasertec Corporation, ASML Holding N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wafer Inspection Market Strategic Shifts
Computational inspection architectures are displacing hardware-centric resolution improvements, enabling defect detection through algorithmic reconstruction rather than purely physical probe scaling.
Multi-beam electron microscopy is decomposing the throughput-resolution tradeoff that constrained single-beam e-beam inspection to sampling applications. Memory manufacturers at South Korea's Pyeongtaek complex are deploying these systems for 100% wafer coverage at 5nm equivalent resolution. The technology is decomposing the historical boundary between optical screening and e-beam verification, collapsing two process steps into unified inline monitoring.
EU F-Gas Regulation phase-down schedules are pressuring fabs to minimize process gas consumption per wafer pass. This regulatory pressure is accelerating adoption of closed-loop etch chambers with integrated film thickness monitoring, embedding inspection functions directly within process equipment. Memory fabs in Dresden and Leuven are retrofitting deposition clusters with spectroscopic ellipsometry modules to eliminate separate metrology queue time.
Consolidated procurement by foundry alliances is compressing vendor qualification cycles and unbundling service contracts from hardware sales. TSMC's supplier consolidation program now mandates API-accessible inspection data streams, displacing proprietary software lock-in. This pattern is most pronounced in Taiwan's Hsinchu corridor, where equipment purchasing has shifted from individual fab autonomy to central technology group negotiation.
Wafer Inspection Market Segmentation
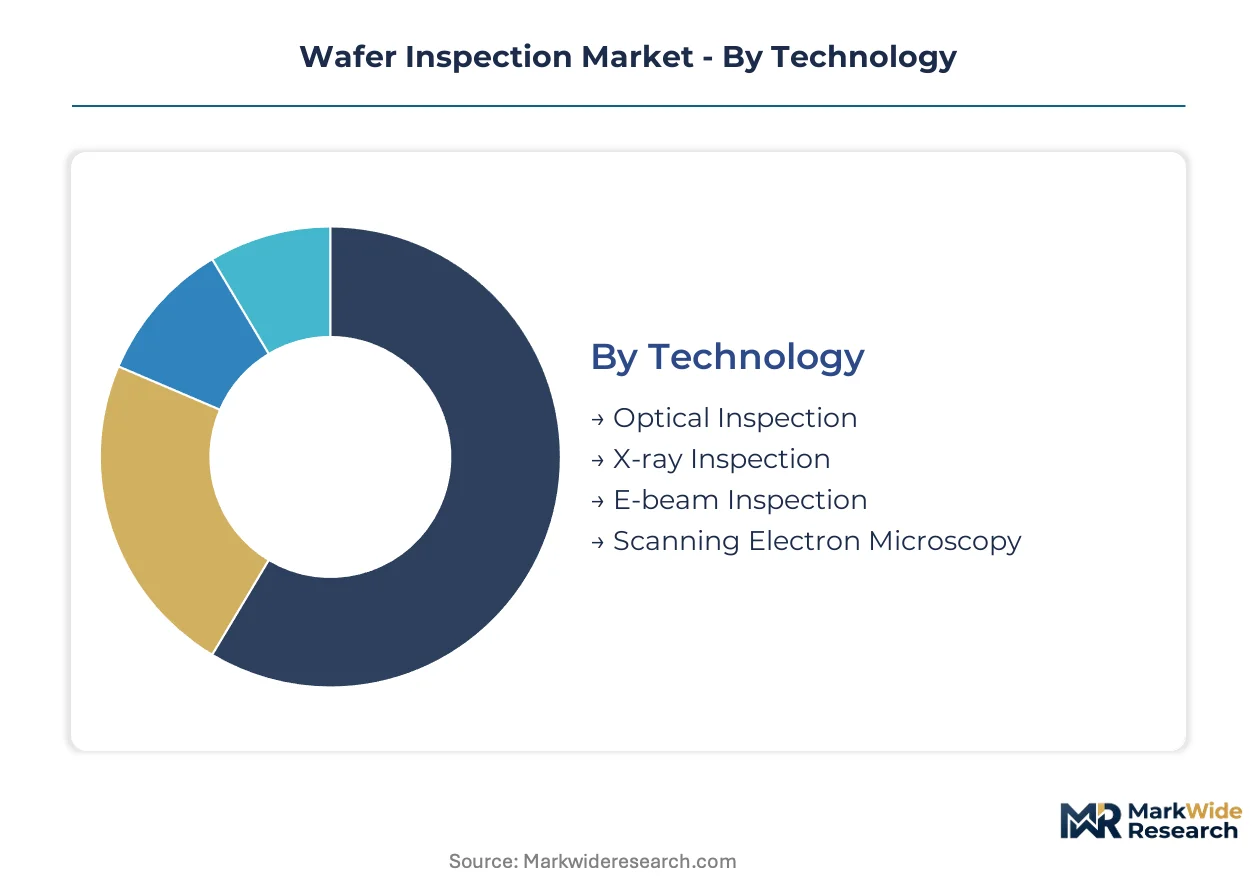
Wafer inspection segmentation reveals how technology specialization fragments procurement budgets across tool categories. Equipment buyers prioritize resolution capabilities and throughput economics differently depending on node requirements and fab maturity.
Technology:
Margin pools concentrate in platforms bridging the resolution-throughput tradeoff at sub-7nm nodes.
- Optical Inspection:Broadband plasma and deep-ultraviolet systems resolve defects above 10nm using scattered light detection. TSMC's Hsinchu fabs deploy these for high-throughput screening across 90% of wafer surface area. The installed base remains largest, though EUV node transitions are compressing its addressable market at leading-edge logic.
- E-beam Inspection:Multi-beam architectures overcome optical diffraction limits for stochastic defect detection at 3nm and below. Samsung's Pyeongtaek complex commissions these for 100% die coverage where pattern fidelity failures escape optical detection. Thermal cathode replacement cycles inflate operating costs versus optical alternatives.
- X-ray Inspection:Penetrating probe technology identifies buried voids and copper interconnect integrity in 3D NAND stacks.
- Scanning Electron Microscopy:Laboratory-grade imaging supports offline defect characterization and root-cause analysis for yield engineering teams.
The dominant share belongs to Optical Inspection, while E-beam Inspection is closing the gap fastest.
Equipment Type:
Cost tier stratification separates capital-intensive automated platforms from lower-unit-value manual tools.
- Automated Inspection Systems:Inline robotic handling enables 24/7 operation with sub-10nm positioning repeatability. Foundries in Taiwan and South Korea standardize on these for production-volume fabs where labor costs exceed depreciation schedules. Multi-beam e-beam variants command premium pricing against optical-only configurations.
- Integrated Test Systems:Modules embedding spectroscopic ellipsometry or scatterometry within deposition and etch clusters eliminate queue time. Applied Materials anchors these within Endura and Producer platforms. EU F-Gas Regulation compliance is accelerating retrofit demand at Dresden and Leuven memory fabs.
- Manual Inspection Tools:Operator-dependent microscopes serve R&D prototyping and failure analysis laboratories.
- Metrology Equipment:Film thickness and critical dimension measurement tools support process control without full defect mapping capability.
Automated Inspection Systems command the largest revenue pool, with Integrated Test Systems expanding most quickly.
End User:
Customer type determines volume scale and specification stringency across procurement decisions.
- Foundries:Pure-play and IDM foundries internalize advanced packaging inspection previously outsourced to OSATs. TSMC, Samsung, and Intel drive specifications for multi-beam throughput and API-accessible data streams. Centralized technology group procurement is compressing vendor qualification cycles.
- Semiconductor Manufacturers:Integrated device makers with captive fabs balance leading-edge and mature node requirements. Memory producers at Micron and SK Hynix prioritize 3D NAND stack inspection for vertical channel hole integrity.
- Microelectronics Companies:Specialty analog and power semiconductor producers emphasize reliability-grade inspection for automotive qualification.
- Research Institutions:Universities and national laboratories acquire refurbished or entry-level tools for materials characterization and workforce training.
Foundries generate the highest absolute demand, though Semiconductor Manufacturers retain pricing leverage through consolidated procurement.
Application:
Application focus shifts with fab maturity from process development toward yield protection.
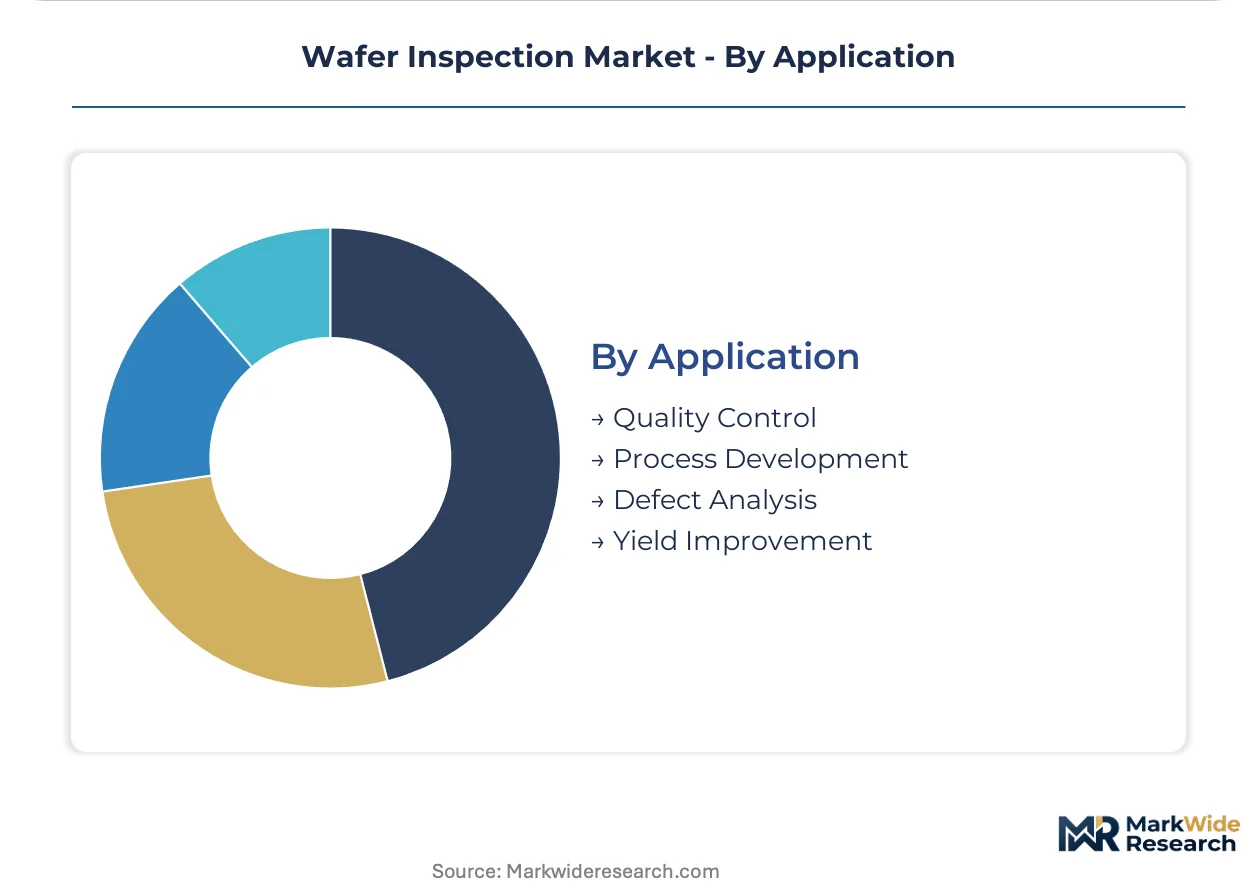
- Yield Improvement:Real-time defect classification using fab-specific machine learning libraries compresses feedback loops from hours to minutes. AI-driven process adjustment is displacing offline statistical analysis. Memory fabs deploy these capabilities most aggressively given die-level failure costs.
- Quality Control:Incoming wafer and outgoing die certification against ISO defect standards gates shipment authorization. Medical-grade chip applications trigger FDA quality system documentation requirements.
- Process Development:New node qualification requires extensive defect library construction before production ramp.
- Defect Analysis:Root-cause investigation of yield excursions supports continuous improvement and customer complaint resolution.
Yield Improvement attracts the steepest investment trajectory, while Quality Control maintains the broadest installed base across fab generations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Taiwan's Hsinchu corridor while procurement leverage accumulates in South Korea's Pyeongtaek complex. Equipment vendors command premium placement in Taiwanese foundry clusters where node transitions demand immediate tool availability. Korean memory producers extract volume discounts through consolidated technology group negotiations.
United States
Intel's Arizona and Oregon fabs drive demand for multi-beam e-beam inspection platforms at sub-3nm development nodes. EPA fluorinated gas regulations pressure yield-per-wafer economics, elevating inspection tool deployment density. The Albany Nanotech Complex in New York anchors public-private research consortia developing next-generation metrology standards.
Taiwan
TSMC's Hsinchu Science Park operations generate the world's densest concentration of 3nm-capable inspection infrastructure. Centralized technology group procurement now mandates API-accessible data streams, displacing proprietary vendor lock-in. Allied suppliers cluster within Taichung and Tainan science parks to minimize logistics latency for tool calibration.
South Korea
Samsung and SK Hynix internalize advanced packaging inspection previously outsourced to OSATs, expanding addressable tool markets. MFDS medical-grade chip documentation requirements tighten certification protocols for automotive and healthcare applications. The Pyeongtaek semiconductor complex commissions 100% wafer coverage systems for vertical NAND stack integrity verification.
Japan
Japanese precision optics suppliers control EUV mask blank polishing and coating, sustaining technical leadership in specialized inspection niches. METI industrial policy directs domestic foundry investment toward 2nm node development. Yokohama and Kyoto host concentrated clusters of electron source and vacuum chamber component fabricators.
China
Domestic GB standards on semiconductor self-sufficiency redirect foundry capex toward local inspection equipment vendors. MIIT technology roadmaps prioritize captive supply of optical and e-beam platforms for mature node production. Shanghai and Hefei science parks concentrate state-backed fab construction with integrated metrology procurement mandates.
Wafer Inspection Market Competitive Environment
Concentration sits with diversified equipment conglomerates that anchor inspection modules within broader process tool portfolios. The vendor base stratifies across three tiers: lithography-integrated platform suppliers, standalone optical specialists, and niche e-beam technology developers. Strategic moves center on unifying process control architectures and compressing vendor qualification cycles through API-standardized data interfaces. Consolidated procurement by foundry alliances is collapsing traditional hardware-plus-service contract bundling.
Within the diversified equipment tier, Applied Materials, Inc. and Lam Research Corporation exemplify platform integration strategies that embed metrology within deposition and etch clusters. KLA Corporation occupies a position representing standalone optical and e-beam inspection specialization, while Lasertec Corporation anchors the precision optics niche for EUV mask blank applications. Hitachi High-Tech Corporation and Onto Innovation Inc. sit within the technology-diversified mid-tier, with Camtek Ltd. and Teradyne Inc. representing packaging-focused inspection segments. ASML Holding N.V. exemplifies lithography-integrated process control convergence at sub-3nm nodes.
| Leading Market Players |
|---|
| Hitachi High-Tech Corporation |
| Onto Innovation Inc. |
| KLA Corporation |
| Camtek Ltd. |
| Teradyne Inc. |
| Applied Materials, Inc. |
| Lam Research Corporation |
| Lasertec Corporation |
| ASML Holding N.V. |
| Others |
Value Chain & Pricing Dynamics
180-to-270-day lead times for multi-beam e-beam inspection platforms concentrate pricing power with Japanese electron source and vacuum chamber suppliers, while foundry buyers in Taiwan and South Korea absorb premiums for configured-to-order systems that compress installation cycles.
Pricing Analysis
The customization-premium spread between standard optical inspection configurations and multi-beam e-beam systems configured for 3nm node compatibility exceeds three-to-one, with thermal field emission cathode replacement cycles inflating total cost of ownership. Pricing stratifies across premium multi-beam platforms, standard broadband plasma optical systems, and economy-tier refurbished tools, with ISO 14644-1 certification grade serving as the primary differentiation driver. Cost compression in economy tiers is intensifying because Chinese domestic vendors are redirecting mature node procurement toward local equipment under GB standards. Memory manufacturers at South Korea's Pyeongtaek complex exhibit the highest price sensitivity due to consolidated technology group negotiations, while Taiwan foundries accept premium positioning for immediate tool availability.
Supply Chain Analysis
Just-in-time inventory strategies dominate optical inspection procurement where component standardization permits rapid assembly, whereas multi-beam e-beam platforms require strategic stockpiling of thermal field emission cathodes given 12-to-18-month replacement cycles and single-source Japanese suppliers. Component fabrication concentrates in Japan for precision electron optics, the United States for plasma source subsystems, and Taiwan for robotic handling modules. Critical dependencies include specialized EUV-grade mirrors, high-voltage power supplies, and ultra-high vacuum chambers. Single-source vulnerability for mask blank polishing and coating equipment creates chokepoint exposure. Distribution runs through foundry technology group procurement offices rather than individual fab autonomy, compressing vendor qualification cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from computational inspection architectures that algorithmically reconstruct defect signatures without physical probe scaling, eroding the resolution advantage that justifies premium hardware pricing.
For Market Incumbents: Consolidate API-accessible data stream capabilities to displace proprietary software lock-in that TSMC's supplier consolidation program now mandates. Deepen captive supply of electron source components to offset Japanese single-source vulnerability for thermal field emission cathodes. Vertical integration into vacuum chamber fabrication reduces lead time exposure that currently concentrates pricing power with Yokohama and Kyoto component suppliers.
For New Entrants and Emerging Players: Differentiate on AI-driven defect classification latency, compressing feedback loops from hours to minutes against incumbent offline statistical analysis workflows. Target India's PLI-subsidized greenfield fab construction where legacy tool replacement constraints do not apply. Penetrate advanced packaging inspection for hybrid bonding and chiplet integration applications that extend requirements beyond front-end wafer metrology.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EPA fluorinated gas regulations and EU F-Gas phase-down schedules are structurally elevating yield-per-wafer economics that reposition inspection from overhead to strategic yield protection. Acquisition targets should prioritize specialized EUV mask blank inspection niches where Japanese precision optics sustain technical leadership against broader-platform competitors. Watch for inflection when China's GB procurement mandates fragment equipment interoperability and create captive domestic vendor ecosystems.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding spectroscopic ellipsometry within Applied Materials deposition clusters eliminates queue time at Dresden memory fabs. |
| Specialist Firm Acquisition | Capturing EUV mask blank inspection expertise from Japanese precision optics suppliers secures niche technical leadership. |
| Geographic Expansion | Establishing service presence in India's PLI-subsidized semiconductor corridors captures greenfield infrastructure demand. |
| Strategic Partnership | API-accessible data stream alliances with TSMC's centralized technology group displace proprietary vendor lock-in. |
| Product Launch | Multi-beam architectures with extended thermal cathode lifetimes reduce 12-to-18-month replacement cost burdens. |
Study Parameters
The analysis maps optical inspection, e-beam inspection, and integrated metrology sub-sectors, each validated through equipment procurement directors at foundry technology groups, field service engineers managing multi-beam platform uptime, and vacuum chamber component fabricators in Japan. Primary interviews with fab operations executives, SEMI standards committee participants, and regulatory affairs specialists at EPA and METI combined with secondary validation through SEC 10-K filings, SEMI equipment market data, customs records for lithography subsystem trade flows, and ISO certification registries. Bottom-up tool shipment tracking and top-down foundry capex analysis triangulate market sizing.
Consistency checks against external benchmarks validated projection outputs against SEMI capital equipment forecasts and foundry alliance disclosed spending plans across the projection horizon. Segmentation dimensions modeled include technology type, equipment automation level, end-user category, and application focus. CAGRs derived from node transition timelines and inspection tool deployment density assumptions. Industry-specific inputs incorporated EUV lithography scaling roadmaps, F-Gas regulation compliance schedules, and China GB procurement mandate implementation trajectories.
Material uncertainties — abrupt node transition delays, electron source supply disruptions, or China domestic vendor substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued EUV lithography scaling, stable Japan-US-Taiwan supplier triad relationships, and linear regulatory phase-in schedules. Revision becomes warranted when China GB procurement mandates cross thresholds that fragment equipment interoperability standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
LCR Meter Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Scuff Tester Market
Test and Measurement
Structure Tester Market
Test and Measurement
Global Conductivity Meters Market
Test and Measurement
VXI Test Equipment Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
Bit Error Rate Tester Market
Test and Measurement
5G Testing Equipment Market
Test and Measurement
AI-Enabled Semiconductor Defect Classification and Review Systems Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Video Measuring System Market