
 Chiplet Integration and Die-to-Die Interconnect Test Solutions Market | 2026-2036
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market Insights
ISO 26262 qualification is bifurcating the supplier landscape for automotive-grade chiplet test systems. Advantest leverages its installed base in memory test to extend into die-to-die interconnect validation. Teradyne competes through R&D intensity in high-parallelism ATE architectures for advanced packaging.
Chiplet integration and die-to-die interconnect test solutions encompass electrical, optical, and thermal verification methods applied to heterogeneous die assemblies, with UCIe and BoW protocols defining lane pitch, bump density, and signal integrity thresholds for sub-micron interconnects. Probe cards and automated test equipment command the largest revenue pools, while optical testing and time-domain reflectometry represent faster-growing technology segments as silicon photonics chiplets proliferate. Fabless companies and foundries drive volume demand, though OSAT providers are capturing expanding margin pools as packaging complexity shifts test requirements downstream.
The U.S. CHIPS Act and NIST standards, alongside EU REACH material restrictions and Taiwan's CEA semiconductor infrastructure policies, are reshaping equipment qualification timelines and substrate material choices for test fixture manufacturers. Japan's METI supply chain resilience programs and South Korea's K-Chips Act are accelerating domestic test capacity buildouts. Stakeholders must monitor which interconnect standard—UCIe, BoW, or proprietary alternatives—achieves ecosystem lock-in, as this will determine capital allocation across probe card geometries and measurement instrument roadmaps.
Market Dynamics
UCIe protocol consolidation is compressing test equipment development cycles while concentrating procurement authority among advanced packaging foundries in Taiwan, South Korea, and the United States.
Growth Catalysts
- Heterogeneous Integration Mandates:High-performance computing clusters in data centers are mandating chiplet architectures to overcome reticle limits, pulling die-to-die interconnect validation into critical path workflows.
- REACH Material Compliance:EU substrate material restrictions are accelerating qualification of lead-free probe card geometries, creating replacement demand across European OSAT networks.
- Silicon Photonics Proliferation:Optical I/O chiplets are expanding test coverage requirements beyond electrical domains into time-domain reflectometry and waveguide integrity verification.
Market Restraints
- Probe Card Substrate Concentration:Advanced organic substrate supply concentrates among Japanese and Taiwanese laminate suppliers, exposing test fixture manufacturers to allocation risk during capacity crunches.
- ISO 26262 Qualification Burden:Automotive-grade test system certification timelines extend 18-24 months, freezing out suppliers lacking functional safety development heritage.
- Copper Pillar Bump Pitch Limits:Sub-10 micron pitch interconnects are approaching physical limits of conventional probe card mechanical compliance, constraining test access for next-generation UCIe implementations.
Strategic Opportunities
- India OSAT Buildout:PLI scheme incentives for semiconductor packaging are attracting test equipment deployment into Gujarat and Karnataka greenfield facilities.
- AI-Driven Test Pattern Generation:Machine learning algorithms trained on interconnect failure modes are converging with adaptive ATE architectures to compress test program development cycles.
- K-Chips Act Domestication:South Korean capital subsidies for advanced packaging test capacity are creating localized procurement channels bypassing incumbent supplier relationships.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:Electromagnetic-thermal-mechanical co-simulation expertise for 3D package test fixture design remains concentrated among a handful of specialized engineering consultancies.
- Legacy ATE Architecture Obsolescence:High-parallelism requirements for known-good-die screening are forcing premature retirement of installed base equipment with inadequate channel density.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chiplet Integration and Die-to-Die Interconnect Test Solutions Market |
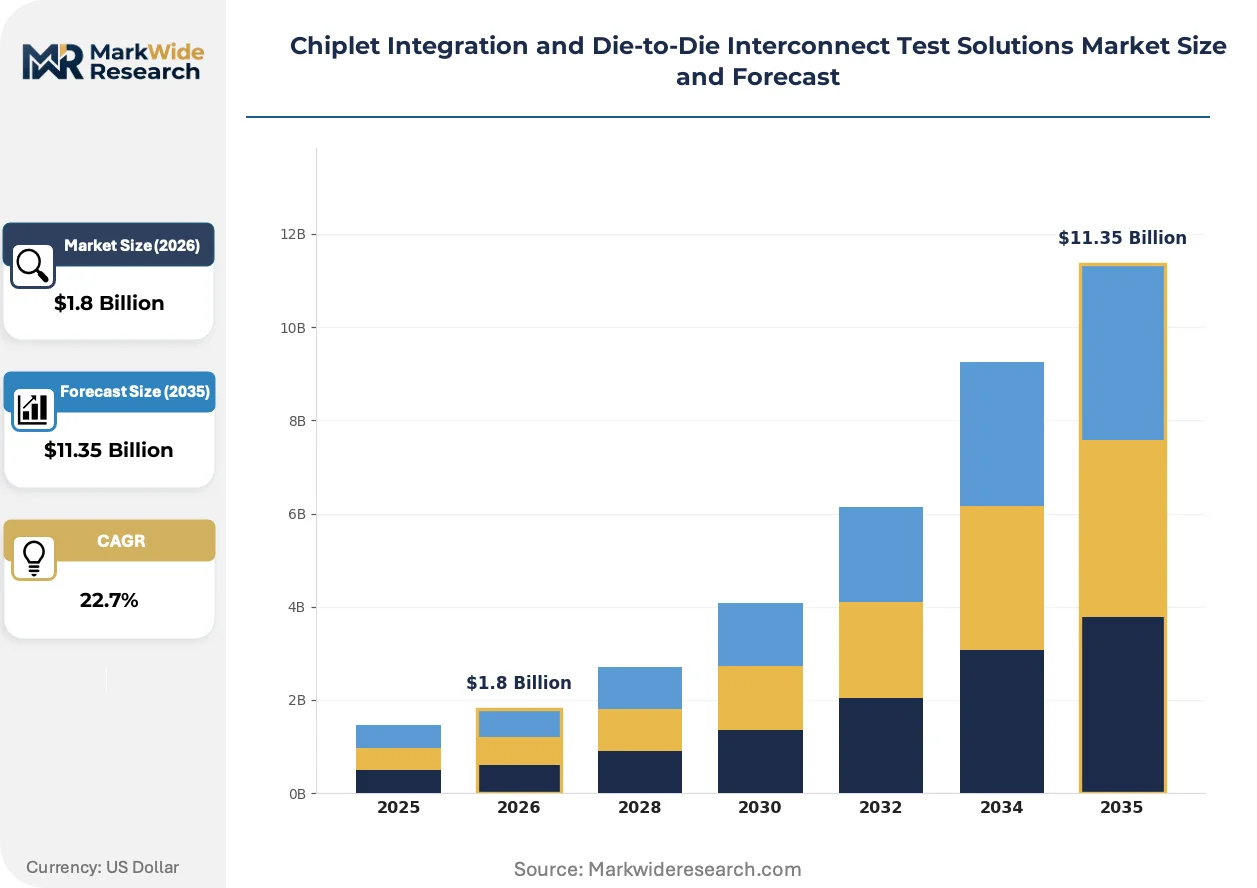
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probe Cards, Test Fixtures, Load Boards, Measurement Instruments, Calibration Tools Technology: Electrical Testing, Optical Testing, Thermal Analysis, Time-Domain Reflectometry, Automated Test Equipment Application: Semiconductor Manufacturing, Chiplet Validation, Package Verification, Reliability Testing, Electrical Characterization End User: Fabless Companies, Foundries, IDM Manufacturers, OSAT Providers, Research Laboratories |
| Companies Covered | Advantest, Teradyne, FormFactor, Cohu, Chroma ATE, Synopsys, Siemens EDA, Cadence Design Systems, Keysight Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market Trends and Innovations
Test methodology convergence is blurring boundaries between wafer probe, final test, and system-level validation as chiplets demand in-situ interconnect characterization across assembly stages.
Photonic probe interfaces are miniaturizing waveguide-to-fiber coupling structures for silicon photonics chiplets. Cloud hyperscalers deploying optical I/O architectures are qualifying these interfaces at production scale. This photonic test hardware is miniaturizing optical path lengths to reduce polarization-dependent loss measurement uncertainty.
CEA semiconductor infrastructure policies in Taiwan are mandating domestic content thresholds for test equipment procurement in Hsinchu Science Park expansion zones. Equipment vendors are localizing software development and calibration service operations to maintain foundry access. Advanced packaging R&D consortia are most affected, redirecting supplier qualification resources toward Taiwan-specific compliance documentation.
Foundries are consolidating test program ownership previously fragmented across OSAT partners. Direct procurement of die-to-die interconnect validation suites by TSMC and Samsung Foundry is displacing traditional OSAT-mediated equipment acquisition. This buyer concentration is most visible in Taiwan, where packaging complexity shifts are compressing supplier negotiation leverage.
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market Segmentation
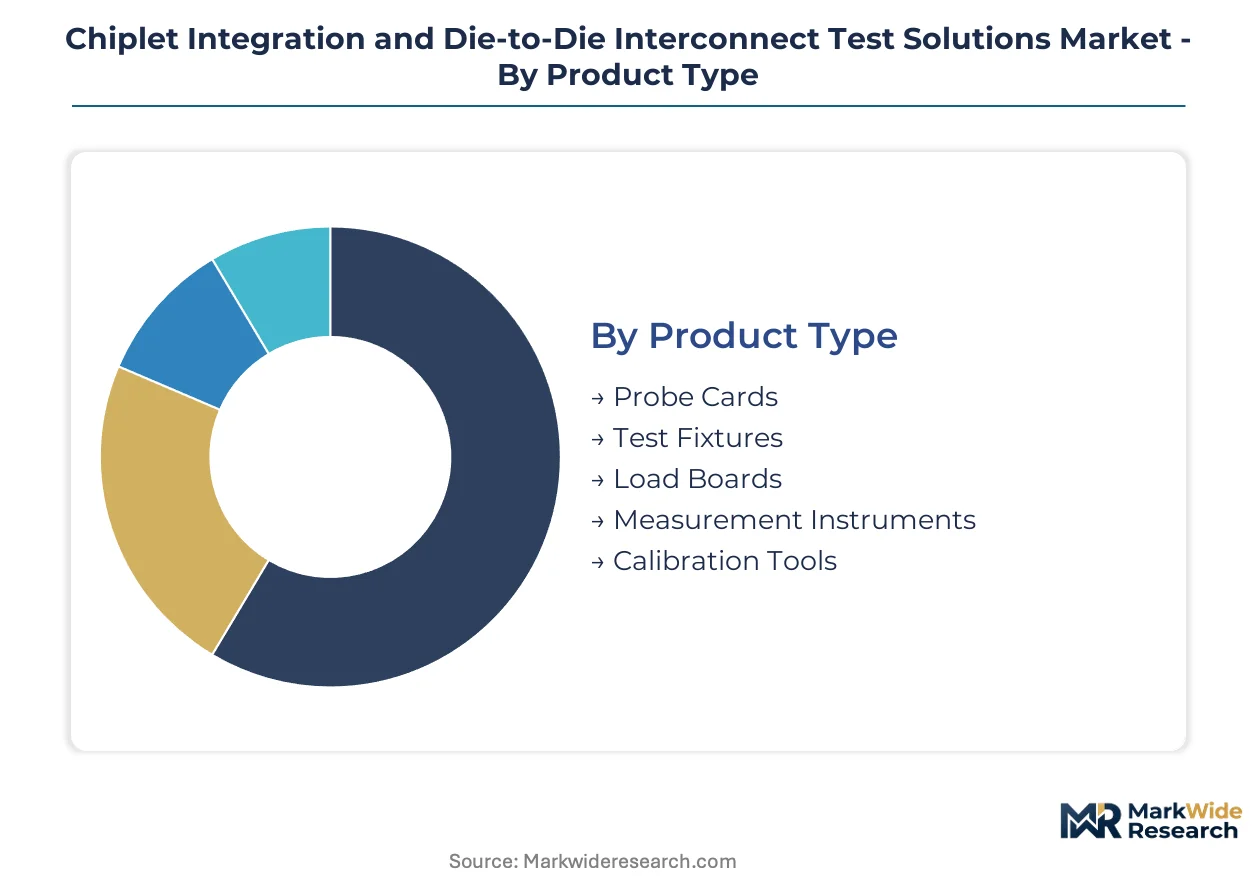
Test solution architectures fragment across hardware layers, measurement domains, and customer procurement hierarchies. Each segmentation axis reveals distinct margin concentration points and technology substitution risks.
Product Type:
Probe cards and test fixtures capture the deepest margin pools due to substrate material complexity and customization intensity.
- Probe Cards:Multi-layer organic substrates with micro-spring or MEMS contactor arrays interface with sub-10 micron bump pitches. Advanced packaging foundries in Taiwan drive specification escalation through UCIe lane density requirements. Copper pillar compliance limits are forcing cantilever redesigns toward vertical probe architectures.
- Test Fixtures:Socket assemblies and thermal management hardware bridge ATE systems to packaged chiplets. OSAT providers in South Korea are consolidating procurement authority for high-parallelism configurations. Fixture lifecycles compress as package form factors proliferate.
- Load Boards:Printed circuit board interfaces route signals between device under test and ATE instrumentation.
- Measurement Instruments:High-bandwidth oscilloscopes and vector network analyzers characterize signal integrity.
- Calibration Tools:Reference standards and traceability systems ensure measurement accuracy across production shifts.
The dominant share belongs to probe cards, while test fixtures are closing the gap fastest.
Technology:
Cost tier stratification separates capital-intensive ATE platforms from specialized instrumentation addons.
- Electrical Testing:Parametric and functional validation of UCIe and BoW interconnects dominates current test floor allocation. Foundries in the United States mandate DC and AC characterization at wafer probe and final test stages. Signal integrity thresholds tighten with each protocol revision.
- Optical Testing:Waveguide insertion loss and polarization-dependent loss verification addresses silicon photonics chiplets. Cloud hyperscalers deploying optical I/O architectures are qualifying photonic probe interfaces at production scale. Measurement uncertainty reduction drives fiber-to-chip coupling miniaturization.
- Thermal Analysis:Infrared thermography and thermal transient testing identify hot spots in 3D stacks.
- Time-Domain Reflectometry:Impedance discontinuity detection locates open and short defects in fine-pitch interconnects.
- Automated Test Equipment:High-parallelism system-on-chip testers execute pattern-based functional validation.
Electrical testing maintains volume leadership, though optical testing is expanding most quickly.
Application:
Customer type determines workflow integration depth and service attachment rates.
- Semiconductor Manufacturing:Wafer-level probe and sort operations screen die before assembly. Fabless companies in Taiwan and South Korea outsource these steps to foundry partners with captive test capacity. Yield learning cycles accelerate through real-time defect classification.
- Chiplet Validation:Known-good-die verification and interconnect protocol compliance testing precede heterogeneous integration. IDM manufacturers with internal packaging operations retain these workflows in-house. UCIe physical layer certification requirements are extending test program development timelines.
- Package Verification:Post-assembly functional and structural integrity checks confirm assembly quality.
- Reliability Testing:Temperature cycling and electromigration stress qualification ensure operational longevity.
- Electrical Characterization:Corner case validation and shmoo plotting define operating margins.
Semiconductor manufacturing commands the largest revenue pool, with chiplet validation gaining share fastest.
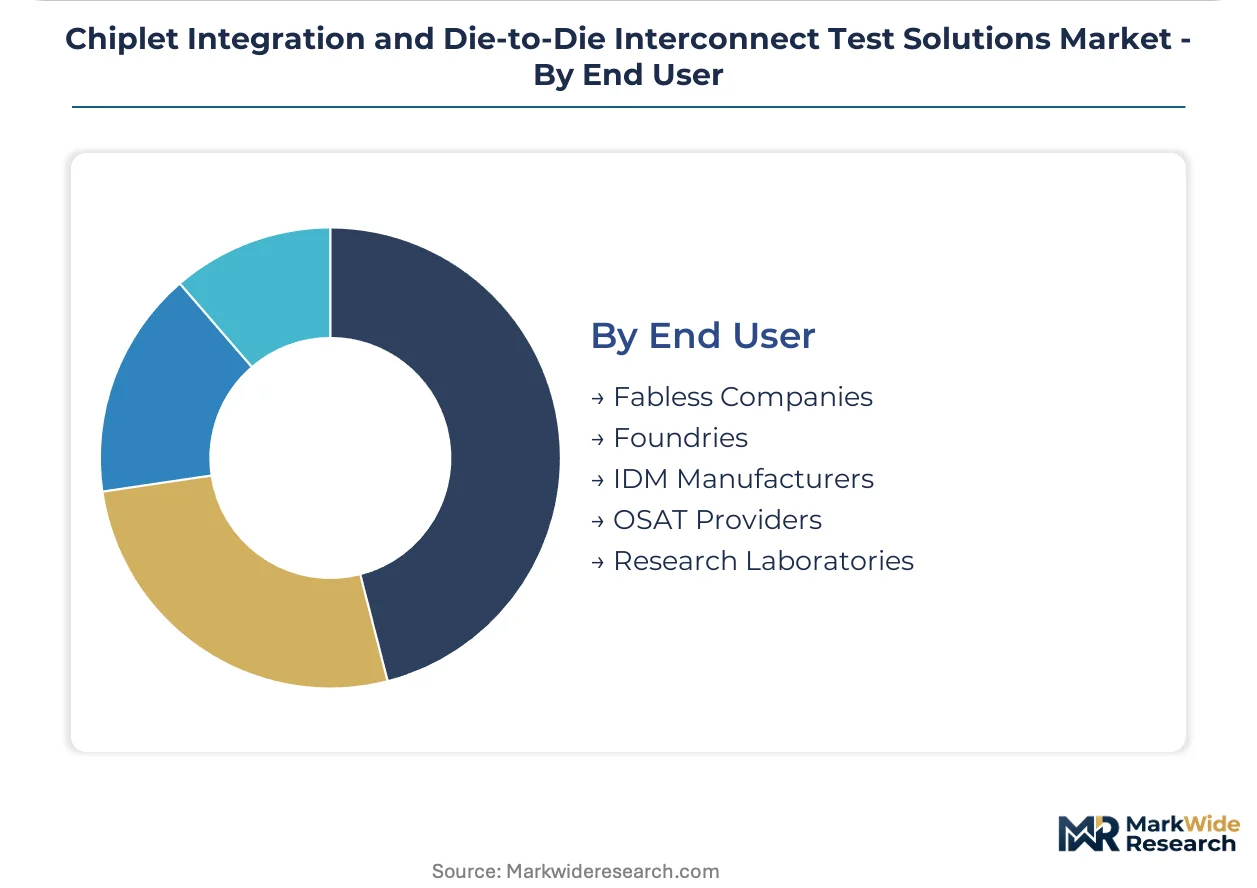
End User:
Supply concentration among advanced packaging foundries is displacing fragmented OSAT procurement patterns.
- Fabless Companies:Design houses without fabrication assets rely on foundry and OSAT partners for test execution. NVIDIA and AMD are driving chiplet architecture adoption in data center accelerators. Direct test program specification involvement is deepening as packaging complexity rises.
- Foundries:TSMC and Samsung Foundry are consolidating test ownership previously fragmented across OSAT networks. Taiwan's CEA semiconductor infrastructure policies mandate domestic content thresholds for equipment procurement in Hsinchu Science Park expansion zones. Supplier qualification resources are redirecting toward Taiwan-specific compliance documentation.
- IDM Manufacturers:Vertically integrated producers with captive packaging maintain end-to-end test control.
- OSAT Providers:Assembly and test subcontractors are capturing expanding margin pools as advanced packaging shifts test requirements downstream.
- Research Laboratories:University and consortium R&D facilities pilot next-generation interconnect technologies.
Foundries hold the dominant procurement position, while OSAT providers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital subsidies for semiconductor packaging are redrawing procurement geography across four major economies. Equipment qualification timelines now hinge on domestic content mandates and foundry proximity requirements.
United States
NIST standards and CHIPS Act funding are accelerating test capacity buildouts in Arizona and Texas. The EPA oversees chemical handling protocols for probe card substrate manufacturing. Intel's expanding packaging footprint in Chandler and Samsung's Taylor facility are consolidating die-to-die interconnect validation workflows domestically.
Taiwan
Advanced packaging foundries in Hsinchu Science Park command the deepest probe card specification pools. CEA semiconductor infrastructure policies mandate domestic content thresholds for equipment procurement in expansion zones. TSMC's CoWoS capacity ramp is compressing supplier negotiation leverage as test program ownership consolidates upstream.
South Korea
K-Chips Act subsidies are localizing advanced packaging test capacity around Seoul and Pyeongtaek. METI-aligned supply chain resilience programs accelerate domestic equipment vendor qualification. Samsung Foundry's direct procurement of UCIe validation suites is displacing traditional OSAT-mediated acquisition channels.
Japan
Advanced organic substrate supply concentrates among laminate suppliers in Nagoya and Osaka corridors. METI supply chain resilience programs prioritize domestic test fixture manufacturing. Tokyo Electron and Shin-Etsu Chemical anchor probe card material ecosystems serving Taiwan and South Korean foundry demand.
India
PLI scheme incentives for semiconductor packaging are attracting test equipment deployment into Gujarat and Karnataka greenfield facilities. The country's national electronics regulator oversees import substitution timelines for ATE systems. Tata Electronics' Dholera facility and CG Power's Sanand plant are establishing first-mover probe card calibration service networks.
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market Competitive Landscape
Player mix skews toward ATE incumbents with memory test heritage extending into advanced packaging validation. Three archetypes dominate: Japanese precision instrument specialists, US high-parallelism system architects, and Taiwan-focused probe card substrate engineers. Competitive moves concentrate on R&D intensity in high-channel-density architectures and strategic localization of software development for foundry compliance.
Among Japanese ATE specialists, Advantest leverages its installed base position to anchor die-to-die interconnect validation workflows. Teradyne exemplifies the US high-parallelism archetype through R&D intensity in system-on-chip tester architectures. FormFactor occupies a position within the probe card specialization tier, representing substrate engineering expertise concentrated around Hsinchu customer proximity. These three companies collectively illustrate how heritage in adjacent test domains creates wedge opportunities into chiplet-specific validation requirements.
| Leading Market Players |
|---|
| Advantest |
| Teradyne |
| FormFactor |
| Cohu |
| Chroma ATE |
| Synopsys |
| Siemens EDA |
| Cadence Design Systems |
| Keysight Technologies |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day probe card substrate lead times concentrate pricing power with Japanese and Taiwanese laminate suppliers, compressing margins for test fixture manufacturers while amplifying cost pass-through leverage at the raw material tier.
Pricing Analysis
Certification level creates the primary spread across automotive-grade ISO 26262-qualified systems and standard industrial-tier equipment. Three-tier pricing structure across premium, standard, and economy levels segments by channel density, thermal management sophistication, and after-sales calibration bundling. Cost compression in standard-tier probe cards is intensifying because foundries in Taiwan are consolidating procurement volumes and demanding volume-scaled contract terms. Fabless companies exhibit the highest price sensitivity due to outsourced test execution models, while captive foundry test operations show the least.
Supply Chain Analysis
Ninety-day organic substrate inventory cycles expose test fixture manufacturers to allocation risk during capacity crunches in Japan and Taiwan. Advanced multi-layer laminate supply draws from Nagoya and Osaka corridors in Japan alongside Hsinchu-adjacent Taiwanese suppliers. Probe card manufacturing rests on copper-clad resin systems, MEMS contactor arrays, and precision-machined ceramic substrates. Single-source vulnerability concentrates in ABF substrate supply for sub-10 micron pitch applications. Distribution runs through direct foundry procurement channels that are displacing traditional OSAT-mediated equipment acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protocol fragmentation across UCIe, BoW, and proprietary interconnect standards is carving out specialized validation niches for equipment vendors with domain-specific measurement expertise.
For Market Incumbents: Consolidate probe card substrate supply relationships through backward integration into laminate manufacturing or long-term offtake agreements with Japanese suppliers. Lock in foundry-direct procurement channels before OSATs lose remaining negotiation leverage. Defend against emerging photonic test specialists by accelerating MEMS-based optical probe interface R&D.
For New Entrants and Emerging Players: Anchor in silicon photonics test instrumentation where established ATE vendors lack optical domain heritage. Target cloud hyperscaler validation labs deploying optical I/O chiplets as the most penetrable entry point. Pursue a specialist-acquisition go-to-market angle by licensing time-domain reflectometry algorithms from university research consortia.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because foundry procurement concentration will compress supplier counts to three-to-five dominant platforms. Prioritize targets with ISO 26262 development heritage and established calibration service networks in Taiwan. Watch for inflection when UCIe protocol revision timelines stabilize and capital allocation shifts from specification uncertainty to capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Manufacturing | Secures ABF laminate supply for sub-10 micron pitch probe cards against Japanese supplier allocation risk. |
| Photonic Probe Interface Miniaturization | Reduces polarization-dependent loss measurement uncertainty for cloud hyperscaler optical I/O deployments. |
| Taiwan Software Development Localization | Satisfies CEA domestic content thresholds for Hsinchu Science Park equipment procurement mandates. |
| AI-Driven Test Pattern Generation | Compresses UCIe physical layer certification timelines through machine learning on interconnect failure modes. |
| India OSAT Calibration Service Buildout | Captures PLI scheme incentives at Tata Electronics Dholera and CG Power Sanand greenfield facilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings from ATE vendors, foundry capex disclosures, and UCIe consortium technical specifications. Interviews with probe card engineering directors, foundry test operations managers, OSAT procurement leads, and semiconductor packaging R&D heads inform demand-side validation. Secondary sources include customs trade data for test equipment imports, Taiwan CEA policy documents, and METI supply chain resilience program filings. Bottom-up equipment shipment analysis triangulates against top-down foundry packaging capacity buildout projections.
Segmentation dimensions modeled span product type, measurement technology, application workflow, and end-user procurement hierarchy across the projection horizon. CAGRs derive from installed base replacement cycles, protocol adoption curves, and foundry capacity expansion schedules. Forecast inputs incorporate UCIe lane density specification escalations, copper pillar pitch compliance limits, and silicon photonics chiplets penetration into data center accelerators.
Decision-makers should treat outputs as directional under assumptions of UCIe protocol consolidation and sustained foundry packaging capacity investment; material deviation would warrant model refresh. Specific risk factors include REACH substrate material restriction enforcement intensity, automotive-grade certification timeline extensions, and optical I/O architecture deployment delays by cloud hyperscalers. Revision becomes warranted when UCIe versus BoW standard adoption rates cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Tensile Testers Market
Test and Measurement
Digital Weighing Machine Market
Test and Measurement
Shock Data Logger Market
Test and Measurement
Uniaxial Tester Market
Test and Measurement
Manufacturing Test Systems Market
Test and Measurement
Metal Testing Equipment Market
Test and Measurement
Battery Resistance Tester Market
Test and Measurement
Calibration Management Software Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Telecom Testing Equipment Market
Test and Measurement
Global Source Measure Unit Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Non Destructive Testers (NDT) Equipment Market
Test and Measurement
Global 5G Test Equipment Market