
 Hay and Forage Rakes Market | 2026-2036
Hay and Forage Rakes Market Size, Share, and Industry Trends Forecast 2026-2036
Hay and Forage Rakes Market Insights
Dealer networks serving mid-sized hay producers is tilting toward bundled service contracts that include precision agriculture support. John Deere leverages its integrated farm management platform to lock in repeat equipment purchases. Kuhn Group anchors its position through specialized rotary rake engineering that commands premium placement in European cooperatives. AGCO Corporation competes via broad geographic coverage across North American and South American dealer footprints.
Hay and forage rakes are ground-driven or power-take-off implements engineered with tine spacing of 2.5 to 4 inches to gather cut forage into windrows without leaf loss, operating at field speeds of 8 to 12 miles per hour to preserve nutritional value in alfalfa and grass hays. Rotary rake configurations now lead unit shipments due to gentler crop handling that reduces dry matter loss compared with wheel rake alternatives. Hydraulic technology deployments are expanding fastest as producers retrofit existing tractors with remote tine adjustment capabilities. Agricultural producers represent the deepest margin pool among end users, though contractor fleets are consolidating purchasing power across multi-state operations.
USDA conservation programs and EPA non-road emissions standards shape equipment design requirements for American manufacturers, while EU Machinery Directive safety mandates and F-Gas Regulation refrigerant rules constrain hydraulic system specifications for European imports. Farm equipment stakeholders must monitor how carbon accounting frameworks will redefine equipment lifecycle valuations and resale premiums.
Market Dynamics
Dairy farm consolidation across the American Midwest is compressing equipment replacement cycles while EU sustainability mandates are forcing redesigns toward lower soil compaction. This dual pressure is reshaping manufacturer R&D allocation and dealer service bundling simultaneously.
Growth Catalysts
- USDA Conservation Programs:Cost-share incentives for precision hay equipment accelerate mechanized forage harvesting adoption among mid-sized producers in Wisconsin and Minnesota.
- Commercial hay export infrastructure:Brazil's scaling operations for Middle Eastern dairy markets concentrate demand for high-capacity rotary rakes with gentle crop handling.
- Hydraulic retrofit technology:Remote tine adjustment capabilities allow producers to upgrade existing tractor fleets without full equipment replacement, extending addressable market reach.
Market Restraints
- Steel input volatility:Tine and frame manufacturing costs fluctuate with commodity pricing, compressing margin predictability for mid-tier equipment suppliers.
- EPA non-road emissions standards:Tier 4 Final compliance requirements add engineering complexity and certification overhead for power-take-off driven implements.
- Wheel rake substitution pressure:Lower capital cost alternatives retain share among price-sensitive hay contractors in fragmented regional markets.
Strategic Opportunities
- Carbon accounting frameworks:Equipment lifecycle valuation methodologies under development will create resale premium differentiation for documented low-compaction designs.
- Precision agriculture bundling:Dealer networks can capture recurring revenue through integrated farm management platform subscriptions tied to rake telemetry.
- Middle Eastern import demand:Saudi and UAE dairy expansion projects require consistent hay supply quality that rotary rake gentle handling uniquely delivers.
Industry Challenges
- Hydraulic technician scarcity:Remote tine adjustment systems require specialized service capability that rural dealer networks struggle to staff.
- EU F-Gas Regulation compliance:Hydraulic system refrigerant specifications constrain import certification timelines for European market entry.
- Legacy tractor integration:Retrofit kit compatibility testing across disparate hydraulic port configurations consumes engineering resources without guaranteed volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hay and Forage Rakes Market |
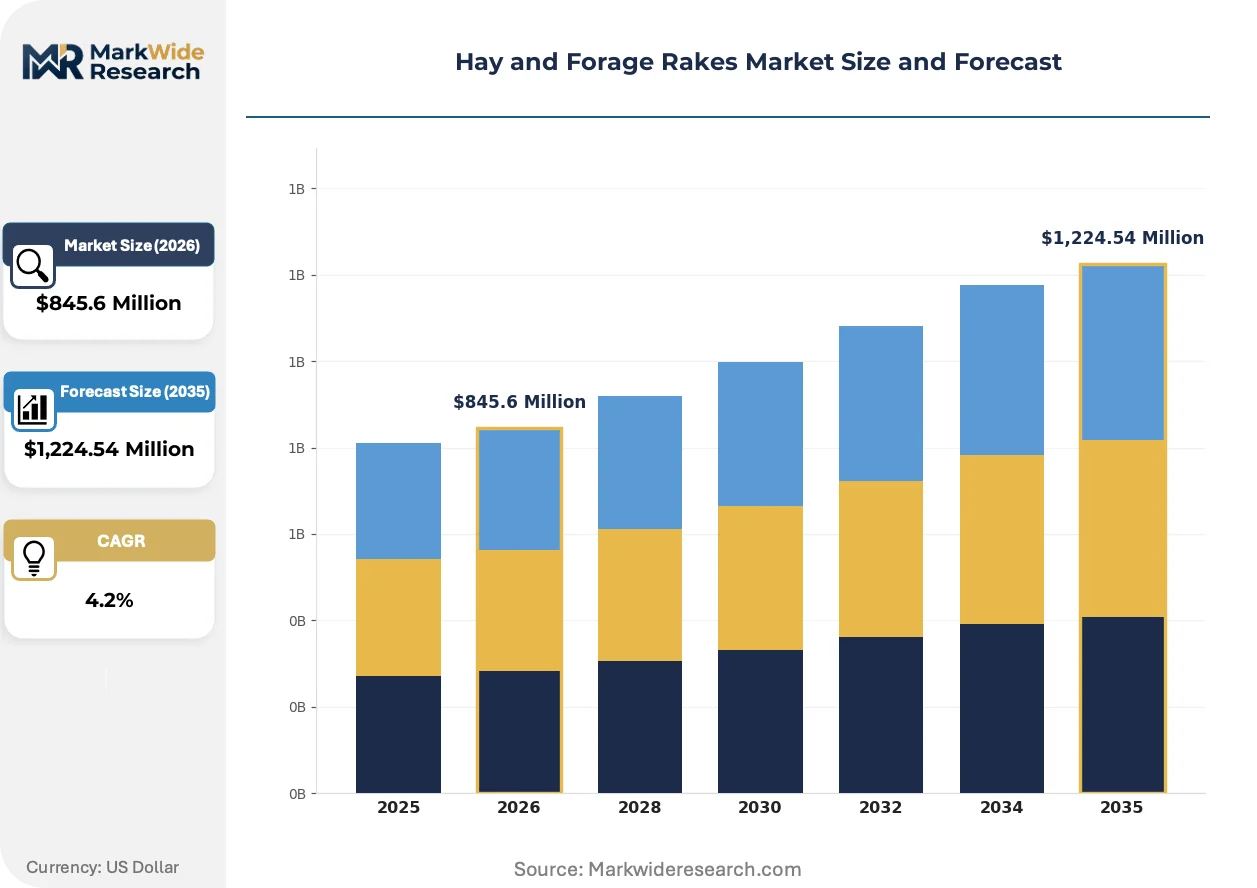
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,224.54 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Rakes, Wheel Rakes, Star Rakes, Landscape Rakes Technology: Hydraulic, Mechanical, Electric, Pneumatic End User: Agricultural Producers, Contractors, Farmers, Landscape Companies Deployment: On-field, Off-field, Portable, Stationary |
| Companies Covered | John Deere, Kuhn Group, New Holland Agriculture, CLAAS Group, AGCO Corporation, Vermeer Corporation, Krone, Kubota Corporation, Maschio Gaspardo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hay and Forage Rakes Market Trends and Innovations
Equipment intelligence and sustainability certification are converging to redefine competitive differentiation. Manufacturers now compete on data integration depth and environmental footprint documentation rather than mechanical reliability alone.
Variable tine spacing technology is migrating from fixed mechanical settings to continuous hydraulic adjustment. Large-scale dairy operations in California's Central Valley are adopting these systems to optimize windrow density across alfalfa cutting schedules. This capability compression is enabling real-time field adjustments that reduce dry matter loss by matching rake aggression to crop moisture conditions.
The EU Farm to Fork Strategy's soil health mandates are forcing redesigns of ground-contact components. Manufacturers must now document pressure-per-square-inch metrics to access cooperative purchasing channels in Germany and France. Rotary rake designs with wider flotation tires and flexible frame geometry are capturing placement in these sustainability-sensitive procurement pools.
Service contract unbundling is fragmenting traditional dealer relationships. Independent precision agriculture consultants in Iowa and Nebraska now specify equipment brands based on API openness rather than historical loyalty. This channel disruption is most visible among contractor fleets operating across multi-state hay production zones where standardized telematics reduce operational complexity.
Hay and Forage Rakes Market Segmentation
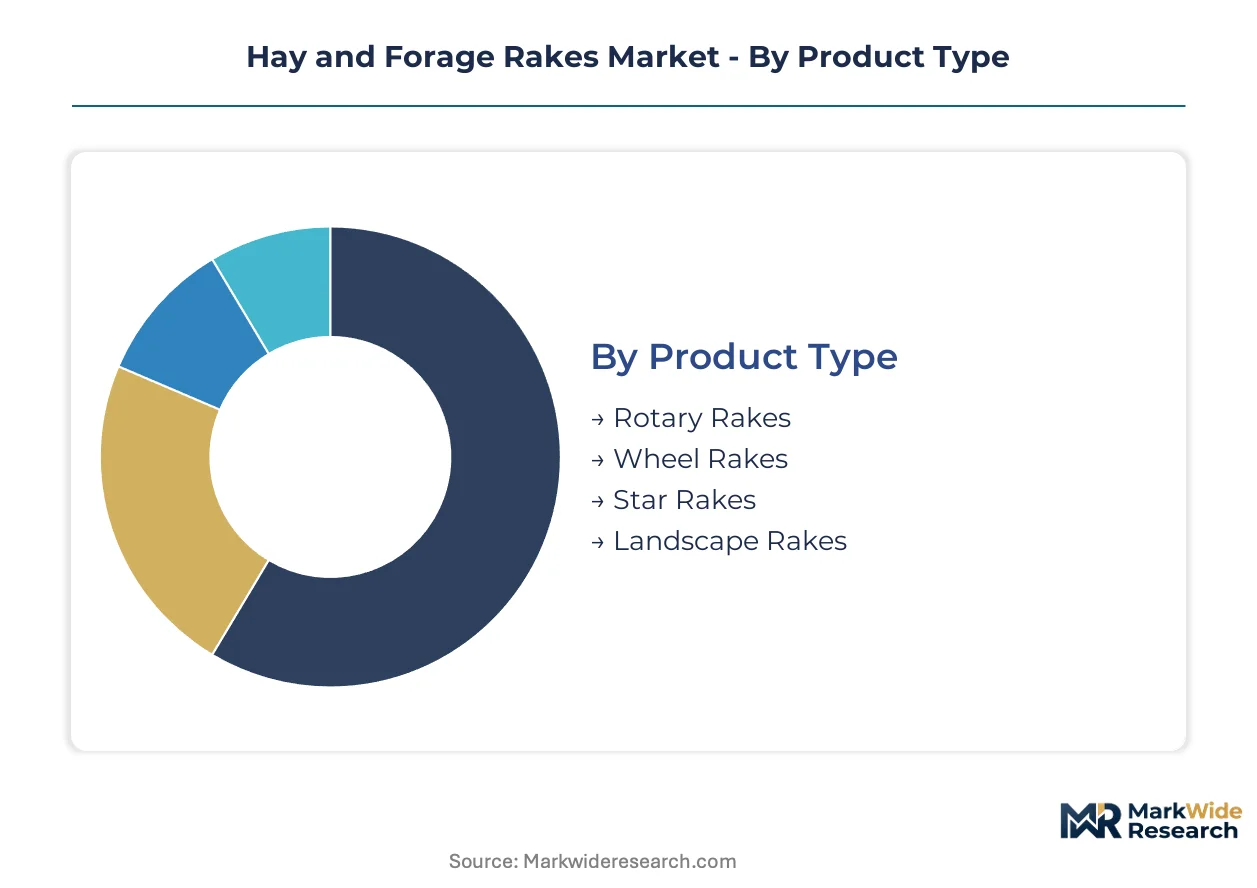
Hay and forage rakes serve distinct operational profiles across dairy, export hay, and landscaping verticals. Segmentation reveals how technology adoption and user scale reshape equipment specifications and service bundling strategies.
Product Type:
Mature mechanical designs dominate volume shipments while emerging configurations target precision handling requirements.
- Rotary Rakes:Tine arms rotate around a central axis with gentle crop engagement that preserves leaf retention in alfalfa. Dairy operations in California's Central Valley specify these for multi-cutting schedules where dry matter loss directly impacts feed value.
- Wheel Rakes:Ground-driven tine wheels offer lower capital entry points with simpler maintenance profiles. Price-sensitive hay contractors in fragmented US regional markets retain these for single-species grass hay where leaf fragility matters less.
- Star Rakes:Radial tine arrays handle heavy crop volumes in European cooperative settings with standardized windrow widths.
- Landscape Rakes:Utility-focused designs serve non-agricultural turf management with interchangeable tine configurations for debris clearing.
Rotary rakes handle the majority of throughput; landscape rakes are gaining share fastest among non-traditional user bases.
Technology:
Cost tier stratification separates premium hydraulic systems from entry-level mechanical alternatives.
- Hydraulic:Remote tine adjustment enables real-time field calibration via tractor-mounted controls. Brazilian commercial hay exporters retrofit existing fleets to access Middle Eastern dairy contract specifications without full equipment replacement.
- Mechanical:Fixed linkage systems eliminate hydraulic complexity and service dependency. Smaller Wisconsin and Minnesota producers under USDA conservation cost-share programs select these for predictable maintenance budgets.
- Electric:Battery-actuated prototypes target compact tractor integration in European vineyards with emissions restrictions.
- Pneumatic:Compressed air systems serve specialized turf applications requiring rapid tine pressure modulation.
Hydraulic systems capture the premium tier; electric configurations show the steepest expansion trajectory in regulatory-constrained environments.
End User:
Customer type determines margin structure and purchasing consolidation patterns across the value chain.
- Agricultural Producers:Owner-operators with deep equipment knowledge prioritize mechanical reliability and dealer proximity. These users generate the deepest margin pool through repeat parts purchases and seasonal service contracts.
- Contractors:Multi-state fleet operators consolidate purchasing power and standardize on brands with open API telematics. Iowa and Nebraska-based hay contractors now specify equipment based on data platform compatibility rather than historical dealer relationships.
- Farmers:Diversified operations with intermittent hay production represent price-sensitive sporadic demand.
- Landscape Companies:Municipal and commercial turf managers seek utility versatility over crop-specific optimization.
Agricultural producers anchor the installed base; contractors are expanding most quickly through fleet consolidation.
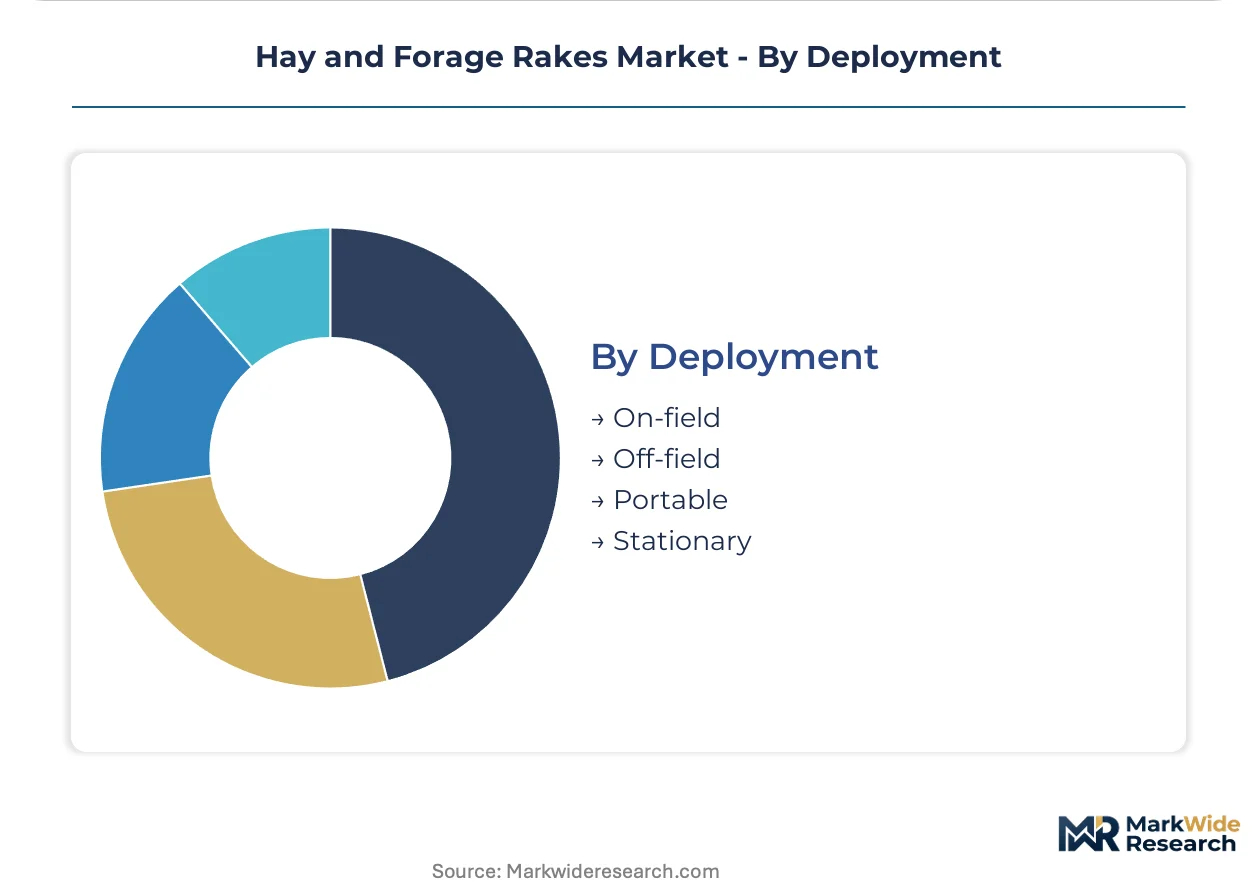
Deployment:
Application context dictates mobility requirements and integration complexity with existing tractor fleets.
- On-field:Permanently mounted implements integrate with dedicated hay equipment lines in large-scale dairy operations. These configurations maximize hourly throughput in California and Wisconsin consolidated farm settings.
- Off-field:Transportable units serve custom harvesters moving between dispersed client properties. Brazilian export hay operations use these for rapid relocation between cutting and baling zones.
- Portable:Quick-attach systems enable tractor sharing across crop and livestock operations on mid-sized Midwest farms.
- Stationary:Fixed-position raking stations serve specialized drying and processing facilities with conveyor integration.
On-field deployment accounts for the largest equipment base; off-field configurations are climbing fastest with contractor fleet expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA conservation programs anchor demand patterns across the American Midwest, while EU sustainability mandates and Brazilian export infrastructure reshape equipment specifications in their respective markets.
United States
Dairy farm consolidation in Wisconsin and Minnesota compresses replacement cycles for precision hay equipment. USDA cost-share incentives under Environmental Quality Incentives Program accelerate mechanized forage harvesting adoption among mid-sized producers. California's Central Valley hosts the densest concentration of large-scale rotary rake deployments for multi-cutting alfalfa schedules.
Germany
EU Farm to Fork Strategy soil health mandates force redesigns of ground-contact components toward lower soil compaction specifications. F-Gas Regulation refrigerant rules constrain hydraulic system specifications for imported implements. Agricultural cooperatives in Bavaria and Lower Saxony now require documented pressure-per-square-inch metrics for equipment procurement.
Brazil
Commercial hay export operations scaling for Middle Eastern dairy markets concentrate demand for high-capacity rotary rakes with gentle crop handling. ANVISA agricultural equipment certification timelines affect import logistics for hydraulic retrofit technologies. São Paulo and Paraná states host the primary export hay processing infrastructure serving Saudi and UAE buyers.
France
EU Machinery Directive safety mandates reshape equipment design requirements for rotary and wheel rake configurations. REACH chemical compliance affects tine coating materials used in heavy crop volume applications. The Île-de-France and Auvergne-Rhône-Alpes regions anchor cooperative purchasing channels demanding sustainability-certified equipment.
Canada
Prairie Provinces hay contractors consolidate fleet purchasing power across multi-state operations spanning Alberta and Saskatchewan. Health Canada PMRA pesticide residue monitoring affects hay export quality specifications that equipment handling must preserve. Ontario's dairy sector drives precision agriculture platform integration with rake telemetry systems.
Hay and Forage Rakes Market Competitive Landscape
Integrated farm management platforms and specialized rotary engineering firms split the market between bundled service ecosystems and premium mechanical differentiation. The vendor base concentrates around three strategic archetypes: diversified agricultural equipment conglomerates with data platform lock-in, specialized hay tool engineering houses commanding cooperative placement, and regional fabricators serving price-sensitive contractor segments. Dominant competitive moves include precision agriculture subscription bundling and hydraulic retrofit technology licensing for legacy fleet upgrades.
Within the diversified equipment tier, John Deere exemplifies platform-integrated positioning, while Kuhn Group occupies the specialized engineering archetype with European cooperative anchoring. AGCO Corporation represents geographic breadth across American and South American dealer footprints. These three names illustrate how competitive positioning stratifies between data ecosystem control, mechanical premiumization, and distribution density.
| Leading Market Players |
|---|
| John Deere |
| Kuhn Group |
| New Holland Agriculture |
| CLAAS Group |
| AGCO Corporation |
| Vermeer Corporation |
| Krone |
| Kubota Corporation |
| Maschio Gaspardo |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese steel tine manufacturing is compressing margin structures for mid-tier hay rake suppliers while simultaneously enabling aggressive pricing postures among European specialized engineering houses. This utilization asymmetry between Asian commodity inputs and Western precision assembly creates divergent pricing power across the value chain.
Pricing Analysis
Geographic price spreads between North American dealer networks and Brazilian import channels exceed 20% for equivalent rotary rake specifications, driven by ANVISA certification overhead and logistics fragmentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by telemetry integration depth and soil compaction certification status. Pricing pressure stems from wheel rake substitution in price-sensitive contractor segments, particularly among fragmented regional hay operations in the American Midwest. Agricultural producers demonstrate the lowest price sensitivity due to lifecycle cost focus, while sporadic-use farmers drive economy-tier volume.
Supply Chain Analysis
Upstream feedstock concentration in Chinese steel billet production and German hydraulic component manufacturing creates dual-source dependency for frame and tine assemblies. Raw material inputs draw from high-grade alloy steel for tine durability, specialized hydraulic seals for remote adjustment systems, and flotation tire compounds for EU soil health compliance. Single-source vulnerability concentrates in precision hydraulic valve production for real-time tine control. Distribution runs through OEM-captive dealer networks in consolidated dairy regions and independent agricultural equipment distributors in fragmented contractor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hay and forage rakes market is approaching a platform-economics inflection where data ecosystem lock-in supersedes mechanical specification as the primary switching cost. Interoperability between farm management platforms and third-party telemetry providers is fragmenting traditional dealer loyalty.
For Market Incumbents: Harden platform stickiness through precision agriculture subscription bundling that captures recurring telemetry revenue from contractor fleet standardization. Deepen backward integration into hydraulic retrofit kit manufacturing to defend margin position against commodity tine suppliers. Prioritize API openness investments to neutralize independent precision agriculture consultants specifying equipment based on data compatibility rather than historical dealer relationships. For New Entrants and Emerging Players: Pursue white-space opportunities in electric-actuated compact rake designs for European vineyard applications with emissions restrictions. Target Brazilian commercial hay export infrastructure as the most penetrable geography, where ANVISA certification timelines have constrained incumbent responsiveness. Anchor go-to-market strategy through hydraulic retrofit technology licensing rather than full equipment manufacturing, reducing capital intensity and accelerating market entry. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision agriculture platform operators with established telemetry subscriber bases across multi-state contractor fleets. Long-term viability over the next decade hinges on carbon accounting framework alignment and documented lifecycle environmental footprinting. Acquisition target archetype: specialized rotary engineering houses with EU cooperative placement and unexploited hydraulic intellectual property. The signal to watch is USDA conservation program funding reauthorization levels, which directly determine mid-sized producer equipment upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Integration | John Deere's farm management ecosystem locks in repeat equipment purchases through telemetry bundling. |
| Hydraulic Retrofit Technology Licensing | Brazilian exporters upgrade existing tractor fleets to meet Middle Eastern dairy contract specifications. |
| EU Soil Compaction Certification Investment | Kuhn Group captures cooperative placement through documented pressure-per-square-inch metrics. |
| Dealer Network Geographic Expansion | AGCO Corporation leverages broad North and South American footprints to serve consolidating contractor fleets. |
| Carbon Accounting Framework Alignment | Equipment lifecycle valuation methodologies will create resale premium differentiation for low-compaction designs. |
Research Methodology
Operator-level perspectives from dairy farm managers, custom hay contractors, agricultural equipment dealers, hydraulic service technicians, and cooperative procurement officers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through USDA program documentation, EPA non-road emissions filings, EU Machinery Directive compliance records, and ANVISA certification databases. Customs trade data for agricultural equipment imports and SEC 10-K disclosures from diversified equipment manufacturers provided volume and value triangulation points. Bottom-up equipment shipment modeling and top-down agricultural machinery spending analysis converged on segment-level estimates.
Scenario-bracketing around USDA conservation funding levels, EU Farm to Fork Strategy implementation pace, and Brazilian export infrastructure buildout shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type configuration, technology tier, end-user scale, and deployment mobility. CAGRs derived from equipment replacement cycle compression in consolidated dairy operations and hydraulic retrofit adoption curves in export hay sectors. Industry-specific forecast inputs encompassed alfalfa cutting schedule intensity and Middle Eastern dairy import demand growth.
Macroeconomic conditions sit as an overlay; deviation in steel commodity pricing, agricultural credit availability, or Middle Eastern currency stability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology adoption elasticity. Cross-checking against agricultural machinery association shipment data and cooperative procurement survey benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Farm Implements Market
Agricultural Equipment
Wheelbarrow Market
Agricultural Equipment
Stock Tanks Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Commercial Grain Mill Market
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Pre-Harvest Equipment Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Planter Market
Agricultural Equipment
Gardening Equipment Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Vegetable Sorting Machines Market