
 Global Feeding Systems Market | 2026-2036
Global Feeding Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feeding Systems Market Analysis
Veterinary nutrition expertise is reorganizing how livestock operations specify feeding equipment, as herdsmen with digital literacy replace traditional farm labor across major dairy regions. Cargill leverages its global grain procurement network to bundle feed supply with system installations. KUHN anchors European demand through its specialization in mixer wagon technology for ration consistency. Fresenius Kabi AG competes in the clinical nutrition segment with enteral feeding devices that meet hospital-grade sterilization protocols.
Feeding systems encompass mechanical and electronic apparatus designed to deliver measured nutrients to animals or patients, incorporating auger mechanisms, pneumatic conveyance, or peristaltic pumps with dosing accuracy typically within two percent of target volume. Their primary purpose spans agricultural productivity optimization and clinical patient sustenance. Automatic feeders command the largest product category share due to labor substitution economics in large-scale dairy, while sensor-based technology is gaining fastest as IoT-enabled intake monitoring reduces feed waste. Livestock farming dominates application demand, though aquaculture represents a concentrated margin pool where species-specific feeding algorithms justify premium pricing.
The FDA regulates enteral feeding devices under Class II medical device standards, while the EU Green Deal's Farm to Fork Strategy imposes methane reduction targets that directly incentivize precision rationing equipment. EPA nutrient management rules in the United States restrict runoff from concentrated animal operations, forcing feed optimization as a compliance pathway. Stakeholders must weigh capital deployment between clinical nutrition standardization and agricultural automation as regulatory pressure diverges across end-use segments.
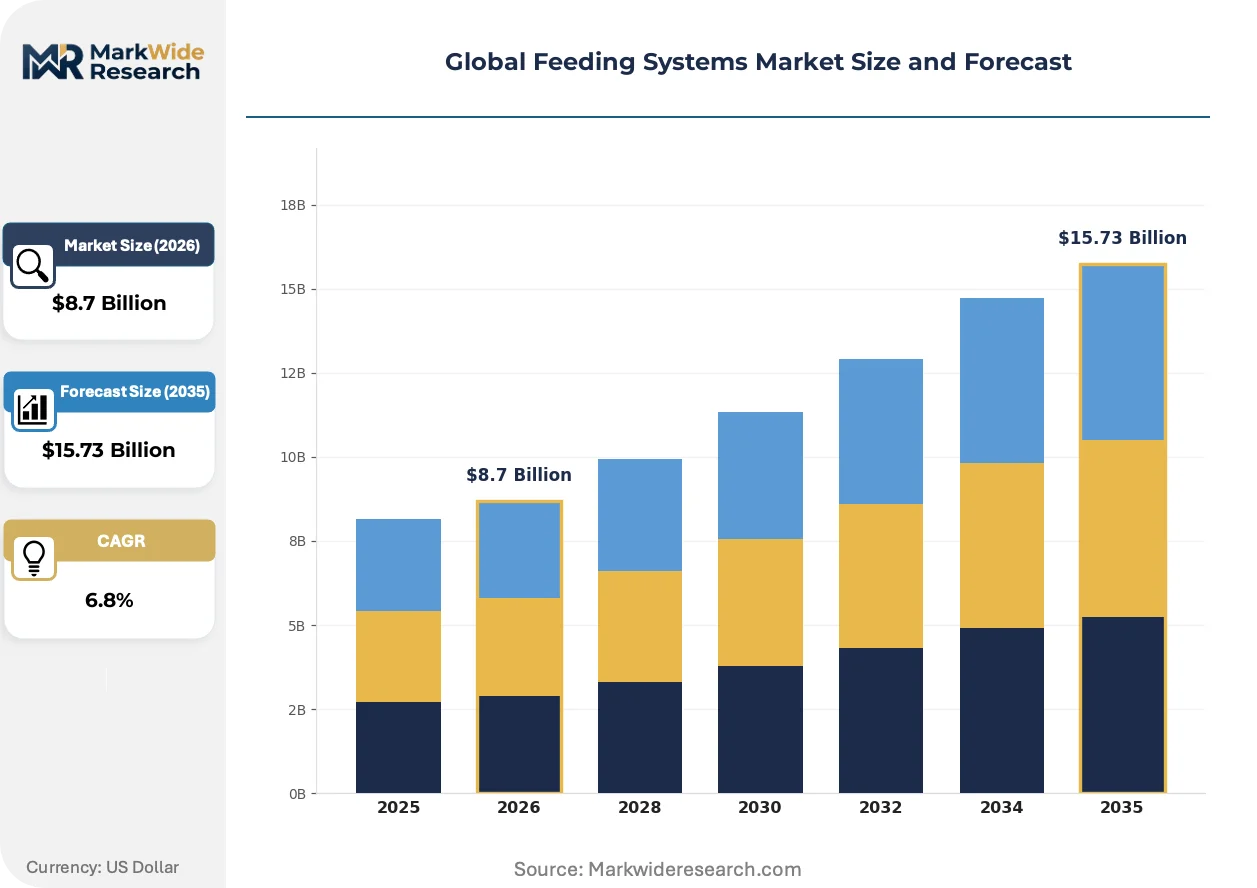
Market Dynamics
Precision rationing technology is reorganizing capital deployment across livestock operations as labor substitution economics collide with methane compliance mandates from Brussels and Washington.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Methane reduction targets force feed optimization investments across Dutch and German dairy clusters. Precision dosing equipment qualifies for green transition financing.
- Sensor fusion architectures:IoT-enabled intake monitoring combined with automated auger systems cuts waste below two percent variance. Large-scale operations in California and Wisconsin deploy these bundles fastest.
- Aquaculture margin pools:Species-specific feeding algorithms for salmon and shrimp operations command premium pricing. Norwegian and Chilean producers replace manual broadcast feeding with programmable systems.
Market Restraints
- Stainless steel input volatility:Auger and mixer wagon fabrication depends on nickel and chromium prices. Foundry concentration in China creates exposure to export quota fluctuations.
- Technical integration gaps:Legacy barn infrastructure lacks ethernet backbone and power conditioning for automated feeders. Retrofit costs often exceed greenfield installation premiums.
- Substitution by contract services:Third-party feed management companies in the Netherlands lease complete rationing systems, converting capex to opex and compressing equipment ownership rates.
Strategic Opportunities
- Brazilian pasture-based beef:Automated mineral and protein supplement dispensers remain underdeployed across Mato Grosso and Goiás. Local assembly partnerships bypass import duty structures.
- Clinical nutrition convergence:Enteral feeding device sterilization protocols from hospital settings transfer to high-value breeding stock operations. Japanese Wagyu producers adopt medical-grade tubing standards.
- US IRA agricultural provisions:Conservation and climate-smart practice incentives cover precision feeding infrastructure. Dairy cooperatives in Wisconsin structure equipment loans against guaranteed credit enhancements.
Industry Challenges
- Mechatronics talent scarcity:Servo calibration and pneumatic troubleshooting skills concentrate among German and Italian equipment specialists. North American dealer networks struggle to field certified technicians.
- FDA Class II device timelines:Enteral feeding pump sterilization validation requires eighteen-to-twenty-four month premarket notification cycles. Agricultural entrants underestimate clinical compliance duration.
- Legacy control system fragmentation:Proprietary communication protocols from DeLaval, Lely, and GEA block seamless third-party feeder integration. Middleware development consumes engineering resources without differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feeding Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Feeders, Gravity Feeders, Manual Feeders, Electronic Feeders Application: Agricultural Use, Aquaculture, Livestock Farming, Pet Care Technology: Smart Feeding, Sensor-Based, RFID Technology, Mechanical Systems End User: Farmers, Pet Owners, Aquaculturists, Livestock Breeders |
| Companies Covered | Cargill, Archer Daniels Midland Company, Boston Scientific Corporation, Cardinal Health, B Braun Melsungen AG, KUHN, Land O'Lakes, Fresenius Kabi AG, Applied Medical Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feeding Systems Market Emerging Trajectories
Feeding system architecture is splitting between precision livestock farming stacks and clinical nutrition platforms as data sovereignty and sterilization protocols diverge.
Computer vision-based intake monitoring is bifurcating equipment categories. Camera arrays mounted above feed bunks track individual animal consumption patterns. North American dairy operations with five-hundred-plus head deploy these systems within twelve-month cycles. The technology is bifurcating the market between sensor-integrated premium feeders and basic timer-based units.
REACH chemical restrictions and EU Green Deal methane benchmarks are tightening material specifications. Stainless steel grade requirements for feed-contact surfaces now exclude certain nickel alloys. Mixer wagon manufacturers in Germany and Italy reformulate auger coatings to maintain wear resistance under new substance limitations. Dutch equipment certification bodies are processing updated technical files under compressed deadlines.
Service unbundling is fragmenting traditional sales models. Equipment vendors separate hardware, software licensing, and nutrition consulting into distinct contract streams. Large dairy cooperatives in Denmark and the Netherlands negotiate software subscriptions independent of capital purchases. This restructuring is most advanced where herd management platforms from multiple suppliers compete for data integration rights.
Global Feeding Systems Market Segmentation
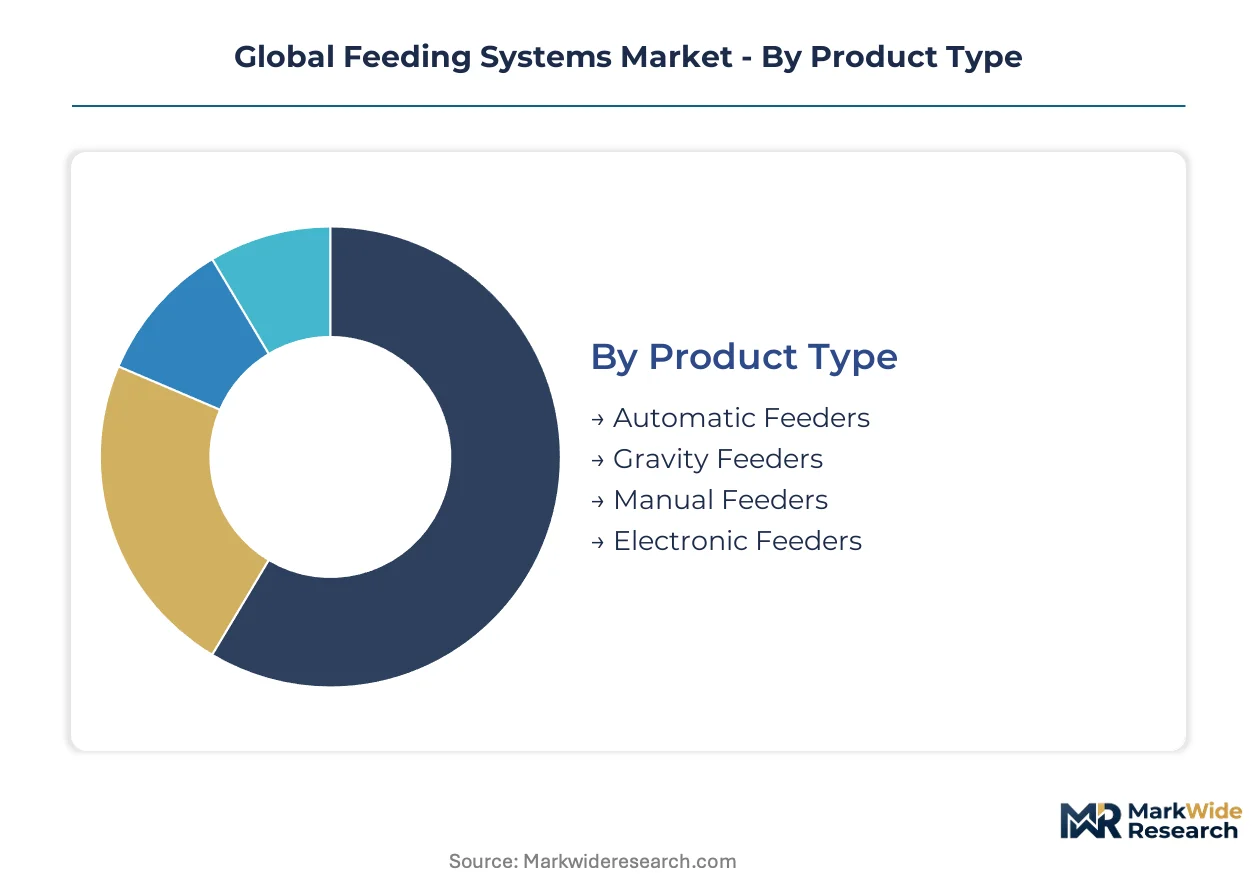
Segmentation in feeding systems reveals how capital allocation splits between labor substitution imperatives and precision monitoring premiums. Equipment buyers prioritize either upfront cost containment or long-term feed conversion efficiency, creating distinct procurement channels across dairy, aquaculture, and clinical end-uses.
Product Type:
Substitution pressure from third-party feed management services hits capital equipment segments hardest, particularly where lease-to-own models convert hardware purchases into operating expenditures.
- Automatic Feeders:Auger-driven and pneumatic dispensers with programmable portion control dominate large-scale dairy installations. Demand concentrates in California's Central Valley and Wisconsin's Fox River watershed, where five-hundred-head operations deploy these systems within compressed replacement cycles driven by EPA nutrient management compliance.
- Sensor-Based Technology:IoT-enabled intake monitoring with load cells and computer vision tracks individual animal consumption patterns. Norwegian salmon producers and Dutch veal operations adopt these fastest, justifying premium pricing through sub-two-percent feed waste reduction.
- Gravity Feeders:Passive hopper designs with flow-rate restrictors serve pasture-based beef and smallholder poultry. Brazilian Mato Grosso ranchers favor these for mineral supplementation where electrical infrastructure remains sparse.
- Manual Feeders:Basic trough and bucket systems persist in emerging market smallholdings and hobby farming segments. Price sensitivity and low utilization rates limit technology upgrade incentives.
Automatic feeders anchor the volume base while sensor-based technology gains share at the steepest rate.
Application:
Margin structure varies dramatically across end-uses, with aquaculture commanding premium pricing for species-specific algorithms while livestock farming drives aggregate unit demand.
- Livestock Farming:Dairy and beef operations deploy precision rationing equipment to meet methane reduction mandates from Brussels and Washington. Dutch and German dairy clusters lead replacement cycles, bundling feed optimization with green transition financing.
- Aquaculture:Programmable systems for salmon and shrimp operations incorporate water-quality sensors and growth-model feeding curves. Chilean and Norwegian producers replace manual broadcast feeding fastest, capturing concentrated margin pools through reduced feed conversion ratios.
- Agricultural Use:Broad-acre grain and forage handling equipment serves mixed farming operations. Demand tracks commodity price cycles and harvest timing rather than continuous monitoring imperatives.
- Pet Care:Programmable dispensers and microchip-activated bowls target urban households with irregular schedules. Unit economics favor outsourced manufacturing with brand differentiation through mobile app integration.
Livestock farming generates the highest absolute equipment demand while aquaculture delivers the steepest margin expansion trajectory.
Technology:
Technology maturity splits the market between proven mechanical reliability and emerging digital integration, with retrofit compatibility determining adoption speed in installed-base segments.
- Smart Feeding:Cloud-connected platforms integrating herd management software with automated dispensers. Danish and Dutch dairy cooperatives negotiate software subscriptions independent of hardware purchases, fragmenting traditional bundled sales models.
- Sensor-Based:Camera arrays and weight platforms track consumption without individual animal identification. North American large-scale operations deploy these within twelve-month cycles, bifurcating the market from timer-based units.
- RFID Technology:Ear-tag or collar-based individual animal recognition enables customized ration delivery. High-value breeding stock operations in Japan and Germany adopt these for genetic optimization programs.
- Mechanical Systems:Timer-actuated and volumetric dispensers without data connectivity. Foundry concentration in China for auger and mixer wagon fabrication creates nickel and chromium price exposure.
Mechanical systems retain the largest installed base while smart feeding platforms climb the fastest in new installations.
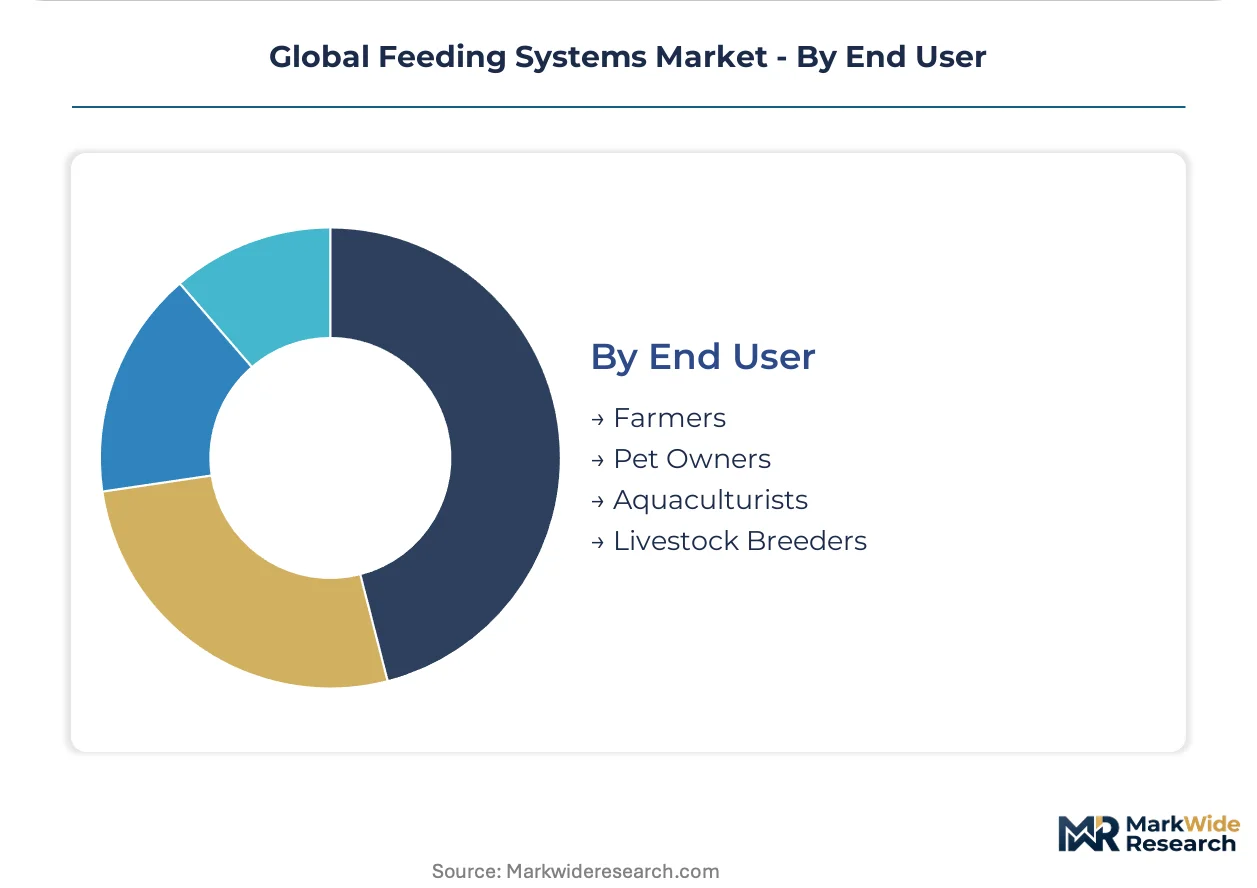
End User:
Procurement sophistication diverges sharply between institutional buyers with technical staff and individual operators prioritizing plug-and-play simplicity.
- Farmers:Dairy and crop-livestock integrated operations with capital access and compliance obligations. Wisconsin and California cooperatives structure equipment loans against IRA conservation credit enhancements.
- Livestock Breeders:Genetic improvement-focused operations with veterinary nutrition expertise. Wagyu producers in Japan adopt medical-grade sterilization protocols from enteral feeding device standards.
- Aquaculturists:Salmon, shrimp, and shellfish producers with species-specific growth modeling requirements. Norwegian producers lead programmable system deployment through marine research institute partnerships.
- Pet Owners:Urban consumers with discretionary spending and convenience priorities. Distribution runs through veterinary clinics and direct-to-consumer channels rather than agricultural dealers.
Farmers represent the largest addressable population while livestock breeders generate the highest per-capita equipment expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA nutrient management rules in the United States anchor the dominant geography, forcing feed optimization investments across concentrated dairy operations while Brussels methane mandates reshape European procurement patterns.
United States
California's Central Valley and Wisconsin's Fox River watershed drive automatic feeder deployment through five-hundred-head operation replacement cycles. EPA nutrient management restrictions on concentrated animal feeding operations mandate feed optimization as runoff compliance pathways. Wisconsin dairy cooperatives structure equipment loans against IRA conservation credit enhancements.
Germany
Dutch and German dairy clusters lead precision rationing equipment replacement cycles driven by methane reduction targets. EU Green Deal Farm to Fork Strategy mandates qualify precision dosing equipment for green transition financing. Mixer wagon manufacturers in Bavaria and North Rhine-Westphalia reformulate auger coatings under REACH chemical restrictions.
Netherlands
Dense livestock operations in Gelderland and Overijssel compress replacement cycles for automated systems. Third-party feed management companies convert capital equipment purchases to operating leases. Dutch equipment certification bodies process updated technical files under compressed EU Green Deal deadlines.
Norway
Salmon producers in Trøndelag and Vestland counties replace manual broadcast feeding with programmable systems fastest. Marine research institute partnerships drive species-specific growth-model feeding curves. Norwegian producers capture concentrated margin pools through reduced feed conversion ratios in fjord-based aquaculture.
Brazil
Mato Grosso and Goiás pasture-based beef operations underdeploy automated mineral and protein supplement dispensers. Local assembly partnerships bypass import duty structures for auger-driven systems. Brazilian ranchers favor gravity feeders where electrical infrastructure remains sparse across the Cerrado biome.
Global Feeding Systems Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with agricultural conglomerates leveraging grain procurement networks against equipment fabricators focused on mixer wagon technology and clinical nutrition platforms. The structure splits between feed supply bundlers and precision hardware specialists. Strategic archetypes include integrated nutrition-to-equipment bundlers, precision dosing technology specialists, and clinical-grade sterilization protocol providers. Dominant competitive moves encompass M&A to secure IoT platform capabilities and geographic expansion through local assembly partnerships in duty-protected markets.
Among the integrated nutrition conglomerates, Cargill leverages its global grain procurement network to anchor bundled feed supply and system installation offerings. KUHN occupies a position exemplifying European precision equipment specialization through its mixer wagon technology focus. Fresenius Kabi AG represents the clinical nutrition archetype with enteral feeding devices meeting hospital-grade sterilization protocols. These three anchors illustrate how competitive positioning splits between agricultural automation and medical device compliance vectors.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Boston Scientific Corporation |
| Cardinal Health |
| B Braun Melsungen AG |
| KUHN |
| Land O'Lakes |
| Fresenius Kabi AG |
| Applied Medical Technology |
| Others |
Supply Flow & Price Mechanics
Long-term equipment lease contracts with embedded service obligations lock in supply access for Dutch dairy cooperatives while capping price volatility exposure across stainless steel input cycles. These structures bundle hardware, software licensing, and nutrition consulting into unified payment streams that transfer foundry cost risk to equipment vendors.
Pricing Analysis
Equipment pricing spreads widest between German precision manufacturers and Chinese foundry-direct suppliers, with auger-driven systems from Bavaria commanding premiums against Mato Grosso-assembled units. Three-tier pricing structure across premium sensor-integrated, standard automatic, and economy gravity-fed levels tracks certification grade and after-sales bundling intensity. Cost compression in mid-tier automatic feeders is intensifying because third-party feed management companies convert ownership to operating leases. Smallholder poultry operators in emerging markets exhibit highest price sensitivity, while Norwegian salmon producers accept premium positioning for species-specific algorithm packages.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for stainless steel auger components sourced from Chinese foundries. Fabrication capacity concentrates in Germany, Italy, and China, with nickel and chromium alloy supply resting on export quota administration by Chinese authorities. Supply chain risk centers on single-source vulnerability for medical-grade tubing specified in Japanese Wagyu breeding operations. Distribution runs through agricultural equipment dealer networks in North America and cooperative procurement consortia in Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feeding system incumbents face substitution pressure from third-party feed management services that convert capital equipment purchases into operating expenditures, eroding ownership-based revenue pools.
For Market Incumbents: Consolidate IoT platform capabilities through targeted engineering acquisitions that close middleware gaps against DeLaval and Lely proprietary protocols. Deepen captive supply of stainless steel components through backward integration into German and Italian foundry partnerships, insulating margin structures from nickel price volatility. These moves defend against lease-to-own substitution models proliferating across Dutch dairy clusters.
For New Entrants and Emerging Players: Lead with automated mineral supplement dispensers for Brazilian pasture-based beef operations in Mato Grosso and Goiás, where electrical infrastructure gaps have delayed precision equipment penetration. Target local assembly partnerships that bypass import duty structures while leveraging gravity-feed engineering simplicity. Position through veterinary nutrition expertise rather than mechanical reliability claims to differentiate from established auger manufacturers.
For Investors and Strategic Acquirers: Sensor fusion technology specialists with marine research institute partnerships represent the most defensible acquisition profile within aquaculture feeding algorithms. Long-term viability hinges on clinical nutrition convergence potential, where enteral device sterilization protocols transfer to high-value breeding stock applications. Watch FDA Class II premarket notification timelines as inflection indicator for agricultural entrants underestimating clinical compliance duration.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Acquisition | Closes middleware gaps against DeLaval and Lely proprietary control systems. |
| Local Assembly Partnership | Bypasses Brazilian import duties while adapting gravity-feed designs to Cerrado infrastructure. |
| Clinical Certification Investment | Transfers FDA Class II sterilization protocols to Wagyu breeding stock operations. |
| Marine Research Institute Alliance | Secures species-specific growth-model feeding curves for Norwegian salmon producers. |
| Software Subscription Unbundling | Fragments traditional bundled sales models across Danish cooperative procurement channels. |
Methodological Framework
A standing panel of dairy herd managers, aquaculture operations directors, veterinary nutritionists, and agricultural equipment dealers provided ongoing calibration against secondary validation from SEC filings, EU Green Deal technical documentation, FDA 510(k) databases, and customs trade records. This study combines primary interviews with these stakeholders and bottom-up installation tracking with top-down macroeconomic triangulation across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks from equipment certification bodies and cooperative procurement disclosures. The analytical framework models product type, application, technology tier, and end-user sophistication across the projection horizon, with CAGRs derived from replacement cycle timing and regulatory compliance deadlines. Forecast inputs incorporate EPA nutrient management rule enforcement patterns and EU methane reduction target trajectories.
The analysis sits within stated boundaries; outcomes outside sustained green transition financing availability or abrupt stainless steel export quota shifts would require recalibration. Forecasts reflect documented assumptions regarding dairy labor substitution economics and aquaculture feed conversion ratio improvements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Fly Trap Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Crop Spraying Drone Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Soil Testing Equipment Market
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Plucker Machine Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Fishing Net Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Plows Market