
 Animal Feed Ingredients Market | 2026-2036
Animal Feed Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed Ingredients Market Analysis
The gap between traceable premium ingredient tiers and undifferentiated commodity bulk is restructuring procurement patterns across livestock supply chains. Cargill leverages its origination networks to anchor grain-forward formulations in North American ruminant operations. BASF SE competes through synthetic amino acid specialization, while Evonik Industries dominates methionine technology leadership.
Animal feed ingredients comprise the constituent materials blended to deliver specified crude protein, energy density, amino acid profiles, and micronutrient levels for targeted livestock performance. These inputs undergo grinding, pelleting, extrusion, or liquid application to achieve homogenous nutrient distribution and feed conversion efficiency. Oilseed meals command durable volume leadership due to their protein density and cost-positioning in swine and poultry rations. Nutritional additives represent the fastest-expanding margin pool as producers seek antibiotic alternatives and precision-formulation tools. Cereal grains occupy mature, price-sensitive demand anchored in ruminant bulk feeding systems.
The FDA governs veterinary feed directive compliance and residue thresholds in the United States, while the EU Green Deal and F-Gas Regulation constrain deforestation-linked soy imports and greenhouse-intensive processing methods. REACH chemical registration requirements in Europe further filter novel additive market entry. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and sourcing requalification timelines.
Market Dynamics
The EU Green Deal's deforestation-free supply chain mandates are compressing procurement timelines for soy and palm derivatives, forcing feed compounders to requalify entire ingredient portfolios under stricter traceability protocols.
Growth Catalysts
- Antibiotic-free mandates:Veterinary feed directive compliance in the United States accelerates demand for phytogenic additives and organic acid blends as growth promoters exit rations.
- Precision fermentation:Novel protein manufacturing methods reduce land-use intensity for high-value amino acid production, attracting capital from sustainability-linked funds.
- Brazil's integrated poultry sector:Vertically coordinated production systems generate captive demand for customized premix formulations with embedded nutritional analytics.
Market Restraints
- Input cost volatility:Maize and soybean meal prices swing with Black Sea export disruptions, compressing blender margins on fixed-price contracts.
- Supply concentration risk:Synthetic lysine and methionine production clusters in China and Southeast Asia expose buyers to freight rate spikes and customs delays.
- Regulatory friction:REACH chemical registration in Europe extends novel additive commercialization timelines by 18-24 months versus other jurisdictions.
Strategic Opportunities
- Underpenetrated aquaculture nutrition:Vietnam and Indonesia shrimp operations lack species-specific micronutrient protocols, creating openings for precision-formulation services.
- Carbon accounting integration:EU CSRD disclosure requirements position low-carbon ingredient certifiers to capture premium pricing from Scope 3-conscious protein brands.
- Enzyme-microbiome convergence:Combining exogenous carbohydrases with targeted probiotic strains enables feed conversion improvements in ruminant methane reduction programs.
Industry Challenges
- Formulation talent scarcity:Nutritional modeling for multi-species operations requires cross-disciplinary expertise in metabolomics and computational biology that outpaces university pipeline output.
- Legacy system integration:Real-time near-infrared analytics deployment confronts siloed ERP architectures at mid-sized compounders, delaying precision-feeding ROI realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed Ingredients Market |
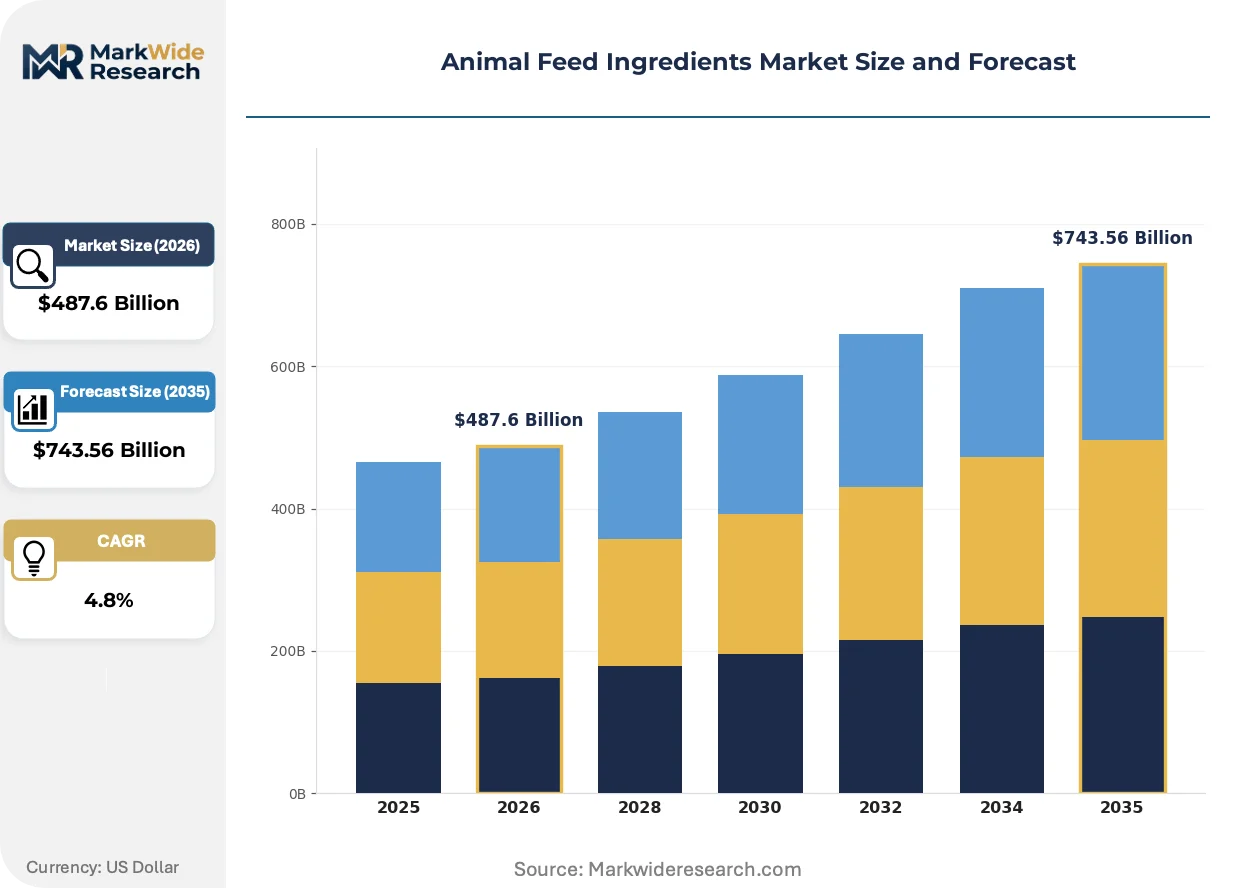
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $743.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Cereal Grains, Oilseed Meals, By-Products, Nutritional Additives Animal Type: Poultry, Swine, Ruminants, Aquaculture Form: Pellets, Crumbles, Mash, Liquid Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | BASF SE, Koninklijke DSM N.V., Cargill, Kemin Industries, Nutreco N.V., Archer Daniels Midland Company, Evonik Industries, Phibro Animal Health Corporation, Land O'Lakes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed Ingredients Market Emerging Trajectories
Digital traceability infrastructure and alternative protein manufacturing methods are compressing traditional commodity sourcing cycles while opening margin pools in verified-sustainable ingredient tiers.
Single-cell protein derived from methanotrophic bacteria is overtaking fishmeal in salmonid diets as Norwegian and Chilean aquaculture operations seek to sever ties with volatile marine ingredient markets. Atlantic salmon producers report feed conversion ratios matching conventional formulations within 18 months of adoption. This protein source is overtaking legacy marine inputs in premium segment positioning.
REACH chemical registration requirements in Europe filter novel additive market entry by mandating full toxicological dossiers for substances above one-tonne annual volume thresholds. Feed enzyme manufacturers face reformulation costs exceeding €2 million per active compound to achieve authorization. The restriction most impacts probiotic live culture suppliers targeting swine gut health applications.
Integrated poultry and pork processors in Brazil and Thailand now contract directly with premix laboratories, bypassing traditional distribution intermediaries. These buyers demand embedded nutritional diagnostics and real-time formulation adjustments based on slaughter yield data. The disintermediation pattern concentrates in Southeast Asia where processor consolidation outpaces compounder technical service expansion.
Animal Feed Ingredients Market Segmentation
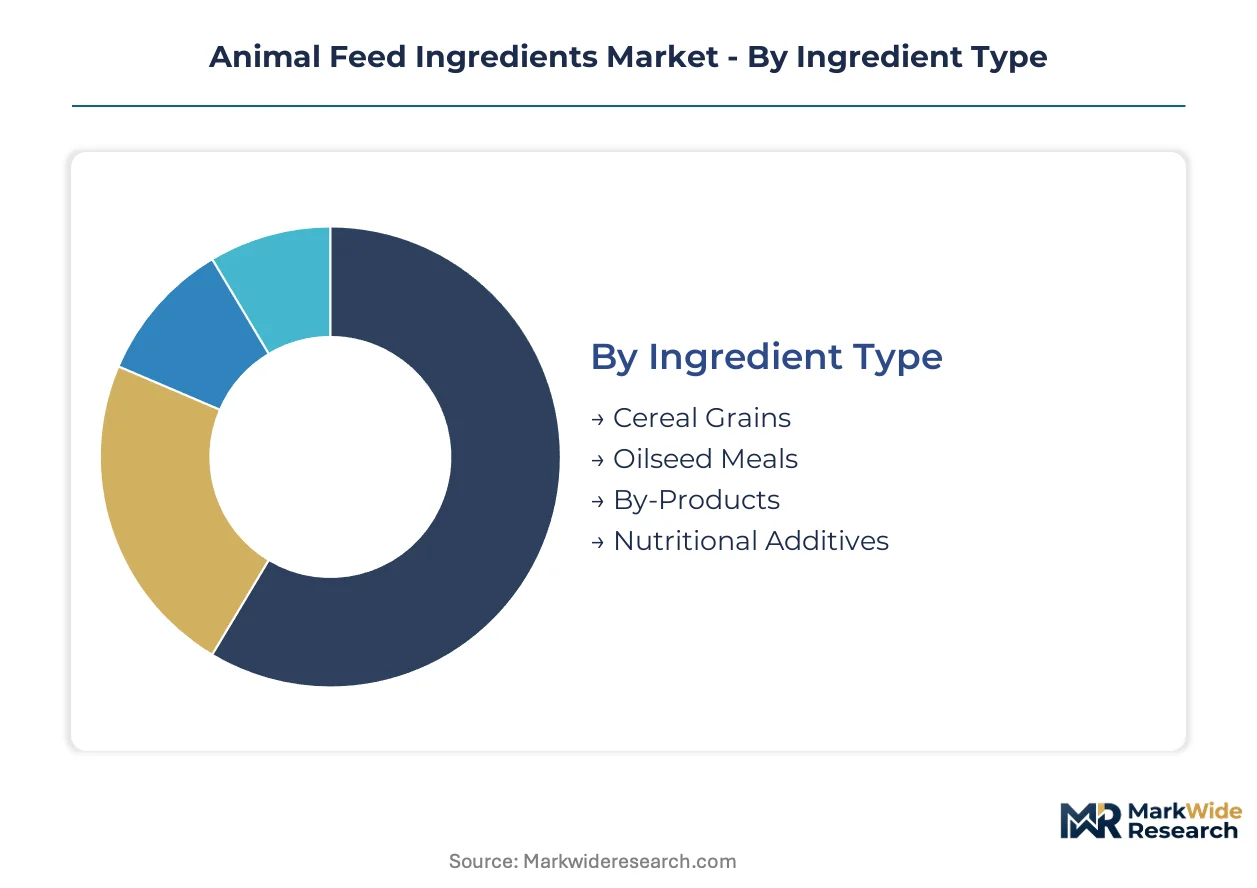
Ingredient categorization determines regulatory pathways and procurement economics across livestock supply chains. Feed compounders structure sourcing strategies around compositional specifications that trigger distinct approval requirements from FDA, EFSA, and national veterinary authorities.
Ingredient Type:
Certification burdens vary sharply across this dimension: cereal grains face minimal novel substance registration, while nutritional additives trigger REACH dossiers in Europe and FDA food additive petitions in the United States.
- Cereal Grains:Maize, wheat, and sorghum deliver metabolizable energy through starch-dense kernels with standardized moisture and protein specifications. Demand concentrates in Iowa and Illinois cattle feedlots where bulk handling infrastructure minimizes per-ton logistics costs against volatile commodity futures.
- Nutritional Additives:Enzymes, probiotics, and organic acid blends require precision dosing to modify gut microbiome function or nutrient bioavailability. Southeast Asian shrimp farms drive specialized amino acid premix demand as producers phase out antibiotic growth promoters under export market pressure.
- Oilseed Meals:Soybean and rapeseed press cakes provide standardized crude protein fractions for monogastric rations.
- By-Products:Distillers grains and wheat middlings repurpose food processing residues into ruminant energy supplements.
Cereal grains sit at the top of the volume ranking, with nutritional additives climbing the fastest.
Animal Type:
Species-specific digestive physiology dictates formulation complexity and margin capture potential across customer segments.
- Poultry:Broiler and layer operations demand finely balanced amino acid profiles to optimize feed conversion ratios in high-turnover production cycles. Brazil's integrated processors generate captive premix demand with embedded real-time formulation adjustments tied to slaughter yield analytics.
- Aquaculture:Salmonid and shrimp species require species-specific micronutrient protocols absent from legacy terrestrial livestock formulations. Norwegian producers are displacing fishmeal with single-cell protein from methanotrophic bacteria to sever ties with volatile marine ingredient markets.
- Swine:Growing-finishing phases drive lysine and methionine consumption in intensive production systems.
- Ruminants:Forage-based systems utilize energy-dense grains and protein supplements to balance rumen microbial efficiency.
Poultry sits at the top of the volume ranking, with aquaculture gaining share fastest.
Form:
Physical processing determines storage stability, transport economics, and on-farm handling requirements across distribution networks.
- Pellets:Steam-conditioned and extruded cylinders minimize feed wastage and improve nutrient density for automated delivery systems. Vietnamese aquaculture operations favor sinking pellets for shrimp pond applications where water stability prevents nutrient leaching.
- Mash:Ground and blended meals offer cost-positioning for backyard and smallholder operations with limited mechanical handling capacity. India's fragmented dairy sector sustains regional mash compounders despite pelleting technology diffusion.
- Crumbles:Broken pellet fragments suit starter diets for young animals with limited intake capacity.
- Liquid:Molasses-based supplements and fat emulsions integrate into total mixed ration systems for high-performance dairy herds.
Pellets sit at the top of the volume ranking, with liquid formulations expanding most quickly in precision-delivery applications.
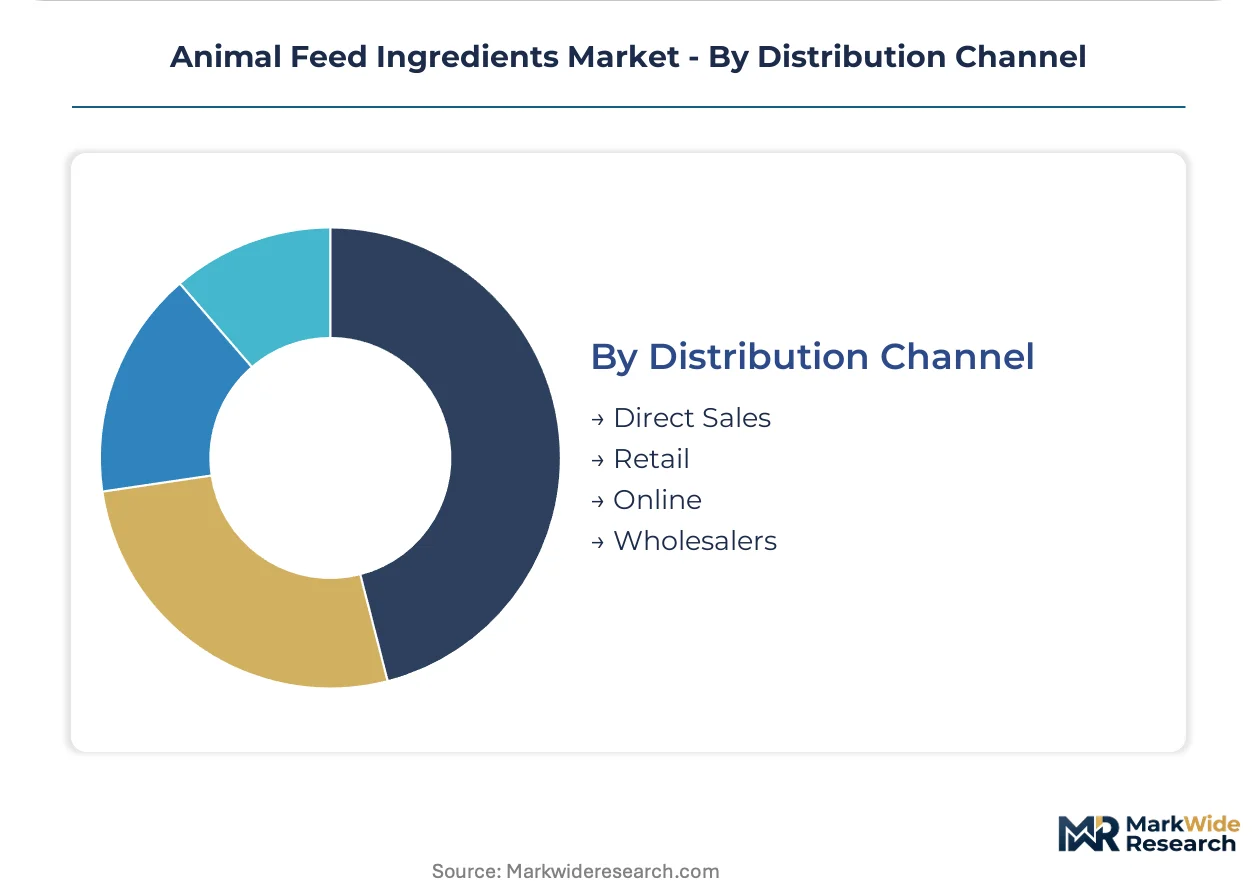
Distribution Channel:
Channel structure reflects customer scale, technical service requirements, and price sensitivity segmentation across the demand base.
- Direct Sales:Premix laboratories contract directly with integrated processors, embedding nutritional diagnostics and slaughter yield feedback loops. Thailand's consolidated pork sector bypasses traditional distribution intermediaries for customized formulation services.
- Wholesalers:Regional distributors aggregate commodity volumes for mid-sized independent farms lacking procurement scale. Black Sea export disruptions have compressed blender margins on fixed-price contracts through input cost volatility.
- Retail:Farm supply stores serve hobby and small-scale producers with bagged finished feeds.
- Online:Digital platforms emerge for specialty additive procurement by niche organic and antibiotic-free operations.
Direct sales sit at the top of the volume ranking, with online channels climbing the fastest in specialty additive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nutritional modeling talent clusters in the Netherlands and Germany, while feed enzyme R&D concentrates in Danish and Swiss research parks. Regulatory divergence between FDA and EFSA pathways shapes regional competitive positioning.
United States
Iowa and Illinois cattle feedlots drive bulk grain procurement at scale. FDA veterinary feed directive compliance accelerates phytogenic additive demand as antibiotic growth promoters exit rations. Cargill leverages its Minneapolis-based origination networks to anchor grain-forward formulations across North American ruminant operations.
Brazil
Vertically integrated poultry processors in São Paulo and Paraná generate captive premix demand with embedded nutritional analytics. ANVISA regulates residue thresholds while the national agricultural research corporation Embrapa advances precision fermentation protocols. The southern states concentrate customized formulation laboratories serving consolidated pork and broiler operations.
China
Synthetic lysine and methionine production clusters in coastal provinces expose buyers to freight volatility and customs delays. SAMR and MEE enforce dual carbon goals that constrain greenhouse-intensive processing methods. Shandong Peninsula houses the dominant amino acid manufacturing capacity serving domestic swine and poultry sectors.
Germany
REACH chemical registration extends novel additive commercialization timelines by 18-24 months versus other jurisdictions. ECHA dossier requirements filter probiotic live culture suppliers targeting swine gut health applications. Bavaria and North Rhine-Westphalia concentrate feed enzyme R&D facilities alongside precision fermentation pilot plants.
Vietnam
Shrimp operations in the Mekong Delta lack species-specific micronutrient protocols, creating openings for precision-formulation services. Export market pressure from EU and US buyers phases out antibiotic growth promoters in aquaculture. Ho Chi Minh City anchors specialized amino acid premix distribution for underpenetrated aquaculture nutrition segments.
Animal Feed Ingredients Market Vendor Landscape
Top-tier vendors anchor integrated supply chains, while mid-tier specialists compete on formulation customization. The vendor base stratifies across grain origination networks, synthetic amino acid technology, and precision additive manufacturing. Three archetypes dominate: agricultural conglomerates with captive origination, chemical specialists with fermentation expertise, and nutrition-focused innovators with microbiome capabilities. M&A activity concentrates on enzyme technology acquisitions, while capacity expansion targets Southeast Asian aquaculture feed mills.
Within the chemical specialist tier, BASF SE and Evonik Industries exemplify synthetic amino acid technology leadership. Among diversified agricultural conglomerates, Cargill occupies a position anchored in grain-forward formulation scale. These three entities represent distinct competitive vectors: fermentation-based amino acid dominance, origination-integrated supply chain control, and precision additive manufacturing specialization.
| Leading Market Players |
|---|
| BASF SE |
| Koninklijke DSM N.V. |
| Cargill |
| Kemin Industries |
| Nutreco N.V. |
| Archer Daniels Midland Company |
| Evonik Industries |
| Phibro Animal Health Corporation |
| Land O'Lakes |
| Others |
Supply Flow & Price Mechanics
Precision fermentation methods for amino acid manufacturing are compressing production costs while redrawing competitive boundaries between synthetic and natural-origin suppliers. This technological shift simultaneously erodes legacy margin structures and concentrates supply leverage among fermentation-capable chemical specialists.
Pricing Analysis
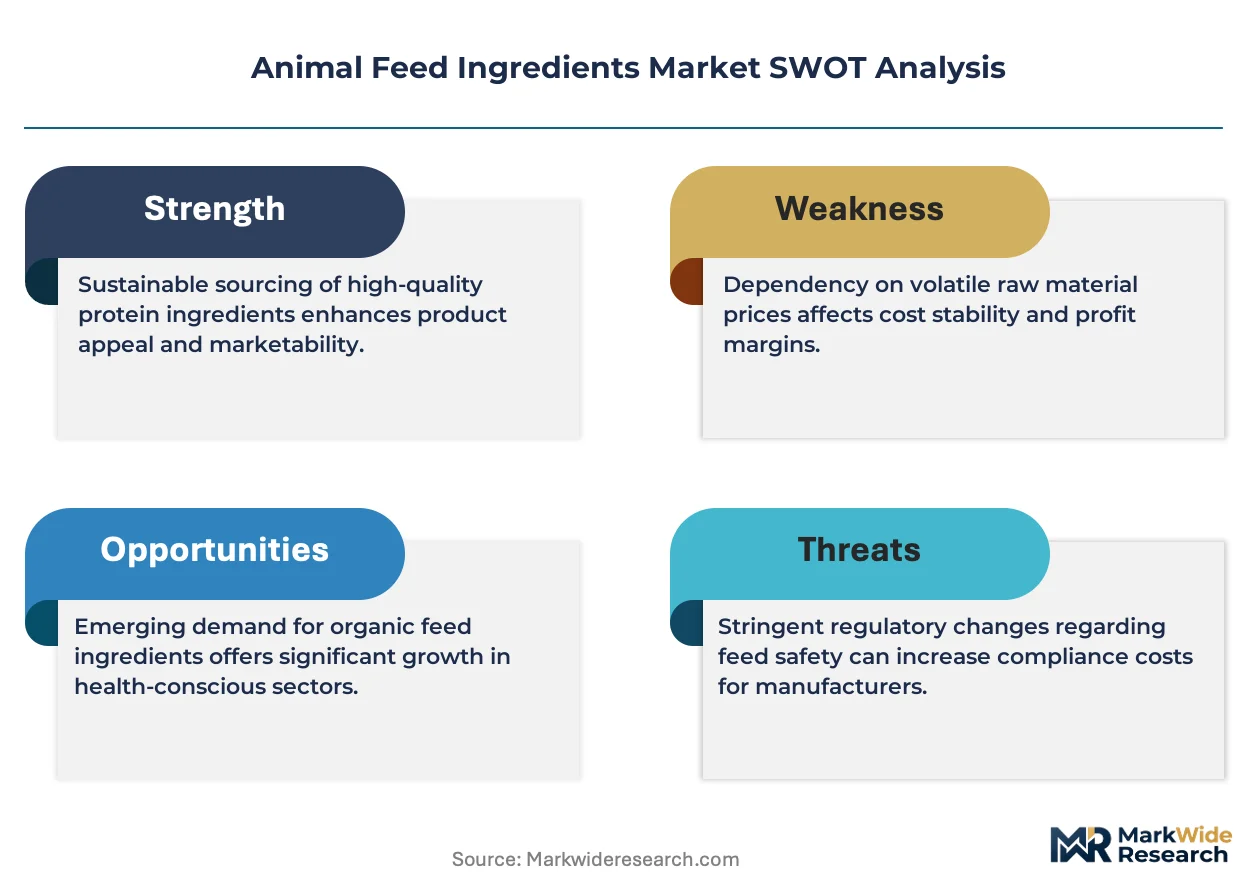
Bundled formulation services command premiums over unbundled commodity ingredient sales across Brazilian and Thai integrated processor contracts. Three-tier pricing structure across premium, standard, and economy levels separates traceable certified ingredients from undifferentiated bulk, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from Black Sea export disruptions inflating maize and soybean meal input costs. Mid-sized independent farms exhibit highest price sensitivity, while vertically coordinated processors absorb premiums for embedded nutritional analytics.
Supply Chain Analysis
Freight rate volatility from synthetic lysine and methionine production clusters in China and coastal Southeast Asia exposes buyers to margin compression. Supply concentration in Shandong Peninsula amino acid facilities, Iowa-Illinois grain origination zones, and Dutch-Belgian enzyme R&D parks creates geographic dependencies. Raw material flows hinge on Brazilian soy crush capacity, Ukrainian maize export corridors, and Norwegian marine ingredient alternatives. Single-source vulnerability in methionine technology licenses dominates risk profiles. Distribution runs through direct premix laboratory contracts with integrated processors, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal feed ingredients function as a stable compounder, with protein demand from expanding aquaculture and poultry sectors providing durable volume foundations.
For Market Incumbents: Extend traceability certification investments to defend premium tier positioning against commodity price erosion. Secure backward integration into precision fermentation capacity for high-value amino acids. Deepen technical service capabilities in Vietnam and Indonesia shrimp nutrition to counter emerging regional formulation specialists. For New Entrants and Emerging Players: Capture underpenetrated aquaculture micronutrient protocols in Mekong Delta operations where species-specific expertise remains scarce. Target carbon accounting certification services for EU CSRD-compliant protein brands seeking Scope 3 reduction. Deploy precision-formulation-as-a-service models to bypass capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional premix laboratories because processor consolidation in Brazil and Thailand generates captive demand for customized technical services. The five-to-ten year horizon favors fermentation technology platforms over grain-trading assets. Acquisition targets should demonstrate embedded nutritional analytics capabilities. Watch EU deforestation-free mandate enforcement timelines as inflection indicator for sourcing requalification spending cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Fermentation | Captures margin pool from synthetic amino acid manufacturing controlled by BASF SE and Evonik Industries. |
| Carbon Certification Program Launch | Positions ingredient suppliers for EU CSRD premium pricing from Scope 3-conscious protein brands. |
| Aquaculture Nutrition Laboratory Expansion | Addresses species-specific micronutrient gaps in Vietnamese and Indonesian shrimp operations. |
| Direct Processor Contracting | Bypasses wholesale intermediaries to embed real-time formulation adjustments tied to slaughter yield data. |
| Enzyme-Microbiome Joint Development | Combines exogenous carbohydrases with probiotics for ruminant methane reduction program participation. |
Methodological Framework
Direct dialogue with feed compounder procurement directors, premix laboratory technical directors, integrated processor nutritionists, and regulatory affairs specialists grounded qualitative findings. Secondary validation drew from FDA veterinary feed directive filings, EFSA novel food assessments, EU Green Deal implementation texts, and Brazilian ANVISA residue threshold updates. Bottom-up volume estimates from ingredient-type and animal-type segments triangulated against top-down macroeconomic projections.
Segment-level CAGRs emerged from modeled interactions between aquaculture expansion rates, antibiotic-free mandate adoption curves, and precision fermentation capacity buildouts across the projection horizon. The analytical framework incorporated ingredient type, animal type, physical form, and distribution channel dimensions alongside regulatory pathway clustering by jurisdiction. Forecast inputs included Black Sea grain export volatility indices and EU deforestation-free supply chain compliance timelines.
Black Sea corridor disruptions, EU traceability mandate enforcement acceleration, and precision fermentation yield breakthroughs are the dominant revision risks to modeled projections. Forecasts reflect documented assumptions about regulatory divergence patterns and technology adoption S-curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
Colombia Agriculture Market
Agriculture and Agri Products
Ginseng Market
Agriculture and Agri Products
Global Animal Feed Dietary Fibers Market
Agriculture and Agri Products
Corn Co-Products Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
African Swine Feed Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Middle East and Africa Bonsai Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Europe Compound Feed Market
Agriculture and Agri Products
Europe Alfalfa Hay Market
Agriculture and Agri Products
Africa Poultry Feed Market