
 Energy and Protein Bars Market | 2026-2036
Energy and Protein Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Energy and Protein Bars Market Insights
EU Green Deal nutrition labeling requirements is realigning the cost-of-entry calculus for European entrants, forcing reformulation investments before products reach shelf. Mondelez International leverages its global snack infrastructure to sustain distribution density across multiple continents. General Mills anchors its position through R&D intensity in whole-grain and protein-fortified bar platforms. Nestlé competes via vertical integration into plant-protein supply chains, reducing ingredient cost volatility.
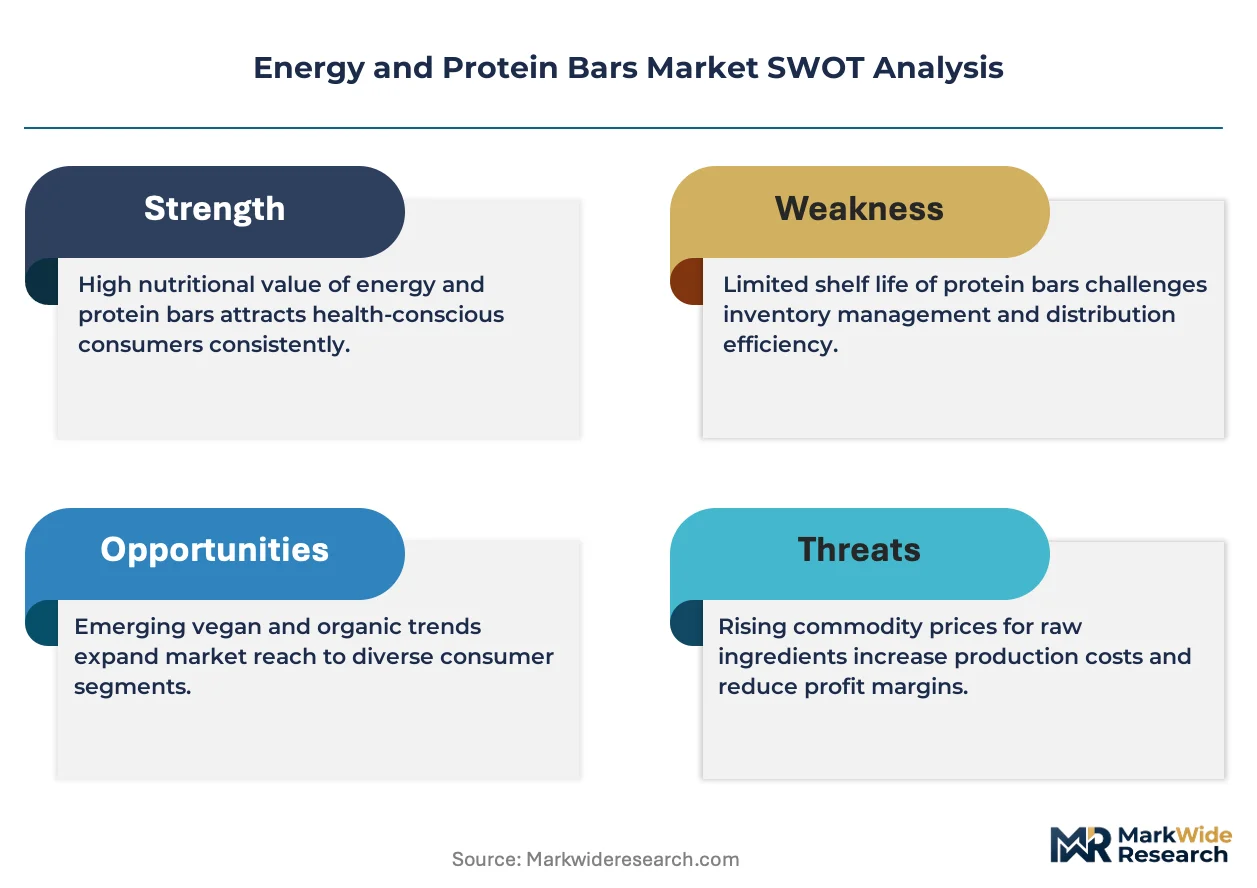
Energy and protein bars are shelf-stable, nutrient-dense food products typically formulated with protein isolates, carbohydrate binders, and lipid sources, manufactured through cold-press extrusion or baked-sheet forming to achieve specified texture and macronutrient targets; their primary commercial purpose is to deliver convenient, portion-controlled nutrition for on-the-go consumption and athletic recovery. The ingredient type dimension shows plant-based formulations capturing the fastest growth trajectory as consumer preference shifts away from dairy-derived proteins, while whey protein remains the margin pool leader due to established supply chains and sports-nutrition credibility. Distribution through gyms and health stores concentrates the highest per-unit margins, though online retail extends volume reach into suburban and rural geographies previously underserved by specialty brick-and-mortar.
FDA nutrition labeling rules and USDA organic certification standards govern product claims and market access in the United States, while EFSA health-claim regulations in Europe restrict how manufacturers communicate performance benefits to consumers. These frameworks elevate compliance spending but simultaneously create barriers that favor established operators with dedicated regulatory affairs capacity. Stakeholders must monitor evolving protein-source sustainability mandates and front-of-pack labeling expansions as these will determine which formulation portfolios retain shelf access across major retail channels.
Market Dynamics
Plant-based protein extraction technologies and EU Green Deal labeling mandates are forcing simultaneous reformulation and compliance investments, compressing margins for entrants while rewarding operators with captive R&D infrastructure.
Growth Catalysts
- Fitness Enthusiast Adoption:Performance-oriented consumers in the United States and Germany are expanding consumption beyond post-workout windows into meal-replacement occasions, broadening addressable demand.
- EFSA Health-Claim Frameworks:Clarified regulatory pathways in Europe enable substantiated protein-content claims, reducing litigation risk for compliant manufacturers.
- Cold-Press Extrusion:This manufacturing process preserves heat-sensitive micronutrients while achieving shelf-stable textures, unlocking clean-label positioning previously unattainable with baked-sheet forming.
Market Restraints
- Pea Protein Input Volatility:Weather-dependent harvests in Canada and France create price swings that compress gross margins for plant-based formulators.
- Whey Supply Concentration:Dairy processing infrastructure clusters in Wisconsin and the Netherlands, creating geographic single-point vulnerabilities for conventional protein sourcing.
- FDA Nutrition Labeling Compliance:Updated serving-size definitions and added-sugar disclosure requirements impose reformulation costs and packaging redesign cycles.
Strategic Opportunities
- Rural China Penetration:E-commerce logistics networks now reach tier-three cities and county-level markets previously inaccessible to specialty nutrition retail.
- Geriatric Nutrition Applications:Sarcopenia-prevention positioning targets adults over 65 with texture-modified, high-protein formats distinct from athletic bars.
- USDA Organic Certification:Federal procurement preferences and retailer slotting-fee reductions for certified products create margin expansion pathways for qualifying suppliers.
Industry Challenges
- Food Technologist Talent Scarcity:Formulation expertise bridging protein chemistry, sensory science, and process engineering commands premium compensation, constraining mid-scale R&D expansion.
- Dual Certification Timelines:Simultaneous pursuit of organic and non-GMO verification extends time-to-market by 8-14 months, delaying revenue recognition.
- Legacy ERP Integration:Lot-traceability requirements for allergen management clash with dated manufacturing-execution systems, forcing costly middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy and Protein Bars Market |
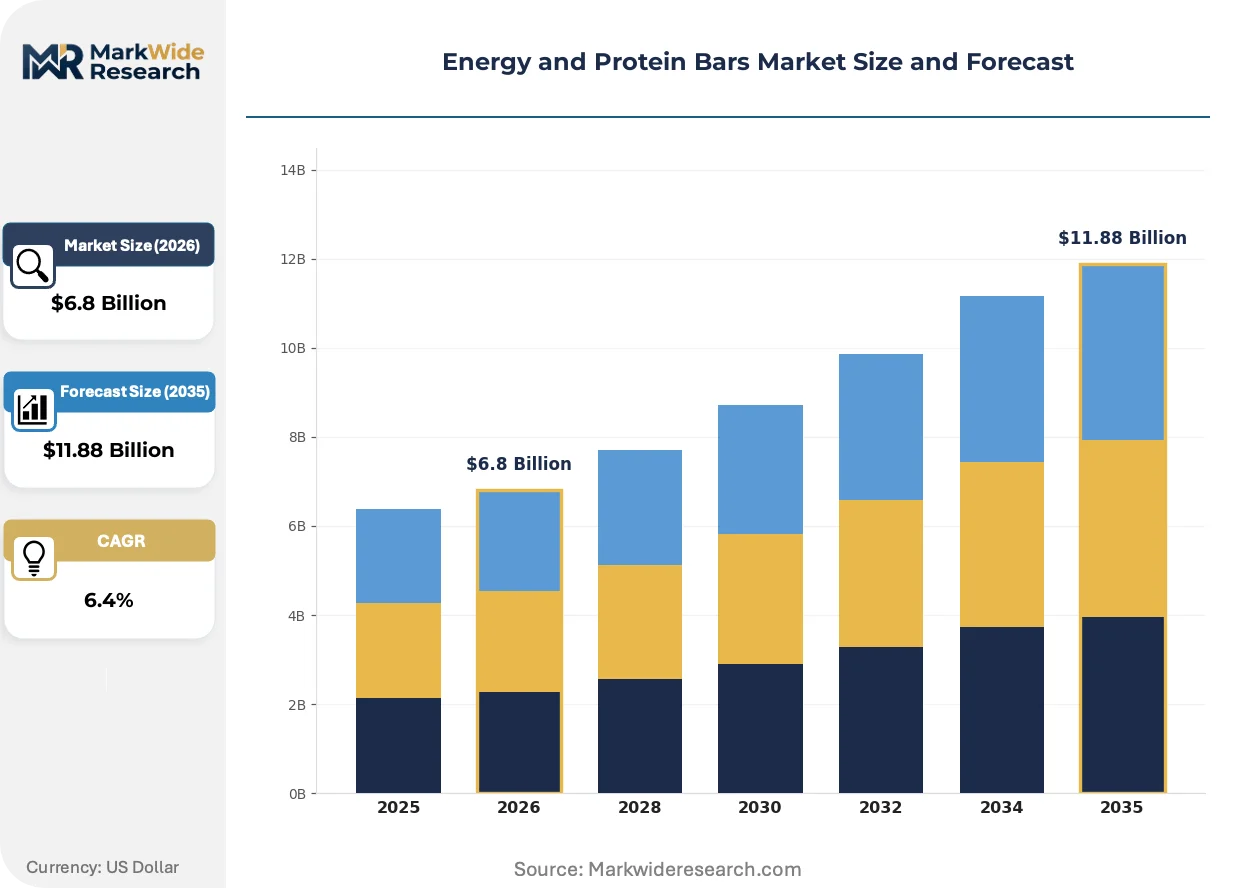
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chewy Bars, Crunchy Bars, Protein Balls, Snack Cubes Ingredient Type: Nuts, Seeds, Whey Protein, Plant-Based Distribution Channel: Supermarkets, Health Stores, Online Retail, Gyms End User: Athletes, Fitness Enthusiasts, Busy Professionals, Students |
| Companies Covered | Mondelez International, General Mills, Nestlé, Quest Nutrition, Mars Incorporated, Kellanov, BellRing Brands, Glanbia, The Simply Good Foods Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy and Protein Bars Market Trends and Innovations
Fermentation-derived protein isolates, front-of-pack sustainability scoring, and direct-to-consumer subscription models are simultaneously reshaping ingredient sourcing, label communication, and customer acquisition economics.
Fermentation-based protein production is expanding into commercial-scale manufacturing, with precision-fermentation platforms converting sugars into complete amino-acid profiles without agricultural land use. Early adopters in the alternative-dairy adjacent space are piloting these inputs for bar applications at pilot-plant scale. This technology is expanding into the ingredient supply base, threatening to displace commodity pea and soy isolates within the premium tier.
EU Green Deal nutrition labeling requirements mandate harmonized front-of-pack scoring across member states, compressing the allowable claim vocabulary for macronutrient ratios. Manufacturers must now reformulate to achieve favorable Nutri-Grade or Eco-Score ratings before shelf placement. German and French retailers are enforcing these thresholds as listing prerequisites, accelerating clean-label R&D spending.
Subscription-based replenishment models displace conventional grocery replenishment for core users, locking in 12-24 week purchase cycles with predictable inventory absorption. Specialty e-commerce platforms and brand-owned storefronts capture this shift, diverting volume from mass-market brick-and-mortar. This pattern concentrates in the United States and United Kingdom where delivery infrastructure and payment-automation maturity support frictionless recurring transactions.
Energy and Protein Bars Market Segmentation
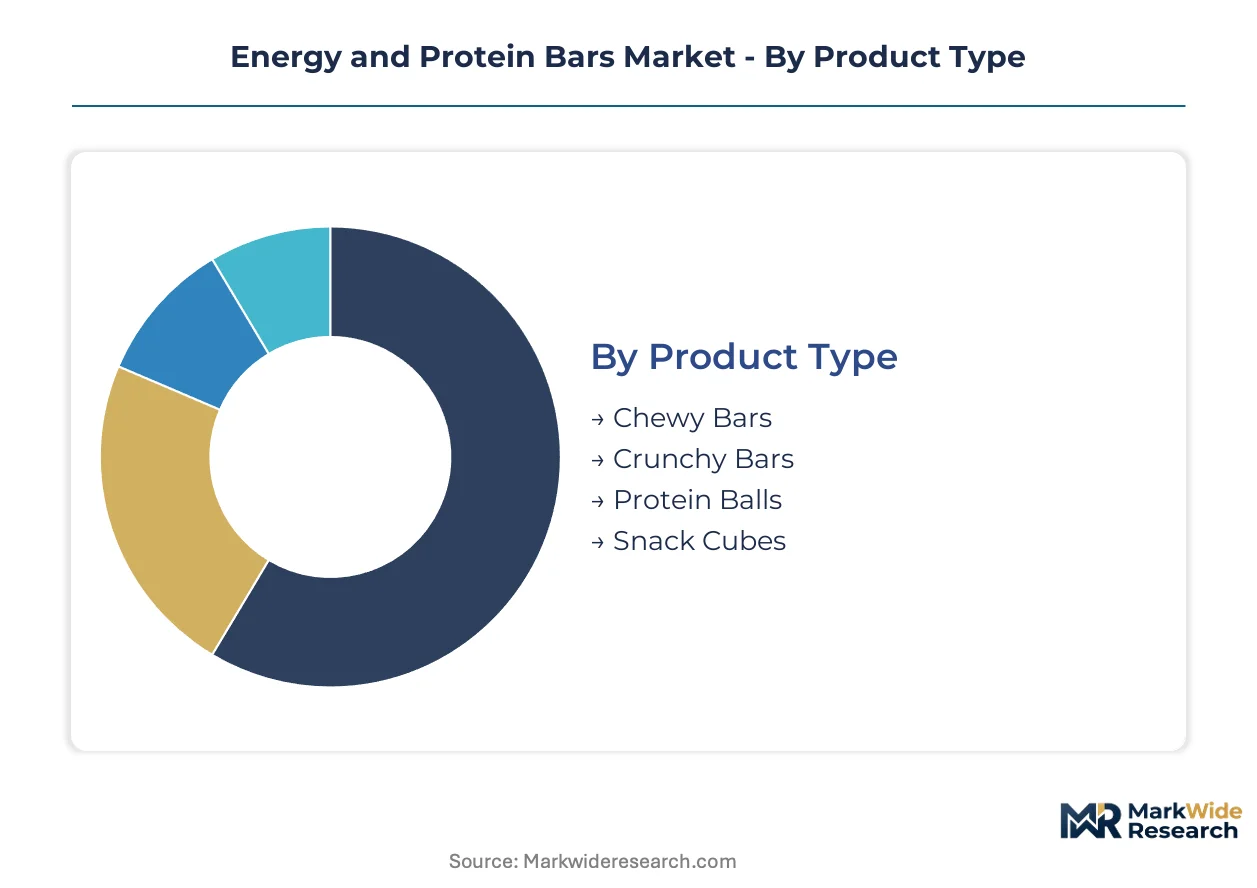
Formulation choices and channel strategies in the Energy and Protein Bars Market determine margin capture and shelf placement. Product texture, protein source, and purchase occasion each create distinct competitive arenas with separate cost-to-serve economics.
Product Type:
Texture innovation cycles drive consumer trial and repeat purchase, with mouthfeel preferences shifting between indulgence and functional minimalism.
- Chewy Bars:Cold-press extrusion preserves moisture-binding hydrocolloids, yielding dense, taffy-like textures that dominate meal-replacement positioning. Demand concentrates in Germany and the United States where consumers prioritize satiety duration over caloric density.
- Crunchy Bars:Baked-sheet forming creates brittle, cereal-like structures through controlled Maillard reactions; puffed rice and protein crisp inclusions provide audible fracture cues. Fitness enthusiasts in China favor this format for pre-workout energy delivery without gastric heaviness.
- Protein Balls:Hand-rolled or molded spherical formats bypass cutting operations, reducing manufacturing CapEx for artisanal entrants.
- Snack Cubes:Bite-sized geometries target portion-control positioning and child-friendly packaging applications.
Volume placements concentrate in Chewy Bars; the faster expansion belongs to Protein Balls.
Ingredient Type:
Input costs and sustainability credentials now outweigh taste as primary formulation determinants for premium tier placement.
- Plant-Based:Pea, rice, and fava bean isolates deliver complete amino-acid profiles through strategic blending ratios. Germany's EFSA-aligned retailers mandate these inputs for shelf access under EU Green Deal procurement guidelines.
- Whey Protein:Dairy-derived concentrates and isolates retain sports-nutrition credibility through leucine-bioavailability data. Wisconsin-sourced whey supplies Mondelez International and General Mills with cost-stable inputs for North American production.
- Nuts:Almond and cashew butter bases provide lipid-phase stability and clean-label simplicity.
- Seeds:Chia, hemp, and pumpkin seed inclusions add omega-3 positioning and textural contrast.
Plant-Based inputs are gaining share fastest; Whey Protein retains the largest absolute volume.
Distribution Channel:
Channel selection dictates pricing architecture and consumer education requirements, with specialty retail commanding margin premiums.
- Health Stores:Staff-assisted selling environments enable ingredient-storytelling and subscription enrollment. The United Kingdom and United States concentrate this channel's revenue contribution.
- Online Retail:Direct-to-consumer storefronts and Amazon marketplace presence capture replenishment automation and data-rich customer relationships.
- Supermarkets:Mass-market placement requires slotting-fee negotiations and front-of-pack compliance with FDA and EU labeling mandates.
- Gyms:Point-of-sweat impulse placement captures post-workout replenishment with minimal competitive set.
Health Stores generate the highest per-unit margins; Online Retail is climbing the fastest.
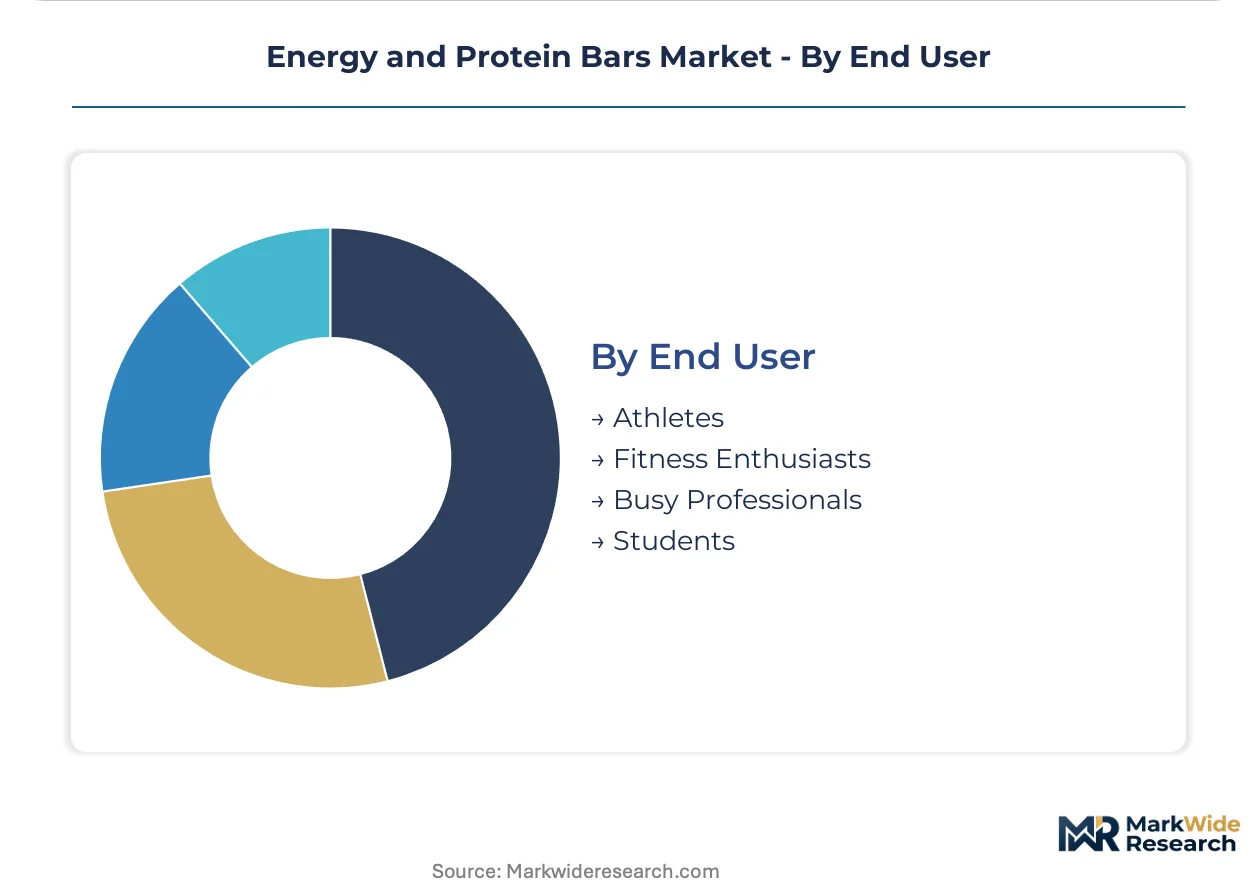
End User:
Usage occasion fragmentation requires distinct formulation architectures, from glycogen-replenishment timing to desk-drawer shelf stability.
- Fitness Enthusiasts:This segment consumes across pre-workout, intra-workout, and recovery windows, driving demand for segmented macronutrient ratios. China and Germany show the steepest adoption curves as gym penetration deepens.
- Athletes:Competitive and elite performers require batch-tested, contaminant-screened products with substantiated performance claims.
- Busy Professionals:Meal-replacement positioning emphasizes convenience and blood-glucose stability for intermittent eating patterns.
- Students:Price-sensitive trial driven by campus retail proximity and social-media-influenced flavor novelty.
Fitness Enthusiasts represent the largest addressable base; Athletes command the premium pricing tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Shenzhen and bonded logistics parks in Rotterdam concentrate contract manufacturing for export-oriented bar production, creating tax-advantaged nodes that shape regional supply allocation.
United States
Fitness enthusiasts in California and Texas drive meal-replacement adoption beyond traditional sports-nutrition occasions. FDA nutrition labeling rules and USDA organic certification standards govern product claims and interstate commerce. Wisconsin anchors whey protein processing infrastructure that supplies Mondelez International and General Mills with cost-stable dairy inputs.
Germany
Clean-label demand in Bavaria and North Rhine-Westphalia accelerates plant-based formulation shifts. EU Green Deal nutrition labeling requirements and EFSA health-claim frameworks restrict permissible marketing language while clarifying compliance pathways. Berlin-Brandenburg clusters specialty food startups piloting cold-press extrusion for nutrient-preserving textures.
China
Gym penetration in Shanghai and Beijing expands pre-workout bar consumption among urban professionals. SAMR food safety regulations and GB standards for pre-packaged foods establish manufacturing and import protocols. The Yangtze River Delta concentrates e-commerce fulfillment centers reaching tier-three cities previously inaccessible to specialty nutrition retail.
United Kingdom
Subscription-model adoption in London and Southeast England diverts volume from conventional grocery replenishment. EFSA-aligned post-Brexit retained regulations maintain health-claim substantiation requirements. The Midlands hosts contract manufacturers serving direct-to-consumer brands with flexible production runs.
Australia
Endurance-sport participation in New South Wales and Victoria sustains demand for glycogen-focused formulations. TGA therapeutic goods oversight and FSANZ food standards govern product classification and label claims. Sydney anchors import-distribution hubs supplying Pacific Island markets with shelf-stable nutrition products.
Energy and Protein Bars Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation, channel, and price-positioning vectors. The vendor base clusters into three tiers: multinational snack conglomerates with global distribution infrastructure, mid-scale nutrition specialists with captive R&D capabilities, and artisanal entrants leveraging direct-to-consumer storefronts. Dominant competitive moves include backward integration into plant-protein supply chains and subscription-based customer acquisition models that displace conventional retail replenishment.
Within the multinational conglomerate tier, Mondelez International, General Mills, and Nestlé exemplify scale-driven positioning that leverages existing snack infrastructure and procurement density. Mondelez International sustains distribution reach across multiple continents through established retail relationships. General Mills anchors its competitive position through R&D intensity in whole-grain and protein-fortified platforms. Nestlé occupies a distinctive position via upstream control over plant-protein supply chains, reducing ingredient cost volatility relative to commodity-dependent competitors.
| Leading Market Players |
|---|
| Mondelez International |
| General Mills |
| Nestlé |
| Quest Nutrition |
| Mars Incorporated |
| Kellanov |
| BellRing Brands |
| Glanbia |
| The Simply Good Foods Company |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists dominate the mid-tier protein bar segment, concentrating manufacturing assets in Wisconsin and the Netherlands to exploit whey processing infrastructure while enforcing pricing discipline through volume commitments to dairy cooperatives.
Pricing Analysis
Short lead-time premiums attach to cold-press extrusion capacity in Germany and California, where nutrient-preserving equipment runs at tight utilization. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade: USDA Organic and EU Green Deal-aligned formulations command shelf-price premiums, while conventional whey-based bars face cost compression from pea protein substitution. Fitness enthusiasts in China exhibit highest price sensitivity, whereas health-store buyers in the United Kingdom accept premium positioning for subscription-locked replenishment.
Supply Chain Analysis
Pea protein supply rests on Canadian and French agricultural harvests, with fava bean isolates emerging from Baltic processing facilities as alternative inputs. Wisconsin and Dutch dairy infrastructure anchors whey concentrate production, creating geographic tethering for conventional formulators. Single-source vulnerability concentrates in Canadian pea protein extraction, where weather-dependent yields transmit volatility downstream. Distribution runs through bonded logistics parks in Rotterdam and Shenzhen, channeling export-oriented production into regional retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around operators with captive R&D infrastructure, as EU Green Deal compliance costs and dual-certification timelines force sub-scale players toward exit or acquisition.
For Market Incumbents: Extend backward integration into plant-protein supply chains to neutralize input cost volatility from Canadian pea harvests. Lock in health-store channel control through exclusive subscription partnerships, defending against direct-to-consumer entrants. Prioritize cold-press extrusion capacity additions in California and Berlin-Brandenburg to capture clean-label premium positioning as EFSA labeling mandates tighten. For New Entrants and Emerging Players: Precision-fermentation protein platforms offer technology-first wedge into the premium tier, displacing commodity isolates with complete amino-acid profiles without agricultural land use. Target geriatric nutrition applications in Japan and rural China penetration via e-commerce logistics as white-space opportunities. Lead with direct-to-consumer storefronts to bypass slotting-fee barriers in mass-market retail. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale nutrition specialists with captive formulation expertise in Germany and the United States, where compliance spending has compressed valuations. Long-term viability centers on operators with demonstrated regulatory affairs capacity spanning FDA and EFSA frameworks. Watch fermentation-derived protein scale-up as inflection indicator for input cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plant-Protein Supply | Captive sourcing from Canadian and Baltic processors reduces exposure to pea protein spot volatility. |
| Cold-Press Extrusion Capacity Expansion | Berlin-Brandenburg and California installations preserve heat-sensitive micronutrients for EU Green Deal compliance. |
| Direct-to-Consumer Subscription Launch | Brand-owned storefronts in the United States and United Kingdom bypass mass-market slotting fees. |
| Precision-Fermentation Protein Piloting | Sugar-to-protein platforms threaten displacement of commodity pea and soy isolates in premium tiers. |
| Geriatric Nutrition Format Development | Texture-modified, high-protein bars target sarcopenia-prevention positioning for adults over 65. |
Research Methodology
Independent corroboration across food technology executives, regulatory affairs specialists at EFSA-aligned firms, health-store category buyers, and contract manufacturing plant managers underwrites the qualitative findings. Secondary validation draws from FDA nutrition labeling filings, EU Green Deal implementation guidance, SAMR food safety registrations, and customs records tracking whey and plant-protein trade flows. Bottom-up demand modeling triangulates against top-down market sizing across ingredient type, product texture, and distribution channel dimensions.
Rate-of-change decomposition separates volume expansion from value capture across the analysis window, with segmentation modeling spanning formulation architecture, protein source, purchase occasion, and regional regulatory cluster. CAGRs derive from curve-fitting historical consumption patterns against projected gym penetration, e-commerce logistics expansion, and certification adoption rates. Forecast inputs incorporate cold-press extrusion capacity buildout timelines and fermentation-protein commercialization milestones.
Several conditions sit outside the modeled scope, including sudden tariff disruptions to Canadian pea protein imports, unanticipated EFSA health-claim restrictions, and rapid precision-fermentation cost breakthroughs. Forecasts reflect documented assumptions about regulatory stability and input cost trajectories. A small set of named triggers warrants ongoing watch: EU Green Deal labeling enforcement severity, Chinese e-commerce subsidy policy shifts, and major dairy cooperative pricing renegotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Weight Management Products Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
Protein Supplements Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market
Sports Nutrition
United States Weight Management Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
United Kingdom Sports Drink Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
Arginine Supplement Market
Sports Nutrition
United States Sports Drink Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Creatine Supplements Market