
 GLA Supplements Market | 2026-2036
GLA Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
GLA Supplements Market Analytics
Evening primrose oil cultivation in China is restructuring global raw material flows for gamma-linolenic acid extraction. Merck KGaA leverages its pharmaceutical-grade manufacturing infrastructure to supply high-purity GLA isolates for clinical research applications. Thermo Fisher Scientific anchors the analytical standards segment with certified reference materials that laboratories require for potency verification. Nordic Naturals differentiates through its omega-fatty acid portfolio integration, positioning GLA within broader essential fatty acid regimens.
Gamma-linolenic acid supplements deliver an omega-6 fatty acid derived primarily from evening primrose, borage, and black currant seed oils, typically standardized to concentrations ranging from 8% to 24% GLA content depending on botanical source. Manufacturers employ cold-press extraction and molecular distillation to preserve fatty acid integrity and remove residual solvents. Softgels dominate current volume due to consumer familiarity and oxidation protection, though liquid formats are gaining traction among pediatric and geriatric populations who require dose flexibility. Black currant oil sources command premium positioning owing to superior GLA concentration and concurrent anthocyanin content, while borage oil competes on cost-efficient higher-yield extraction.
The FDA oversees dietary supplement Good Manufacturing Practices through 21 CFR Part 111, mandating identity testing and contaminant screening that elevates compliance costs for smaller entrants. EFSA's health claims assessment framework restricts permissible marketing language, forcing reformulation toward substantiated endpoints like skin barrier maintenance. Australia's TGA maintains parallel therapeutic goods registration pathways that bifurcate the market between listed complementary medicines and prescription-grade products. Stakeholders must monitor evolving pharmacovigilance requirements as regulators scrutinize omega-6 to omega-3 ratio claims and long-term safety profiles in chronic supplementation protocols.
Market Dynamics
Evening primrose cultivation concentration in China's Xinjiang and Heilongjiang provinces is compressing raw material sourcing flexibility, forcing manufacturers to diversify toward black currant and borage alternatives or absorb volatile agricultural input costs.
Growth Catalysts
- EFSA substantiated claims:The EU regulator's approval of skin barrier maintenance and inflammation modulation endpoints permits compliant brands to differentiate through permissible marketing language.
- Fitness sector demand:Athletes and recreational exercisers prioritize GLA for exercise-induced inflammation management, expanding the consumer base beyond traditional women's health positioning.
- Supercritical CO2 extraction:This solvent-free processing technology preserves thermolabile fatty acids while eliminating residual hexane concerns, satisfying clean-label procurement criteria.
Market Restraints
- Input cost volatility:Evening primrose seed prices fluctuate with Chinese agricultural policy shifts and climate variability in primary growing regions.
- Regulatory friction:Australia's TGA therapeutic goods registration bifurcates the market, requiring separate compliance pathways for listed complementary versus prescription-grade products.
- Substitution threat:Marine omega-3 concentrates and specialized pro-resolving mediators compete for inflammation management positioning with stronger clinical trial backing.
Strategic Opportunities
- Pediatric formulation expansion:Liquid GLA formats address dosing flexibility needs for children with atopic dermatitis, an underpenetrated segment in North American and European markets.
- Clean beauty convergence:Topical GLA-infused serums and capsules target ingestible beauty positioning, leveraging EFSA-approved skin hydration claims.
- Direct-to-consumer channel maturation:Subscription models and personalized nutrition platforms reduce retail margin compression while capturing recurring revenue.
Industry Challenges
- Analytical chemistry capability gaps:Few contract laboratories maintain ISO 17025 accreditation for fatty acid methyl ester profiling, creating bottlenecks in identity verification.
- Cross-border compliance complexity:Divergent maximum permitted GLA concentration limits between Health Canada and FDA jurisdictions complicate unified formulation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GLA Supplements Market |
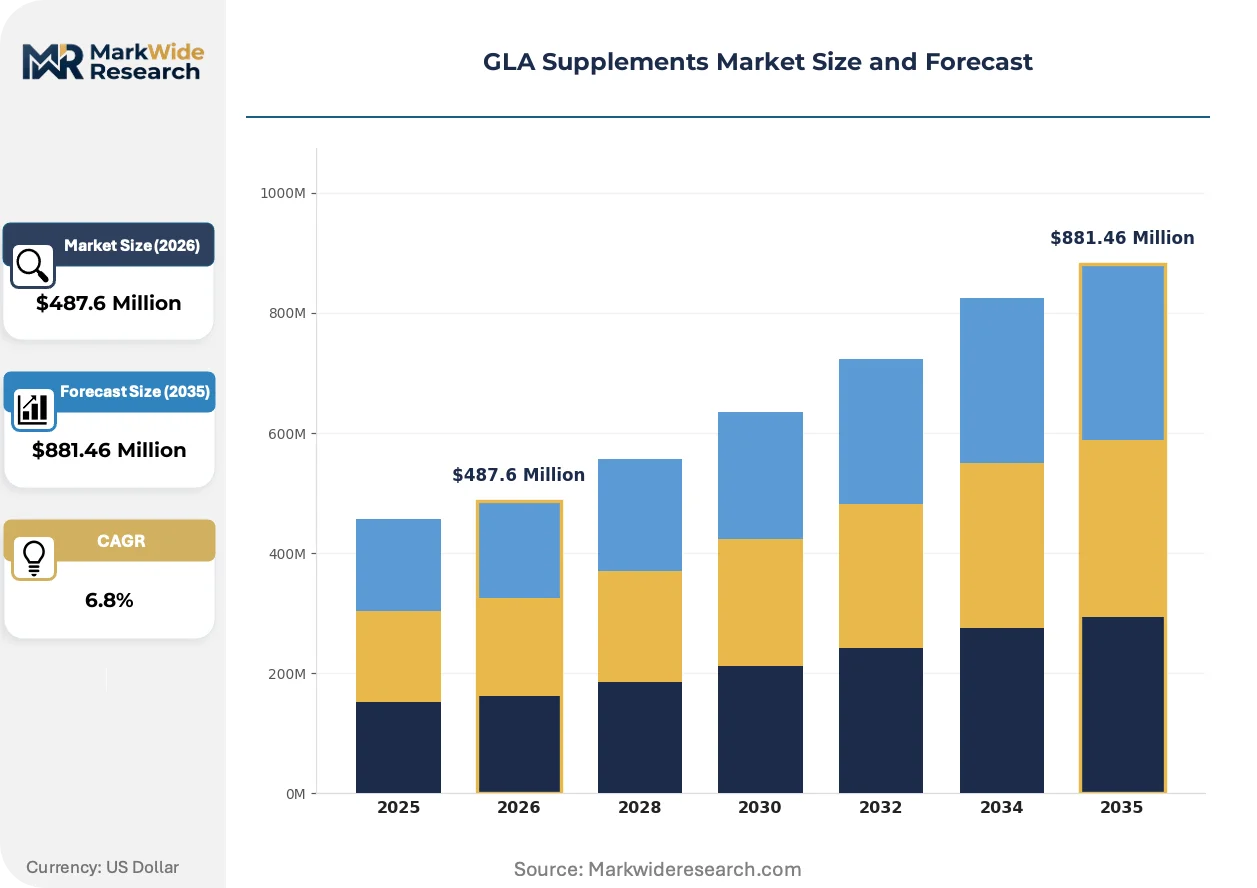
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softgels, Capsules, Powder, Liquid Source: Evening Primrose Oil, Borage Oil, Black Currant Oil, Others End User: Health Conscious Consumers, Athletes, Patients, Fitness Enthusiasts Distribution Channel: Online Retail, Pharmacies, Specialty Stores, Supermarkets |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific, Enzo Life Sciences, Inc., Cayman Chemical, Charkit Chemical, Cherish Pharma, Changsha Vigorous-Tech, Nordic Naturals, Nature's Way Products, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GLA Supplements Market Evolving Landscape
Extraction technology advancement and regulatory claim substantiation are reshaping competitive differentiation, while demand-side channel evolution compresses traditional wholesale structures.
Supercritical CO2 extraction equipment is automating the removal of residual solvents and oxidation-prone impurities from evening primrose and borage oils. Mid-sized supplement manufacturers in Germany and the Netherlands are adopting these systems to achieve pharmaceutical-grade purity without molecular distillation infrastructure. This technology is automating quality parity between artisanal and industrial production scales.
REACH regulation updates on novel food ingredient notifications are tightening botanical oil import documentation requirements for EU market entry. The European Food Safety Authority's expanded novel food catalog now classifies certain black currant cultivars as requiring pre-market authorization, extending product development timelines. German and French importers are responding by vertically integrating into controlled-environment cultivation to secure regulatory grandfathering.
Subscription-based personalized nutrition platforms are displacing retail pharmacy and mass-market shelf presence for GLA products. Athletic and wellness-focused consumers in California, Texas, and Florida now initiate purchase journeys through algorithm-driven supplement stacks rather than brick-and-counter consultation. This channel rotation concentrates customer data ownership with platform operators rather than ingredient suppliers.
GLA Supplements Market Segmentation
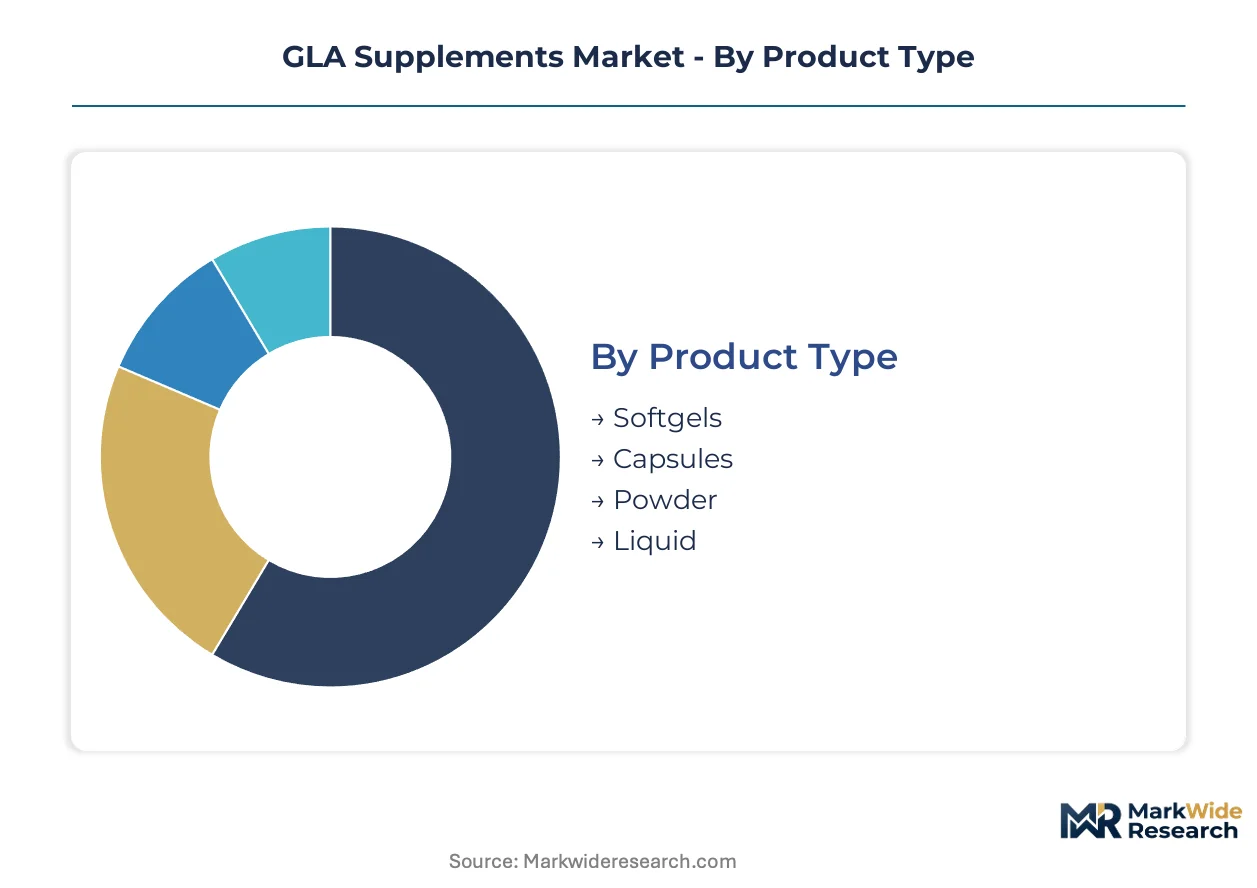
GLA supplement formulations vary dramatically in bioavailability, oxidation stability, and dosing precision. Manufacturers align product architecture with specific consumption contexts, from portable softgels for travelers to titratable liquids for pediatric protocols.
Product Type:
Encapsulation technology and physical state determine shelf-life economics and consumer compliance rates.
- Softgels:Gelatin or plant-based shells enclose oil-based GLA extracts, providing superior oxygen barrier properties that extend stability to 24-36 months. Fitness enthusiasts in California and Texas favor softgels for gym bag portability, though gelatin sourcing faces clean-label scrutiny from vegan consumer segments.
- Liquid:Dropper-dispensed or pump-bottle formats enable precise milligram adjustment for children with atopic dermatitis and elderly patients with swallowing difficulties. Demand concentrates in pediatric specialty clinics across Germany and the Netherlands, where allergists prescribe weight-calibrated dosing regimens.
- Capsules:Two-piece hard shells accommodate powder or beadlet formulations, offering vegetarian alternatives to gelatin softgels. Health food retailers in Canada stock capsule formats for plant-based positioning.
- Powder:Bulk containers serve compounding pharmacies and functional food manufacturers integrating GLA into smoothie bases or meal replacements. Sports nutrition brands in Australia blend powder into pre-workout formulations.
Mature deployment sits with softgels. Newer deployment is concentrated in liquid formats for precision-dosing applications.
Source:
Botanical provenance dictates GLA concentration, co-constituent profile, and agricultural supply risk.
- Evening Primrose Oil:Oenothera biennis seeds yield 8-10% GLA content with concurrent linoleic acid, requiring higher dosage volumes for therapeutic effect. Chinese cultivation in Xinjiang and Heilongjiang provinces supplies over 70% of global raw material, exposing manufacturers to climate volatility and export policy shifts.
- Black Currant Oil:Ribes nigrum seeds deliver 15-20% GLA alongside anthocyanin antioxidants, commanding premium pricing in dermatological and anti-aging applications. Controlled-environment cultivation in Poland and New Zealand is expanding to reduce dependency on Chinese evening primrose flows.
- Borage Oil:Borago officinalis achieves the highest natural GLA concentration at 20-24%, enabling cost-efficient formulation with lower capsule counts. Spanish and UK agricultural cooperatives dominate borage seed production for European manufacturing.
- Others:Fungal-derived GLA from Mortierella alpina and genetically modified safflower cultivars serve pharmaceutical research and infant formula applications requiring non-botanical sourcing.
Evening primrose oil anchors volume production. Black currant oil is climbing the fastest on premium positioning.
End User:
Consumer motivation and clinical context reshape formulation priorities and channel strategy.
- Health Conscious Consumers:Preventive wellness seekers prioritize clean-label sourcing and EFSA-substantiated skin hydration claims, purchasing through subscription platforms rather than retail pharmacies.
- Fitness Enthusiasts:Recreational and competitive athletes use GLA for exercise-induced inflammation modulation, driving demand for NSF Certified for Sport and Informed Sport tested products.
- Patients:Individuals with diagnosed atopic dermatitis, rheumatoid arthritis, or diabetic neuropathy require clinician-guided dosing, often accessing GLA through prescription-grade pathways in Australia's TGA-regulated market.
- Athletes:Professional and elite amateur competitors represent a narrower segment than fitness enthusiasts, demanding batch-tested products with documented absence of WADA-prohibited substances.
Health conscious consumers dominate volume. Patients represent the steepest expansion trajectory as clinical validation accumulates.
Distribution Channel:
Channel selection determines margin structure, customer data ownership, and regulatory compliance burden.
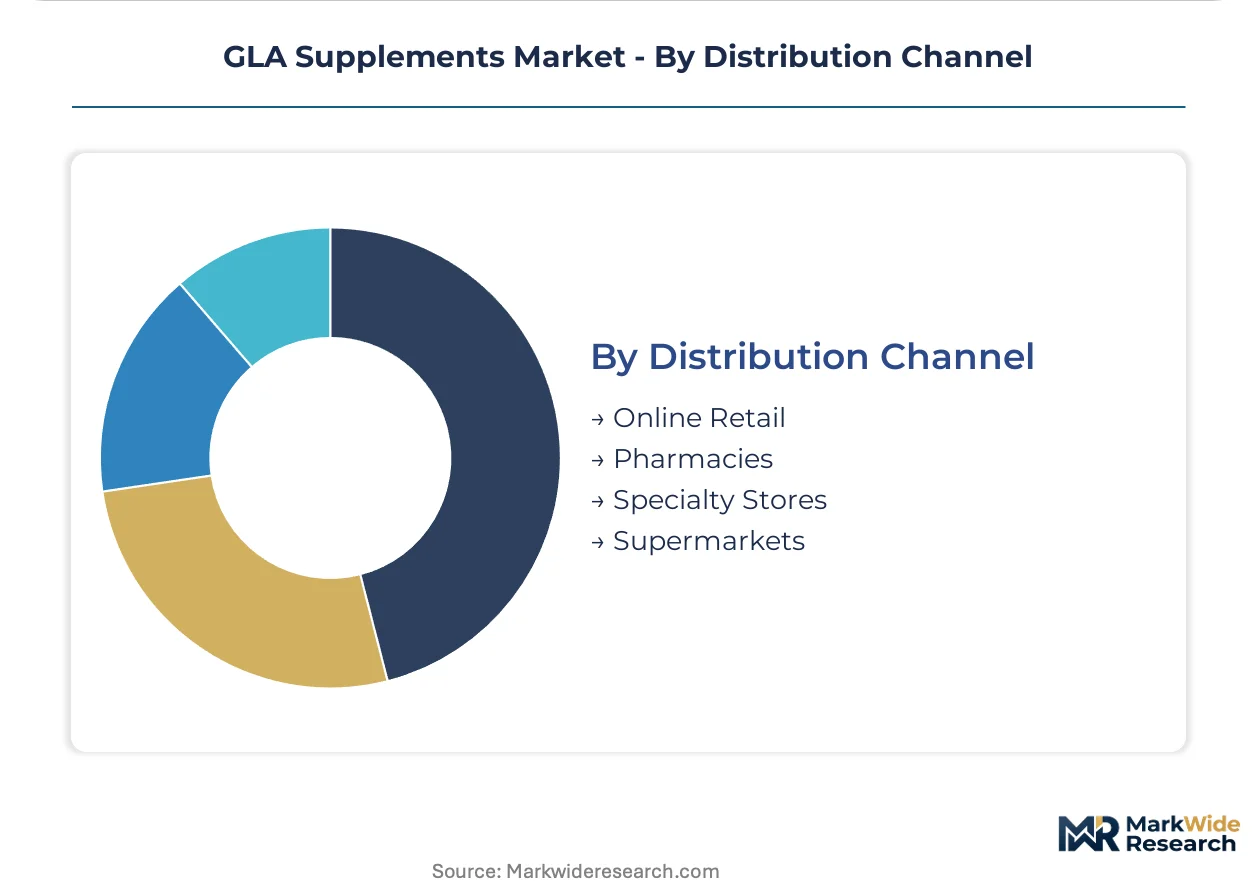
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capture recurring revenue through subscription models, concentrating customer relationships with algorithm-driven wellness stacks rather than ingredient suppliers.
- Pharmacies:Community and hospital pharmacies serve clinically referred patients requiring pharmacist consultation, particularly in Germany's apothecary-dominant retail environment.
- Specialty Stores:Health food cooperatives and vitamin boutiques curate premium-positioned black currant oil products with organic and non-GMO certifications.
- Supermarkets:Mass-market grocers stock economy-tier evening primrose oil softgels, competing primarily on price-per-capsule metrics.
Pharmacies retain stable prescription-adjacent volume. Online retail is gaining share fastest as platform operators consolidate supplement purchasing journeys.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Evening primrose cultivation in China's Xinjiang and Heilongjiang provinces supplies over 70% of global raw material, anchoring production geography while exposing manufacturers to climate volatility and export policy shifts. This concentration forces formulation diversification toward black currant and borage alternatives across importing regions.
United States
Fitness enthusiasts in California, Texas, and Florida drive demand for exercise-induced inflammation management, expanding GLA beyond traditional women's health positioning. FDA oversight through 21 CFR Part 111 mandates identity testing and contaminant screening that elevates compliance costs for smaller entrants. Direct-to-consumer supplement brands in Los Angeles and Austin command expanding digital shelf space through subscription models and personalized nutrition platforms.
Germany
Preventive wellness seekers prioritize clean-label sourcing and EFSA-substantiated skin hydration claims, purchasing through subscription platforms rather than retail pharmacies. REACH regulation updates on novel food ingredient notifications tighten botanical oil import documentation requirements for EU market entry. Mid-sized supplement manufacturers in Germany and the Netherlands adopt supercritical CO2 extraction systems to achieve pharmaceutical-grade purity without molecular distillation infrastructure.
China
Agricultural policy shifts and climate variability in Xinjiang and Heilongjiang provinces compress raw material sourcing flexibility for evening primrose seed. The country's national pharmaceutical regulator maintains oversight of dietary supplement manufacturing standards that parallel international GMP frameworks. Cultivation concentration in these northwestern provinces is restructuring global raw material flows for gamma-linolenic acid extraction.
Australia
Individuals with diagnosed atopic dermatitis, rheumatoid arthritis, or diabetic neuropathy access GLA through prescription-grade pathways in the TGA-regulated market. TGA therapeutic goods registration bifurcates the market between listed complementary medicines and prescription-grade products, requiring separate compliance pathways. Sports nutrition brands blend GLA powder into pre-workout formulations for the athletic segment.
Poland
Controlled-environment cultivation of black currant is expanding to reduce dependency on Chinese evening primrose flows, securing supply chain resilience. EFSA's health claims assessment framework restricts permissible marketing language, forcing reformulation toward substantiated endpoints like skin barrier maintenance. Polish agricultural cooperatives are vertically integrating into cultivation to secure regulatory grandfathering under expanded novel food catalog classifications.
GLA Supplements Market Competitive Landscape
Global majors compete with regional champions across extraction technology and regulatory compliance capabilities. The market structure blends pharmaceutical-grade manufacturers with botanical specialists and direct-to-consumer wellness platforms. Three archetypes dominate: laboratory chemical suppliers serving research applications, nutritional oil specialists integrating GLA within broader fatty acid portfolios, and contract manufacturers enabling private-label market entry. Competitive moves concentrate on supercritical CO2 extraction adoption and backward integration into controlled-environment cultivation.
Within the pharmaceutical-grade tier, Merck KGaA leverages manufacturing infrastructure to supply high-purity GLA isolates for clinical research applications. Thermo Fisher Scientific anchors the analytical standards segment with certified reference materials that laboratories require for potency verification. Nordic Naturals occupies a position within the nutritional oil specialists, differentiating through omega-fatty acid portfolio integration that positions GLA within broader essential fatty acid regimens. These three represent distinct competitive vectors: research-grade purity, analytical verification, and consumer-facing portfolio breadth.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific |
| Enzo Life Sciences, Inc. |
| Cayman Chemical |
| Charkit Chemical |
| Cherish Pharma |
| Changsha Vigorous-Tech |
| Nordic Naturals |
| Nature's Way Products, LLC |
| Others |
Value Network & Pricing Analysis
Fitness sector procurement teams in California and Texas now mandate NSF Certified for Sport documentation as a baseline qualification, forcing manufacturers to absorb third-party testing costs or surrender shelf space to compliant rivals. This specification compression is reshaping cost structures across extraction tiers and compressing margins for non-certified producers.
Pricing Analysis
Certification bundling now separates premium-positioned black currant oil from unverified evening primrose alternatives, with EFSA-substantiated skin barrier claims commanding measurable price premiums over generic inflammation positioning. Three-tier pricing structure across premium, standard, and economy levels reflects GLA concentration differentials, organic certification status, and supercritical CO2 processing verification. Price differentiation stems from analytical testing burdens and cold-chain logistics requirements. Economy-tier evening primrose softgels face the sharpest price compression as supermarket private-label entrants flood mass-market channels.
Supply Chain Analysis
Polish domestic-content requirements for novel food grandfathering status are redirecting cultivation investment toward controlled-environment black currant operations, reducing import dependency. Raw material flows concentrate on Chinese evening primrose from Xinjiang and Heilongjiang, Spanish and UK borage seed cooperatives, and emerging Polish and New Zealand black currant cultivation. Supply chain risk centers on climate volatility in northwestern Chinese growing regions and export policy unpredictability. Distribution runs through direct-to-consumer subscription platforms, German apothecary networks, and North American specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction systems are displacing legacy hexane-based processing infrastructure, creating capability gaps that favor capital-rich incumbents while opening formulation niches for technology-first entrants.
For Market Incumbents: Deepen backward integration into controlled-environment cultivation in Poland and New Zealand to secure regulatory grandfathering under EFSA novel food expansions. Expand ISO 17025-accredited fatty acid methyl ester profiling capacity to eliminate contract laboratory bottlenecks that delay batch release. Priority levers include captive supply of pharmaceutical-grade GLA isolates and analytical verification services that lock in clinical research relationships. For New Entrants and Emerging Players: Precision-dosing liquid formats for pediatric atopic dermatitis protocols offer the most penetrable white-space target, with demand concentrating in German and Dutch allergist practices where weight-calibrated regimens dominate. Subscription-based personalized nutrition platforms provide algorithm-driven customer acquisition with lower retail margin compression than pharmacy or supermarket channels. Clean-label positioning with supercritical CO2 extraction verification enables differentiation against legacy hexane-processed competitors. For Investors and Strategic Acquirers: The window for entry favors mid-sized European manufacturers with supercritical CO2 extraction infrastructure and EFSA claim substantiation capabilities. Long-term viability hinges on vertical control over cultivation rather than trading-position dependency on Chinese evening primrose flows. Watch for TGA prescription-grade pathway expansions in Australia as the inflection signal for clinical validation accumulation shifting market access requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Adoption | Eliminates residual solvent concerns while preserving thermolabile fatty acid integrity for clean-label positioning. |
| Controlled-Environment Cultivation Expansion | Polish and New Zealand black currant operations reduce dependency on Chinese evening primrose climate volatility. |
| EFSA Claim Substantiation Investment | Skin barrier maintenance approval permits compliant marketing language that differentiates from generic inflammation claims. |
| Pediatric Liquid Formulation Development | Weight-calibrated dosing protocols address unmet need in German and Dutch atopic dermatitis treatment pathways. |
| Direct-to-Consumer Platform Integration | Subscription models capture recurring revenue while concentrating customer data ownership with algorithm-driven wellness stacks. |
Research Methodology
Document review covered FDA 21 CFR Part 111 guidance documents, EFSA novel food catalog updates, and TGA therapeutic goods registration pathways, complemented by interviews with extraction technology suppliers, botanical oil procurement managers at supplement manufacturers, regulatory affairs specialists, and pediatric allergists in Germany and the Netherlands. Secondary validation drew from customs trade data, SEC filings of publicly traded nutritional oil companies, and clinical trial registries. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments.
Segment-level projections across product type, botanical source, end-user motivation, and distribution channel were generated through driver-based modeling over the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating fitness sector expansion, pediatric clinical protocol adoption, and subscription platform penetration rates. Forecast inputs included evening primrose seed price volatility indices, supercritical CO2 equipment installation timelines, and EFSA health claims assessment queue lengths.
Several conditions sit outside the modeled scope, including abrupt Chinese agricultural export restrictions, novel food reclassification of established cultivars, and WADA prohibited substance list revisions affecting athletic certification requirements. Forecasts reflect assumptions regarding regulatory stability and climate patterns in primary growing regions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
South America Sports Nutrition Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
United States Weight Management Market
Sports Nutrition
United Kingdom Sports Drink Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Active Nutrition Market
Sports Nutrition
Protein Supplements Market