
 Branched Chain Amino Acid Supplements Market | 2026-2036
Branched Chain Amino Acid Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Branched Chain Amino Acid Supplements Market Analytics
Registered sports nutritionists and exercise physiologists is redrawing competitive boundaries as qualified formulation expertise becomes scarcer than manufacturing capacity. Ajinomoto leverages decades of fermentation-derived amino acid leadership to sustain premium positioning in ingredient supply. Kyowa Hakko Bio anchors its reputation on pharmaceutical-grade purity standards that differentiate it from commodity producers. Evonik competes through synthetic biology capabilities that extend its reach into precision fermentation for next-generation BCAA production.
Branched chain amino acid supplements contain L-leucine, L-isoleucine, and L-valine in ratios typically ranging from 2:1:1 to 4:1:1, formulated to support muscle protein synthesis and reduce exercise-induced catabolism through mTOR pathway activation. Powders dominate volume due to dosing flexibility and lower per-serving cost structures, while capsules capture margin pools among convenience-seeking travelers and workplace consumers. Vegan formulation segments are expanding fastest as plant-derived fermentation replaces traditional animal-based extraction methods, though synthetic routes still occupy the cost-sensitive mass market tier.
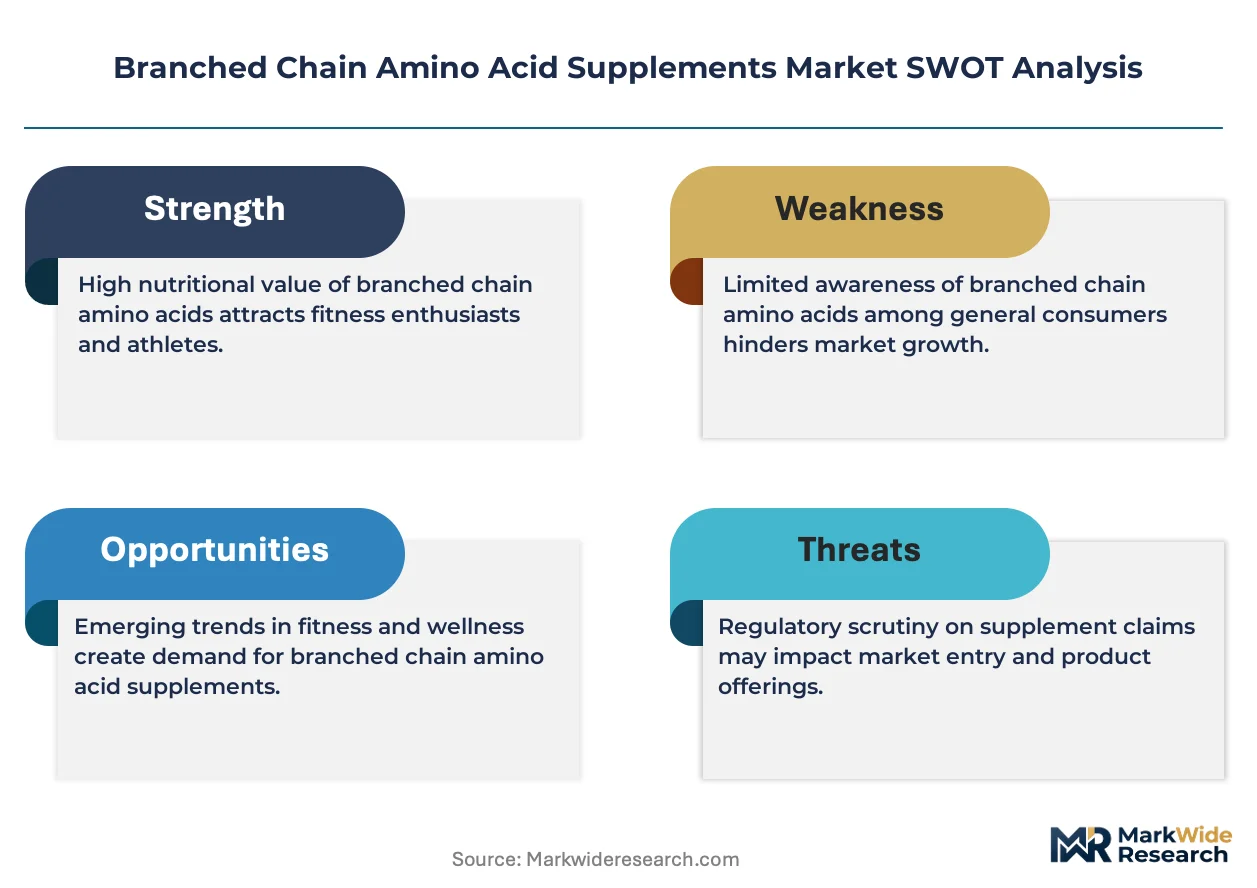
FDA Current Good Manufacturing Practice regulations and EFSA health claims frameworks shape permissible marketing language and substantiation requirements across major markets. ISO 17025 accreditation for third-party testing laboratories has become a de facto market access threshold as retailer liability concerns intensify. Stakeholders must monitor evolving positions on leucine threshold claims and novel delivery technologies that could reset efficacy expectations and reformulation cycles.
Market Dynamics
Fermentation-derived amino acid production is displacing extraction-based methods as the dominant supply architecture, compressing cost curves while forcing legacy manufacturers to requalify their ingredient sourcing under tightening FDA and EFSA purity frameworks.
Growth Catalysts
- Plant-Based Fermentation Expansion:Microbial cell culture platforms enable vegan BCAA formulations that satisfy EFSA Novel Food safety assessments while opening access to ethically constrained consumer segments previously blocked from animal-derived products.
- Recreational Fitness Democratization:Boutique studio chains and connected fitness hardware are normalizing structured training regimens among non-athlete demographics, expanding addressable demand beyond competitive sports nutrition into mainstream wellness.
- mTOR Pathway Research Deepening:Clinical substantiation of leucine threshold dosing for muscle protein synthesis is validating premium positioning strategies and supporting differentiated marketing claims under FDA structure-function guidelines.
Market Restraints
- Input Cost Volatility:Corn and sugar feedstock price swings directly pressure fermentation economics, squeezing margin pools for producers without long-term agricultural supply contracts or captive carbohydrate sourcing.
- Supply Concentration Risk:Pharmaceutical-grade amino acid production clusters heavily in Japanese and South Korean fermentation facilities, creating geographic vulnerability to regional logistics disruptions or trade policy friction.
- Regulatory Claim Friction:FDA enforcement discretion on disease-state implications limits permissible marketing language for exercise recovery and performance positioning, constraining differentiation in saturated retail channels.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Personalized dosing algorithms based on training load data are capturing recurring revenue streams while bypassing retail margin extraction and building proprietary customer datasets.
- Clinical Nutrition Adjacencies:Sarcopenia and cachexia therapeutic applications represent underdeveloped prescription-adjacent segments where pharmaceutical-grade BCAA purity standards command reimbursement-adjacent pricing.
- Synthetic Biology Convergence:Precision fermentation platforms integrating CRISPR-edited microbial strains with continuous bioprocessing are collapsing production timelines and enabling custom ratio formulations at scale.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Qualified sports nutritionists with exercise physiology credentials capable of translating clinical research into compliant product positioning command premium compensation that mid-tier brands struggle to absorb.
- Third-Party Certification Backlogs:ISO 17025 laboratory accreditation queues and NSF Certified for Sport processing delays are extending new product introduction timelines and freezing promotional calendars.
- Legacy ERP Integration Complexity:Batch record digitization and electronic quality management system upgrades required for FDA 21 CFR Part 11 compliance are consuming capital that would otherwise fund formulation innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Branched Chain Amino Acid Supplements Market |
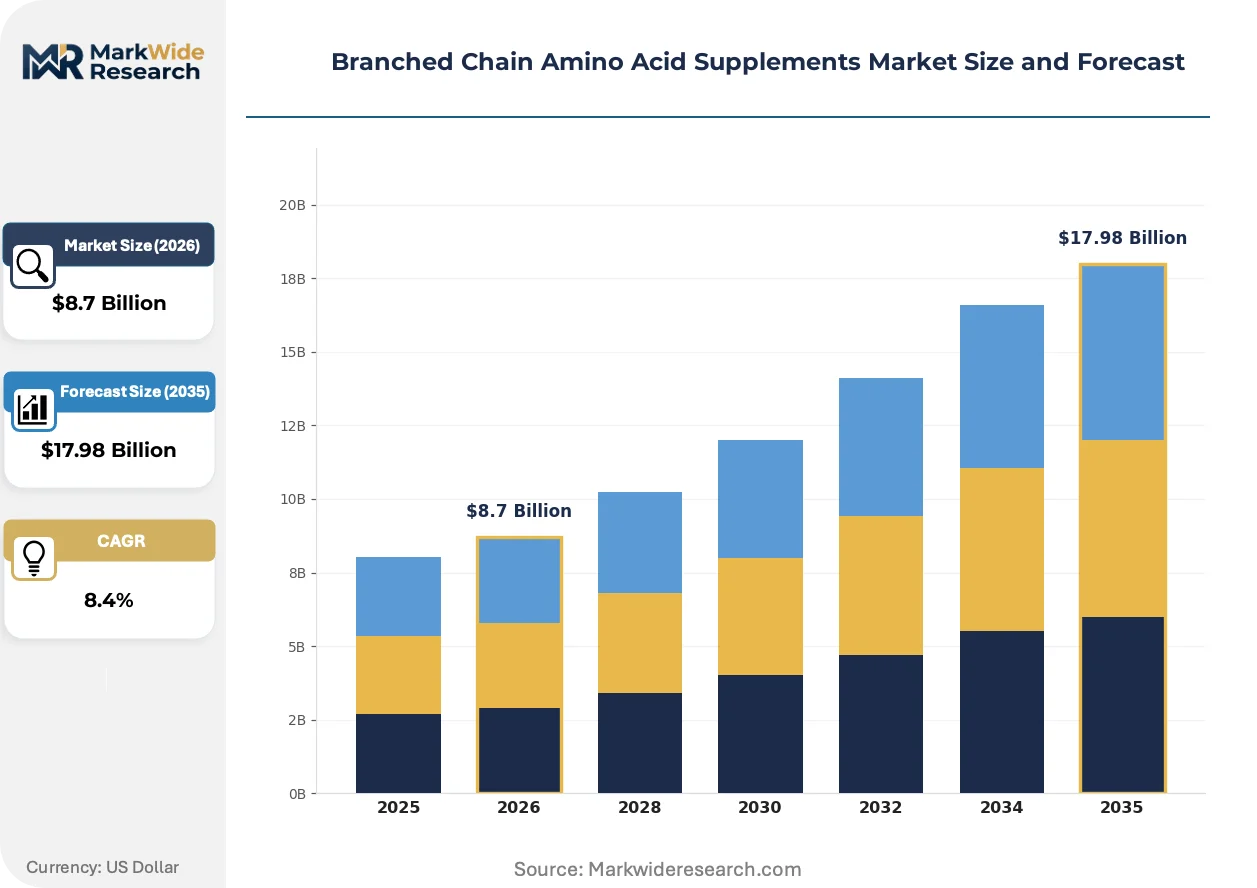
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powders, Capsules, Liquids, Tablets End User: Athletes, Bodybuilders, Fitness Enthusiasts, General Health Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Gyms Formulation: Vegan, Non-GMO, Organic, Synthetic |
| Companies Covered | Ajinomoto, Kyowa Hakko Bio, Evonik, BASF, Toray Industries, DSM, Archer Daniels Midland, Cargill, Glanbia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Branched Chain Amino Acid Supplements Market Evolving Landscape
Bioprocessing advances and regulatory digitization are restructuring how BCAA supplements are manufactured, validated, and distributed, with implications cascading from fermentation economics through retail channel configuration.
Continuous fermentation bioreactors are displacing traditional fed-batch systems as the preferred production architecture for high-purity L-leucine isolation. Contract manufacturers in South Korea and Japan are retrofitting existing pharmaceutical amino acid facilities to capture sports nutrition volume with faster turnaround times and tighter lot-to-lot consistency. This technology compression is enabling smaller brands to access pharmaceutical-grade supply tiers previously reserved for clinical nutrition applications.
EFSA health claims substantiation requirements are tightening permissible efficacy language across European markets, forcing reformulation cycles that prioritize clinical trial investment over marketing spend. The Novel Food catalog expansion for microbial biomass sources is accelerating regulatory approval pathways for next-generation vegan BCAA substrates. German and French retailers are now requiring pre-market notification documentation as a listing prerequisite, filtering out undercapitalized entrants.
Subscription-based replenishment models are capturing repeat purchase behavior previously fragmented across retail and e-commerce channels. Fitness app integrations that synchronize BCAA dosing recommendations with training calendar data are displacing static product discovery on marketplace platforms. This behavioral shift concentrates most visibly in United States metropolitan markets where connected fitness hardware penetration and direct-to-consumer logistics infrastructure have achieved critical density.
Branched Chain Amino Acid Supplements Market Segmentation
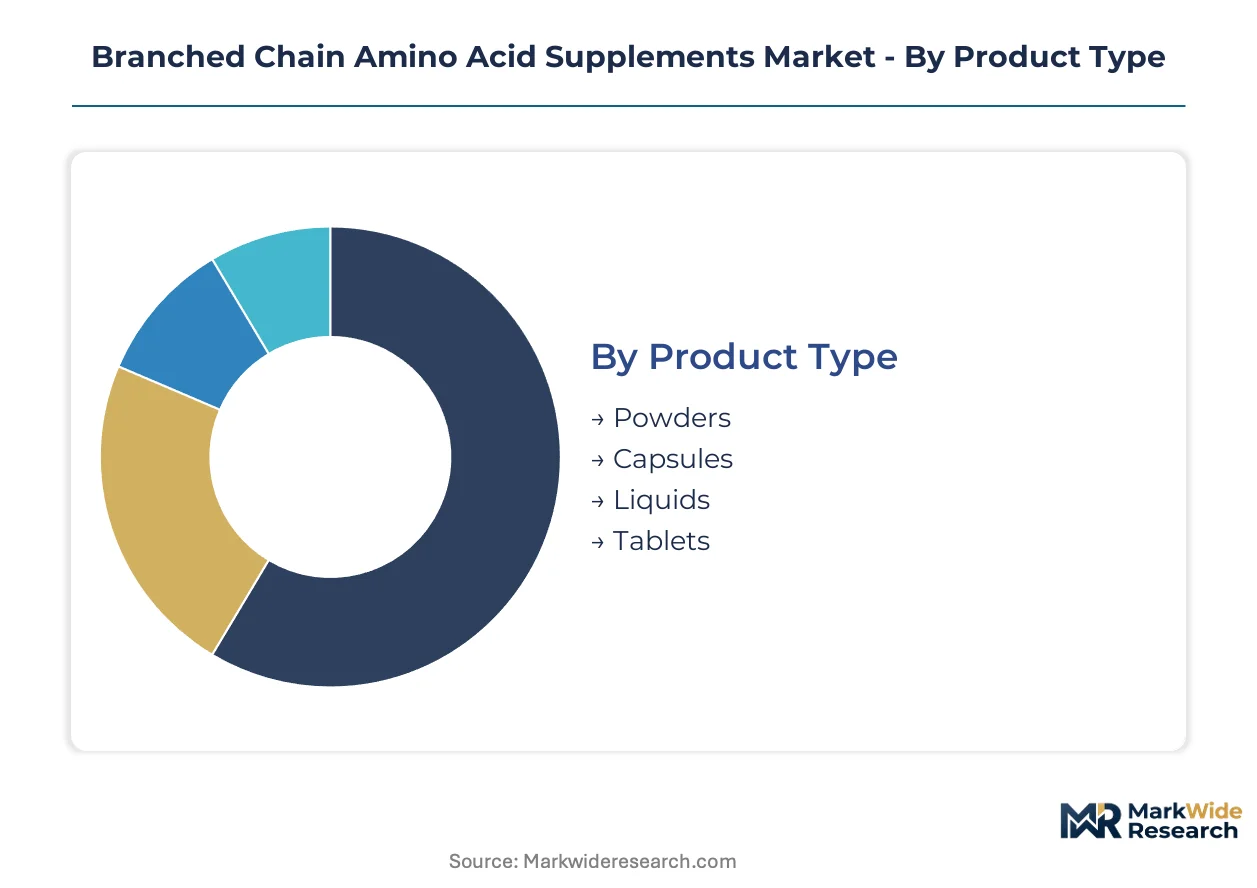
BCAA supplement segmentation reveals how formulation chemistry and channel economics create divergent margin profiles across consumer microsegments. Product format and sourcing claims increasingly determine price realization more than functional efficacy alone.
Product Type:
Powder formats face the most acute substitution pressure from ready-to-drink alternatives, while capsules and tablets compete against functional foods and fortified beverages for convenience-seeking users.
- Powders:Bulk dry formulations offering dosing flexibility from 5g to 20g servings with 2:1:1 to 4:1:1 leucine ratios. Demand concentrates in United States home-gym setups and CrossFit affiliates where cost-per-serving optimization drives repurchase behavior.
- Capsules:Pre-measured gelatin or HPMC shells delivering 500mg to 1000mg per unit for travel and workplace consumption. Japanese and South Korean commuters favor blister-pack configurations that bypass TSA liquid restrictions.
- Liquids:Ready-to-drink shots with rapid absorption claims targeting intra-workout timing windows.
- Tablets:Compressed effervescent or chewable formats competing with gummy vitamins for entry-level supplement users.
Powders anchor the volume base while liquids gain share at the steepest rate.
End User:
Cost tier stratification separates clinically validated dosing regimens from mass-market wellness positioning.
- Athletes:Competitive and collegiate performers following NSF Certified for Sport protocols with batch-tested leucine thresholds. NCAA and Olympic training facilities in California and Texas drive institutional procurement with quarterly tender cycles.
- Bodybuilders:Physique competitors prioritizing gram-scale leucine loading during contest preparation phases. IFBB Pro League athletes in Florida and Ohio sustain premium pricing for pharmaceutical-grade isolation.
- Fitness Enthusiasts:Recreational lifters and boutique studio members seeking recovery optimization without competitive drug-testing constraints.
- General Health:Aging populations targeting sarcopenia prevention through maintenance-dose regimens.
Bodybuilders command the highest per-capita spend while fitness enthusiasts expand the addressable base most rapidly.
Distribution Channel:
Margin compression intensity varies by inventory velocity and return authorization complexity.
- Online Retail:Direct-to-consumer platforms and marketplace storefronts with subscription replenishment algorithms. Amazon and iHerb fulfillment centers in Nevada and Pennsylvania enable next-day delivery to dense metropolitan zones.
- Specialty Stores:Vitamin Shoppe and GNC brick-and-mortar locations with trained staff consultation. Mall-based footprints in Texas and Florida retain higher basket values through bundled accessory sales.
- Supermarkets:Mass-market retail placement alongside protein bars and sports drinks.
- Gyms:Point-of-sale placement at Equinox, Life Time, and boutique studio reception desks.
Online retail captures the majority of volume flow while gym-based distribution delivers the steepest expansion trajectory.
Formulation:
Supply concentration in fermentation capacity creates sourcing tier differentiation.
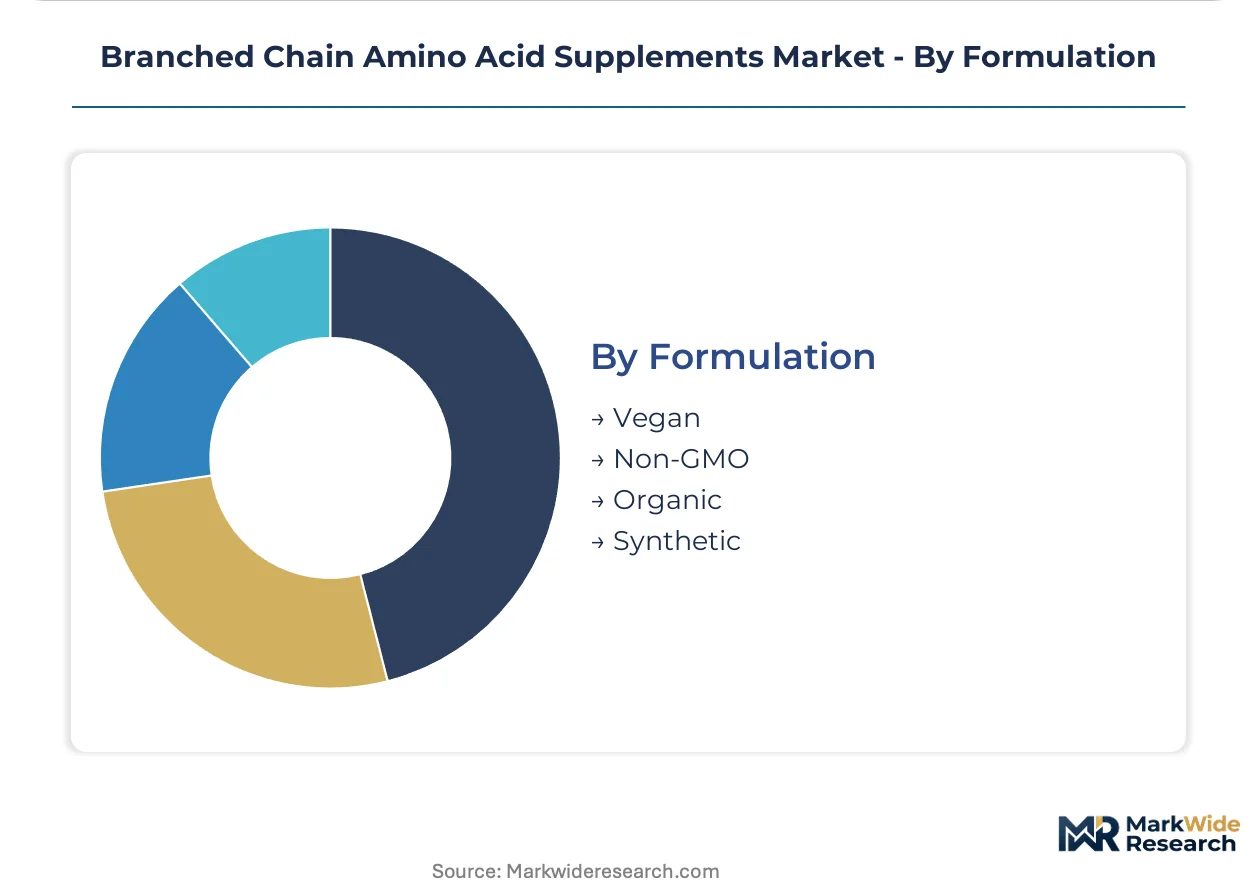
- Vegan:Microbial-derived L-leucine from corn or sugar feedstock fermentation satisfying EFSA Novel Food assessments. German and Dutch consumers drive premium positioning through ethical sourcing claims.
- Non-GMO:Identity-preserved supply chains with third-party verification through Non-GMO Project standards. United States natural channel retailers in Colorado and Oregon mandate this certification for shelf placement.
- Organic:USDA or EU organic certified substrates with restricted synthetic input profiles.
- Synthetic:Chemically synthesized racemic mixtures serving cost-sensitive mass market tiers.
Synthetic formulations retain volume leadership while vegan alternatives climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets, with the United States prioritizing direct-to-consumer convenience while Asian markets emphasize pharmaceutical-grade purity standards and European buyers drive ethical sourcing claims through regulatory pressure.
United States
Recreational fitness expansion and connected fitness hardware penetration fuel demand through subscription-based replenishment models. FDA Current Good Manufacturing Practice regulations enforce batch-level documentation and electronic quality management systems. Amazon and iHerb fulfillment centers in Nevada and Pennsylvania enable next-day delivery density that supports direct-to-consumer channel dominance.
Germany
EFSA Novel Food assessments and health claims substantiation requirements filter product entry, favoring clinically validated formulations. The country's national pharmaceutical regulator enforces strict purity documentation for sports nutrition imports. Berlin and Munich retail clusters now mandate pre-market notification documentation as a listing prerequisite, filtering undercapitalized entrants from shelf placement.
Japan
Pharmaceutical-grade amino acid fermentation capacity concentrates in Kanto and Kansai industrial corridors, supplying global clinical nutrition tiers. METI industrial standards govern microbial cell culture platform certification for export markets. Tokyo and Osaka commuter patterns sustain blister-pack capsule demand for workplace and travel consumption formats.
South Korea
Contract manufacturers retrofit pharmaceutical amino acid facilities to capture sports nutrition volume with faster turnaround times. The country's national food and drug safety administration enforces microbial biomass source registration under tightening purity frameworks. Seoul Capital Area biotech clusters pioneer continuous fermentation bioreactor deployment for high-purity L-leucine isolation.
United Kingdom
Boutique studio chains and CrossFit affiliates in London and Manchester drive powder format demand through cost-per-serving optimization. The national food standards agency aligns with EFSA frameworks on permissible efficacy language for exercise recovery claims. Southeast England distribution hubs connect to continental European supply chains while serving domestic direct-to-consumer platform growth.
Branched Chain Amino Acid Supplements Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation-derived supply chains creating vertical moats that commodity synthetics cannot replicate. Japanese and South Korean pharmaceutical-grade producers anchor the premium ingredient tier, while agricultural conglomerates and chemical multinationals compete on feedstock integration and scale economics. Three archetypes dominate: fermentation specialists with decades of amino acid platform expertise, diversified chemical players leveraging synthetic biology capabilities, and nutrition ingredient aggregators bundling BCAA into broader sports nutrition portfolios. Competitive moves concentrate on backward integration into corn and sugar feedstock sourcing, plus technology licensing partnerships that extend precision fermentation reach.
Within the fermentation specialist tier, Ajinomoto and Kyowa Hakko Bio occupy positions defined by pharmaceutical-grade purity standards and decades of microbial cell culture platform development. Evonik exemplifies the synthetic biology convergence archetype, with German engineering capabilities extending into precision fermentation infrastructure. Among diversified nutrition ingredient aggregators, Glanbia represents the bundling strategy, integrating BCAA supply into broader sports nutrition and performance ingredient portfolios.
| Leading Market Players |
|---|
| Ajinomoto |
| Kyowa Hakko Bio |
| Evonik |
| BASF |
| Toray Industries |
| DSM |
| Archer Daniels Midland |
| Cargill |
| Glanbia |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day pharmaceutical-grade amino acid lead times from Japanese and South Korean fermentation facilities concentrate pricing power among legacy producers while compressing margin pools for brands without captive supply or long-term offtake arrangements. Inventory velocity differentials between powder bulk formats and precision-dosed capsules further stratify working capital requirements across the value chain.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical-grade BCAA procurement, with spot market exposure limited to synthetic racemic mixtures serving cost-sensitive mass market tiers. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport formulations from conventional dietary supplements and unbranded commodity powders. Cost compression in synthetic routes is intensifying because agricultural feedstock volatility squeezes fermentation economics without contracted corn or sugar supply. Fitness enthusiasts exhibit highest price sensitivity, while bodybuilders and clinical nutrition buyers absorb premiums for pharmaceutical-grade purity documentation.
Supply Chain Analysis
Inventory positioning at Amazon and iHerb fulfillment centers in Nevada and Pennsylvania enables next-day delivery density that shapes downstream working capital strategies for direct-to-consumer brands. Pharmaceutical-grade amino acid production clusters heavily in Japan, South Korea, and select German synthetic biology facilities, creating geographic concentration risk for brands dependent on microbial cell culture platforms. Raw material dependencies center on corn and sugar feedstocks, gelatin or HPMC capsule shells, and pharmaceutical-grade filtration media. Tariff exposure on imported fermentation-derived inputs from East Asian trade corridors represents the dominant structural vulnerability. Distribution runs through direct-to-consumer subscription platforms, specialty retail, and gym-based point-of-sale placement in descending volume order.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fitness app ecosystem interoperability is reconfiguring customer acquisition economics, as training data integration transforms BCAA replenishment from transactional purchase to embedded platform utility.
For Market Incumbents: Secure exclusive supply agreements with Japanese and South Korean fermentation specialists before contract manufacturing capacity saturates. Lock in multi-year corn and sugar feedstock contracts to insulate margin pools from agricultural commodity volatility. Prioritize ISO 17025 laboratory accreditation investment to preempt retailer liability requirements that undercapitalized competitors cannot satisfy. For New Entrants and Emerging Players: Anchor in sarcopenia and cachexia therapeutic applications where pharmaceutical-grade purity standards command reimbursement-adjacent pricing and regulatory barriers filter incumbent competition. Target aging populations in Germany and the United Kingdom with maintenance-dose regimens positioned outside saturated athlete demographics. Pursue white-label partnerships with connected fitness hardware platforms to bypass retail margin extraction entirely. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core amino acid fermentation assets amid portfolio rationalization pressures. Five-to-ten-year viability hinges on precision fermentation platform ownership rather than synthetic chemistry legacy. Monitor EFSA Novel Food catalog expansion velocity as signal for regulatory approval pathway accessibility that would reset competitive entry costs.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Investment | CRISPR-edited microbial strains collapse L-leucine production timelines at commercial scale. |
| Direct-to-Consumer Subscription Launch | Training load algorithms from Whoop or Garmin integrations capture recurring revenue streams. |
| Clinical Nutrition Adjacency Expansion | Sarcopenia therapeutic applications unlock prescription-adjacent pricing tiers beyond sports nutrition. |
| Backward Integration into Feedstock Supply | Captive corn or sugar sourcing insulates fermentation economics from agricultural commodity swings. |
| Third-Party Certification Acceleration | NSF Certified for Sport and ISO 17025 accreditation preempt retailer liability requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA enforcement discretion memoranda, EFSA Novel Food catalog entries, and customs trade data for amino acid imports. Primary interviews engaged sports nutrition formulators, exercise physiologists, contract manufacturing procurement leads, and specialty retail category buyers. Secondary validation drew from NSF International certification databases, ISO 17025 laboratory accreditation registries, and connected fitness platform integration documentation. Bottom-up demand modeling triangulated against top-down supply capacity assessments across fermentation and synthetic production routes.
Segmentation dimensions modeled include product format, end-user archetype, distribution channel, and formulation sourcing claim across the projection horizon. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory inflection points and technology substitution curves. Forecast inputs incorporate EFSA health claims substantiation timelines, continuous fermentation bioreactor deployment rates, and fitness app ecosystem penetration metrics.
Decision-makers should treat outputs as directional under assumptions of stable FDA and EFSA regulatory frameworks and continued agricultural feedstock availability; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Arginine Supplement Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
Creatine Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Hydroxymethylbutyrate Supplement Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Active Nutrition Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
China Sports Drink Market
Sports Nutrition
Sports Nutrition Market