
 Caloric Supplements Market | 2026-2036
Caloric Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Caloric Supplements Market Insights
Direct-to-consumer online platforms is narrowing as specialty nutrition shops and health clinics reclaim patient trust through personalized consultation models. Abbott Laboratories leverages its hospital formulary relationships to sustain institutional penetration across clinical nutrition segments. Nestlé Health Science anchors its position in elderly care through dedicated medical food portfolios. Glanbia competes aggressively in sports nutrition by controlling premium whey protein sourcing from Irish dairy cooperatives.
Caloric supplements comprise concentrated macronutrient formulations—typically delivering 200–600 kcal per serving through proteins, carbohydrates, and lipids—engineered for individuals with elevated energy requirements or compromised nutritional status. Manufacturers employ spray-drying and microencapsulation to preserve bioactive stability during shelf storage and gastric transit. Protein powders and meal replacement shakes command the largest revenue pools, with weight gainers representing a faster-growing niche driven by bodybuilding and clinical recovery protocols. High-calorie drinks targeted at nursing facilities and home care patients capture above-average margins due to reimbursement-linked pricing and specialized packaging requirements.
FDA oversees medical food classification and health claim substantiation in the United States, while EFSA mandates rigorous clinical evidence for nutrient-specific claims across European markets. China's SAMR enforces GB standards for nutritional fortification and label accuracy, creating divergent compliance pathways for multinational portfolios. Stakeholders must monitor evolving reimbursement criteria for clinical nutrition and adapt formulation strategies to preempt tightening sugar and additive restrictions in major health systems.
Market Dynamics
FDA medical food classification tightening and EFSA health claim substantiation protocols are forcing manufacturers to restructure clinical evidence generation and reformulate legacy portfolios before 2026 compliance deadlines.
Growth Catalysts
- Aging demographics in Germany:Nursing facilities and home care programs are expanding reimbursement coverage for high-calorie medical nutrition, creating institutional pull-through for concentrated liquid formulations.
- EFSA nutrient-specific claim pathways:Rigorous clinical evidence requirements are paradoxically advantaging established players with dedicated research budgets, consolidating shelf access in European pharmacy channels.
- Microencapsulation advances:Spray-drying innovations are extending bioactive stability windows, enabling clean-label positioning that commands premium positioning in sports nutrition retail.
Market Restraints
- Whey protein input volatility:Irish and New Zealand dairy cooperative pricing swings compress margin predictability for premium isolate formulations.
- China SAMR GB standard divergence:Nutritional fortification and label accuracy requirements create parallel compliance costs that fragment production runs for multinational portfolios.
- Plant protein substitution threat:Pea and rice protein isolates are capturing ethical-consumer segments previously loyal to dairy-derived caloric supplements.
Strategic Opportunities
- Underpenetrated clinical recovery protocols:Post-surgical and oncology nutrition guidelines in France and Italy remain inconsistently implemented, creating white space for medical food education programs.
- Direct-to-patient subscription models:Specialty nutrition shops and health clinics are reclaiming trust through personalized consultation, opening recurring revenue streams beyond mass retail.
- Sugar reduction mandates:Health system procurement criteria in the United Kingdom and Netherlands are tightening additive restrictions, rewarding early movers with reformulated palatability profiles.
Industry Challenges
- Clinical nutrition talent scarcity:Formulation scientists with dual expertise in gastric transit stability and sensory science command premium compensation that strains mid-tier R&D budgets.
- Medical food certification timelines:FDA institutional review and EFSA scientific opinion processes extend product launch windows by 18-24 months versus conventional supplements.
- Legacy ERP integration friction:Batch-level traceability requirements for pharmaceutical-grade production strain existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caloric Supplements Market |
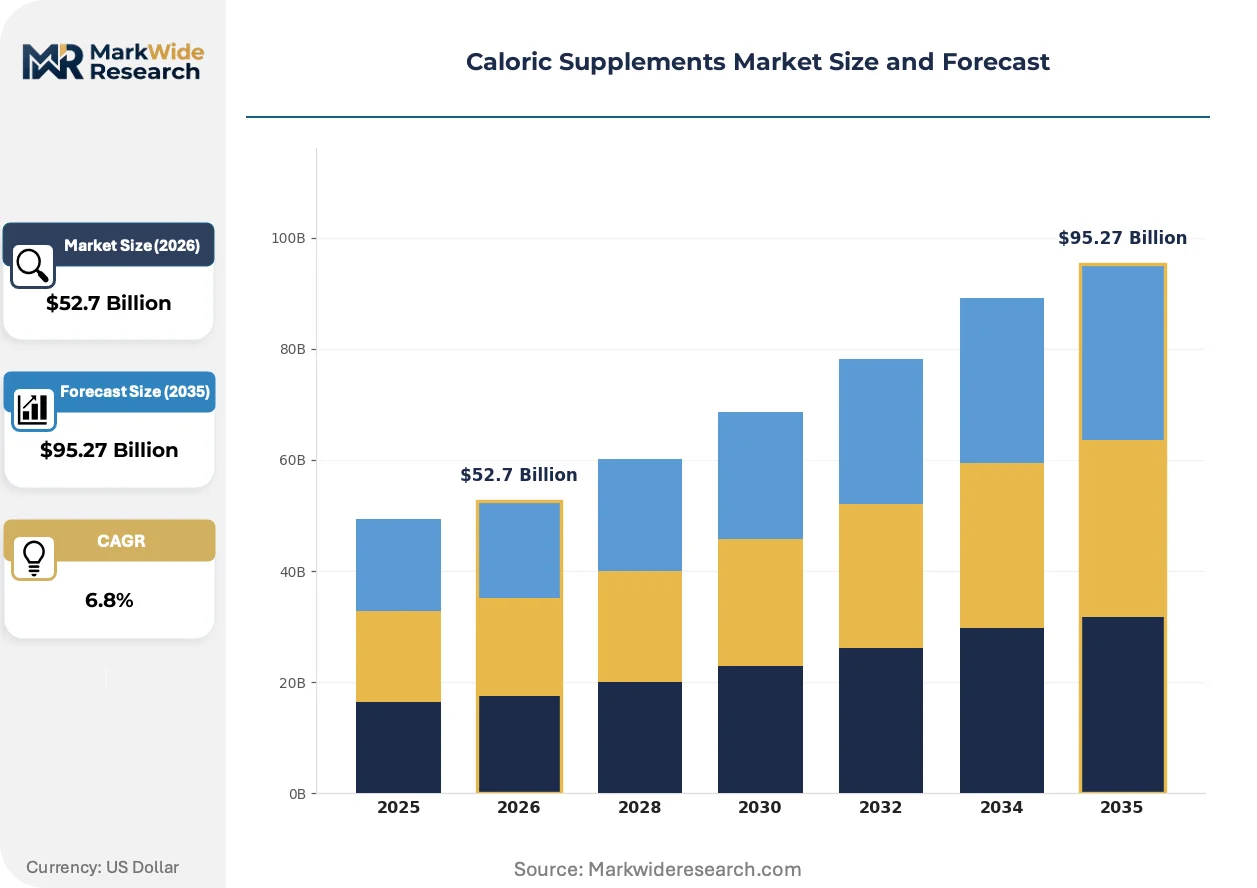
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Energy Bars, Meal Replacement Shakes, Weight Gainers, High-Calorie Drinks Application: Sports Nutrition, Clinical Nutrition, Weight Management, Elderly Care, Pediatric Support End User: Athletes, Hospitals, Fitness Centers, Nursing Facilities, Home Care Patients Distribution Channel: Retail Pharmacies, Online Stores, Specialty Nutrition Shops, Direct Sales, Health Clinics |
| Companies Covered | Abbott Laboratories, Nestlé Health Science, Glanbia, Herbalife, Amway, Bayer, Nature’s Bounty, Otsuka Holdings, Mead Johnson Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caloric Supplements Market Trends and Innovations
Formulation science and distribution economics are diverging sharply between clinical-grade medical foods and performance-oriented sports nutrition, with regulatory pressure accelerating this bifurcation.
Precision fermentation-derived proteins are achieving functional parity with dairy isolates at commercial scale. Sports nutrition brands in the United States and Germany are accelerating procurement of these inputs to secure supply independence from agricultural commodity cycles. Traditional whey concentration infrastructure is rendering obsolete for mid-market positioning as biomanufacturing costs compress.
EFSA's evolving health claims standards are mandating randomized controlled trial evidence for muscle maintenance and recovery positioning. European manufacturers are restructuring clinical affairs departments and partnering with university medical centers to generate publication-grade data. Medical food segments bear the heaviest compliance burden, with pharmacy channel access now contingent on successful scientific opinion outcomes.
Amateur athletes are consolidating purchasing through specialized nutrition shops that bundle biometric testing with personalized supplement protocols. Mass-market e-commerce platforms are losing share to these consultative channels in the United States and China. Bodybuilding and endurance communities in California and Shanghai metro areas exhibit the strongest channel migration, valuing credential-backed guidance over algorithmic recommendations.
Caloric Supplements Market Segmentation
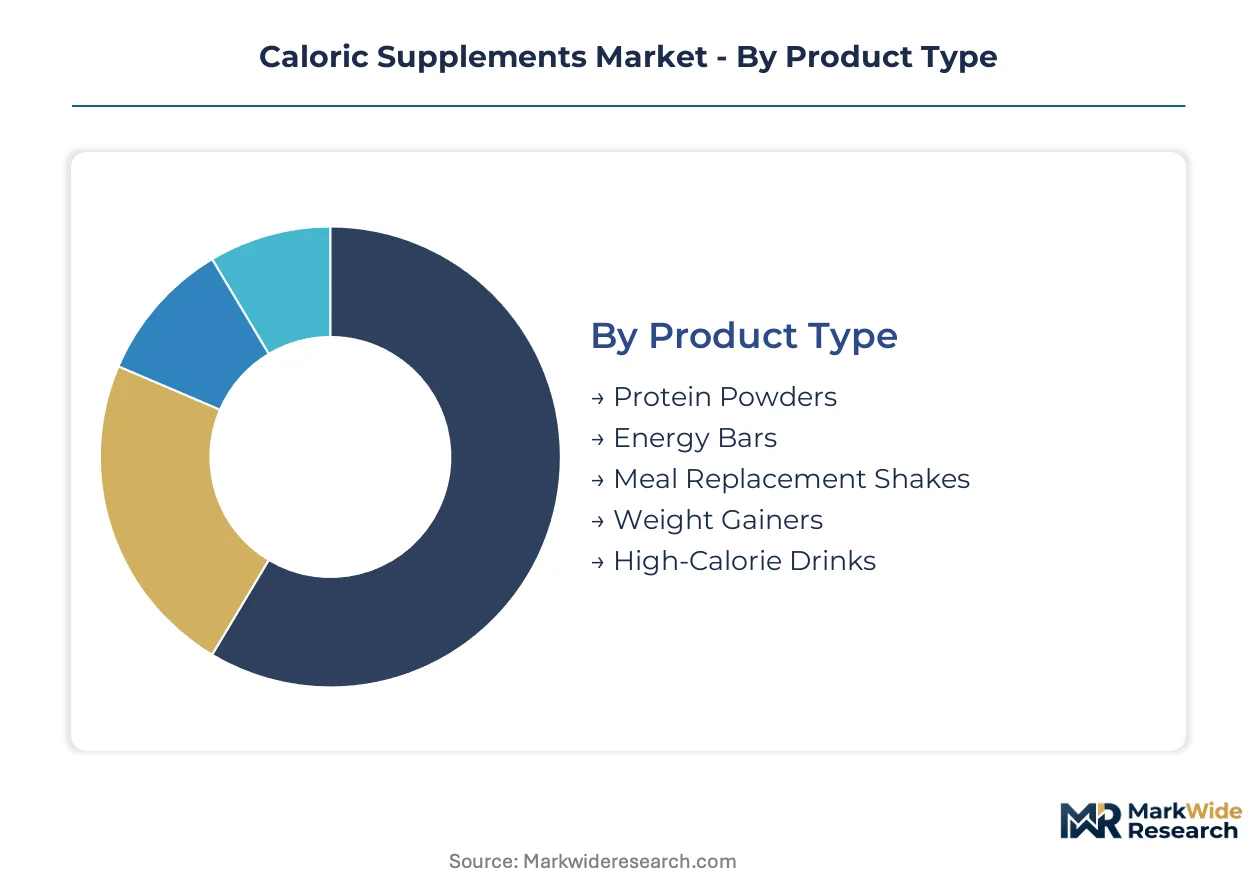
Caloric supplements fragment sharply across formulation physics and procurement context. Manufacturers optimize production runs differently for shelf-stable powders versus refrigerated clinical liquids. Channel access determines margin capture, with institutional formulary placements commanding premium pricing over mass retail.
Product Type:
Inventory velocity varies dramatically across physical formats, with ready-to-drink liquids turning fastest and bulk powders sitting longest on warehouse shelves.
- Protein Powders:Concentrated dairy or plant-derived isolates delivering 20-30g protein per 30g serving, requiring moisture-barrier packaging to prevent caking. Demand clusters in United States fitness centers and German bodybuilding communities where consumers prioritize cost-per-gram efficiency. EFSA health claim substantiation for muscle maintenance positioning drives R&D investment toward clinical-grade evidence generation.
- Meal Replacement Shakes:Complete macronutrient profiles (protein, carbohydrate, lipid, micronutrient) formulated to ISO 17025 nutritional adequacy standards. Nursing facilities in Germany and home care programs in the United States specify these for patients with chewing difficulties or appetite suppression. Reimbursement-linked procurement in institutional channels sustains above-average margins despite formulation complexity.
- Energy Bars:Compressed carbohydrate-protein matrices with shelf stability extending 12-18 months. Amateur endurance athletes in California metro areas drive recurring purchase frequency.
- Weight Gainers:Hypercaloric formulations exceeding 600 kcal per serving through maltodextrin and protein blends. Bodybuilding protocols in Shanghai and Los Angeles create concentrated demand pockets.
- High-Calorie Drinks:Liquid concentrates in aseptic packaging for dysphagia patients and post-surgical recovery. FDA medical food classification requirements extend development timelines versus conventional supplements.
Protein powders anchor the volume base while high-calorie drinks gain share at the steepest rate.
Application:
Margin structure diverges across reimbursement environment, with clinical segments capturing institutional pricing power and sports applications competing on brand equity.
- Sports Nutrition:Performance-oriented formulations targeting muscle protein synthesis and glycogen replenishment windows. Amateur and professional athletes in the United States, Germany, and China consolidate purchasing through specialty shops offering biometric consultation. Precision fermentation proteins are displacing traditional whey in premium positioning.
- Clinical Nutrition:Medical foods for compromised nutritional status including oncology, post-surgical recovery, and malabsorption syndromes. EFSA scientific opinion requirements and FDA medical food classification create 18-24 month launch delays. Hospital formulary relationships determine market access.
- Weight Management:Portion-controlled meal replacements with defined glycemic response profiles. Pharmacy channel placement in European markets requires nutrient-specific claim substantiation.
- Elderly Care:Texture-modified and flavor-optimized formulations addressing age-related hypogeusia. Germany's nursing facility expansion drives institutional procurement volume.
- Pediatric Support:Micronutrient-fortified caloric densification for failure-to-thrive protocols. Prescription requirements limit channel access to clinical settings.
Clinical nutrition commands the premium pricing tier while sports nutrition expands most quickly.
End User:
Procurement authority concentrates differently across settings, with hospital pharmacy committees exercising institutional control versus individual athlete discretionary spending.
- Hospitals:Acute care and rehabilitation facilities specifying medical foods through centralized pharmacy and therapeutics committees. FDA formulary review processes and Joint Commission standards constrain supplier switching.
- Nursing Facilities:Long-term care operators in Germany and the United States managing high-calorie drink procurement through group purchasing organizations. Reimbursement rate pressure drives volume contracting.
- Athletes:Individual and team purchasers prioritizing batch-certified formulations free from prohibited substances. INFORMED-SPORT and NSF Certified for Sport programs influence brand selection.
- Fitness Centers:Gyms and CrossFit boxes retailing branded supplement lines through pro-shop arrangements. California and Shanghai metro areas exhibit highest per-capita consumption.
- Home Care Patients:Discharged individuals or chronic condition managers purchasing through durable medical equipment suppliers or direct-to-patient subscriptions. Insurance coverage variability creates price sensitivity.
Hospitals anchor the volume base while home care patients gain share at the steepest rate.
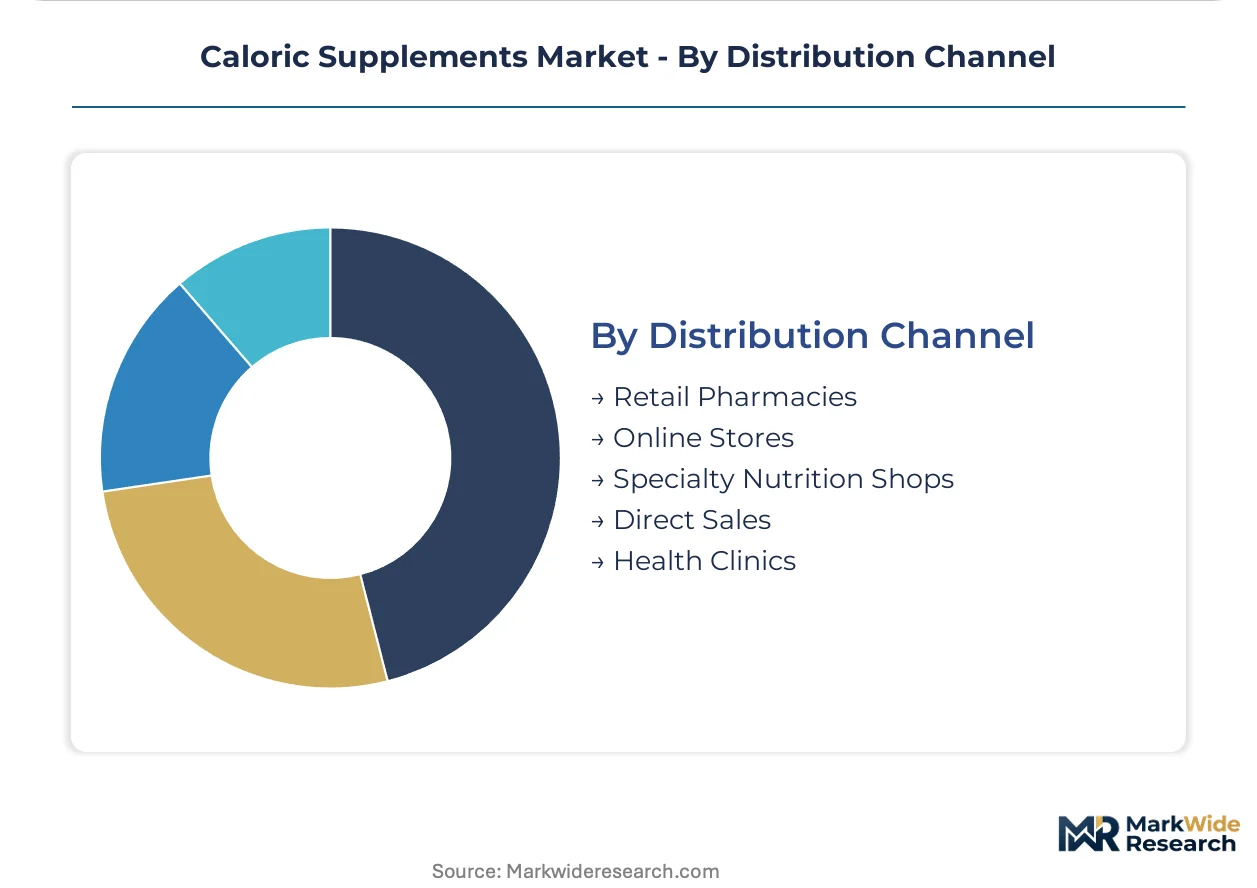
Distribution Channel:
Trust architecture determines channel performance, with credential-backed consultation reclaiming share from algorithmic e-commerce recommendations.
- Specialty Nutrition Shops:Consultative retail environments bundling biometric testing, body composition analysis, and personalized protocol design. United States and China urban clusters show strongest channel migration.
- Health Clinics:Physician and dietitian offices dispensing medical foods with professional guidance. EFSA health claim substantiation requirements reinforce pharmacy channel legitimacy.
- Retail Pharmacies:European pharmacy chains with trained staff capable of medical food counseling. Shelf access contingent on scientific opinion outcomes.
- Online Stores:Direct-to-consumer platforms facing margin compression from subscription model competitors. Amazon and Tmall dominate mass-market volume.
- Direct Sales:Manufacturer field forces calling on hospital nutrition committees and nursing facility purchasing departments. Relationship intensity sustains institutional penetration.
Online stores anchor the volume base while specialty nutrition shops gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites Europe's dominance in clinical nutrition distribution, while Shanghai Yangshan Port's bonded pharmaceutical zones anchor Asia-Pacific supply consolidation for high-calorie medical foods.
United States
Hospital formulary networks and Medicare reimbursement pathways drive institutional procurement of medical-grade caloric supplements. FDA medical food classification requirements extend product development timelines for domestic manufacturers. The Greater Boston corridor concentrates precision fermentation startups displacing traditional whey sourcing in sports nutrition formulations.
Germany
Nursing facility expansion and statutory long-term care insurance create institutional pull-through for high-calorie liquid nutrition. EFSA scientific opinion requirements for nutrient-specific claims tighten pharmacy channel access for European manufacturers. The Rhine-Ruhr industrial belt hosts spray-drying infrastructure serving both clinical and performance nutrition segments.
China
SAMR GB standards for nutritional fortification and label accuracy create divergent compliance pathways for multinational portfolios entering domestic channels. Shanghai's Zhangjiang Hi-Tech Park clusters biomanufacturing facilities producing precision fermentation-derived proteins for sports nutrition brands. Home care patient subscriptions through Tmall Health are gaining share from hospital discharge protocols.
Japan
Aging demographics and PMDA medical food frameworks sustain demand for texture-modified caloric supplements in elderly care facilities. METI's healthcare innovation programs subsidize gastric transit stability research for next-generation formulations. The Kansai region's Osaka-Kobe pharmaceutical corridor concentrates contract manufacturing for regional medical nutrition brands.
United Kingdom
NHS procurement criteria tightening sugar and additive restrictions reward early movers with reformulated palatability profiles. MHRA medical device and borderline substance classifications create regulatory friction for novel delivery formats. London's health tech cluster incubates direct-to-patient subscription platforms bypassing traditional pharmacy distribution.
Caloric Supplements Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin from bioactive sourcing and encapsulation technology. The vendor base stratifies across pharmaceutical-grade medical food manufacturers, sports nutrition brands, and dairy-derived ingredient processors. Three archetypes dominate: hospital formulary incumbents with institutional relationships, direct-to-consumer brands with subscription infrastructure, and precision fermentation startups securing supply independence from agricultural cycles. Capacity expansion in spray-drying facilities and strategic partnerships with university medical centers for clinical evidence generation represent the dominant competitive vectors.
Among diversified nutrition conglomerates, Abbott Laboratories and Nestlé Health Science occupy positions anchored by hospital formulary penetration and medical food portfolios. Glanbia exemplifies the ingredient-integrated archetype through its control of premium whey sourcing channels. These three entities represent distinct strategic postures: institutional access, clinical portfolio breadth, and upstream supply capture.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé Health Science |
| Glanbia |
| Herbalife |
| Amway |
| Bayer |
| Nature's Bounty |
| Otsuka Holdings |
| Mead Johnson Nutrition |
| Others |
Pricing and Supply Chain Analysis
Rhine-Ruhr industrial belt spray-drying capacity determines margin capture across European clinical nutrition, with facility utilization rates directly translating to pricing power in high-calorie liquid formulations. German nursing facility procurement contracts and United States hospital formulary placements anchor the premium tier, while spot-market whey protein sourcing creates volatility in sports nutrition cost structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade medical foods from mass-market sports powders and private-label economy formulations. Certification grade under FDA medical food classification and EFSA scientific opinion outcomes drive substantial price differentiation between institutional and retail channels. Cost compression in standard-tier sports nutrition is intensifying because precision fermentation proteins are achieving cost parity with dairy isolates. Home care patients exhibit highest price sensitivity due to insurance coverage variability, while hospital pharmacy committees demonstrate lowest sensitivity given reimbursement-linked procurement.
Supply Chain Analysis
Export-control restrictions on precision fermentation bioreactor technology limit capacity expansion in emerging biomanufacturing hubs, constraining supply growth for alternative protein inputs. Manufacturing concentrates in Ireland, New Zealand, and Germany for dairy-derived isolates, while China and United States facilities dominate precision fermentation scale-up. Raw material dependencies include whey protein concentrate, maltodextrin, and specialized lipid fractions for medical food applications. Single-source vulnerability in Irish dairy cooperative supply creates structural risk for premium isolate formulations. Distribution runs through institutional formulary networks for clinical nutrition and specialty nutrition shops for performance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with FDA medical food classification and EFSA health claim substantiation creating switching costs that protect incumbent positions.
For Market Incumbents: Insulate formulary relationships through dedicated clinical affairs investment generating publication-grade evidence for EFSA scientific opinions. Expand backward integration into precision fermentation capacity in Greater Boston and Shanghai Zhangjiang clusters to secure supply independence from agricultural commodity cycles. Deepen hospital nutrition committee engagement before 2026 compliance deadlines tighten.
For New Entrants and Emerging Players: Pursue direct-to-patient subscription models in United States and China urban clusters where specialty nutrition shops are reclaiming trust from mass e-commerce. Target post-surgical and oncology nutrition protocols in France and Italy where guideline implementation remains inconsistent. Anchor go-to-market strategy through biometric testing partnerships that bundle personalized consultation with product protocols.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among clinical nutrition specialists with institutional formulary placements and insurance-linked reimbursement pathways. Five-to-ten-year viability favors manufacturers with dual expertise in gastric transit stability and sensory science. Acquisition focus should center on precision fermentation startups achieving commercial-scale protein parity. Watch for inflection in United Kingdom and Netherlands sugar reduction mandate enforcement as signal for reformulation-ready portfolio premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Scientific Opinion Investment | Pharmacy channel access in European markets now requires successful scientific opinion outcomes. |
| Precision Fermentation Scale-Up | Commercial protein parity secures supply independence from Irish and New Zealand dairy cooperative pricing. |
| Direct-to-Patient Subscription Launch | Recurring revenue streams bypass mass retail margin compression in United States and China. |
| Hospital Formulary Expansion | Institutional penetration sustains above-average pricing through Medicare and statutory insurance reimbursement. |
| Sugar Reduction Reformulation | Early compliance with United Kingdom and Netherlands procurement criteria captures health system contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with formulation scientists, hospital nutrition committee directors, nursing facility procurement managers, and specialty nutrition shop operators; and secondary validation through FDA medical food registration databases, EFSA health claim opinions, SAMR GB standard filings, and hospital formulary records. Bottom-up demand modeling across patient populations and athlete segments triangulated with top-down revenue estimates from institutional procurement databases.
Forecast inputs span product type segmentation by physical format and application segmentation by clinical versus performance positioning across the projection horizon. CAGRs derive from volume-demand modeling tied to aging demographic trajectories, nursing facility expansion rates, and amateur athlete participation trends. Analysis incorporates reimbursement policy evolution in German statutory long-term care insurance and United States Medicare pathways.
Macroeconomic conditions sit as an overlay; deviation in dairy commodity pricing cycles or precision fermentation capital cost curves would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and clinical evidence generation success rates. Material shifts in EFSA health claim substantiation requirements or FDA medical food classification criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
China Sports Drink Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
United States Sports Drink Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Creatine Market
Sports Nutrition
Protein Supplements Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Weight Management Products Market
Sports Nutrition
Global Sexual Enhancement Supplements Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
South America Sports Nutrition Market