
 Cyber Security and Big Data Analytics Market | 2026-2036
Cyber Security and Big Data Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Cyber Security and Big Data Analytics Market Outlook
GDPR enforcement is rebalancing the cost-of-entry calculus for vendors serving European enterprises, forcing smaller players to invest in compliance architecture before revenue scale justifies the spend. Microsoft leverages its cloud-native security stack to anchor enterprise accounts across hybrid environments. Palo Alto Networks differentiates through platform consolidation, bundling firewall, endpoint, and analytics into unified subscription tiers. Splunk competes on data ingestion scale, sustaining dominance in security information and event management workloads for Fortune 500 security operations centers.
Cyber Security and Big Data Analytics denotes the convergence of defensive information assurance technologies with large-scale data processing architectures capable of ingesting petabyte-scale telemetry for pattern recognition and anomaly detection. These systems employ distributed computing frameworks, machine learning classifiers, and real-time stream processing to identify, correlate, and respond to multi-vector threats across heterogeneous IT estates. Managed Services leads the Service Type dimension as enterprises outsource twenty-four-hour security operations center functions to address chronic talent shortages. Threat Intelligence within the Solution category captures expanding margin pools as geopolitical cyber activity drives demand for predictive indicators. Encryption technology anchors the Technology segment amid post-quantum cryptography migration timelines set by standards bodies.
The EU AI Act and GDPR jointly shape product development roadmaps for vendors operating in European jurisdictions, mandating explainability in automated threat scoring and restricting cross-border data flows for training datasets. In the United States, NIST zero-trust architecture guidelines and SEC cyber disclosure rules are tightening accountability for publicly traded entities, directly expanding addressable demand for continuous monitoring and audit-ready reporting tools. Stakeholders must weigh the capital requirements of multi-jurisdiction compliance against the pricing power conferred by certification barriers when allocating R&D budgets across product lines.
Market Dynamics
Zero-trust architecture mandates from NIST are compressing procurement cycles across US federal agencies, forcing legacy perimeter vendors to rearchitect product roadmaps around continuous verification workflows. This regulatory pressure is reshaping competitive positioning for security analytics platforms serving government and regulated enterprise segments.
Growth Catalysts
- EU AI Act explainability mandates:Automated threat scoring systems must embed interpretable decision logic, expanding addressable demand for governance tooling across European financial services and critical infrastructure operators.
- Post-quantum cryptography migration:Standards bodies have set migration timelines for encryption algorithms, accelerating hardware refresh cycles in defense and telecommunications verticals.
- Managed security services outsourcing:Chronic talent shortages in security operations center functions are pushing mid-market enterprises toward twenty-four-hour outsourced monitoring contracts.
Market Restraints
- Specialized talent scarcity:Machine learning engineering for security applications requires hybrid skill sets combining adversarial tactics knowledge with distributed systems architecture, constraining vendor scaling velocity.
- Cross-border data flow restrictions:GDPR territoriality rules limit training dataset aggregation across European jurisdictions, fragmenting model development pipelines.
- Legacy infrastructure entrenchment:On-premises security information and event management deployments create switching friction that extends sales cycles for cloud-native alternatives.
Strategic Opportunities
- Geopolitical threat intelligence services:State-sponsored cyber activity is expanding demand for predictive indicators among energy and defense contractors in NATO member states.
- Convergence of endpoint detection with data loss prevention:Unified agent architectures reduce operational overhead for enterprises managing heterogeneous device fleets across hybrid work environments.
- SEC cyber disclosure rule compliance:Publicly traded entities require audit-ready reporting tools for material incident documentation, opening specialized SaaS segments.
Industry Challenges
- Multi-jurisdiction certification timelines:Vendors must sequence FedRAMP, StateRAMP, and EU cybersecurity certification assessments, stretching product launch schedules.
- Integration complexity with operational technology networks:Industrial control system environments require protocol-specific parsers that extend engineering resource allocation for analytics platforms targeting manufacturing verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyber Security and Big Data Analytics Market |
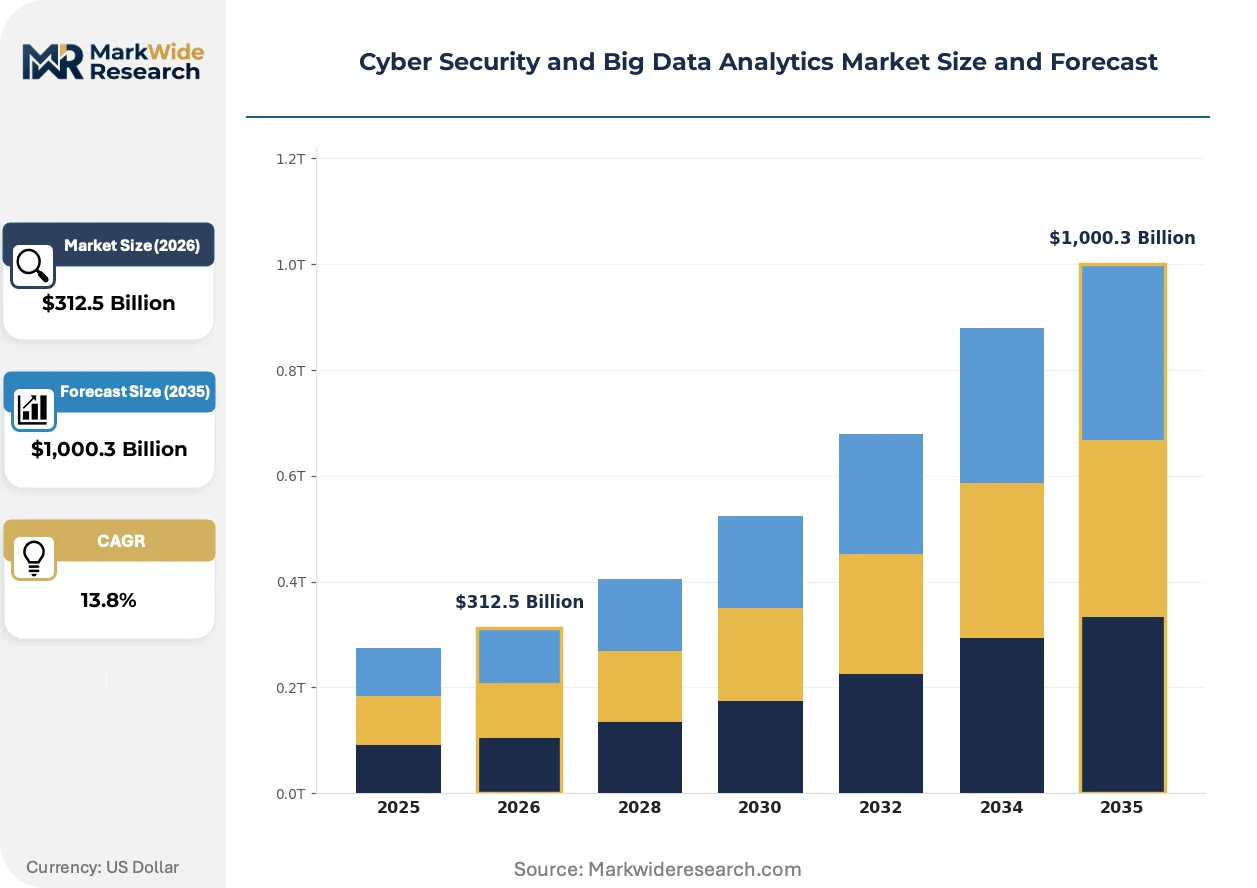
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $1,000.3 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
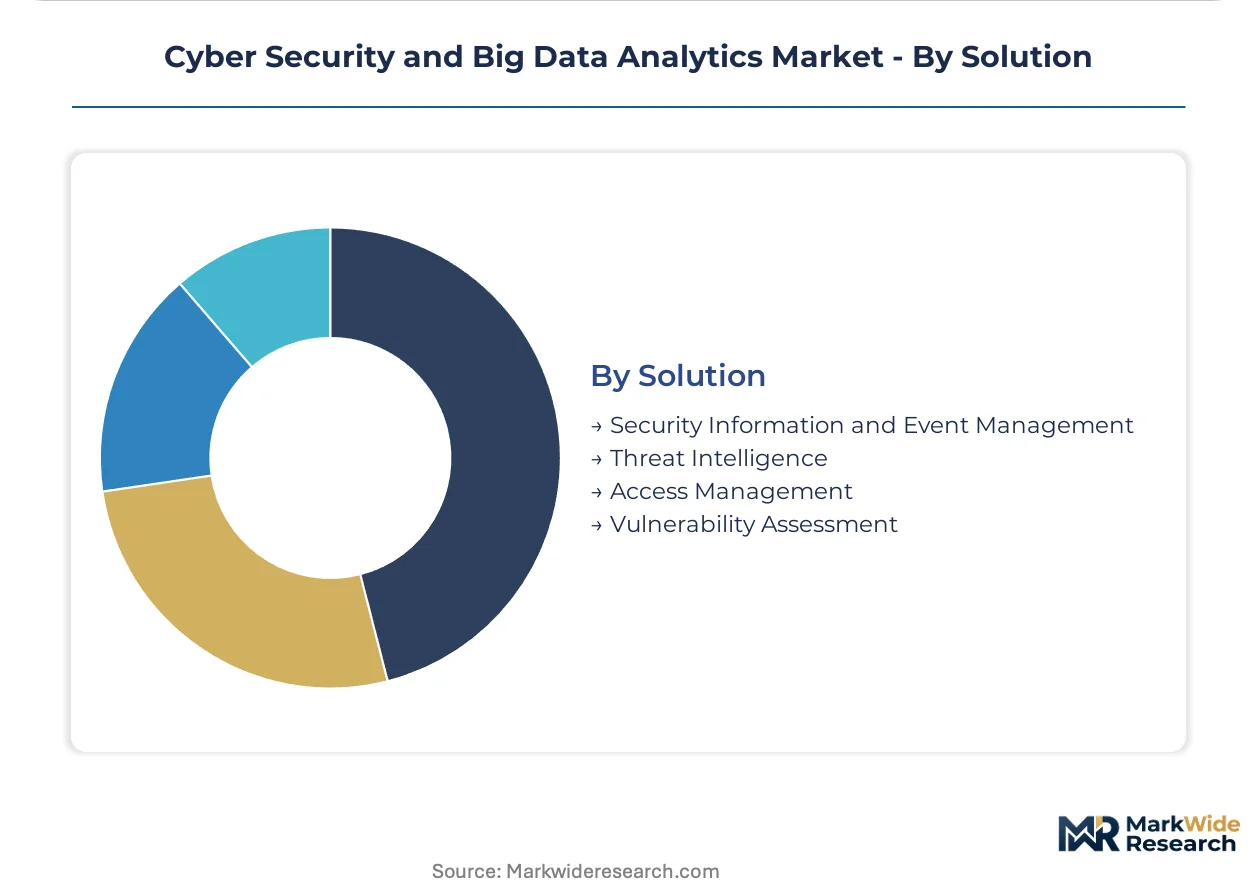
| Segmentation | Technology: Encryption, Firewall, Intrusion Detection System, Anti-virus Service Type: Consulting, Implementation, Managed Services, Audit Services End User: Financial Services, Healthcare, Government, Retail Solution: Security Information and Event Management, Threat Intelligence, Access Management, Vulnerability Assessment |
| Companies Covered | IBM, Microsoft, Oracle, Amazon Web Services, Palo Alto Networks, Splunk, Broadcom, Check Point Software Technologies, Fortinet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyber Security and Big Data Analytics Market Strategic Shifts
Real-time stream processing architectures are displacing batch-oriented security analytics, compressing threat detection latencies from hours to seconds. This shift is forcing incumbent vendors to rebuild ingestion pipelines around Apache Kafka and Flink ecosystems.
Extended detection and response platforms are overtaking siloed point solutions by correlating telemetry across endpoint, network, and identity layers. Mid-market enterprises are adopting these consolidated stacks to reduce alert fatigue and tool sprawl. The structural consequence is margin compression for standalone endpoint protection vendors lacking native network visibility.
The EU AI Act's risk classification framework for automated decision systems is mandating human-in-the-loop overrides for high-risk threat scoring applications. Financial institutions in Germany and France are rebuilding model governance workflows to satisfy national regulator interpretations of the Brussels text. This compliance burden is favoring vendors with pre-built explainability dashboards over retrofit-dependent competitors.
Security procurement committees are consolidating vendor relationships around platform subscriptions rather than best-of-breed point solutions. Large manufacturing enterprises in the US Midwest are negotiating enterprise-wide security analytics contracts that bundle managed detection response with cloud access security broker functions. This concentration pattern is visible most acutely among Fortune 500 industrials with mature zero-trust implementation timelines.
Cyber Security and Big Data Analytics Market Segmentation

Segmentation in cyber security and big data analytics reflects divergent deployment architectures across threat vectors, operational models, and compliance regimes. Understanding these divisions reveals where capital concentrates and where vendor roadmaps must adapt to heterogeneous buyer requirements.
Technology:
Technical specifications determine integration complexity and refresh cycles for defensive infrastructure.
- Encryption:Post-quantum algorithm migration is accelerating hardware replacement in defense and telecommunications verticals. NIST timelines are compressing procurement decisions for federal contractors and NATO-aligned infrastructure operators.
- Firewall:Next-generation platforms with deep packet inspection and application-layer awareness are displacing stateful inspection legacy deployments. Financial services institutions in the United States are consolidating perimeter and microsegmentation functions into unified policy engines.
- Intrusion Detection System:Network-based and host-based variants employ signature and anomaly detection methods for real-time threat identification.
- Anti-virus:Endpoint protection platforms integrate behavioral analysis and machine learning classifiers beyond traditional signature matching.
Mature deployment sits with Firewall. Newer deployment is concentrated in Encryption.
Service Type:
Cost tier stratification separates capital-intensive internal builds from recurring operational expenditures.
- Managed Services:Twenty-four-hour security operations center outsourcing addresses chronic talent scarcity in mid-market enterprises. European manufacturers are contracting specialized providers to satisfy GDPR incident response timelines without building captive teams.
- Consulting:Advisory engagements span zero-trust architecture design, compliance gap assessments, and incident response planning. United States federal agencies are accelerating procurement of NIST framework implementation support.
- Implementation:Deployment services cover platform configuration, integration with existing telemetry sources, and rule tuning for specific threat models.
- Audit Services:Independent verification of control effectiveness supports regulatory attestation requirements and cyber insurance underwriting.
Recurring revenue concentrates in Managed Services. Project-based engagement is expanding fastest in Consulting.
End User:
Application context dictates threat model sophistication and procurement authority structures.
- Financial Services:Real-time fraud detection and algorithmic trading protection demand sub-second telemetry processing. EU AI Act explainability mandates are forcing German and French institutions to rebuild automated threat scoring governance workflows.
- Government:Classified network protection and critical infrastructure defense require FedRAMP and StateRAMP certification. United States civilian agencies are consolidating procurement around zero-trust architecture mandates.
- Healthcare:HIPAA-covered entities balance patient data protection with clinical workflow continuity. Ransomware targeting of hospital networks is expanding demand for segmented backup architectures.
- Retail:Point-of-sale system protection and e-commerce fraud prevention address high-volume transaction environments with seasonal demand spikes.
Procurement maturity sits with Financial Services. Regulatory pressure is expanding fastest in Government.
Solution:
Functional architecture determines data ingestion scale and correlation complexity across telemetry sources.
- Security Information and Event Management:Centralized log aggregation and correlation engines process petabyte-scale telemetry for pattern recognition. Fortune 500 security operations centers in the United States sustain dominance of incumbent vendors through data retention commitments.
- Threat Intelligence:Predictive indicators of adversary tactics, techniques, and procedures support proactive defense posture. Geopolitical cyber activity is expanding margin pools for services targeting energy and defense contractors in NATO member states.
- Access Management:Identity verification and privilege control systems enforce least-privilege principles across hybrid cloud estates.
- Vulnerability Assessment:Continuous scanning and prioritization workflows address exposure management in dynamic infrastructure environments.
Platform consolidation sits with Security Information and Event Management. Specialized margin expansion is climbing the fastest in Threat Intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bangalore and Hyderabad concentrate Indian cybersecurity R&D activity through software technology park incentives and customs duty exemptions on imported testing equipment.
United States
Federal zero-trust procurement mandates from NIST compress sales cycles for security analytics vendors serving defense and civilian agencies. SEC cyber disclosure rules tighten accountability for publicly traded entities, expanding demand for continuous monitoring tools. Northern Virginia's Dulles Technology Corridor hosts the densest concentration of security operations centers serving federal contracts.
Germany
Industrial manufacturing conglomerates in Baden-Württemberg and Bavaria drive demand for operational technology security integration. The EU AI Act's risk classification framework mandates human-in-the-loop overrides for automated threat scoring in financial applications. Frankfurt's financial district anchors compliance-focused procurement for explainable AI governance tooling.
United Kingdom
London's insurance market and Edinburgh's fintech cluster generate specialized demand for cyber risk quantification platforms. The National Cyber Security Centre's guidance shapes procurement specifications for critical national infrastructure operators. Cambridge's technology corridor concentrates machine learning security research through university-industry partnerships.
India
Bangalore and Hyderabad special economic zones attract global security operations center outsourcing through talent density and cost arbitrage. The country's national data protection authority's evolving framework creates compliance preparation spending among IT services exporters. Mumbai's financial district drives real-time fraud detection deployments for payment system operators.
Japan
Tokyo's financial institutions and Osaka's manufacturing base sustain demand for integrated security information and event management platforms. METI's cybersecurity framework guidelines shape enterprise procurement specifications for critical infrastructure sectors. The Kansai region's industrial automation cluster generates specialized demand for operational technology protocol parsers.
Cyber Security and Big Data Analytics Market Competitive Environment
United States vendors anchor the premium platform tier; Israeli and European specialists hold differentiated positions in threat intelligence and encryption segments. Market structure concentrates around three to five integrated platform providers with comprehensive cloud-native stacks, while dozens of point-solution vendors compete on specialized detection capabilities. Strategic archetypes include cloud hyperscalers bundling security into infrastructure contracts, network security incumbents pivoting toward zero-trust architectures, and data analytics specialists leveraging ingestion scale advantages. Dominant competitive moves encompass platform consolidation through acquisition and vertical integration into managed detection response services.
Within the integrated platform tier, Microsoft and Palo Alto Networks exemplify divergent routes to enterprise account anchoring, while Splunk occupies a position representing data-scale competitive moats in security operations center workloads. These three vendors collectively illustrate how cloud-native delivery, bundled subscription packaging, and petabyte-scale telemetry processing constitute distinct but overlapping strategic positions in contested enterprise procurement cycles.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Oracle |
| Amazon Web Services |
| Palo Alto Networks |
| Splunk |
| Broadcom |
| Check Point Software Technologies |
| Fortinet |
| Others |
Value Chain & Pricing Dynamics
Machine learning engineering talent costs cascade through security analytics pricing tiers, with FedRAMP-certified implementations commanding substantial premiums over uncertified alternatives and spot-contract SOC staffing compressing margins for mid-market managed services providers.
Pricing Analysis
Short lead-time deployments for incident response retainers command 40-60% premiums over standard quarterly subscription cycles. Three-tier pricing structure across premium FedRAMP-High, standard commercial, and economy mid-market tiers separates compliance-grade offerings from volume plays. Pricing pressure stems from hyperscaler bundling of security functions into infrastructure contracts, eroding standalone tool margins. Government contractors exhibit lowest price sensitivity due to mandate-driven procurement; mid-market manufacturing shows highest sensitivity, delaying refresh cycles.
Supply Chain Analysis
Domestic-content mandates in US federal procurement are reshaping sourcing for hardware security modules and specialized SOC infrastructure toward domestic fabrication. Supply concentrates in Taiwan for advanced encryption processors, Israel for threat intelligence feeds, and the United States for cloud-native platform development. Component dependencies span specialized ASICs for post-quantum cryptography, GPU clusters for model training, and proprietary threat signature databases. Single-source vulnerability sits with Taiwanese semiconductor fabrication for high-assurance cryptographic modules. Distribution runs through direct enterprise sales for platform vendors and channel partners for point solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform vendors with sufficient R&D scale to absorb multi-jurisdiction compliance costs, forcing point-solution specialists toward acquisition or niche retreat.
For Market Incumbents: To counter hyperscaler bundling of security into infrastructure contracts, anchor enterprise accounts through zero-trust architecture consulting engagements that embed platform subscriptions. Pursue backward integration into managed detection response services to capture recurring revenue streams and deepen customer switching costs. For New Entrants and Emerging Players: EU AI Act explainability mandates in Germany and France open a window for governance-tooling specialists without legacy retrofit burdens. Target mid-market European manufacturers lacking captive compliance teams. Lead with pre-built explainability dashboards rather than detection algorithms. For Investors and Strategic Acquirers: FedRAMP authorization backlogs clearing for cloud-native platforms is the leading indicator that procurement velocity will accelerate for authorized vendors. Five-to-ten-year viability favors specialists with demonstrated certification velocity over undifferentiated detection engines. Watch NIST zero-trust implementation timeline announcements as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Consolidation | Bundling SIEM, XDR, and identity functions reduces enterprise tool sprawl and procurement friction. |
| Managed Detection Response Expansion | Twenty-four-hour SOC outsourcing addresses chronic talent scarcity in mid-market verticals. |
| Post-Quantum Cryptography Migration | NIST timelines accelerate hardware refresh cycles for defense and telecommunications infrastructure. |
| Regulatory Compliance Tooling | EU AI Act explainability mandates expand addressable demand for governance workflows in financial services. |
| Threat Intelligence Specialization | Geopolitical cyber activity drives predictive indicator demand among NATO-aligned energy contractors. |
Study Parameters
Document review covered SEC cyber disclosure filings, EU regulatory texts, and NIST framework publications, complemented by interviews with CISOs at Fortune 500 industrials, federal procurement officers, managed security services executives, and threat intelligence analysts. Secondary sources included hyperscaler capex disclosures, FedRAMP authorization databases, and customs records for cryptographic hardware trade flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Model outputs span value projections across the analysis window, with segmentation by technology type, service model, end-use vertical, and deployment architecture. CAGRs derive from regression analysis of historical procurement velocity against regulatory mandate timelines. Industry-specific inputs incorporate FedRAMP authorization queue depths, EU AI Act national implementation variance, and zero-trust architecture adoption curves.
The model assumes a particular technology adoption path; alternative pathways for quantum-resistant cryptography standardization would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement intensity and federal procurement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
ASEAN Cyber Security Market
Cybersecurity
Nigeria Cybersecurity Market
Cybersecurity
Global Automated Breach and Attack Simulation (BAS) Market
Cybersecurity
Global Cyber Situational Awareness Market
Cybersecurity
Cloud-Based Database Security Market
Cybersecurity
Server Security Market
Cybersecurity
Europe Data Exfiltration Market
Cybersecurity
Open RAN Security Market
Cybersecurity
Morocco Cybersecurity Market
Cybersecurity
Micro Segmentation Technology Market
Cybersecurity
Home Wi-Fi Security Solutions Market
Cybersecurity
Network Security Market
Cybersecurity
Bahrain Cybersecurity Market
Cybersecurity
Global Digital Forensic Laboratory As a Service Market
Cybersecurity
Web Application Firewall Market
Cybersecurity
Latin America IoT Security Market