
 Endpoint Protection Platforms (EPP) Market | 2026-2036
Endpoint Protection Platforms (EPP) Market Size, Share, and Industry Trends Forecast 2026-2036
Endpoint Protection Platforms (EPP) Market Foresight
The gap between premium AI-native EPP suites and commodity antivirus bundles is repositioning how buyers evaluate total cost of ownership versus threat detection efficacy. CrowdStrike Falcon leverages cloud-native architecture to sustain real-time telemetry advantages across distributed endpoints. Microsoft Defender for Endpoint anchors enterprise accounts through native Windows integration and bundling economics. Palo Alto Networks Cortex differentiates via tight coupling with network security stacks, occupying the converged SASE-EPP intersection.
Endpoint Protection Platforms combine agent-based software deployed on laptops, servers, and mobile devices with centralized policy engines that enforce malware prevention, exploit blocking, and device control at the network edge, typically requiring kernel-level drivers for behavioral monitoring and sub-100-millisecond response latency. Cloud-based deployment now leads new installations as organizations retire on-premises management servers, while machine learning-infused detection layers command premium pricing against legacy signature-based antivirus segments. Behavioral analysis capabilities are gaining fastest in healthcare institutions and government agencies facing advanced persistent threats, though integration services still capture significant margin pools where heterogeneous tool consolidation demands custom engineering.
The US Federal Risk and Authorization Management Program and HIPAA security rules shape product requirements for government and healthcare buyers, mandating continuous monitoring and audit-grade logging that elevates baseline feature sets. EU NIS2 and the Cyber Resilience Act expand liability onto platform vendors for unpatched vulnerabilities, accelerating European demand for automated remediation. Stakeholders must weigh whether to consolidate on single-vendor XDR stacks or preserve best-of-breed EPP autonomy as detection engineering talent scarcity intensifies.
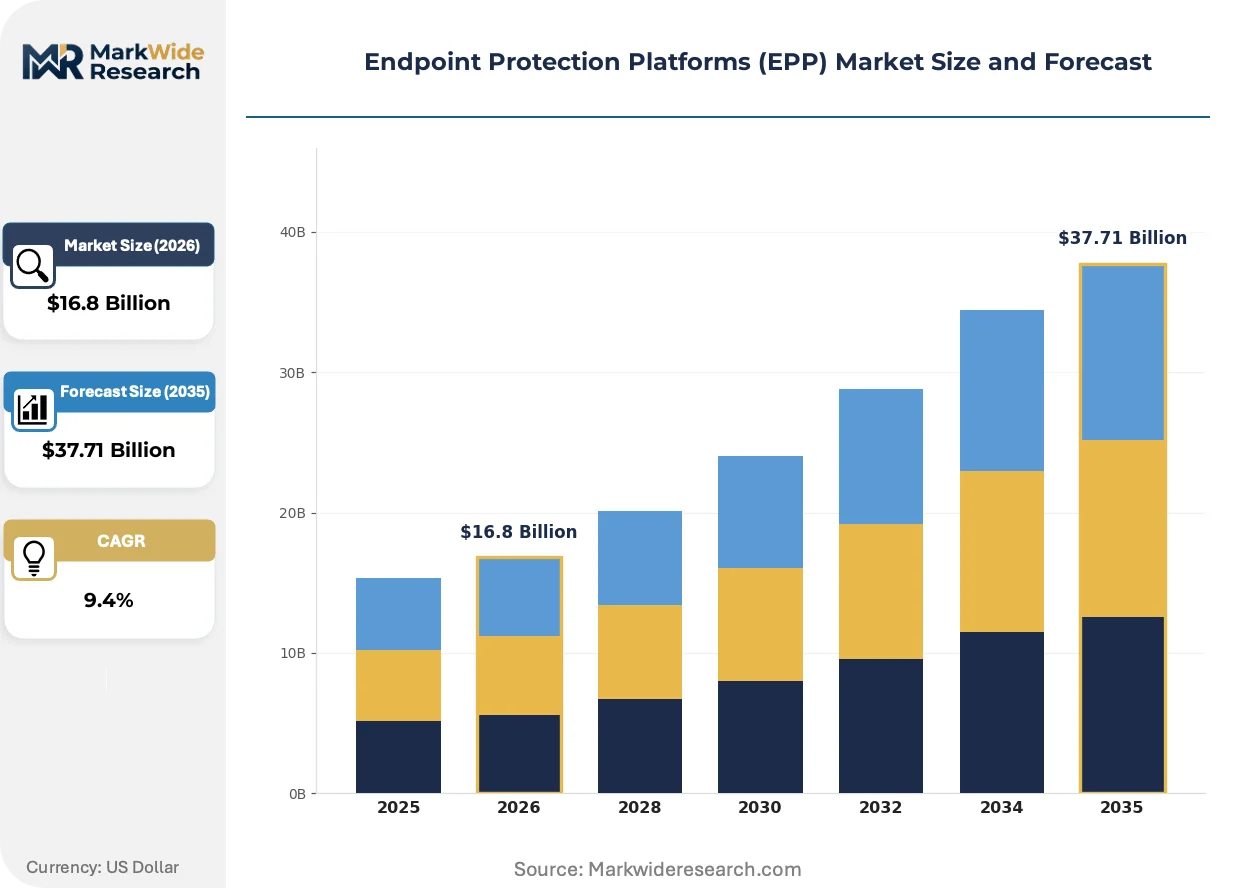
Market Dynamics
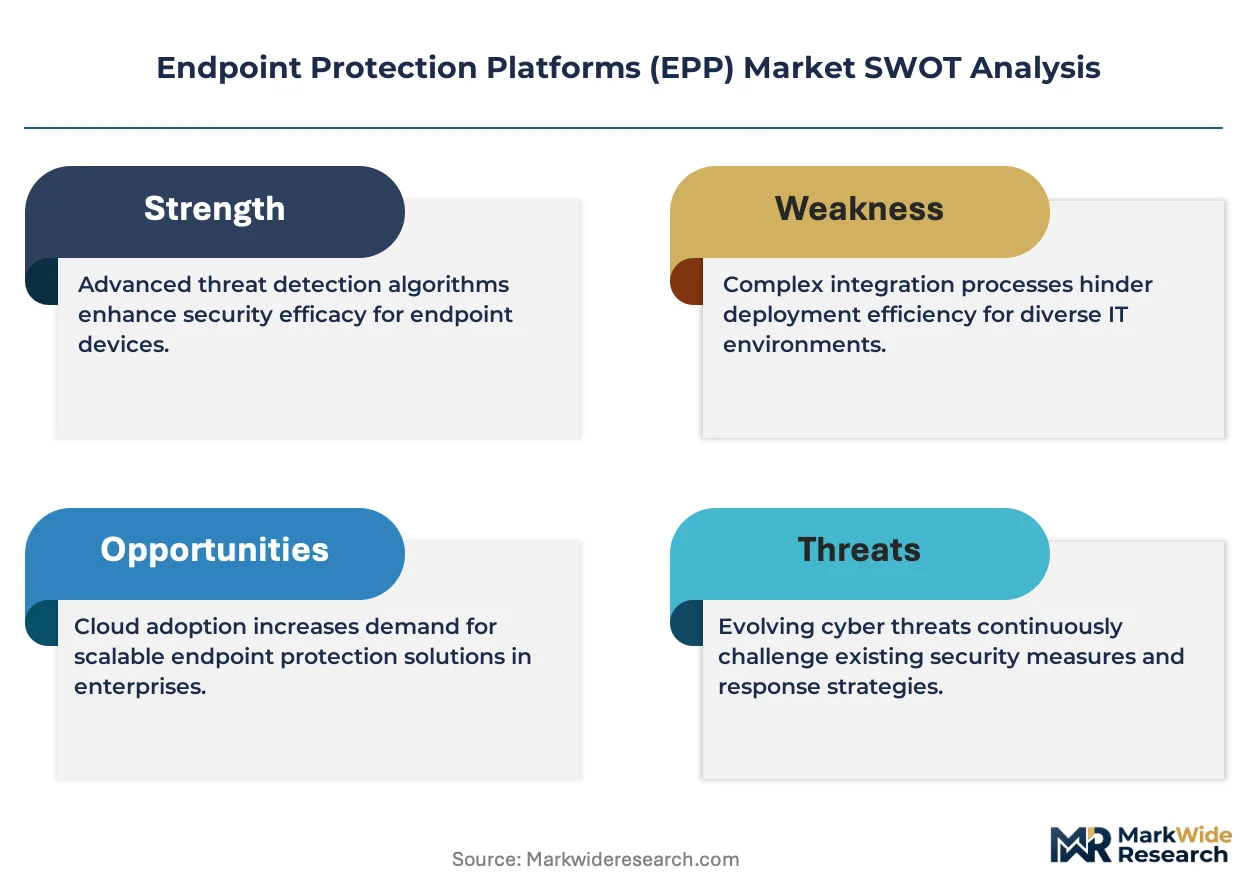
Cloud-native telemetry architectures are compressing the competitive moat between premium EPP suites and legacy antivirus vendors, forcing buyers to re-evaluate detection efficacy against total cost of ownership. The EU AI Act and NIS2 Directive are accelerating automated remediation requirements across European critical infrastructure operators.
Growth Catalysts
- EU AI Act enforcement:Critical infrastructure operators in Germany and France face mandatory continuous monitoring mandates, expanding procurement of machine learning-infused detection layers.
- Automotive manufacturing clusters:Stuttgart and Wolfsburg industrial zones drive enterprise-grade platform adoption for securing distributed operational technology endpoints.
- Behavioral analysis capabilities:Healthcare institutions facing advanced persistent threats are upgrading from signature-based systems to kernel-level behavioral monitoring solutions.
Market Restraints
- Detection engineering talent scarcity:The shortage of specialists capable of tuning machine learning models and writing behavioral detection rules constrains vendor scaling and inflates implementation costs.
- Kernel driver certification friction:Microsoft Windows driver signature requirements and Apple macOS notarization delays extend product release cycles and increase compliance overhead.
- Legacy antivirus substitution pressure:Commodity bundled solutions from operating system vendors displace standalone EPP spending in price-sensitive mid-market accounts.
Strategic Opportunities
- Converged SASE-EPP integration:Vendors coupling endpoint telemetry with secure access service edge networking capture cross-sell revenue from enterprises consolidating security stacks.
- Automated remediation mandates:The EU Cyber Resilience Act creates liability for unpatched vulnerabilities, driving demand for autonomous response capabilities among European manufacturers.
- US Federal authorization pathways:FedRAMP and HIPAA security rule compliance open federal healthcare and civilian agency procurement channels for audit-grade logging platforms.
Industry Challenges
- Heterogeneous tool consolidation complexity:Enterprises operating mixed endpoint estates require custom engineering to integrate EPP with existing SIEM and SOAR investments.
- Sub-100-millisecond latency requirements:Real-time behavioral blocking demands kernel-level optimization across diverse operating system versions and hardware configurations.
- XDR stack consolidation pressure:Buyers weighing single-vendor extended detection and response suites against best-of-breed EPP autonomy complicate vendor retention strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endpoint Protection Platforms (EPP) Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $37.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Small Businesses, Enterprises, Government, Healthcare Institutions Technology: Machine Learning, Behavioral Analysis, Threat Intelligence, Antivirus Service Type: Consulting, Integration, Support, Training |
| Companies Covered | Palo Alto Networks Cortex, Trend Micro Vision One, CrowdStrike Falcon, Elastic Security, Acronis Cyber Protect Cloud, SentinelOne Singularity, Sophos Intercept X, Cisco Secure Endpoint, Microsoft Defender for Endpoint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endpoint Protection Platforms (EPP) Market Shifts & Advancements
Agentless endpoint telemetry and extended detection and response convergence are restructuring how security platforms capture and correlate threat intelligence across distributed environments. Vendors are racing to embed autonomous response capabilities before regulatory deadlines compress implementation windows.
Extended detection and response (XDR) is consolidating standalone EPP, endpoint detection and response, and network telemetry into unified data lakes with cross-domain correlation engines. Financial services firms with distributed trading floors are adopting these integrated suites to reduce alert fatigue and accelerate mean-time-to-response. The architecture is compressing vendor margins in the standalone EPP segment while elevating data platform specialists.
The EU Cyber Resilience Act imposes strict vulnerability disclosure and automated patch mandates on software vendors supplying critical infrastructure operators. Manufacturers of industrial control systems must now certify endpoint protection components meet baseline security requirements before market entry. German automotive suppliers are restructuring procurement specifications to prioritize vendors with EU-established security operations centers.
Enterprise security teams are compressing vendor consolidation cycles from multi-year best-of-breed experiments toward single-platform commitments. CISOs at US healthcare systems facing HIPAA audit scrutiny favor integrated suites with native audit-grade logging over point solutions requiring custom integration. The preference shift is visible most acutely in hospital networks with limited detection engineering headcount.
Endpoint Protection Platforms (EPP) Market Segmentation
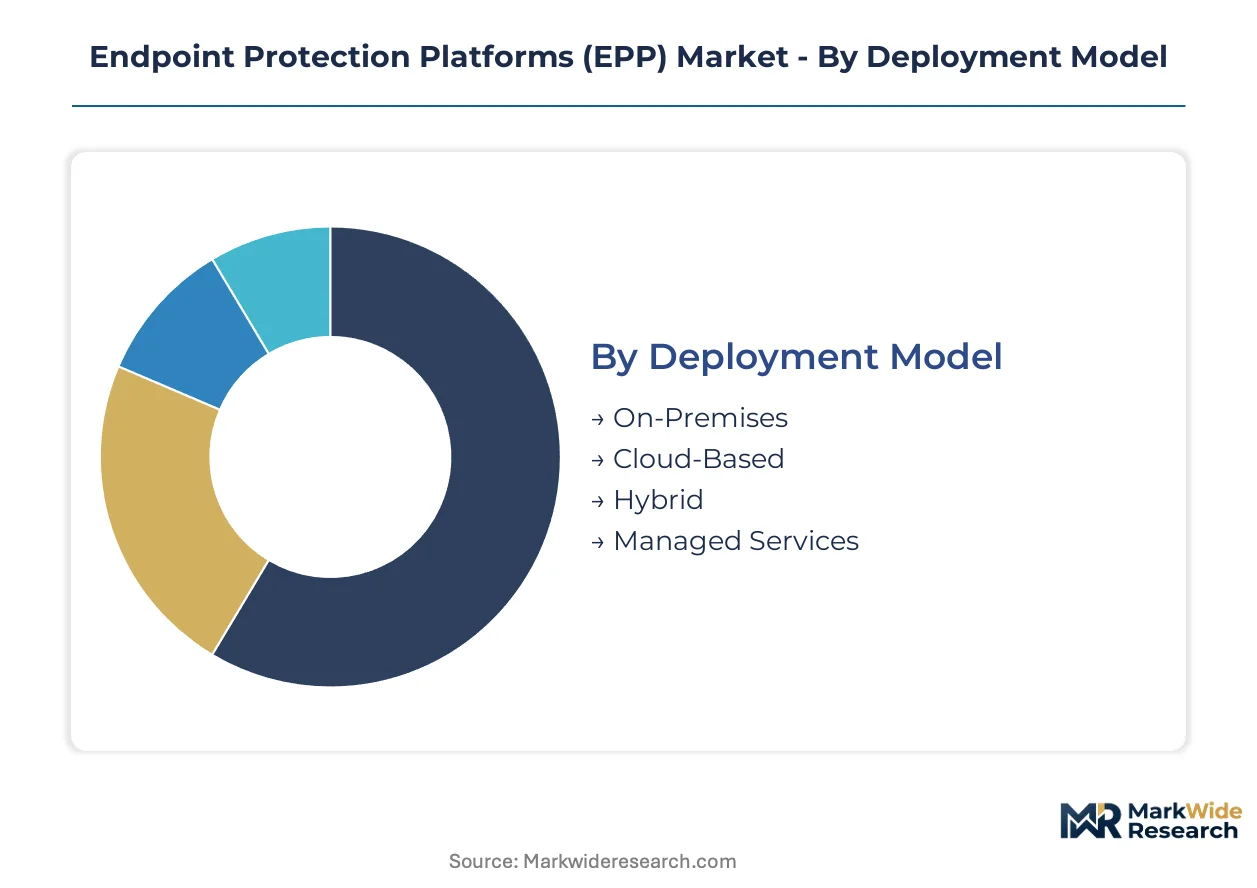
Endpoint Protection Platforms fragment across four critical dimensions that determine procurement economics and technical architecture. Deployment models dictate infrastructure overhead, while technology layers separate premium detection capabilities from commodity prevention. Understanding these splits reveals where vendor margins concentrate and where substitution pressure looms.
Deployment Model:
Supply concentration in cloud infrastructure is compressing delivery economics and reshaping how vendors capture recurring revenue versus perpetual license streams.
- Cloud-Based:Cloud-native architectures stream real-time telemetry through centralized policy engines without on-premises management servers. German automotive clusters in Stuttgart and Wolfsburg drive enterprise-grade procurement for securing distributed operational technology endpoints. Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
- On-Premises:Self-hosted management servers retain air-gapped environments in defense and classified government facilities where data sovereignty mandates prohibit external connectivity. US Federal Risk and Authorization Management Program compliance requirements sustain niche demand despite shrinking new installations. Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
- Hybrid:Split architectures preserve sensitive workloads on-premises while extending cloud policy management to distributed endpoints. Financial services firms with distributed trading floors adopt this model to balance latency requirements with centralized visibility.
- Managed Services:Outsourced security operations centers assume endpoint monitoring and response responsibilities, capturing mid-market accounts lacking detection engineering headcount. EU NIS2 Directive mandates are accelerating procurement among European critical infrastructure operators.
Cloud delivery dominates new installations, though hybrid retention reflects persistent sovereignty constraints in regulated sectors.
End User:
Procurement sophistication varies sharply across buyer types, with compliance mandates and threat exposure determining willingness to pay for machine learning-infused detection layers.
- Enterprises:Large organizations operate heterogeneous endpoint estates requiring kernel-level behavioral monitoring across Windows, macOS, and Linux variants. HIPAA security rules and FedRAMP authorization pathways shape product requirements for US healthcare and federal buyers, mandating continuous monitoring and audit-grade logging that elevates baseline feature sets.
- Government:National security and civilian agencies impose strict certification requirements including Common Criteria evaluation and country-specific cryptographic modules. The EU AI Act enforcement timeline is accelerating automated remediation procurement among European critical infrastructure operators.
- Healthcare Institutions:Hospital networks facing advanced persistent threats upgrade from signature-based systems to behavioral analysis capabilities, though limited security staffing favors integrated suites over point solutions requiring custom engineering.
- Small Businesses:Price-sensitive accounts confront commodity bundled solutions from operating system vendors that displace standalone EPP spending, compressing addressable market for premium vendors.
Enterprise procurement anchors vendor revenue, while healthcare institutions present the steepest expansion trajectory as HIPAA audit scrutiny intensifies.
Technology:
Capability stratification separates premium pricing tiers, with machine learning and behavioral layers commanding multiples over legacy signature-based prevention.
- Behavioral Analysis:Kernel-level drivers monitor process execution chains and memory anomalies to block zero-day exploits without prior signature knowledge. Sub-100-millisecond response latency requirements demand optimization across diverse operating system versions and hardware configurations.
- Machine Learning:Statistical models trained on threat telemetry identify polymorphic malware variants that evade static detection, sustaining real-time efficacy advantages across distributed endpoints.
- Threat Intelligence:External feeds of indicators of compromise enrich local detection with adversary campaign context, though integration complexity favors vendors with native data platform investments.
- Antivirus:Signature-based file scanning retains baseline prevention role but faces margin compression as operating system vendors bundle equivalent functionality at no incremental cost.
Behavioral analysis captures premium positioning today, while machine learning models face talent scarcity constraints on vendor scaling.
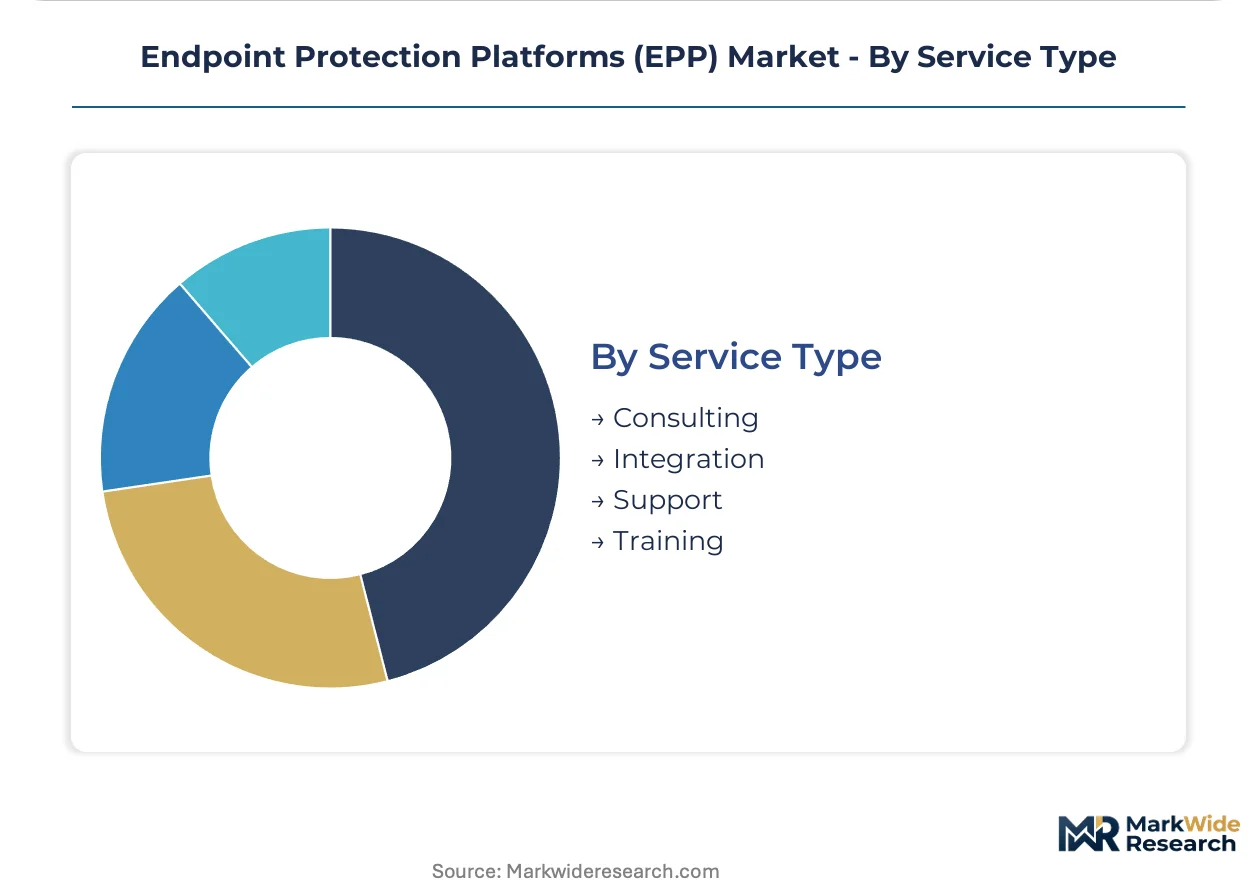
Service Type:
Professional services margins reflect integration complexity where heterogeneous tool consolidation demands custom engineering beyond standard product deployment.
- Integration:Custom engineering connects EPP telemetry with existing SIEM and SOAR investments, capturing significant margin pools in enterprise accounts with mixed security estates. XDR stack consolidation pressure complicates vendor retention strategies as buyers weigh single-vendor suites against best-of-breed autonomy.
- Consulting:Advisory engagements assess endpoint security posture and design migration paths from legacy antivirus, particularly in European manufacturing restructuring procurement specifications around EU Cyber Resilience Act compliance.
- Support:Technical assistance and escalation management sustain operational continuity, with tiered response commitments differentiating enterprise contracts.
- Training:Detection engineering skill development addresses talent scarcity constraining vendor scaling and inflating implementation costs.
Integration services dominate services revenue, with consulting expanding most quickly alongside regulatory compliance deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cybersecurity engineering talent concentrates disproportionately in the United States, Germany, and Israel, anchoring platform development and enterprise procurement gravity. National regulatory frameworks now dictate where vendors establish security operations centers and compliance certifications. Industrial manufacturing clusters in Stuttgart, Detroit, and Shenzhen generate concentrated endpoint protection demand.
United States
Federal healthcare systems and financial services firms drive enterprise-grade procurement for audit-grade logging platforms. HIPAA security rules and FedRAMP authorization pathways mandate continuous monitoring capabilities that elevate baseline feature requirements. Hospital networks across the Midwest and Southeast favor integrated suites over point solutions.
Germany
Automotive suppliers in Stuttgart and Wolfsburg industrial zones procure kernel-level behavioral monitoring for operational technology endpoints. EU NIS2 Directive and Cyber Resilience Act enforcement accelerate automated remediation procurement among critical infrastructure operators. Manufacturing clusters now prioritize vendors with EU-established security operations centers.
United Kingdom
Financial services firms in the City of London and Canary Wharf adopt converged SASE-EPP suites to secure distributed trading floors. UK regulatory frameworks align with EU baseline requirements post-Brexit, maintaining stringent vulnerability disclosure mandates. NHS Digital procurement specifications favor cloud-native architectures with native audit capabilities.
Japan
Automotive and electronics manufacturers in the Nagoya and Osaka industrial corridors drive demand for sub-100-millisecond response latency solutions. METI cybersecurity guidelines emphasize supply chain resilience for critical infrastructure operators. Tokyo-based financial institutions consolidate on platforms with native cross-domain correlation engines.
India
IT services exporters in Bangalore and Hyderabad expand managed security services partnerships to address detection engineering talent scarcity. RBI cybersecurity guidelines impose baseline endpoint protection requirements on financial institutions. Mumbai-based banking consortiums drive procurement of machine learning-infused detection layers.
Endpoint Protection Platforms (EPP) Market Competitive Landscape
Capital-heavy platform vendors compete with asset-light security software specialists, creating tiered competitive dynamics. The vendor base stratifies between cloud-native architects, legacy antivirus incumbents, and network security convergers. Three archetypes dominate: telemetry platform specialists, operating system bundlers, and SASE-EPP integrators. Consolidation pressure intensifies through strategic partnerships and portfolio diversification moves.
Within the cloud-native telemetry tier, CrowdStrike Falcon and SentinelOne Singularity exemplify architectures optimized for real-time behavioral monitoring across distributed endpoints. Palo Alto Networks Cortex occupies the converged SASE-EPP intersection, anchoring network-security integration strategies. Microsoft Defender for Endpoint represents operating system bundling economics, capturing enterprise accounts through native Windows integration.
| Leading Market Players |
|---|
| Palo Alto Networks Cortex |
| Trend Micro Vision One |
| CrowdStrike Falcon |
| Elastic Security |
| Acronis Cyber Protect Cloud |
| SentinelOne Singularity |
| Sophos Intercept X |
| Cisco Secure Endpoint |
| Microsoft Defender for Endpoint |
| Others |
Supply & Pricing Matrix
Backward integration into cloud infrastructure anchors supply positioning and pricing power for platform vendors competing against operating system bundlers. Kernel-level driver development and security operations center buildouts in Germany and the United States concentrate cost structures while enabling premium-tier machine learning detection capabilities that command subscription multiples over commodity antivirus.
Pricing Analysis
Bundled versus unbundled service splits separate enterprise-grade behavioral analysis suites from commodity operating system security features. Three-tier pricing structure across premium behavioral monitoring, standard machine learning detection, and economy signature-based prevention reflects capability stratification. Cost compression in the mid-market intensifies as Microsoft Defender native integration displaces standalone procurement. Small businesses exhibit highest price sensitivity while federal healthcare systems facing HIPAA mandates show lowest elasticity for audit-grade logging platforms.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand for cloud-native telemetry platforms while managed security service providers capture mid-market accounts lacking detection engineering headcount. Engineering talent concentrates in the United States, Germany, and Israel, anchoring product development and security operations center placement. Distribution runs through value-added resellers and systems integrators in European manufacturing clusters and North American healthcare networks. Single-source vulnerability in kernel driver certification pipelines creates release cycle risk as Microsoft and Apple tighten signature requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate where automated remediation capabilities meet EU regulatory deadlines, compressing implementation windows for vendors with pre-certified cloud architectures. Premium-tier behavioral analysis suites capture pricing power as healthcare institutions upgrade from signature-based systems.
For Market Incumbents: Extend cloud-native telemetry advantages into converged SASE-EPP suites before network security vendors capture cross-sell revenue. Invest in EU-established security operations centers to satisfy German automotive supplier procurement specifications around Cyber Resilience Act compliance. Kernel driver certification pipelines represent a critical capacity constraint requiring dedicated engineering resources to maintain release velocity against Microsoft and Apple notarization delays. For New Entrants and Emerging Players: The price-point gap between premium AI-native suites and economy bundled solutions creates white-space for hybrid deployment specialists serving financial services firms with distributed trading floors. Target healthcare institutions in the US Midwest and Southeast where limited security staffing favors integrated suites over point solutions requiring custom engineering. Lead with managed services wrappers that outsource detection engineering talent scarcity for mid-market accounts. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native telemetry specialists because heterogeneous tool consolidation demands custom integration engineering that incumbents struggle to deliver at scale. Long-term viability favors vendors with native data platform investments and cross-domain correlation engines. Watch EU NIS2 Directive enforcement timelines as inflection indicators for automated remediation procurement acceleration among critical infrastructure operators.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Converges endpoint telemetry with SASE networking to capture cross-sell revenue from consolidating enterprises. |
| Acquisition of Specialist Firm | Adds kernel-level behavioral monitoring capabilities that satisfy sub-100-millisecond response latency requirements. |
| Geographic Expansion | Establishes EU security operations centers to meet German automotive supplier Cyber Resilience Act procurement mandates. |
| Strategic Partnership | Integrates EPP telemetry with existing SIEM and SOAR investments to reduce heterogeneous tool consolidation friction. |
| Product Launch | Deploys agentless endpoint telemetry architectures that compress competitive moats between premium and legacy vendors. |
Research Methodology
Direct dialogue with CISOs, IT procurement officers, platform engineers, and managed security service providers grounds qualitative assessment in operational reality. Secondary validation draws from SEC filings, FedRAMP authorization databases, EU regulatory filings, and healthcare system procurement records. Bottom-up deployment model sizing and top-down regulatory impact assessment triangulate market scope across cloud-native, on-premises, hybrid, and managed service delivery architectures.
Bottom-up endpoint count modeling by organization size and vertical overlays top-down IT security spending elasticity analysis across the projection horizon. Segmentation dimensions include deployment model, end-user type, technology layer, and service category, with cross-cutting geographic adoption patterns. CAGRs derive from regression analysis against endpoint proliferation rates and regulatory compliance deadline clustering. Forecast inputs incorporate kernel driver certification pipeline constraints and detection engineering talent scarcity projections.
Caveats apply where EU AI Act enforcement timing or Microsoft bundling strategy shifts could materially shift the outlook. Forecasts reflect assumptions around cloud migration velocity and critical infrastructure operator procurement cycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Enterprise Mobility Security Market
Cybersecurity
Network Security Market
Cybersecurity
Application-Level Encryption Market
Cybersecurity
Global API Security Market
Cybersecurity
Cybersecure Vehicle Control Unit Gateway Systems Market
Cybersecurity
United States Cybersecurity Market
Cybersecurity
Israel Cybersecurity Market
Cybersecurity
Open RAN Security Market
Cybersecurity
Global Cloud Encryption Market
Cybersecurity
Asia Pacific Data Exfiltration Market
Cybersecurity
Global Healthcare IoT Security Market
Cybersecurity
France Cybersecurity Market
Cybersecurity
Global Network Security Policy Management Market
Cybersecurity
Threat Intelligence Market
Cybersecurity
Global Cyber Data Security Market
Cybersecurity
Global Network Forensics Market