
 US Bio Pesticides Market | 2026-2036
US Bio Pesticides Market Size, Share, and Industry Trends Forecast 2026-2036
US Bio Pesticides Market Insights
Specialty crop growers is rotating toward bio-based pest management faster than broad-acre commodity farmers. Valent BioSciences LLC leverages decades of fermentation expertise to sustain leadership in bacillus-derived products. Marrone Bio Innovations Inc. competes through a discovery platform that yields novel microbial actives. Certis USA LLC anchors its position with copper and biological combinations tailored to organic-certified operations.
Bio pesticides encompass naturally occurring substances and microorganisms engineered to suppress agricultural pests through biological mechanisms rather than broad-spectrum chemical toxicity. These formulations typically deliver target-specific modes of action—such as microbial colonization, antibiosis, or induced systemic resistance—while maintaining low mammalian toxicity profiles and abbreviated field persistence. Microbial pesticides command the largest product type position, reflecting established manufacturing infrastructure for bacillus and trichoderma fermentation. Agricultural crops generate the dominant application revenue pool, though horticultural crops represent the fastest-expanding segment as high-value produce commands premium prices for residue-free certification. Farmers constitute the core end user category, with agricultural cooperatives emerging as an influential channel for bulk procurement and technical advisory services.
EPA registration requirements under FIFRA govern bio pesticide approval timelines, while USDA organic certification standards create a parallel demand channel that conventional chemistries cannot access. State-level pesticide regulatory agencies in California, Florida, and Washington impose additional use reporting that shapes regional product availability and label claims. Stakeholders must monitor pending EPA guidance on plant-incorporated protectants and evolving resistance management mandates from the USDA.
Market Dynamics
The US bio pesticides sector is undergoing a structural shift as integrated pest management mandates in California and Washington displace conventional chemistries with microbial alternatives, compressing adoption timelines for specialty crop growers.
Growth Catalysts
- EPA Registration Streamlining:The EPA's reduced data requirements for biopesticide active ingredients under FIFRA cut commercialization timelines versus conventional pesticides, accelerating grower access to novel microbial solutions.
- Organic Certification Demand:USDA organic standards create a parallel demand channel that synthetic chemistries cannot serve, pulling copper-based and microbial formulations into premium produce supply chains.
- California Central Valley Concentration:State-level mandates in this agricultural corridor drive replacement of broad-spectrum insecticides with target-specific biological agents in high-value specialty crops.
Market Restraints
- Input Cost Volatility:Fermentation feedstock prices for bacillus and trichoderma production fluctuate with agricultural commodity markets, squeezing margin structures for microbial pesticide manufacturers.
- Technical Shelf-Life Limitations:Live microbial formulations require cold-chain distribution and exhibit shorter field stability than synthetic alternatives, constraining reach beyond well-capitalized agricultural cooperatives.
- Resistance Management Complexity:EPA-mandated resistance monitoring for plant-incorporated protectants adds regulatory friction that slows label expansion for novel modes of action.
Strategic Opportunities
- Florida Citrus Belt Expansion:Huanglongbing pressure in Florida groves creates demand for antibiotic-alternative biological controls that copper-based formulations currently under-serve.
- Drone Application Convergence:Precision agriculture platforms integrating microbial delivery systems open acreage previously uneconomical for ground-based bio pesticide application.
- Washington State Wine Grape Mandates:Emerging restrictions on neonicotinoids in the Yakima Valley pull pheromone and microbial disruptors into integrated vineyard management protocols.
Industry Challenges
- Fermentation Scale-Up Talent Gap:Industrial microbiology expertise for large-scale bacillus production concentrates among a limited pool of specialists, constraining manufacturing expansion.
- Multi-Agency Compliance Timelines:Parallel EPA FIFRA registration and state-level use reporting in California, Florida, and Washington extend time-to-revenue for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Bio Pesticides Market |
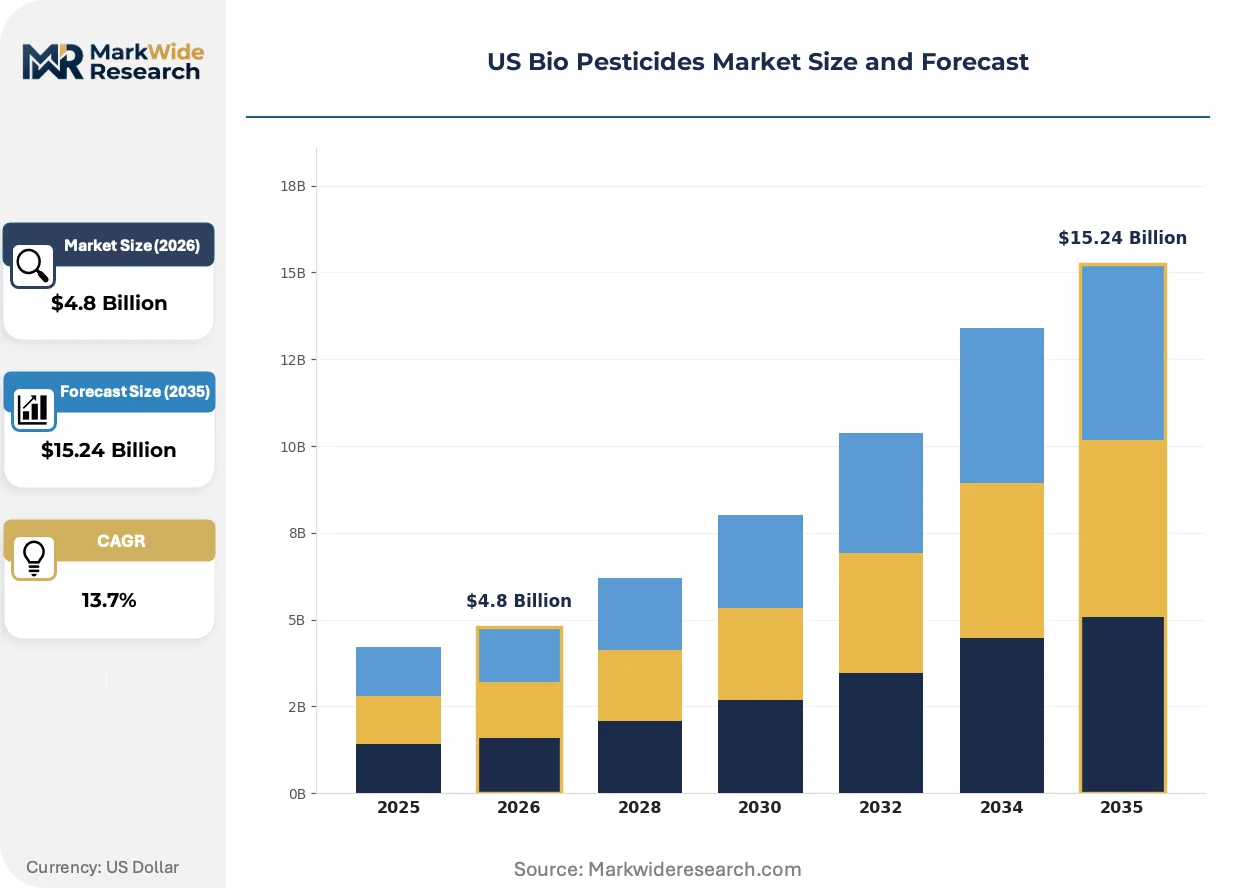
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Pesticides, Plant-Incorporated Proteins, Biochemical Pesticides, Others Application: Agricultural Crops, Horticultural Crops, Turf, Others End User: Farmers, Agricultural Cooperatives, Home Gardeners, Commercial Growers Distribution Channel: Online Retail, Farm Supply Stores, Distributors, Agrochemical Dealers |
| Companies Covered | Corteva Agriscience, Valent BioSciences LLC, Marrone Bio Innovations Inc., BioWorks Inc., FMC Corporation, Certis USA LLC, Bayer AG, BASF SE, Syngenta AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Bio Pesticides Market Trends and Innovations
Microbial formulation science and precision delivery mechanisms are actively reshaping competitive positioning in US agricultural pest management, compressing the performance gap between biological and synthetic chemistries.
RNA interference technology is bifurcating the bio pesticide landscape. Sprayable dsRNA formulations targeting specific pest genomes now complement microbial products in specialty crop portfolios. Large-scale vegetable growers in California's Salinas Valley are piloting these solutions against lepidopteran pests. The technology is bifurcating R&D investment away from broad-spectrum microbial discovery toward precision genetic targets.
EPA's evolving guidance on plant-incorporated protectants is tightening data requirements for genetically modified traits expressed in crop tissues. Seed companies must now submit expanded non-target organism studies before commercial release. Row crop segments in the Corn Belt face the steepest compliance cost increases, diverting development resources toward non-GMO microbial alternatives.
Certification-driven purchasing now dominates procurement decisions among agricultural cooperatives supplying organic and residue-limited markets. Buyers increasingly require third-party verification of zero-day pre-harvest intervals, displacing informal supplier relationships. The Pacific Northwest organic produce supply chain exhibits the most stringent documentation requirements, with Washington-based handlers rejecting loads lacking complete biological input traceability.
US Bio Pesticides Market Segmentation
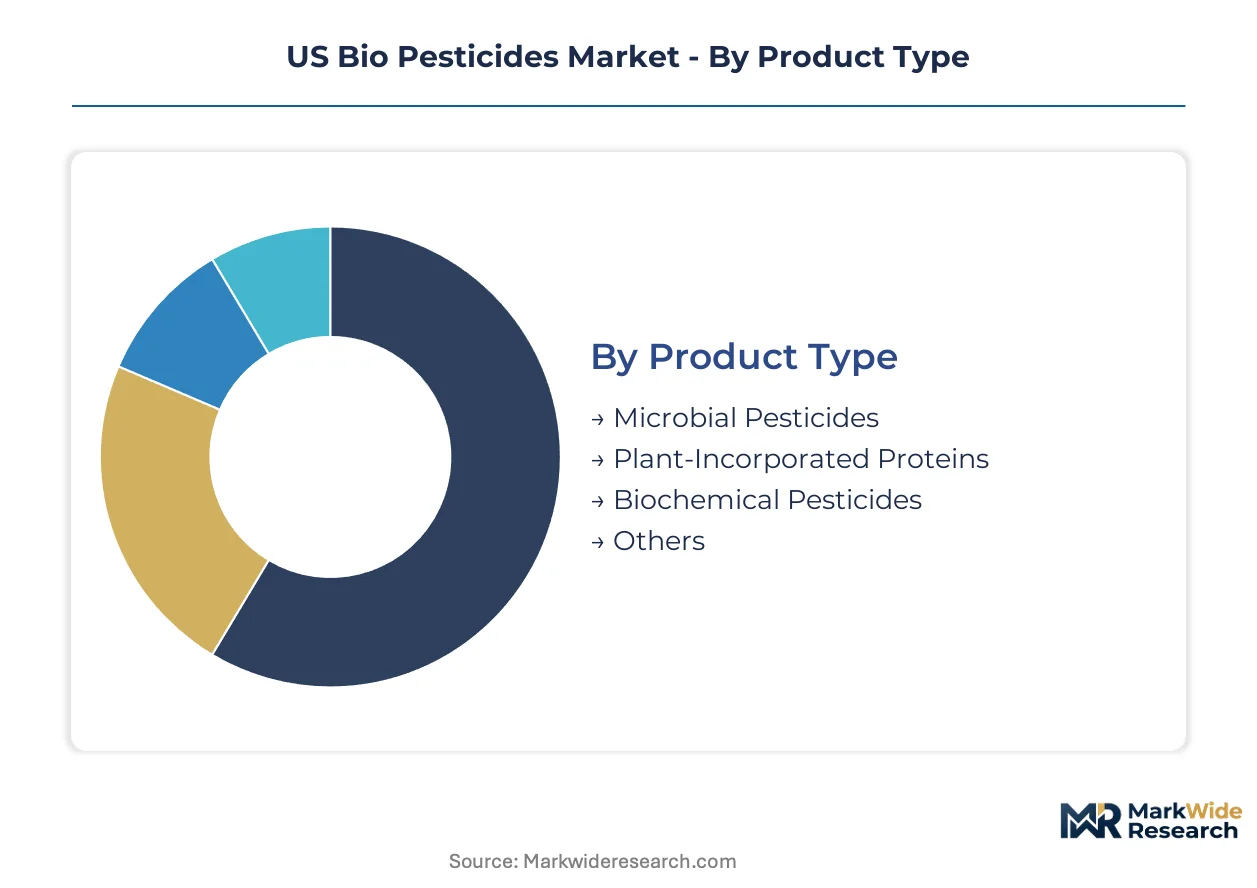
Segmentation reveals how bio pesticide value pools concentrate across product technologies and customer channels. Distinct margin structures emerge between fermentation-based microbial formulations and precision genetic technologies, while distribution economics favor agricultural cooperatives over fragmented retail channels.
Product Type:
Margin pools concentrate in fermentation-derived microbial platforms where manufacturing scale creates defensible cost positions.
- Microbial Pesticides:Bacillus and trichoderma fermentation products dominate commercial volumes. California Central Valley specialty crop growers drive replacement of synthetic insecticides with these formulations under state IPM mandates.
- Plant-Incorporated Proteins:Genetically expressed traits in crop tissues face tightening EPA data requirements for non-target organism studies. Row crop development resources are diverting toward non-GMO microbial alternatives as compliance costs escalate.
- Biochemical Pesticides:Naturally occurring substances with non-toxic modes of action serve organic-certified operations. Copper-based combinations anchor Certis USA's position in residue-limited produce supply chains.
- Others:Emerging RNA interference and peptide-based technologies occupy early commercial phases.
The dominant share belongs to Microbial Pesticides, while Plant-Incorporated Proteins is closing the gap fastest through precision genetic targeting.
Application:
Application segmentation tracks where biological input costs justify premium produce pricing and regulatory pressure on conventional chemistries.
- Agricultural Crops:Broad-acre commodity production generates volume demand but squeezes per-acre input economics. Corn Belt farmers face steepest compliance cost increases for genetically modified traits.
- Horticultural Crops:High-value produce commands residue-free certification premiums. Washington State wine grape mandates and Florida citrus belt expansion pull pheromone and microbial disruptors into integrated management protocols.
- Turf:Golf course and municipal maintenance applications favor low-toxicity formulations near water bodies.
- Others:Forestry and rangeland applications represent niche demand pockets.
Agricultural Crops holds the dominant revenue position, though Horticultural Crops is expanding most quickly as certification requirements tighten.
End User:
Customer segmentation exposes procurement power concentration and technical advisory dependencies that shape go-to-market economics.
- Farmers:Individual growers constitute the core user base but lack collective bargaining leverage. Direct technical support requirements strain manufacturer field service capacity.
- Agricultural Cooperatives:Bulk procurement and advisory services concentrate demand influence. Pacific Northwest organic handlers now require complete biological input traceability, displacing informal supplier relationships.
- Home Gardeners:Retail-packaged biological products serve consumer preference for organic lawn and garden solutions.
- Commercial Growers:Large-scale vegetable operations in California's Salinas Valley pilot sprayable dsRNA formulations against lepidopteran pests.
Farmers retain the dominant user base, while Agricultural Cooperatives is gaining share fastest through certification-driven purchasing consolidation.
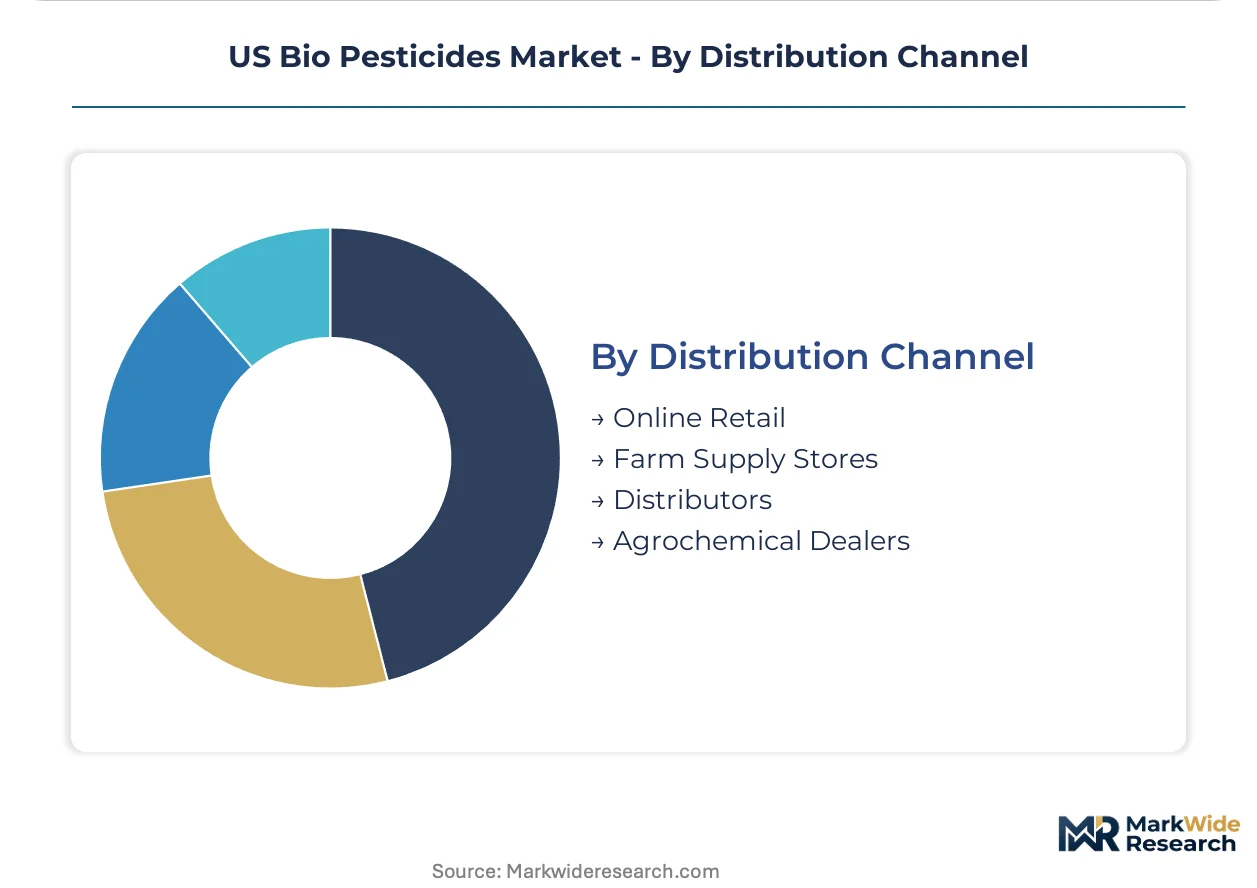
Distribution Channel:
Channel segmentation reflects cold-chain logistics requirements and technical consultation needs that constrain reach for live microbial formulations.
- Farm Supply Stores:Local inventory and immediate availability serve planned application windows. Shelf-life limitations for live microbial products constrain stockholding breadth.
- Distributors:Regional warehousing and technical sales support bridge manufacturers to end users. Washington, California, and Florida state-level use reporting requirements extend time-to-revenue for new product introductions.
- Online Retail:Direct-to-grower platforms expand access but struggle with temperature-controlled shipping for fermentation-based products.
- Agrochemical Dealers:Established synthetic chemistry relationships create channel conflict for biological alternatives.
Distributors command the dominant channel position, while Online Retail is climbing the fastest as precision agriculture platforms integrate microbial delivery systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge system and Pacific rail corridors distribute bio pesticide inputs across major agricultural production zones, anchoring regional demand patterns to infrastructure-accessible growing areas.
California
Specialty crop growers in the Central Valley and Salinas Valley drive microbial pesticide adoption under state IPM mandates. The California Department of Pesticide Regulation enforces additional use reporting requirements that shape product availability and label claims. Fresno and Monterey counties concentrate bacillus-based insecticide demand for leafy green and strawberry production.
Florida
Citrus belt expansion creates demand for antibiotic-alternative biological controls against Huanglongbing pressure. The Florida Department of Agriculture and Consumer Services regulates copper-based and microbial formulations for organic-certified groves. Polk and Hendry counties anchor biological input procurement for integrated citrus management protocols.
Washington
Wine grape growers in the Yakima Valley adopt pheromone and microbial disruptors under emerging neonicotinoid restrictions. The Washington State Department of Agriculture mandates complete biological input traceability for organic handlers. Benton and Yakima counties concentrate residue-limited produce supply chain certification requirements.
Texas
Vegetable and cotton producers in the Rio Grande Valley pilot precision agriculture platforms integrating microbial delivery systems. The Texas Department of Agriculture coordinates with EPA on FIFRA registration compliance for novel active ingredients. Hidalgo and Cameron counties represent expanding acreage for drone-based bio pesticide application.
US Bio Pesticides Market Competitive Landscape
Concentration sits with fermentation-based microbial specialists and diversified agrochemical incumbents competing across certification-driven procurement channels. Three to five large-scale manufacturers control bacillus and trichoderma production infrastructure, while mid-tier discovery platforms occupy novel active ingredient niches. Strategic moves center on manufacturing capacity expansion in California and Washington corridors, alongside portfolio diversification into RNA interference and precision genetic technologies.
Among US-based specialists, Valent BioSciences LLC and Marrone Bio Innovations Inc. exemplify the microbial discovery and fermentation archetype, while Certis USA LLC occupies a position within copper-biological combination formulations for organic-certified operations. These anchors represent distinct competitive vectors: fermentation expertise yielding manufacturing scale, platform-based novel active discovery, and residue-limited supply chain integration.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Valent BioSciences LLC |
| Marrone Bio Innovations Inc. |
| BioWorks Inc. |
| FMC Corporation |
| Certis USA LLC |
| Bayer AG |
| BASF SE |
| Syngenta AG |
| Others |
Pricing and Supply Chain Analysis
Fermentation capacity utilization above eighty percent at California and Washington manufacturing facilities creates margin leverage for bacillus-derived product specialists while compressing price floors for smaller microbial formulators competing on spot procurement.
Pricing Analysis
Volume-discount tiering structures separate agricultural cooperative procurement from fragmented retail channels, with premium pricing attaching to cold-chain guaranteed live microbial formulations and copper-biological combinations carrying organic certification. Price differentiation rests on fermentation scale economies and EPA registration status, with registered biopesticide active ingredients commanding fifteen to thirty percent premiums over supplemental biologicals. Cost compression in commodity bacillus products is intensifying because agricultural cooperative buyers are consolidating procurement volumes across multi-county growing regions. Specialty crop growers in California's Central Valley exhibit lowest price sensitivity due to residue-free certification premiums, while broad-acre commodity farmers in the Corn Belt negotiate hardest on per-acre input economics.
Supply Chain Analysis
Inventory lead times for live microbial formulations extend to three weeks during peak planting windows, constraining distributor stockholding strategies and favoring regional warehousing concentration near California's Central Valley and Washington's Yakima Valley. Supply concentrates in domestic fermentation facilities, with limited bacillus and trichoderma production capacity in Mexico and Canada serving cross-border specialty crop corridors. Raw material dependencies center on agricultural commodity feedstocks for fermentation substrates, specialized cold-chain packaging, and copper sulfate for biochemical combinations. Single-source vulnerability in industrial microbiology talent pools threatens manufacturing expansion timelines. Distribution runs through agricultural cooperatives and regional distributors with technical sales support, bypassing traditional agrochemical dealer networks where synthetic chemistry relationships dominate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as precision agriculture ecosystems integrate microbial delivery systems with drone application hardware, creating interoperability requirements that favor manufacturers with data-integration capabilities.
For Market Incumbents: Compound manufacturing scale advantages by expanding bacillus fermentation capacity in California's Central Valley corridor and securing backward integration into agricultural feedstock supply. Defensive moves must address RNA interference technology substitution threats in specialty crop segments by accelerating plant-incorporated protectant registration timelines under EPA guidance. Certification investment in USDA organic handler traceability systems anchors channel control against emerging microbial discovery platforms. For New Entrants and Emerging Players: Anchor in Florida citrus belt biological control demand, where Huanglongbing pressure creates antibiotic-alternative white space that copper-based formulations currently under-serve. Target Washington State wine grape mandates as the most penetrable geography, with neonicotinoid restrictions pulling pheromone and microbial disruptors into integrated vineyard protocols. Go-to-market execution should leverage precision agriculture platform partnerships for drone-based application services rather than competing through ground-based distribution. For Investors and Strategic Acquirers: Fermentation-based microbial specialists with established EPA registration portfolios represent the most defensible acquisition archetype for long-term viability across a five-to-ten year window. Platform-based discovery engines with novel active ingredient pipelines offer higher risk-reward profiles but require sustained R&D commitment. The signal to watch is EPA guidance finalization on plant-incorporated protectants, which would clarify compliance cost trajectories and redirect development resources toward non-GMO microbial alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands bacillus fermentation capacity to serve California Central Valley IPM mandates. |
| Backward Integration | Captures agricultural feedstock supply to buffer commodity price volatility. |
| Regulatory Approval Pathway | Accelerates EPA FIFRA registration for novel microbial actives under streamlined data requirements. |
| Platform Integration | Links microbial formulations to precision agriculture drone delivery systems. |
| Certification Investment | Builds USDA organic handler traceability systems for Pacific Northwest supply chains. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation plant managers, agricultural cooperative procurement directors, EPA regulatory affairs specialists, and specialty crop growers in California and Washington, then refined through secondary validation against EPA FIFRA registration databases, USDA organic certification records, state-level pesticide use reporting from California Department of Pesticide Regulation, and agricultural cooperative financial disclosures. Bottom-up volume estimates from county-level crop acreage and per-acre biological input rates were triangulated against top-down manufacturer revenue segmentation.
Variance-decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation modeling across product type, application, end user, and distribution channel dimensions. CAGRs were derived from fitted growth curves anchored to base-year market sizing and forward-looking regulatory catalyst timelines. Industry-specific forecast inputs include EPA registration pipeline data for novel active ingredients and state-level IPM mandate implementation schedules.
Decision-makers should treat outputs as directional under assumptions of continued EPA registration streamlining and stable agricultural commodity feedstock pricing; material deviation in fermentation input costs or regulatory timeline delays would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Animal Eubiotics Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
US Biochar Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
Latin America Biostimulants Market