
 HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market | 2026-2036
HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market Size, Share, and Industry Trends Forecast 2026-2036
HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market Insights
Photocatalytic hydrophilic coating technology is fragmenting across multiple deposition methods as OEMs demand tighter haze specifications for next-generation augmented reality windshields. AGC leverages its fused glass-coating integration to sustain premium supply relationships with Japanese and European automakers. Saint-Gobain Sekurit anchors European production capacity through its specialized float-line modifications for HUD-grade substrates. NSG Group competes on thermal management performance in electrothermal defogging architectures.
HUD-compatible low-haze windshield defogging coating systems comprise thin-film surface treatments engineered to maintain luminous transmittance above 85% while enabling rapid moisture dispersal through superhydrophilic or electrothermal mechanisms, typically deposited via magnetron sputtering or sol-gel processes onto laminated automotive glazing. The primary commercial purpose centers on eliminating visual interference in projected display systems without compromising windshield structural integrity or optical quality. Hydrophilic coatings dominate current OEM specifications due to their passive operation and compatibility with existing float-glass lines, while UV-curable spray technologies represent the fastest-growing application segment as aftermarket installers seek lower-capital retrofit solutions. Passenger vehicle manufacturers concentrate margin pools around multi-year coating supply agreements tied to platform-level HUD adoption.
FDA oversight of optical device clarity standards intersects with NHTSA glazing safety regulations to define permissible haze thresholds for US-market HUD-integrated windshields, creating dual compliance burdens for coating formulators. The EU AI Act's forthcoming requirements for human-machine interface transparency are expected to tighten optical performance certification protocols for augmented reality display systems. REACH chemical restrictions on perfluorinated compounds continue forcing reformulation of legacy hydrophobic-hydrophilic hybrid coatings toward fluorine-free alternatives. Stakeholders must monitor the divergence between regional optical clarity certification regimes as HUD resolution specifications escalate toward 4K projection standards.
Market Dynamics
Photocatalytic coating deposition is hybridizing with electrothermal architectures as OEMs pursue redundant defogging systems capable of satisfying augmented reality HUD clarity specifications without single-point failure risks.
Growth Catalysts
- EU Green Deal material mandates:Automotive glazing suppliers are reformulating solvent-based coating chemistries toward waterborne alternatives to secure platform-level supply contracts with Stuttgart and Munich-based premium manufacturers.
- Head-up display platform proliferation:Passenger vehicle OEMs are embedding HUD systems across mid-tier vehicle segments, expanding addressable glazing surface area requiring low-haze treatment beyond luxury flagships.
- Magnetron sputtering line investment:Specialized float-glass producers are retrofitting production assets in Germany and Japan to deposit nanostructured hydrophilic films at automotive-scale throughput.
Market Restraints
- Indium tin oxide input volatility:Electrothermal coating architectures depend on transparent conductive oxide layers subject to critical mineral supply concentration and price fluctuation.
- REACH perfluorinated compound restrictions:Legacy hydrophobic-hydrophilic hybrid formulations face phased elimination, forcing costly reformulation cycles for established coating suppliers.
- Sol-gel process yield limitations:Wet-chemical deposition methods exhibit batch-to-batch optical variability that conflicts with tight haze specifications demanded by next-generation augmented reality windshields.
Strategic Opportunities
- UV-curable spray retrofit channel:Aftermarket installers are adopting low-capital application equipment to serve vehicle owners seeking HUD-compatible clarity restoration without full windshield replacement.
- Dual carbon goal alignment in China:Domestic automotive OEMs are qualifying fluorine-free hydrophilic coatings to satisfy MIIT sustainable material procurement guidelines while maintaining optical performance.
- Electrothermal-photocatalytic convergence:Coating formulators are developing multifunctional thin-film stacks combining passive moisture management with active thermal defogging for extreme climate operation.
Industry Challenges
- Optical metrology talent scarcity:Coating quality assurance teams require specialized expertise in luminous transmittance and haze measurement protocols that outpaces vocational training pipeline output.
- NHTSA-FDA dual certification timelines:US-market HUD-integrated windshields must satisfy overlapping optical clarity and glazing safety review processes that extend product qualification cycles.
- Legacy float-line integration complexity:Established glass manufacturing facilities face mechanical and thermal constraints when retrofitting magnetron sputtering chambers for HUD-grade substrate production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market |
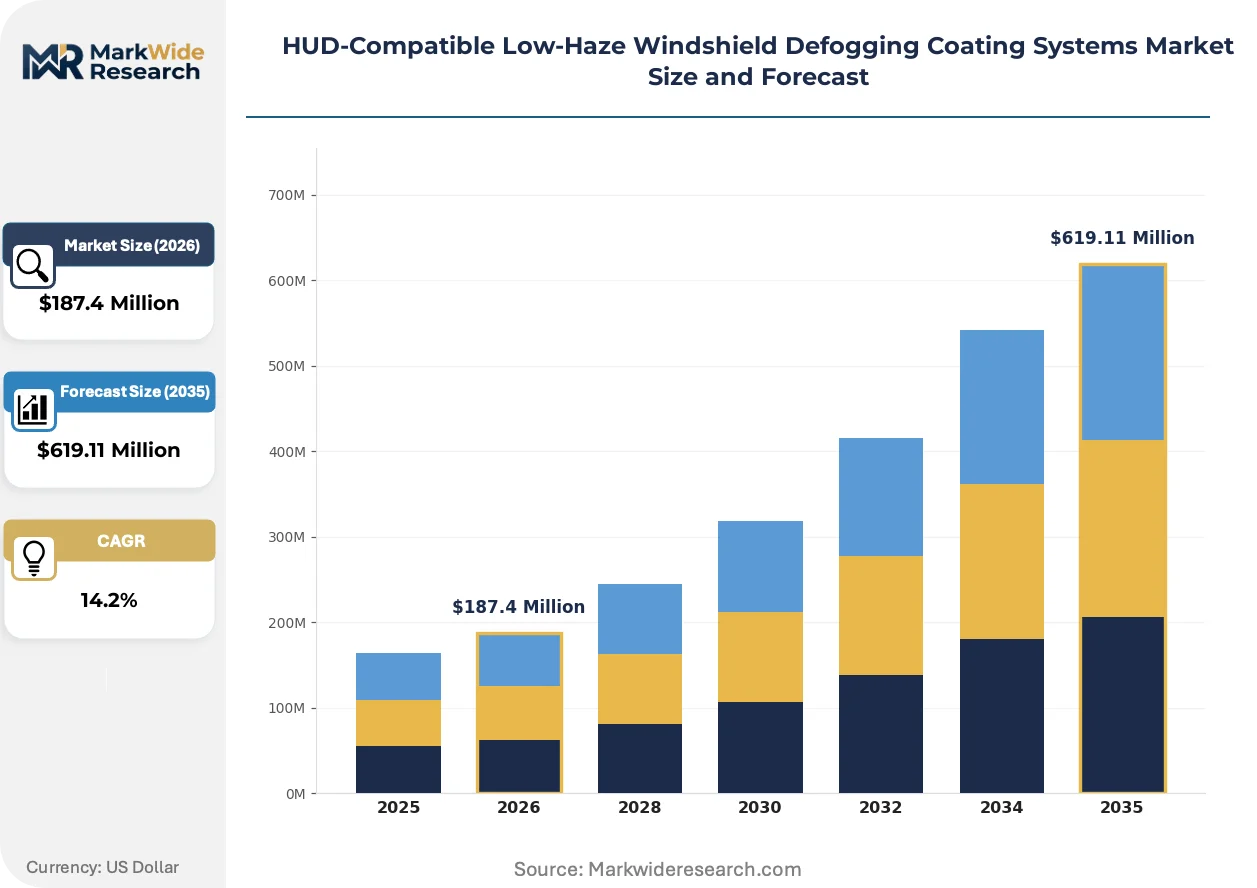
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophilic Coatings, Anti-fog Films, Nano-coated Sheets, Polymer-based Layers, Inorganic Composite Films Technology: Photocatalytic, Electrothermal, Hydrophobic-Hydrophilic Hybrid, Spray-applied, UV-Curable Application: Augmented Reality Displays, Navigation Systems, Heads-up Displays, Driver Assistance Interfaces End User: Passenger Vehicle Manufacturers, Commercial Fleet Operators, Aftermarket Installers, Specialty Vehicle Producers |
| Companies Covered | AGC, Saint-Gobain Sekurit, NSG Group, Fuyao Group, Gauzy, Eastman Chemical, Xinyi Glass, Vitro, Oribay Group Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market Trends and Innovations
Coating functionality is bifurcating between passive hydrophilic surfaces and active electrothermal architectures as augmented reality display resolution requirements redefine acceptable optical interference thresholds.
Sol-gel-derived titania-silica nanocomposite coatings are hybridizing with sputtered transparent conductive oxide layers to create multifunctional thin-film stacks capable of simultaneous photocatalytic moisture dispersion and resistive heating. Tier-1 glazing suppliers serving Japanese and European OEMs are piloting these hybrid architectures on specialized float-line segments. The convergence is compressing the addressable market for single-mechanism coating solutions while opening premium pricing tiers for verified dual-function formulations.
REACH chemical restrictions on perfluorinated compounds are forcing systematic reformulation of legacy hydrophobic-hydrophilic hybrid coatings toward fluorine-free alternatives. Coating formulators are accelerating R&D investment in silicon-based hydrophilic chemistries that satisfy haze specifications without restricted substances. German and French automotive glazing supply chains are experiencing the most acute compliance pressure due to proximity to ECHA enforcement mechanisms and domestic OEM sustainability procurement criteria.
Multi-year coating supply agreements are displacing spot purchasing as passenger vehicle manufacturers consolidate procurement around platform-level HUD adoption strategies. Tier-1 suppliers are capturing extended visibility through volume-commitment contracts tied to specific vehicle architecture launches. This concentration is most visible in Germany's premium automotive manufacturing corridor, where Stuttgart-based OEMs are locking in coating capacity three to five years ahead of production ramp.
HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market Segmentation
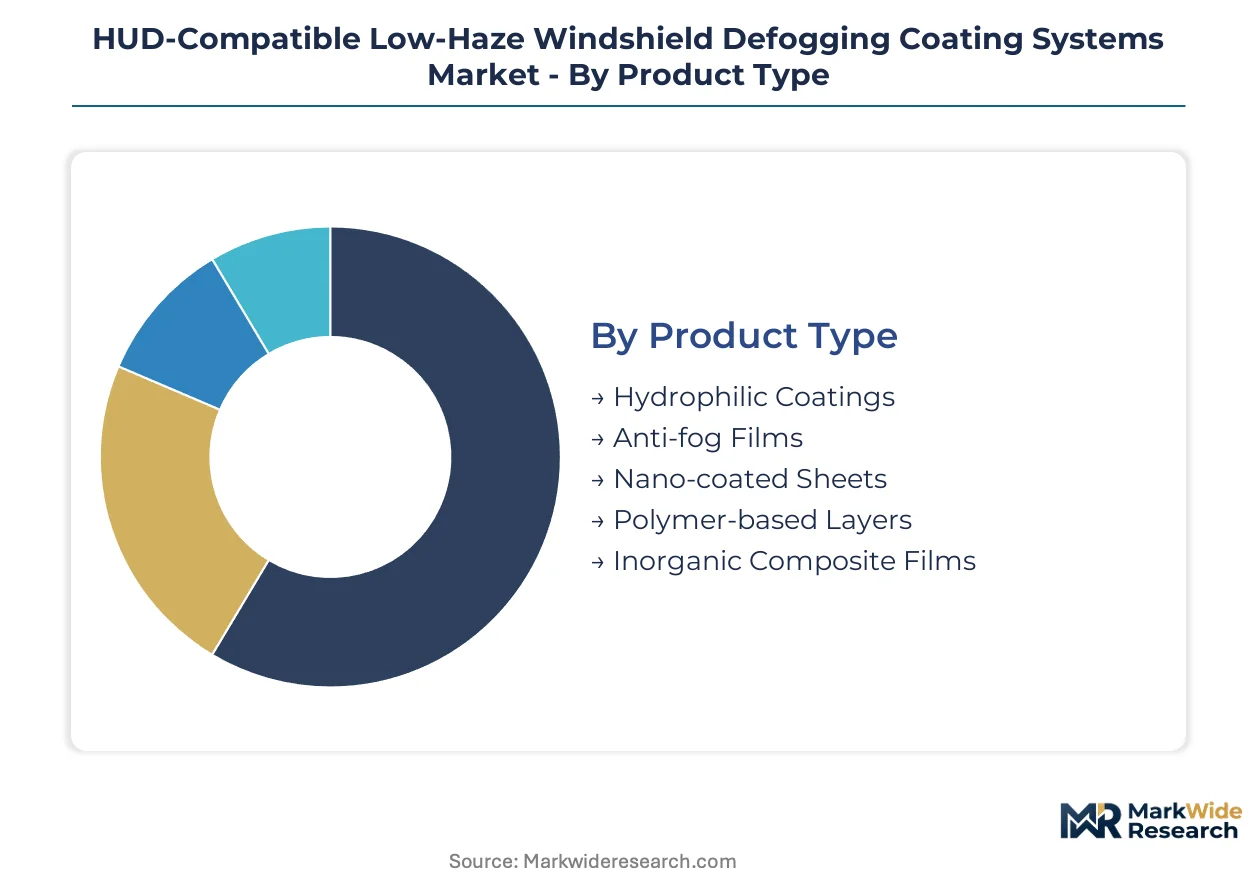
HUD-compatible low-haze windshield defogging coating systems fragment across four structural dimensions that determine pricing power, qualification timelines, and supply chain positioning. Product type and technology choices define the core manufacturing investment, while application specificity and end-user channel dictate margin capture and volume scaling potential.
Product Type:
The use-case spectrum spans passive surface treatments to integrated substrate solutions, with each tier demanding distinct deposition infrastructure and optical certification rigor.
- Hydrophilic Coatings:Titania-silica nanocomposite films deposited via magnetron sputtering or sol-gel processes achieve superhydrophilic surfaces with luminous transmittance above 85%. German premium OEMs in Stuttgart and Munich concentrate procurement around these coatings for platform-level HUD integration, driven by EU Green Deal mandates favoring waterborne chemistries over solvent-based alternatives.
- Anti-fog Films:Polymer-substrate laminates with embedded hydrophilic surface layers offer retrofit compatibility for aftermarket channels. Aftermarket installers in Japan and Germany favor these for lower-capital application equipment, though haze specifications lag integrated coating solutions.
- Nano-coated Sheets:Pre-coated glass substrates from specialized float-line segments.
- Polymer-based Layers:Flexible film alternatives for non-glass glazing applications.
- Inorganic Composite Films:Multi-layer stacks combining photocatalytic and conductive oxide functionality.
Established volume favors hydrophilic coatings; emerging adoption favors anti-fog films.
Technology:
Cost tier stratification separates capital-intensive vacuum deposition from accessible spray-applied alternatives, with hybrid architectures commanding premium positioning.
- Photocatalytic:UV-activated titania surfaces enabling passive moisture dispersion without electrical infrastructure. Japanese float-glass producers anchor production capacity for this technology, serving domestic OEMs and European export markets under REACH-compliant fluorine-free formulations.
- Electrothermal:Transparent conductive oxide layers with resistive heating capability for active defogging. Indium tin oxide supply concentration and price volatility constrain scaling, though dual-function stacks with photocatalytic layers are gaining share in extreme climate specifications.
- Hydrophobic-Hydrophilic Hybrid:Legacy formulations facing phased elimination under perfluorinated compound restrictions.
- Spray-applied:Field-deployable coating methods for aftermarket and repair channels.
- UV-Curable:Rapid-cure chemistries reducing application cycle times in retrofit operations.
Photocatalytic systems dominate OEM specifications; UV-curable methods are climbing the fastest in aftermarket penetration.
Application:
Resolution requirements across display modalities create divergent haze tolerance thresholds that reshape coating qualification priorities.
- Heads-up Displays:Conventional projection systems requiring luminous transmittance maintenance above 85% with minimal optical interference. Passenger vehicle manufacturers embed these across mid-tier segments beyond luxury flagships, expanding addressable glazing surface area.
- Augmented Reality Displays:Next-generation systems with 4K projection standards demanding sub-1% haze specifications. ECHA enforcement proximity and EU AI Act forthcoming requirements tighten optical certification protocols for German and French supply chains.
- Navigation Systems:Lower-resolution display integration with relaxed optical tolerances.
- Driver Assistance Interfaces:Safety-critical overlay systems with intermediate clarity requirements.
Heads-up displays anchor current volume; augmented reality displays are gaining share fastest in premium platform planning.
End User:
Procurement pattern divergence separates multi-year coating supply agreements from spot purchasing, with channel-specific qualification burdens.
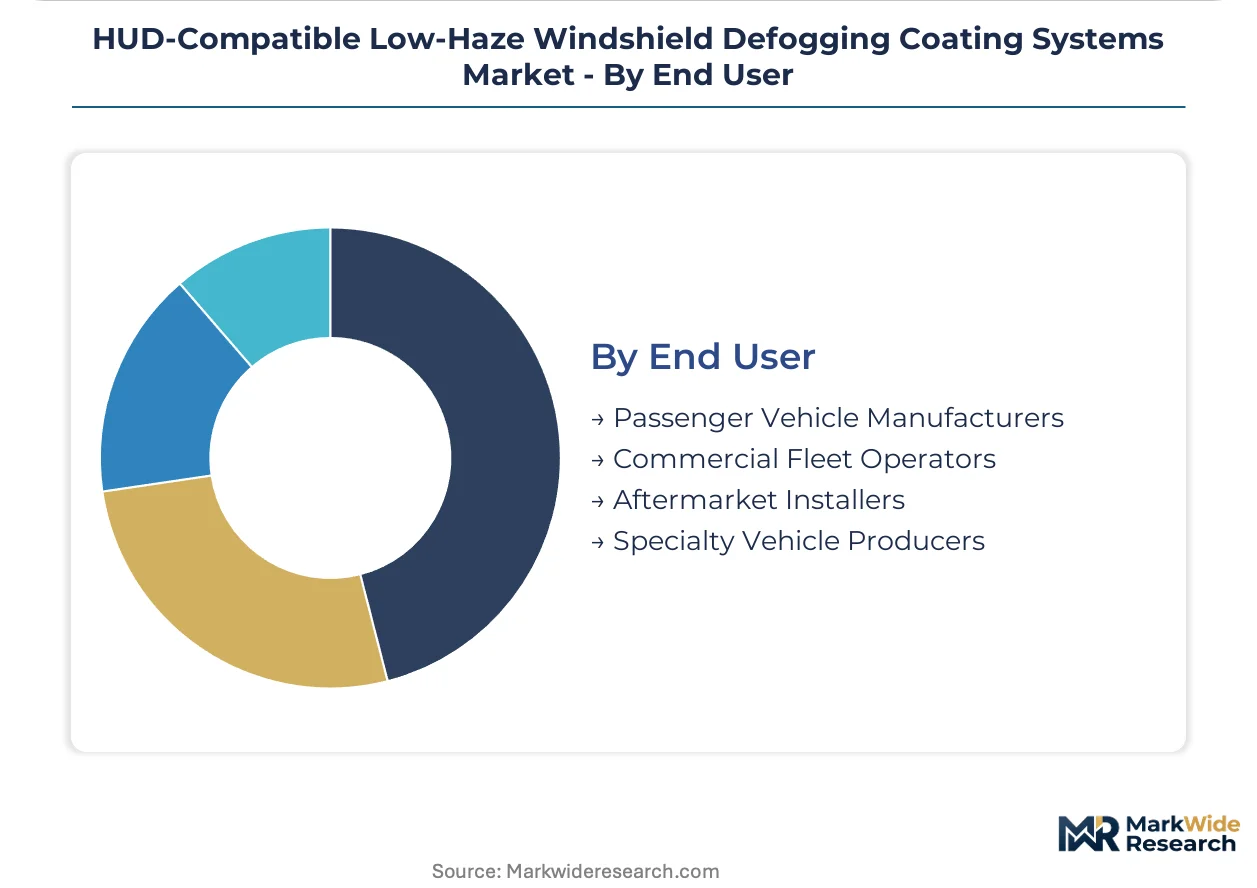
- Passenger Vehicle Manufacturers:Platform-level procurement with three-to-five-year volume commitments tied to HUD adoption strategies. Stuttgart-based OEMs lock in coating capacity ahead of production ramp, consolidating supply relationships around Tier-1 glazing specialists.
- Aftermarket Installers:Low-capital retrofit channels seeking clarity restoration without full windshield replacement. UV-curable spray technologies and anti-fog films serve this segment, though NHTSA-FDA dual certification timelines extend product qualification cycles for US-market entrants.
- Commercial Fleet Operators:Volume purchasers with standardized vehicle specifications.
- Specialty Vehicle Producers:Low-volume, high-customization requirements with extended qualification flexibility.
Passenger vehicle manufacturers concentrate margin pools; aftermarket installers are expanding most quickly as HUD penetration extends vehicle age demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese float-glass producers export photocatalytic coating capacity to German premium OEMs, while Chinese suppliers serve domestic automotive clusters under MIIT dual carbon procurement guidelines.
Germany
Stuttgart and Munich-based manufacturers lock in multi-year coating supply agreements three to five years ahead of production ramp. ECHA enforcement of REACH perfluorinated compound restrictions forces systematic reformulation toward fluorine-free hydrophilic chemistries. The Baden-Württemberg automotive corridor concentrates magnetron sputtering line investment for HUD-grade substrate production.
Japan
Domestic OEMs anchor demand for titania-silica nanocomposite films with luminous transmittance above 85%. METI industrial standards guide coating qualification protocols for augmented reality display integration. Kanto region float-glass producers sustain premium supply relationships through fused glass-coating integration capabilities.
United States
Mid-tier vehicle segment expansion extends addressable glazing surface area beyond luxury flagships. NHTSA glazing safety regulations intersect with FDA optical device clarity standards to define dual compliance burdens for coating formulators. Southeast automotive manufacturing clusters face extended product qualification cycles from overlapping federal review processes.
China
Domestic OEMs qualify fluorine-free hydrophilic coatings to satisfy MIIT sustainable material procurement guidelines. SAMR market supervision ensures GB standards alignment for imported coating chemistries. Yangtze River Delta automotive glazing suppliers pilot electrothermal-photocatalytic hybrid architectures for extreme climate specifications.
HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market Competitive Landscape
On the supply side, the industry is consolidating around Tier-1 glazing specialists with platform-level supply relationships and specialized float-line modification capabilities. Three strategic archetypes dominate: integrated glass-coating producers with captive deposition infrastructure, chemical formulators supplying coating materials to third-party applicators, and aftermarket-focused specialists in UV-curable spray technologies. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs consolidate procurement around multi-year volume commitments.
Among integrated glass-coating producers, AGC, Saint-Gobain Sekurit, and NSG Group exemplify the archetype of suppliers with fused deposition capabilities and established premium OEM relationships. These entities occupy positions where specialized float-line modifications for HUD-grade substrates create qualification barriers for aspirant competitors. Their geographic footprints align with major automotive manufacturing corridors in Japan and Europe, reflecting historical concentration in markets where regulatory pressure on optical clarity and chemical sustainability has tightened earliest.
| Leading Market Players |
|---|
| AGC |
| Saint-Gobain Sekurit |
| NSG Group |
| Fuyao Group |
| Gauzy |
| Eastman Chemical |
| Xinyi Glass |
| Vitro |
| Oribay Group Automotive |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Main logistics corridor's freight cost dynamics amplify supply concentration effects for German float-glass producers, compressing margin capture for magnetron sputtering equipment operators while enabling downstream price differentiation between captive OEM supply and aftermarket channels.
Pricing Analysis
Current-generation photocatalytic hydrophilic coatings command substantial premiums over prior-generation sol-gel formulations, while next-generation electrothermal-photocatalytic hybrids are establishing new price ceilings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from REACH-driven reformulation costs for fluorine-free chemistries. Aftermarket installers exhibit highest price sensitivity due to low-capital equipment constraints, while Stuttgart-based OEMs show lowest sensitivity tied to platform-level multi-year agreements.
Supply Chain Analysis
Upstream feedstock concentration for titania precursors centers on Chinese and Japanese chemical suppliers, with indium tin oxide for electrothermal layers drawing from South Korean and Chinese transparent conductive oxide producers. Raw material dependencies include nanostructured titania, high-purity silica, and rare-earth-doped conductive oxides. Single-source vulnerability for indium concentrates supply risk in electrothermal architectures. Distribution runs through Tier-1 glazing specialists with captive float-line modifications, bypassing independent applicators for OEM volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized optical metrology expertise functions as the critical scarce capability in this market, with qualified haze measurement technicians outnumbering available positions across German and Japanese coating qualification facilities.
For Market Incumbents: Build certification moats by investing in EU AI Act pre-compliance testing infrastructure for augmented reality display integration. Secure platform-level supply agreements with Stuttgart-based OEMs through dedicated magnetron sputtering line capacity. Acquire fluorine-free formulation IP from distressed chemical suppliers facing REACH enforcement pressure. For New Entrants and Emerging Players: The US Southeast automotive manufacturing corridor offers underpenetrated access for UV-curable spray retrofit channels, where NHTSA-FDA dual certification timelines have deterred established players. Target commercial fleet operators seeking standardized HUD clarity restoration across aging vehicle populations. Partner with regional aftermarket distributors to bypass direct OEM qualification burdens. For Investors and Strategic Acquirers: Chemical formulators with silicon-based hydrophilic IP portfolios represent the priority acquisition archetype for long-term viability within a five-to-ten year window. Monitor ECHA enforcement acceleration against perfluorinated compounds as the inflection signal for distressed asset availability in legacy coating formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Float-Line Modification for HUD-Grade Substrates | AGC and Saint-Gobain Sekurit anchor premium supply relationships through specialized deposition infrastructure. |
| Fluorine-Free Chemistry Reformulation | REACH perfluorinated compound restrictions force systematic R&D investment toward compliant hydrophilic alternatives. |
| UV-Curable Spray Channel Development | Aftermarket installers adopt low-capital application equipment to serve vehicle owners without full windshield replacement. |
| Dual-Function Thin-Film Stack Convergence | Electrothermal-photocatalytic hybrids command premium positioning for extreme climate augmented reality specifications. |
| Multi-Year Volume Commitment Contracts | Stuttgart-based OEMs lock in coating capacity three to five years ahead of production ramp. |
Research Methodology
Desk research of automotive glazing trade publications, patent filings, and ECHA regulatory databases preceded structured interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and coating formulator R&D leads. Primary fieldwork combined with secondary validation against SEC filings from listed glass manufacturers, customs data on titania precursor imports, and IHS Markit vehicle production databases. Bottom-up coating volume estimates triangulated against top-down HUD penetration projections across passenger vehicle segments.
Assumptions held fixed include current REACH enforcement trajectories and MIIT dual carbon procurement guidelines, while variables included augmented reality display adoption rates and indium price volatility scenarios. The analytical framework modeled product type, technology, application resolution tier, and end-user channel dimensions across the analysis window. CAGRs derived from segment-level volume build-ups incorporating platform-level HUD adoption curves and coating surface area per vehicle estimates.
Practitioners should monitor ECHA perfluorinated compound restriction acceleration and NHTSA-FDA dual certification timeline convergence for early signals of supply chain restructuring. Forecasts reflect these documented assumptions regarding regulatory enforcement and technology substitution patterns. Quarterly review of magnetron sputtering line utilization rates and aftermarket UV-curable spray adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Environment Control
Aerospace Flight Control System Market
Aircraft Environment Control
Aircraft Waste Tank Market
Aircraft Environment Control
Aircraft Air Conditioning Unit Market
Aircraft Environment Control
Turbine Air Filtration Market
Aircraft Environment Control
Ice Protection Systems Market
Aircraft Environment Control
Commercial Aircraft Air Management System Market
Aircraft Environment Control
Airborne Molecular Contamination Control Services Market
Aircraft Environment Control
Gas Turbine Air Filtration Market