
 United States Articulated Robot Market | 2026-2036
United States Articulated Robot Market Size, Share, and Industry Trends Forecast 2026-2036
United States Articulated Robot Market Intelligence
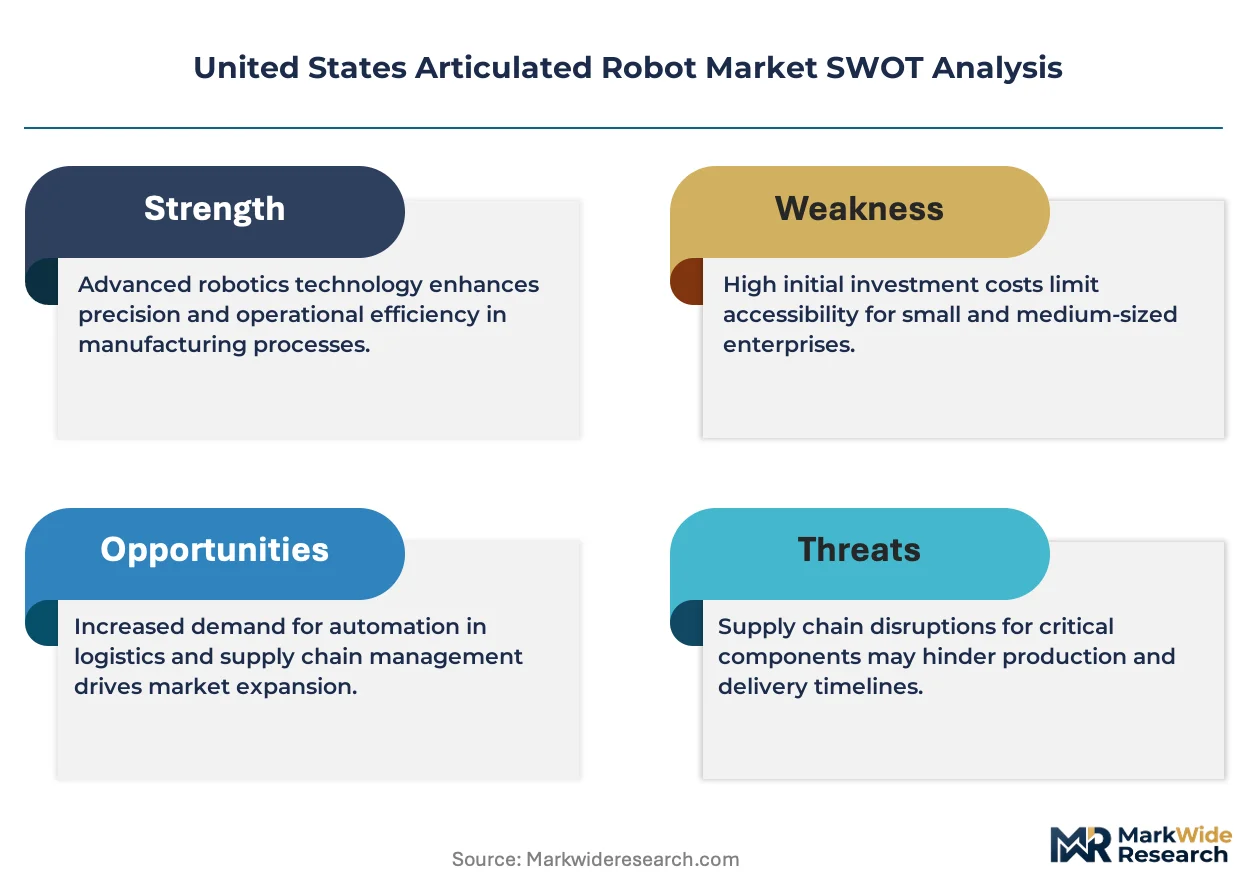
Skilled robot technician availability is bifurcating the United States Articulated Robot Market into automated-heavy and automation-lagging facilities. FANUC Corporation anchors its position through captive servo motor production in its Michigan and Georgia facilities. ABB Ltd. differentiates via software-integrated robotics targeting arc welding and machine tending workflows. KUKA AG navigates the defense-aerospace segment with heavy-payload articulated systems certified to Department of Defense supplier standards.
An articulated robot employs rotary joints—typically four to six axes—to manipulate tools or payloads through three-dimensional workspaces with repeatability below 0.1 millimeter. Electric-drive technology dominates new installations for its precision and energy efficiency, while hydraulic systems retain niche dominance in foundries and forging operations where payloads exceed 500 kilograms. Material handling robots command the largest installed base across automotive stamping and electronics distribution centers, whereas inspection applications within pharmaceutical cleanrooms represent the fastest-expanding demand pocket due to FDA validation requirements for automated visual defect detection.
OSHA machine guarding standards and ANSI/RIA R15.06 safety requirements shape robot system design, forcing integrators to add collaborative force-limiting features or physical safeguarding barriers. The FDA's 21 CFR Part 11 electronic records framework extends to robotic inspection lines in pharmaceutical packaging, adding software validation costs that filter vendor eligibility. Stakeholders must weigh NIST cybersecurity framework alignment against total cost of ownership as connected articulated systems face escalating ransomware exposure in operational technology networks.
Market Dynamics
The United States Articulated Robot Market is experiencing structural compression as electric vehicle battery assembly demands collide with a finite pool of certified robot technicians across the Great Lakes manufacturing corridor.
Growth Catalysts
- OSHA Machine Guarding Standards:Tightened workplace safety mandates are accelerating replacement cycles for legacy industrial robots with collaborative force-limiting systems in automotive stamping plants.
- Electric Vehicle Battery Assembly:Cell-to-pack manufacturing workflows are driving six-axis robot deployment for precision electrode stacking and thermal interface material application.
- NIST Cybersecurity Framework:Industrial automation integrators are retrofitting connected articulated systems with encrypted operational technology networks to meet federal compliance benchmarks.
Market Restraints
- Servo Motor Supply Concentration:Captive production of precision motion components concentrates in Michigan and Georgia facilities, creating geographic vulnerability for non-vertically integrated system builders.
- Pharmaceutical Software Validation Costs:FDA 21 CFR Part 11 electronic records requirements add six-figure compliance burdens that filter vendor eligibility for cleanroom inspection applications.
- Hydraulic System Niche Lock-in:Foundry and forging operations above 500-kilogram payloads remain tethered to hydraulic actuation due to electric drive torque density limitations.
Strategic Opportunities
- Defense-Aerospace Certification Gap:Department of Defense supplier standards for heavy-payload articulated systems remain underpenetrated by non-specialized integrators.
- Collaborative Robot-Human Workflows:ANSI/RIA R15.06 safety-compliant force-limiting features are opening machine tending applications previously reserved for fully caged automation.
- Ohio River Valley Retrofit Demand:Tier-1 automotive suppliers in legacy Ohio plants are accelerating phased migrations from four-axis to six-axis articulated configurations.
Industry Challenges
- Certified Technician Scarcity:FANUC, ABB, and KUKA proprietary programming environments fragment skill portability across the Great Lakes installation base.
- Legacy System Integration Friction:Retrofit projects in Michigan stamping plants face I/O protocol mismatches between 1990s-era PLCs and modern Ethernet-based robot controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Articulated Robot Market |
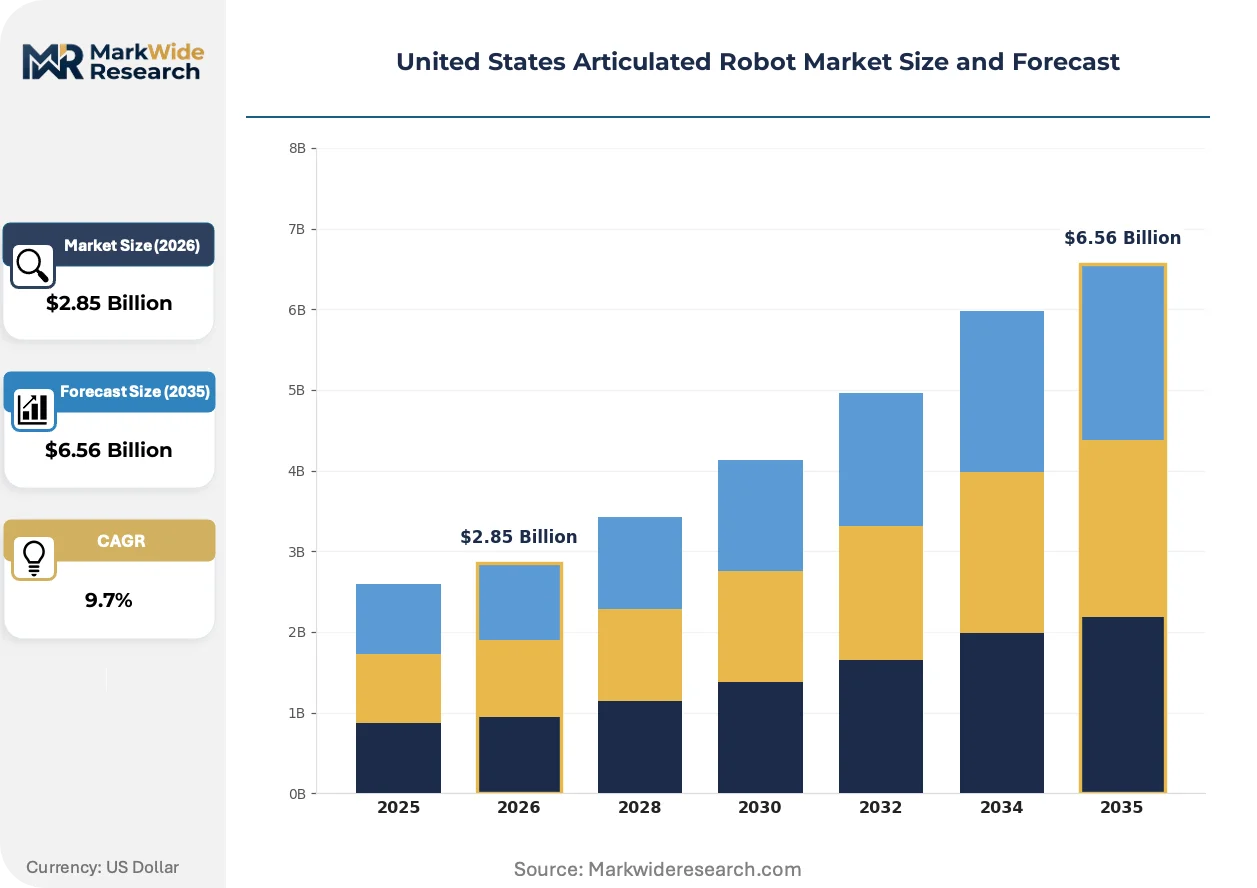
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $6.56 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Welding Robots, Material Handling Robots, Assembly Robots, Painting Robots End User: Automotive, Electronics, Food & Beverage, Pharmaceuticals Technology: Electric, Hydraulic, Pneumatic, Hybrid Application: Manufacturing, Packaging, Inspection, Logistics |
| Companies Covered | FANUC Corporation, ABB Ltd., KUKA AG, Yaskawa Electric Corporation, Kawasaki Heavy Industries Ltd., Mitsubishi Electric Corporation, Denso Wave Incorporated, Seiko Epson Corporation, Universal Robots, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Articulated Robot Market Strategic Shifts & Innovations
Software-integrated robotics is actively compressing hardware differentiation across the United States Articulated Robot Market as arc welding and machine tending workflows demand unified programming environments.
Electric-drive servo technology with integrated torque sensing is displacing pneumatic auxiliary axes in automotive body-in-white assembly lines. Tier-1 Michigan suppliers are adopting these systems at 18-month replacement cycles. This displacement is compressing maintenance intervals while enabling real-time force-feedback quality monitoring that pneumatic systems cannot replicate.
OSHA's pending updates to machine guarding interpretive guidelines are forcing physical safeguarding barrier redesigns for mixed human-robot workcells. Automotive OEMs in Ohio and Indiana are pre-emptively installing collaborative-rated six-axis systems to avoid compliance-driven production halts. The affected segment is responding by consolidating integrator relationships with vendors holding active ANSI/RIA R15.06 certification.
Buying committees in pharmaceutical packaging are unbundling after-sales service contracts from initial hardware procurement. Midwest distribution centers for generic drug manufacturers are negotiating separate multi-year maintenance agreements with third-party technicians rather than captive OEM service arms. This pattern is most visible in Illinois and Wisconsin cleanroom operations where FDA validation requirements create switching costs that favor specialized independent service providers.
United States Articulated Robot Market Segmentation
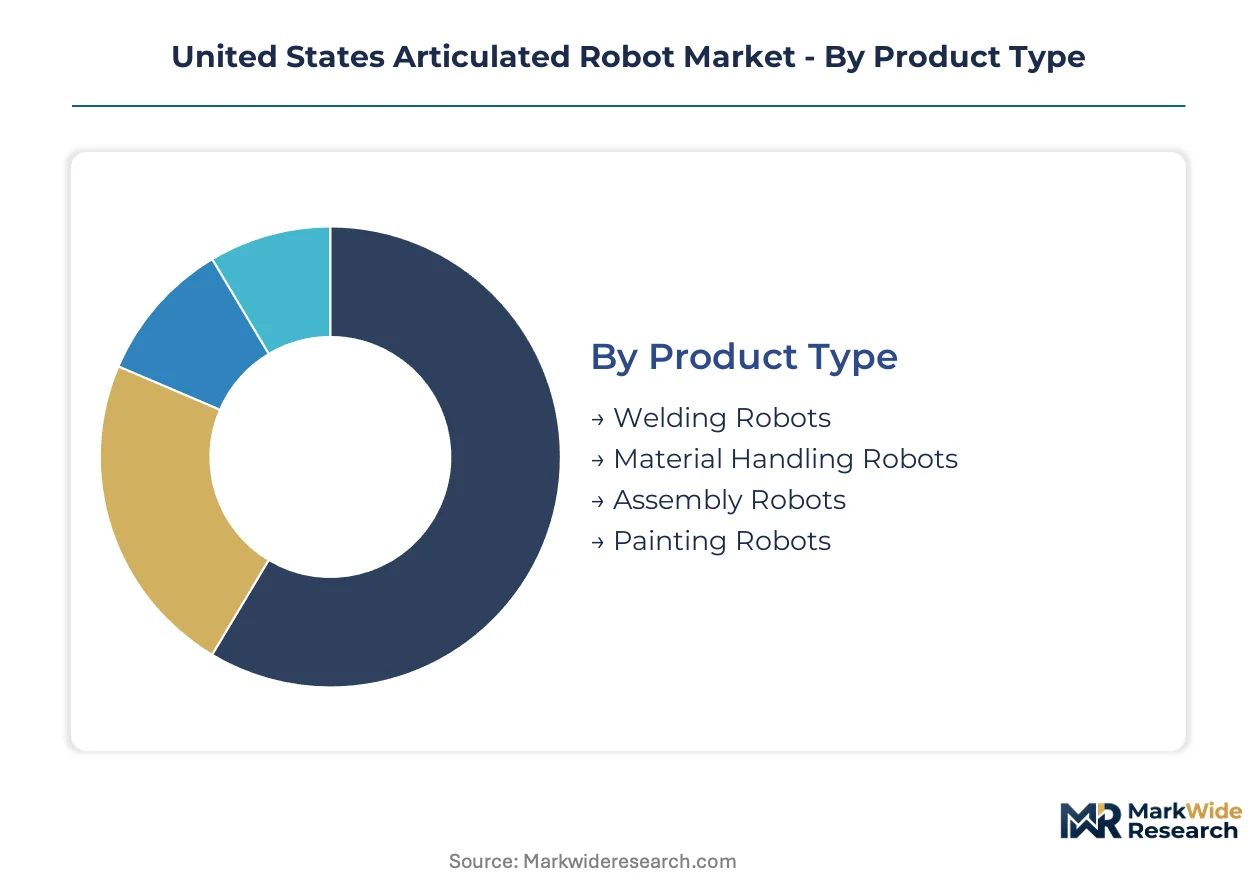
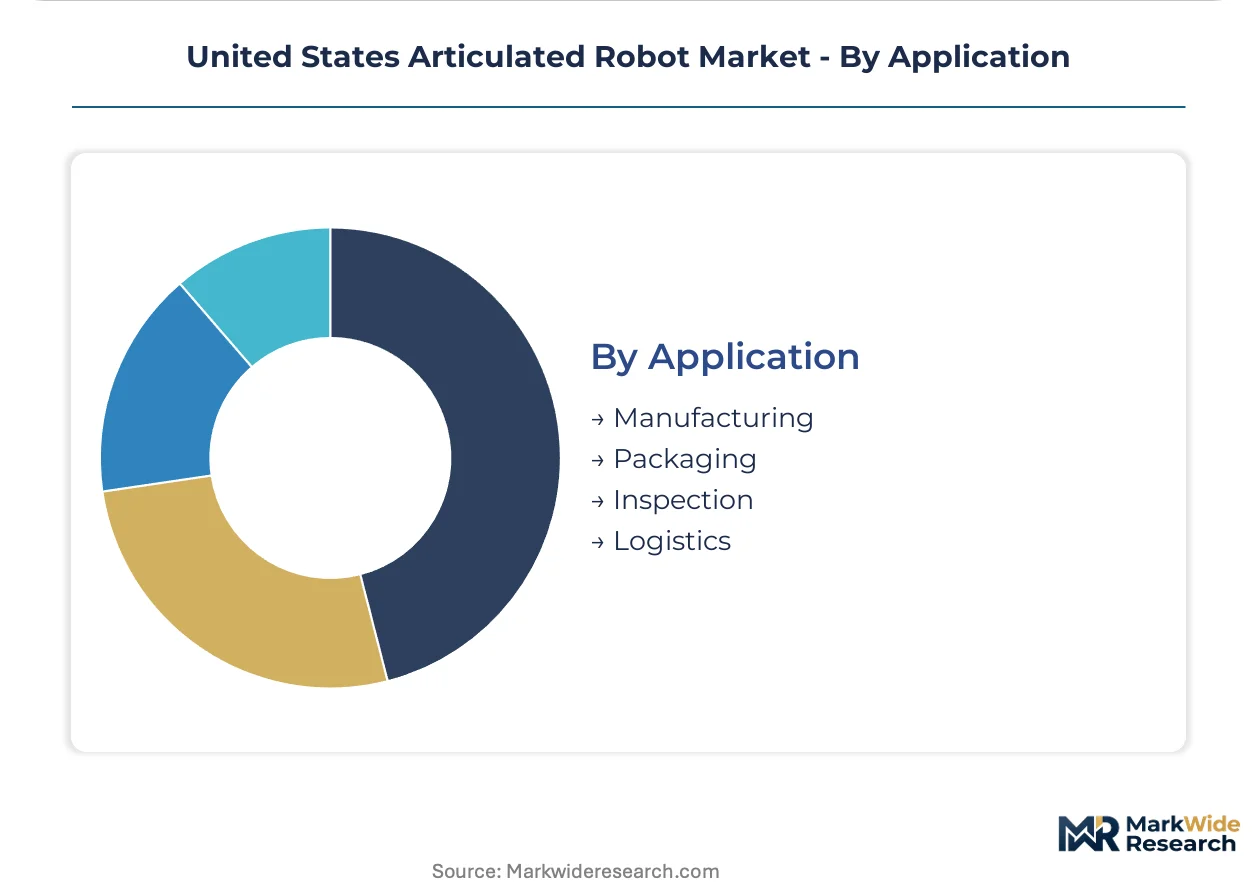
Articulated robot procurement patterns in the United States diverge sharply across manufacturing verticals, with automotive OEMs prioritizing six-axis precision while pharmaceutical buyers emphasize FDA-validated inspection protocols. Understanding these segment boundaries clarifies why integrators in Michigan and Ohio maintain divergent inventory strategies despite serving adjacent geographies.
Product Type:
Substitution pressure from collaborative cobots and Cartesian gantry systems weighs heaviest on painting and basic material handling configurations, where payload precision requirements remain forgiving.
- Material Handling Robots:Four-to-six-axis configurations dominate automotive stamping and electronics distribution centers with repeatability below 0.1 millimeter. Michigan Tier-1 suppliers are retrofitting legacy four-axis systems with collaborative force-limiting variants to satisfy OSHA machine guarding updates.
- Welding Robots:Arc welding and spot welding articulated systems integrate real-time seam tracking via software-integrated robotics. Ohio River Valley automotive body-in-white lines are displacing pneumatic auxiliary axes with electric-drive servo technology bearing integrated torque sensing.
- Assembly Robots:Precision electrode stacking for electric vehicle battery cell-to-pack workflows demands six-axis articulation with sub-millimeter repeatability.
- Painting Robots:Explosion-proof electric-drive systems serve automotive finishing lines with ATEX-compliant sealed housings.
Material handling robots anchor the volume base while welding robots gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive automotive deployments from pharmaceutical installations where software validation costs dominate total ownership economics.
- Automotive:Electric vehicle battery assembly is accelerating six-axis robot deployment across Michigan and Ohio for thermal interface material application and cell stacking. FANUC, ABB, and KUKA proprietary programming environments fragment technician portability across the Great Lakes installation base.
- Electronics:Cleanroom-rated articulated systems handle semiconductor wafer transfer and display panel assembly with ISO Class 4 particulate compliance.
- Pharmaceuticals:FDA 21 CFR Part 11 electronic records requirements impose six-figure software validation burdens that filter vendor eligibility for automated visual defect detection lines.
- Food & Beverage:IP69K washdown-rated electric-drive robots serve high-pressure sanitary cleaning protocols in Midwest protein processing facilities.
Automotive absorbs the heaviest capital deployment while pharmaceuticals exhibits the most rapid compliance-driven specification escalation.
Technology:
Geographic supply concentration for precision motion components shapes procurement vulnerability across non-vertically integrated system builders.
- Electric:Servo motor technology with integrated torque sensing dominates new installations for precision and energy efficiency. Captive production concentrates in Michigan and Georgia facilities, creating geographic vulnerability for independent integrators.
- Hydraulic:Foundry and forging operations above 500-kilogram payloads retain hydraulic actuation due to electric drive torque density limitations.
- Pneumatic:Auxiliary axis applications in legacy automotive lines face displacement by electric-drive alternatives with real-time force-feedback quality monitoring.
- Hybrid:Combines electric precision for primary axes with hydraulic power for heavy-payload wrist configurations in aerospace structural assembly.
Electric systems command the dominant installation share while hybrid architectures climb fastest in defense-aerospace certification pathways.
Application:
Customer type bifurcation separates high-volume automotive manufacturing from inspection applications where FDA validation creates specialized vendor ecosystems.
- Manufacturing:Body-in-white assembly and battery cell stacking in Michigan and Ohio absorb the majority of six-axis articulated system procurement.
- Inspection:Automated visual defect detection in pharmaceutical cleanrooms represents the most quickly expanding demand pocket due to FDA validation requirements for electronic records compliance.
- Packaging:Midwest generic drug distribution centers are unbundling after-sales service contracts from hardware procurement, negotiating separate multi-year maintenance agreements with third-party technicians.
- Logistics:Electronics distribution centers in Illinois and Wisconsin deploy articulated systems for mixed-SKU palletizing with vision-guided depalletizing.
Manufacturing retains the deepest installed base while inspection demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety mandates and NIST cybersecurity frameworks anchor the United States Articulated Robot Market, concentrating procurement decisions across the Great Lakes manufacturing corridor where automotive electrification accelerates robot deployment.
Michigan
Electric vehicle battery assembly lines in Michigan drive six-axis robot procurement for cell stacking and thermal interface material application. OSHA machine guarding standards force Tier-1 suppliers to retrofit legacy four-axis systems with collaborative force-limiting variants. The Detroit-Warren-Dearborn metropolitan area hosts the densest concentration of FANUC captive servo motor production facilities.
Ohio
Automotive body-in-white assembly in Ohio River Valley plants accelerates displacement of pneumatic auxiliary axes with electric-drive servo technology. ANSI/RIA R15.06 safety requirements shape integrator selection for mixed human-robot workcells. Cleveland-Akron and Cincinnati metropolitan clusters absorb the majority of phased four-axis to six-axis migration projects.
Indiana
Pre-emptive collaborative robot installation in Indiana automotive OEMs avoids pending OSHA machine guarding interpretive guideline disruptions. NIST cybersecurity framework alignment filters vendor eligibility for connected operational technology networks. The Indianapolis-Carmel-Anderson metro anchors Midwest distribution center automation for electronics and pharmaceutical logistics.
Illinois
Pharmaceutical packaging operations in Illinois unbundle after-sales service contracts from hardware procurement, negotiating separate multi-year maintenance agreements. FDA 21 CFR Part 11 electronic records requirements impose software validation burdens that favor specialized independent service providers. Chicago-Naperville-Elgin cleanroom facilities represent the fastest-expanding inspection application demand pocket.
Wisconsin
Generic drug distribution centers in Wisconsin deploy articulated systems for vision-guided depalletizing under FDA-validated protocols. ISO Class 4 particulate compliance requirements concentrate procurement among cleanroom-rated system builders. The Milwaukee-Waukesha metropolitan area anchors Midwest electronics distribution automation for mixed-SKU palletizing workflows.
United States Articulated Robot Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive production of precision motion components distinguishing the upper tier from non-vertically integrated system builders. The market structure compresses around software-integrated robotics capabilities as hardware differentiation erodes across arc welding and machine tending workflows. Three archetypes dominate: vertically integrated Japanese manufacturers with captive servo motor facilities, European software-centric specialists targeting collaborative applications, and diversified industrial conglomerates with defense-aerospace certification pathways. Competitive moves concentrate on strategic partnerships for cybersecurity compliance and capacity expansion in Great Lakes corridor service networks.
Among Japanese integrated manufacturers, FANUC Corporation and Yaskawa Electric Corporation exemplify the captive-production archetype with in-house servo motor supply chains. ABB Ltd. occupies a position representing European software-centric specialization, while KUKA AG anchors the defense-aerospace certification tier. These three companies collectively illustrate the strategic bifurcation between hardware-integrated and software-differentiated competitive positioning across the United States installation base.
| Leading Market Players |
|---|
| FANUC Corporation |
| ABB Ltd. |
| KUKA AG |
| Yaskawa Electric Corporation |
| Kawasaki Heavy Industries Ltd. |
| Mitsubishi Electric Corporation |
| Denso Wave Incorporated |
| Seiko Epson Corporation |
| Universal Robots |
| Others |
Cost & Logistics Intelligence
Sixteen-week servo motor lead times from Michigan and Georgia captive facilities concentrate pricing power among vertically integrated Japanese manufacturers while compressing margins for non-integrated system builders across the Great Lakes corridor. This inventory tightness amplifies geographic price spreads between Tier-1 automotive OEMs with long-term offtake agreements and mid-size integrators exposed to spot-market component volatility.
Pricing Analysis
Geographic price spreads of 12-18 percent separate Michigan-based Tier-1 automotive OEMs with captive service contracts from Ohio River Valley mid-size integrators purchasing on spot markets. Three-tier pricing structure across premium certified, standard compliance, and economy non-validated levels dominates procurement, with FDA 21 CFR Part 11 validation tiers commanding the widest spreads. Cost compression in economy non-validated tiers is intensifying because Chinese electric-drive component imports are displacing legacy pneumatic auxiliary axis suppliers. Tier-1 automotive OEMs exhibit lowest price sensitivity due to total-cost-of-ownership procurement frameworks, whereas generic pharmaceutical distributors in Illinois and Wisconsin demonstrate highest sensitivity to unbundled service contract pricing.
Supply Chain Analysis
Inbound logistics costs through Port of Long Beach congestion and trans-Pacific container availability constraints are elevating landed costs for Japanese and European robot controller imports. Geographic supply concentration centers on Japan for precision servo motors, Germany for heavy-payload harmonic drives, and China for electric-drive power electronics. Raw material dependencies rest on rare-earth magnets for motor torque density, high-purity copper for winding efficiency, and semiconductor-grade silicon for encoder precision. Single-source vulnerability in Michigan and Georgia captive servo production creates geographic concentration risk for non-vertically integrated integrators. Distribution runs through authorized OEM service networks in Detroit-Warren-Dearborn, Cleveland-Akron, and Chicago-Naperville-Elgin metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated Tier-1 automotive OEMs in Michigan and Ohio as procurement committees centralize robot system purchasing across multi-plant footprints, fragmenting integrator pricing leverage.
For Market Incumbents: Compound defensive positioning through captive servo motor capacity expansion in Georgia and ANSI/RIA R15.06 certification pre-emption ahead of OSHA machine guarding guideline updates. Deepen software-integrated robotics R&D in arc welding and machine tending workflows to offset hardware commoditization pressure from Chinese electric-drive imports. Lock in Tier-1 automotive OEMs with multi-year cybersecurity compliance service bundles anchored to NIST framework alignment. For New Entrants and Emerging Players: FDA 21 CFR Part 11 validation fast-tracks for pharmaceutical cleanroom inspection applications open the most penetrable white-space corridor, as incumbent OEM service arms struggle with six-figure software validation cost absorption. Target Illinois and Wisconsin generic drug distribution centers with unbundled third-party maintenance agreements that undercut captive OEM pricing by 20-30 percent. Pursue defense-aerospace certification partnerships with Department of Defense supplier standards as the primary go-to-market angle, leveraging heavy-payload hybrid electric-hydraulic architectures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across collaborative six-axis system manufacturing as force-limiting sensor integration and real-time torque feedback electronics raise unit production costs. Long-term viability across the analysis window favors acquisition targets with active ANSI/RIA R15.06 certification and established NIST cybersecurity framework implementation track records. Watch for inflection in Ohio River Valley four-axis to six-axis migration project backlogs as the demand signal indicating sustained replacement cycle momentum.| Strategic Initiative | Industry Significance |
|---|---|
| ANSI/RIA R15.06 Certification Pre-emption | OSHA machine guarding updates will filter integrator eligibility in Michigan automotive stamping plants. |
| NIST Cybersecurity Framework Alignment | Connected operational technology networks in Indiana OEMs face ransomware exposure requiring encrypted retrofit investment. |
| Captive Servo Motor Capacity Expansion | Georgia and Michigan facility additions reduce geographic vulnerability for Japanese integrated manufacturers. |
| Software-Integrated Robotics R&D | Unified programming environments for arc welding compress hardware differentiation across ABB and KUKA positioning. |
| Defense-Aerospace Certification Pathway | Department of Defense supplier standards remain underpenetrated by non-specialized integrators in heavy-payload segments. |
Research Approach
A spread of perspectives from robot system integrators, Tier-1 automotive procurement directors, pharmaceutical cleanroom operations managers, and FDA validation consultants converged on the working assumptions shaping this analysis. Primary fieldwork with Michigan and Ohio plant engineers, FANUC and ABB aftermarket service heads, and NIST cybersecurity framework auditors combined with secondary validation from SEC 10-K filings, OSHA machine guarding interpretive guidelines, FDA 21 CFR Part 11 enforcement records, and IHS Markit automotive production databases. Bottom-up unit shipment estimates triangulated against top-down capital expenditure disclosures from major automotive OEMs.
Segmentation dimensions modeled include product type articulation configuration, end-user vertical adoption intensity, technology drive architecture, and application workflow complexity across the projection horizon. CAGRs were derived from installed base replacement cycle analysis and electric vehicle battery assembly line expansion trajectories. Forecast inputs incorporated OSHA regulatory timeline assumptions, NIST cybersecurity compliance cost curves, and FANUC-ABB-KUKA proprietary programming environment fragmentation effects on technician availability.
Decision-makers should treat outputs as directional under sustained electric vehicle production growth and OSHA machine guarding enforcement intensity assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions without contingency for trade policy shocks or rare-earth magnet supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Gantry Industrial Robots Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Soft Exoskeleton Market
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Logistics Robots Market
Robotics and Automation
Automotive Robotic Painting Market
Robotics and Automation
Motion Control Software in Robotics Market
Robotics and Automation
Asia-Pacific Robotics and Automation Actuators Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
AGV Intelligent Management Systems Market
Robotics and Automation
Japan Articulated Robot Market