
 United Kingdom Cloud Robotics Market | 2026-2036
United Kingdom Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Cloud Robotics Market Insights
The UK Net Zero Strategy and associated industrial decarbonisation mandates are expanding requirements for energy-efficient automated systems across British manufacturing facilities. SLAMcore leverages proprietary spatial intelligence algorithms to anchor its position in autonomous navigation for mobile robotics platforms. Oxa competes through its focus on autonomous vehicle-to-cloud integration for logistics applications. Dexory differentiates by controlling hardware-software stack development for warehouse inventory management systems.
Cloud robotics denotes networked robotic systems that offload computation, data storage, and machine learning model training to remote cloud infrastructure, operating through latency-optimised 5G or fibre connections with typical response thresholds below 50 milliseconds for real-time control loops. The architecture enables fleet learning across distributed robot deployments, reducing per-unit onboard processing costs while centralising software updates. Industrial robots and autonomous mobile robots currently dominate hardware shipments, though collaborative robots represent the fastest-expanding product category as British SMEs seek flexible automation without dedicated safety caging. Edge computing integration within the technology stack is deepening as manufacturers address latency-sensitive pick-and-place operations and predictive maintenance workloads.
The Health and Safety Executive (HSE) enforces machinery safety standards for collaborative robot installations, while the UK Department for Science, Innovation and Technology coordinates AI governance frameworks affecting cloud-connected autonomous systems. British Standards Institution (BSI) certification requirements for robotic equipment create compliance thresholds that filter smaller technology vendors from enterprise procurement shortlists. Stakeholders must monitor forthcoming amendments to the Product Safety and Metrology Bill, as these provisions will likely impose additional cybersecurity and data localisation obligations on cloud robotics deployments handling operational data across UK industrial sites.
Market Dynamics
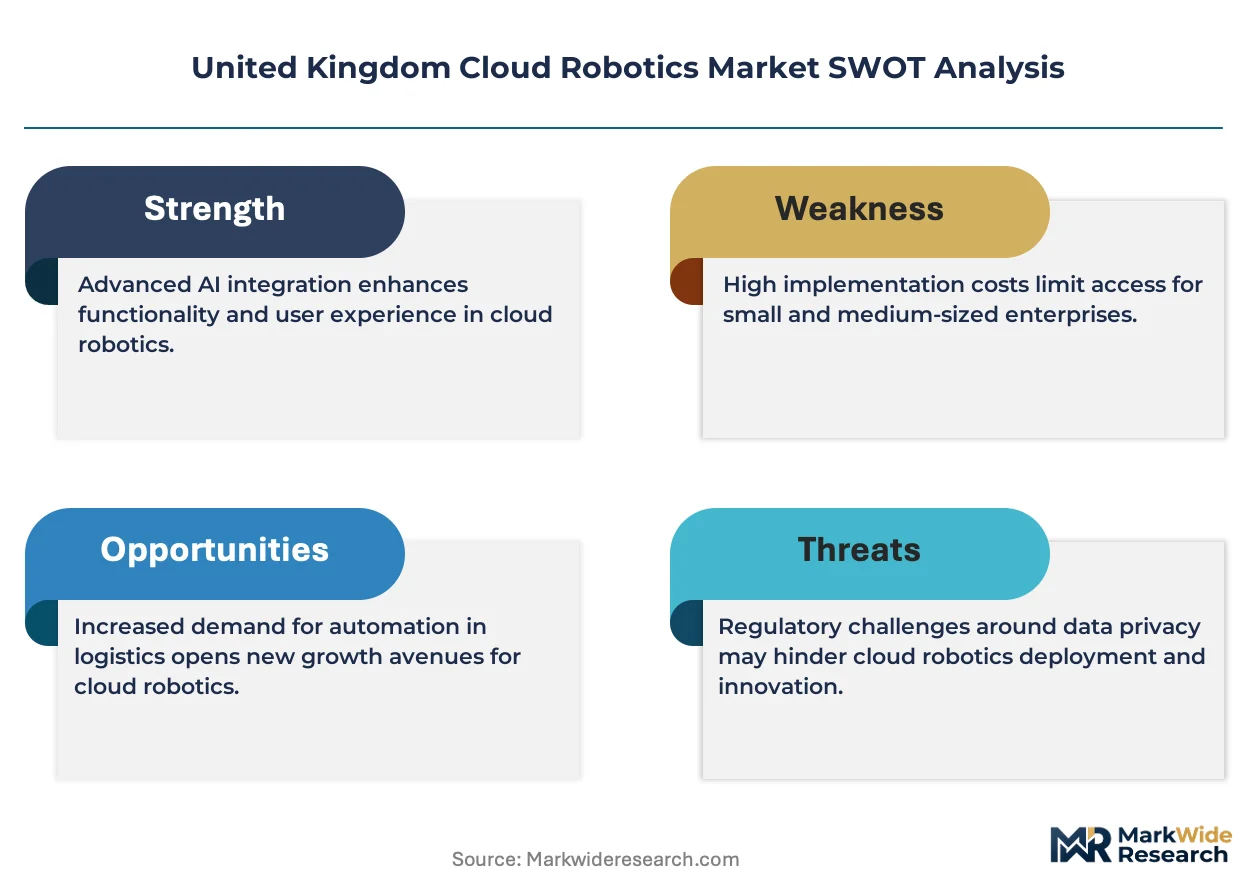
The UK Cloud Robotics Market is experiencing structural transformation driven by the convergence of 5G network rollouts and tightening HSE safety mandates for collaborative robot deployments in British industrial facilities.
Growth Catalysts
- Net Zero industrial mandates:The UK government's decarbonisation requirements for manufacturing facilities are accelerating demand for energy-efficient automated systems that reduce operational emissions.
- Midlands logistics automation:Warehouse operators across the East Midlands and West Midlands are deploying autonomous mobile robots to address labour availability constraints in e-commerce fulfilment centres.
- 5G private network deployments:British telecommunications infrastructure upgrades are enabling sub-50 millisecond latency thresholds essential for real-time cloud robotics control loops.
Market Restraints
- BSI certification barriers:British Standards Institution robotic equipment certification requirements filter smaller technology vendors from enterprise procurement shortlists, concentrating supplier options.
- Legacy system integration costs:Manufacturing facilities in Greater Manchester and the West Midlands face substantial capital requirements to retrofit existing production lines for cloud-connected robotics.
- Cybersecurity infrastructure gaps:The forthcoming Product Safety and Metrology Bill amendments will impose additional data localisation obligations that many current deployments lack technical readiness to satisfy.
Strategic Opportunities
- SME collaborative robot penetration:Small and medium enterprises across South East England represent underpenetrated demand for flexible automation solutions requiring no dedicated safety caging.
- Fleet learning monetisation:Cloud architecture enables centralised machine learning model training across distributed robot deployments, creating recurring software revenue streams from operational data.
- Edge-cloud hybrid architectures:Convergence of edge computing with centralised cloud processing addresses latency-sensitive pick-and-place operations while maintaining fleet coordination capabilities.
Industry Challenges
- Interoperability standardisation delays:Absence of unified communication protocols between cloud robotics platforms and existing warehouse management systems complicates multi-vendor deployments.
- Specialised technician scarcity:British manufacturing regions face acute shortages of engineers qualified to maintain cloud-connected autonomous systems and troubleshoot 5G-dependent control failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Cloud Robotics Market |
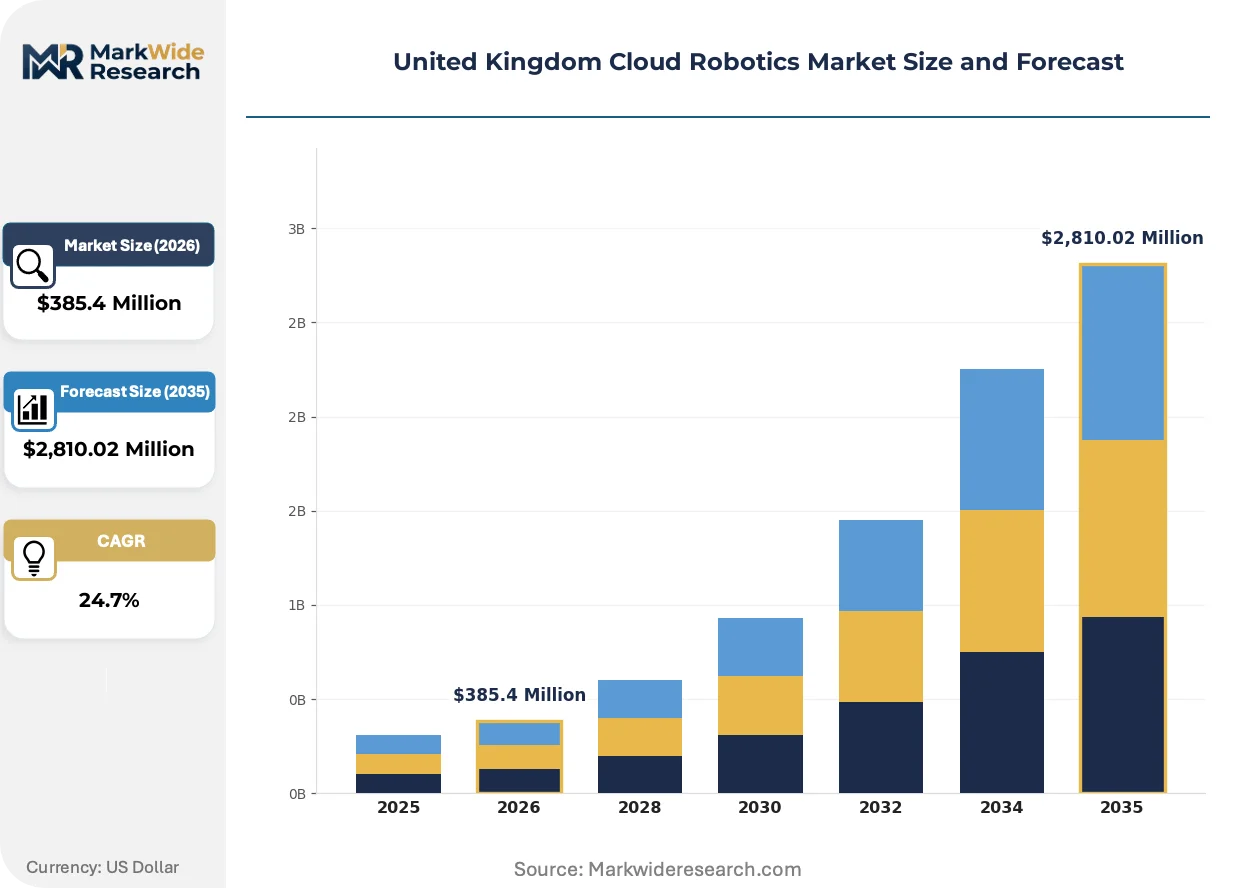
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $2,810.02 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Service Robots, Collaborative Robots, Autonomous Mobile Robots Technology: Machine Learning, Computer Vision, Natural Language Processing, Edge Computing Application: Warehouse Automation, Agriculture Automation, Healthcare Assistance, Manufacturing Automation End User: Logistics Providers, Crop Management Firms, Medical Facilities, Production Plants |
| Companies Covered | Ortelio Ltd., Oxa, Automata, SLAMcore, Dexory, Neuracore, BOW, Masters of Pie, TM Robotics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Cloud Robotics Market Trends and Innovations
Edge computing architectures are reshaping how British manufacturers balance computational loads between on-device processing and centralised cloud infrastructure for latency-critical operations.
Edge computing nodes are integrating directly into autonomous mobile robot hardware to handle real-time obstacle avoidance and path planning. Automotive suppliers along the West Midlands corridor are deploying these hybrid systems at scale. The technology is integrating predictive maintenance workloads that previously required full cloud offload, compressing response times for safety-critical functions.
The UK Department for Science, Innovation and Technology is coordinating AI governance frameworks affecting cloud-connected autonomous systems. These provisions are forcing robotics vendors to implement explainable decision-making algorithms for regulatory compliance. Collaborative robot manufacturers serving British SMEs are most affected, adapting product roadmaps to accommodate forthcoming algorithmic accountability requirements.
Capital expenditure models are transitioning from equipment ownership to robotics-as-a-service arrangements among Midlands warehouse operators. Third-party logistics providers are displacing traditional hardware procurement with operational expenditure contracts bundling maintenance and software updates. This shift concentrates most visibly among e-commerce fulfilment centres in the East Midlands where seasonal volume fluctuations demand flexible automation scaling.
United Kingdom Cloud Robotics Market Segmentation
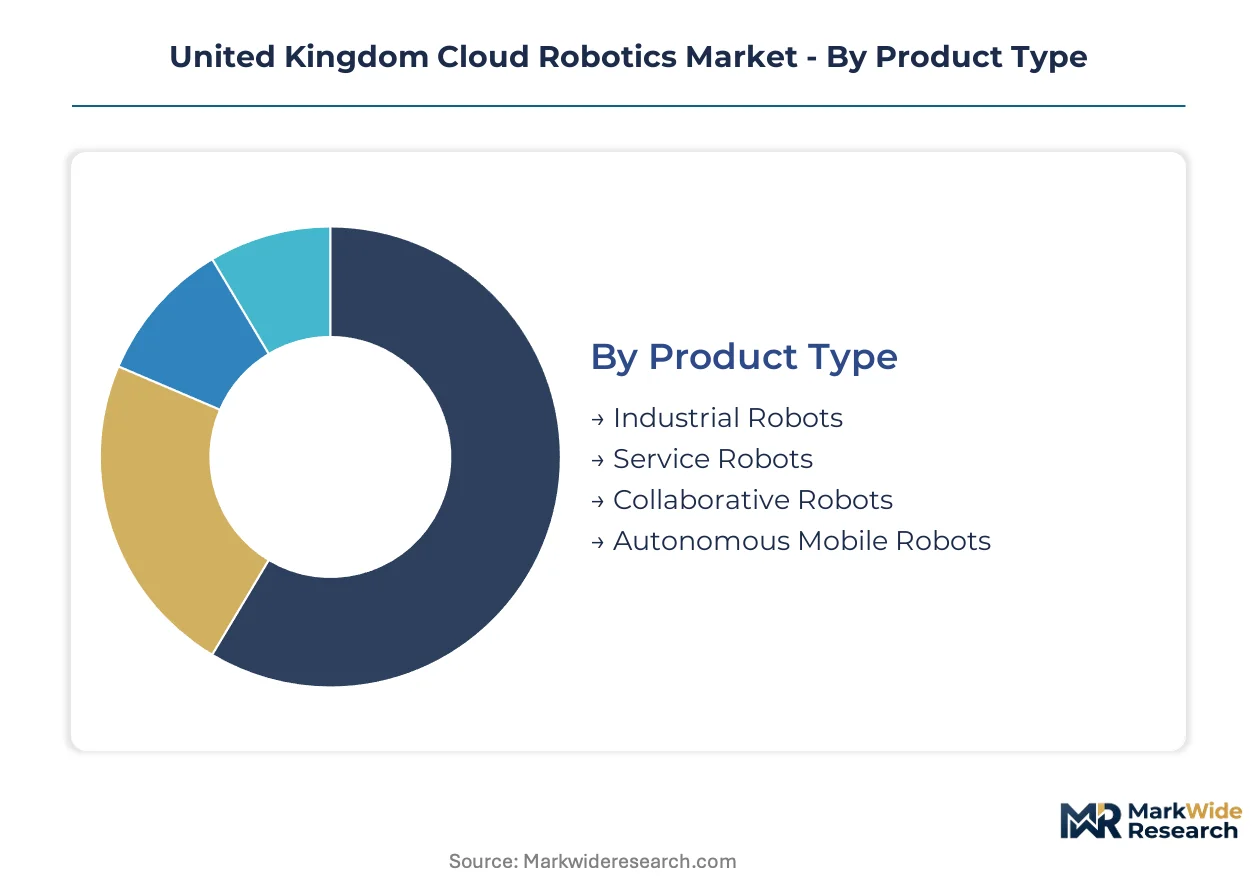
Cloud robotics segmentation in the United Kingdom reveals how computational offloading, hardware form factors, and sector-specific deployment constraints reshape procurement patterns across British industrial facilities. Understanding these dimensions clarifies why Midlands logistics operators prioritise autonomous mobility while West Midlands manufacturers favour collaborative systems.
Product Type:
Industrial robots dominate unit shipments by volume, though collaborative and autonomous mobile platforms command premium pricing through software-defined capabilities and reduced installation overhead.
- Industrial Robots:Heavy-duty articulated systems with six-plus degrees of freedom handle welding, painting, and assembly in West Midlands automotive plants. Greater Manchester production facilities favour these for high-throughput operations where cloud connectivity enables centralised production analytics without line stoppages.
- Collaborative Robots:Force-limited articulated arms operate alongside human workers without safety caging, integrating torque sensors and vision systems for adaptive task execution. South East England SMEs drive demand here, seeking flexible automation that accommodates batch-size-one manufacturing without dedicated perimeter guarding.
- Service Robots:Non-industrial platforms perform cleaning, security patrol, and facility maintenance across British commercial properties.
- Autonomous Mobile Robots:Lidar-equipped vehicles navigate dynamic warehouse environments using SLAM-based localisation.
Today's leader: Industrial Robots. Tomorrow's challenger: Collaborative Robots.
Technology:
Edge Computing and Computer Vision concentrate investment where latency constraints collide with real-time decision requirements in British manufacturing environments.
- Machine Learning:Cloud-based model training enables fleet-wide performance improvements as operational data aggregates from distributed robot deployments across Midlands fulfilment networks.
- Computer Vision:Convolutional neural networks process visual data for object recognition, quality inspection, and navigation guidance. East Midlands warehouse operators deploy these systems for parcel dimensioning and damage detection at inbound receiving stations.
- Natural Language Processing:Voice command interfaces and human-robot dialogue systems enable intuitive programming for non-technical operators in healthcare assistance deployments.
- Edge Computing:On-device processing nodes handle sub-50 millisecond control loops locally while cloud coordination manages fleet orchestration.
Computer Vision anchors current procurement budgets. Edge Computing is climbing the fastest as 5G private networks mature.
Application:
Warehouse automation absorbs the majority of cloud robotics capital expenditure, though manufacturing automation offers higher per-unit software attach rates through predictive maintenance modules.
- Warehouse Automation:Goods-to-person systems, automated sortation, and inventory tracking dominate East Midlands and South East logistics corridors where e-commerce volume growth outpaces labour availability.
- Manufacturing Automation:Cloud-connected production lines enable centralised quality analytics and predictive maintenance across West Midlands automotive supplier networks.
- Agriculture Automation:Autonomous platforms perform crop monitoring, precision spraying, and harvesting assistance in East Anglia and Lincolnshire farming regions.
- Healthcare Assistance:Robotic systems support patient mobility, medication delivery, and surgical assistance in NHS trusts and private medical facilities.
Warehouse Automation captures current deployment scale. Manufacturing Automation shows the steepest expansion trajectory through industrial decarbonisation mandates.
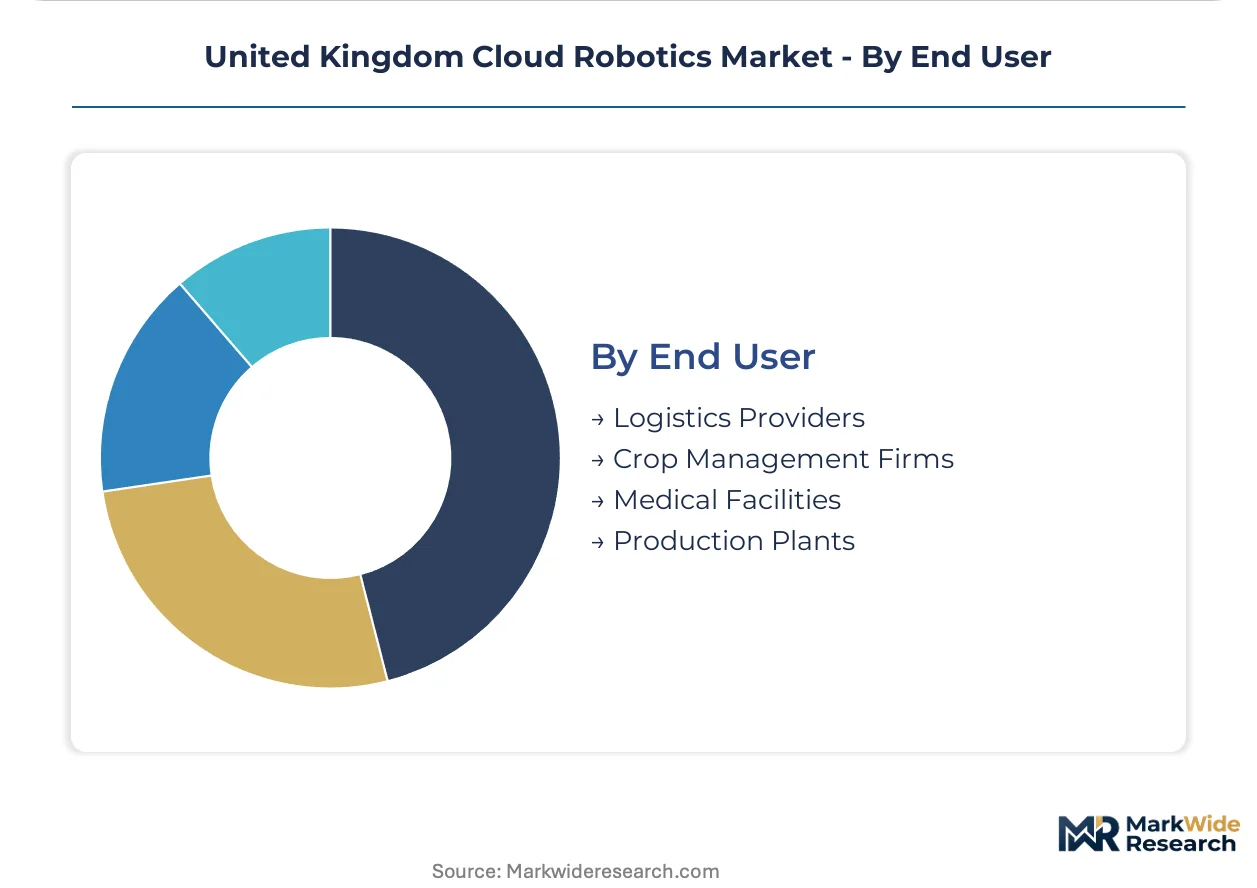
End User:
Logistics providers and production plants represent mature demand with established procurement processes, while medical facilities and crop management firms present emerging adoption curves with distinct integration challenges.
- Logistics Providers:Third-party warehouse operators across the Midlands deploy autonomous mobile robots at scale, with seasonal volume fluctuations driving robotics-as-a-service contract structures.
- Production Plants:Discrete and process manufacturers in Greater Manchester and the West Midlands integrate cloud robotics for quality consistency and energy efficiency compliance.
- Medical Facilities:NHS trusts and private hospitals evaluate collaborative platforms for patient handling and sterile logistics, constrained by infection control protocols and clinical validation requirements.
- Crop Management Firms:Large-scale agricultural operators in eastern England trial autonomous platforms for soil monitoring and targeted intervention.
Logistics Providers anchor current revenue concentration. Medical Facilities represent the most complex procurement pathway due to regulatory validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in the East Midlands and West Midlands anchor British cloud robotics deployment, with university research clusters feeding directly into regional automation supply chains.
Greater London and South East
E-commerce fulfilment demand from Thames Valley distribution hubs drives autonomous mobile robot procurement. The Health and Safety Executive enforces machinery safety standards for collaborative installations. Slough and Milton Keynes warehouse operators deploy goods-to-person systems at scale.
West Midlands
Automotive supplier networks require predictive maintenance modules for welding and assembly lines. The UK Department for Science, Innovation and Technology coordinates AI governance frameworks affecting cloud-connected systems. Coventry and Birmingham production facilities integrate heavy-duty articulated robots for quality analytics.
East Midlands
Seasonal volume fluctuations push third-party logistics providers toward robotics-as-a-service contracts. British Standards Institution certification requirements filter smaller vendors from enterprise procurement shortlists. Nottingham and Leicester fulfilment centres lead autonomous mobile robot density.
Greater Manchester
Discrete manufacturers seek energy-efficient automated systems for Net Zero compliance. The forthcoming Product Safety and Metrology Bill amendments impose data localisation obligations on cloud deployments. Oldham and Bolton industrial parks retrofit production lines for cloud connectivity.
Scotland
North Sea oil services firms trial autonomous platforms for facility maintenance and inspection. Scottish Enterprise innovation funding supports robotics startups developing edge computing architectures. Aberdeen and Glasgow research institutes collaborate on fleet learning algorithms for harsh environments.
United Kingdom Cloud Robotics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the UK cloud robotics landscape. Established automation vendors with captive hardware manufacturing anchor the premium tier, while software-native entrants capture mid-market share through subscription pricing. The vendor base stratifies into three archetypes: full-stack hardware-software integrators, pure-play navigation software specialists, and cloud infrastructure providers. Dominant competitive moves include strategic partnerships between robotics vendors and telecommunications operators for private 5G deployments, plus portfolio diversification into adjacent warehouse management software.
Within the navigation software specialist tier, SLAMcore and Neuracore exemplify asset-light business models built on proprietary spatial intelligence algorithms. Among full-stack hardware-software integrators, Dexory and Automata occupy positions controlling end-to-end development for inventory management and collaborative automation respectively. Oxa represents the autonomous vehicle-to-cloud integration archetype, anchoring logistics-focused deployments.
| Leading Market Players |
|---|
| Ortelio Ltd. |
| Oxa |
| Automata |
| SLAMcore |
| Dexory |
| Neuracore |
| BOW |
| Masters of Pie |
| TM Robotics |
| Others |
Pricing and Supply Chain Analysis
Cloud compute infrastructure costs cascade through UK cloud robotics pricing tiers, with hyperscaler processing fees and 5G private network provisioning expenses concentrating margin pressure on mid-market vendors serving East Midlands logistics operators.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware ownership from software subscription tiers across British industrial deployments. Robotics-as-a-service contracts bundle maintenance, cloud processing, and fleet management into per-hour operational expenditure models preferred by seasonal warehouse operators. Price differentiation rests on BSI certification grade and 5G network integration depth, with uncertified entrants undercutting premium vendors by fifteen to twenty percent. Cost compression in the mid-tier intensifies because legacy system retrofit requirements inflate total cost of ownership. Small and medium enterprises across South East England exhibit highest price sensitivity, while automotive suppliers in the West Midlands prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Reverse-logistics flows for sensor refurbishment and actuator remanufacturing are emerging as margin recovery channels for UK robotics vendors managing distributed fleet deployments. Hardware assembly draws from China, Germany, and Taiwan for precision gearboxes, lidar modules, and edge computing processors. Lithium-ion power systems, optical encoders, and carbon-fibre structural components anchor bill-of-materials volatility. Single-source vulnerability concentrates in solid-state lidar supply where Israeli and American vendors dominate technical roadmaps. Distribution runs through systems integrators and direct-to-plant channels, with Midlands-based engineering consultancies controlling specification influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK cloud robotics market functions as a regulatory compounder where HSE safety mandate evolution and forthcoming Product Safety and Metrology Bill amendments continuously expand compliance-driven replacement cycles.
For Market Incumbents: Cement market position through captive 5G private network partnerships with British telecommunications operators, insulating against pure-play software entrants. Deepen backward integration into edge computing processor supply chains to offset semiconductor allocation volatility. Prioritise BSI certification maintenance as regulatory thresholds filter smaller competitors from enterprise procurement shortlists. For New Entrants and Emerging Players: Third-party logistics providers in the East Midlands represent the most penetrable channel partner type for robotics-as-a-service market entry. Target SME manufacturing clusters in South East England where flexible collaborative robot demand outstrips incumbent service coverage. Pursue white-label navigation software licensing to established warehouse management system vendors as a capital-light go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where fleet learning data assets concentrate among navigation software specialists lacking hardware manufacturing scale. Five-to-ten year viability favors full-stack integrators controlling both sensor hardware and cloud orchestration layers. Acquisition target archetypes include edge computing architecture startups with Scottish Enterprise innovation funding validation. Monitor HSE collaborative robot safety guideline amendment timing as inflection indicator for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Private Network Partnership | Telecommunications operators Vodafone and BT enable sub-50 millisecond latency thresholds essential for real-time control. |
| BSI Certification Acceleration | British Standards Institution robotic equipment approval filters smaller vendors from enterprise procurement shortlists. |
| Edge Computing Architecture Development | Scottish Enterprise innovation funding supports robotics startups building hybrid processing nodes for latency-critical operations. |
| Fleet Learning Data Monetisation | Centralised machine learning model training across distributed deployments creates recurring software revenue streams. |
| Robotics-as-a-Service Contract Structuring | Operational expenditure models displace capital equipment ownership among seasonal East Midlands fulfilment operators. |
Research Methodology
Direct dialogue with warehouse operations directors, maintenance engineers at West Midlands automotive suppliers, cloud robotics platform engineers, and HSE safety compliance officers grounded qualitative findings in operational reality. Secondary validation drew from UK Department for Science, Innovation and Technology policy disclosures, British Standards Institution certification registries, Health and Safety Executive machinery safety bulletins, and Ofcom 5G spectrum allocation records. Bottom-up unit deployment tracking across Greater Manchester, West Midlands, and East Midlands industrial corridors triangulated against top-down capital expenditure estimates from logistics provider annual filings.
Bottom-up segmentation modeling across product type, technology stack, application vertical, and end-user category generated volume and value outputs throughout the forecast period. Computer vision and edge computing technology trajectories, collaborative robot safety certification timelines, and Net Zero industrial decarbonisation mandate compliance deadlines served as industry-specific forecast inputs. CAGRs were derived from installation base growth rates and software attach rate expansion assumptions.
Revisions become necessary when Product Safety and Metrology Bill amendment provisions materialise with stricter data localisation obligations than currently anticipated. Forecasts reflect assumptions about 5G private network rollout pace, HSE collaborative robot safety standard evolution, and hyperscaler cloud compute pricing stability. Practitioners should monitor HSE machinery safety guideline publication schedules and British Standards Institution certification requirement changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Service Robotics Market
Robotics and Automation
Medical Rehabilitation Robotics Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Self-Driving Floor Scrubbers Market
Robotics and Automation
Robotic Welding Market
Robotics and Automation
United States Agricultural Robots Market
Robotics and Automation
Robot Charging Station Market
Robotics and Automation
Global K-12 Robotic Toolkits Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Lab Robotics Market