
 Aircraft Floor Panels Market | 2026-2036
Aircraft Floor Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Floor Panels Market Analysis
Asset-light leasing and power-by-the-hour service models is fragmenting capital deployment across the supply chain, enabling smaller specialists to secure tooling contracts once reserved for integrated primes. Collins Aerospace leverages vertical integration across aerostructures and interiors to sustain captive demand for proprietary floor systems. Triumph Group competes through specialized fabrication capabilities in bonded honeycomb assemblies. Hexcel Corporation anchors its position through carbon fiber prepreg supply relationships with tier-one panel laminators.
Aircraft floor panels are structural sandwich assemblies, typically combining aluminum or Nomex honeycomb cores with phenolic-impregnated fiberglass or carbon fiber face sheets, engineered to meet strict strength-to-weight ratios and 16g crash load requirements for passenger safety. Their primary purpose is to provide rigid, fire-resistant walking surfaces that integrate seat tracks, cargo tie-downs, and utility routing while minimizing parasitic weight in commercial and military airframes. Honeycomb panels dominate current OEM installations due to decades of certified performance, yet composite panels represent the fastest-growing category as thermoplastic resins displace thermosets for faster cycle times and recyclability. CFRP material adoption is accelerating among defense contractors seeking radar-absorbing properties and fatigue resistance in next-generation platforms.
FAA Part 25.853 flammability standards and EASA CS-25 certification requirements govern smoke density and toxic gas emission limits, directly determining which resin systems and core materials gain airworthiness approval. The EU Green Deal and REACH chemical restrictions are forcing reformulation of legacy phenolic resins, creating compliance costs that favor suppliers with in-house testing laboratories. Stakeholders must monitor evolving MRO Provider retrofit specifications as airlines extend fleet lifecycles rather than acquiring new aircraft, shifting volume toward removable installation types and condition-based replacement protocols.
Market Dynamics
Thermoplastic resin systems are compressing cure cycles from hours to minutes, forcing incumbent phenolic laminators to retool or cede share to automated thermoplastic stamping operations. This materials transition redistributes competitive advantage toward suppliers with in-house resin formulation and rapid-heat-press capabilities.
Growth Catalysts
- Narrow-body commercial aircraft production:Boeing and Airbus backlogs for single-aisle platforms are pulling floor panel volumes upward, with seat-track integration requirements driving specification standardization across OEM programs.
- FAA Part 25.853 flammability mandates:Smoke density and toxic gas emission limits are filtering out non-compliant core materials, advantaging certified honeycomb and thermoplastic suppliers with established test data libraries.
- Carbon fiber prepreg penetration:Defense contractors are specifying CFRP face sheets for radar-absorbing floor assemblies in stealth platforms, opening adjacent demand beyond commercial aviation.
Market Restraints
- Aramid fiber price volatility:Nomex honeycomb core costs swing with petrochemical feedstock indices, compressing laminator margins when long-term OEM contracts lock in fixed pricing.
- Supply concentration in US Pacific Northwest:Boeing's final assembly dominance concentrates tier-one panel demand in a single geography, exposing suppliers to program-specific volume shocks.
- REACH chemical restrictions:The EU Green Deal is forcing reformulation of legacy phenolic resins, raising compliance costs for European suppliers without captive testing laboratories.
Strategic Opportunities
- India defense modernization:The country's PLI scheme for aerospace components is attracting floor panel laminators to establish local stamping and bonding operations for indigenous fighter programs.
- Thermoplastic-thermoset hybrid cores:Fusion bonding of thermoplastic face sheets to thermoset honeycomb is enabling recyclability compliance while retaining crash-load certification.
- Power-by-the-hour MRO contracts:Airlines are unbundling floor panel replacement from heavy maintenance checks, creating standalone procurement channels for removable installation types.
Industry Challenges
- Autoclave capacity scarcity:Large-format bonding equipment requires seven-figure capital commitments, constraining mid-tier entrants from qualifying for OEM direct supply.
- FAA-EASA dual certification timelines:Parallel validation processes for new resin systems extend time-to-revenue by 18-24 months, freezing development capital.
- Legacy fleet retrofit compatibility:Condition-based replacement protocols must interface with 30-year-old seat-track geometries, complicating panel design standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Floor Panels Market |
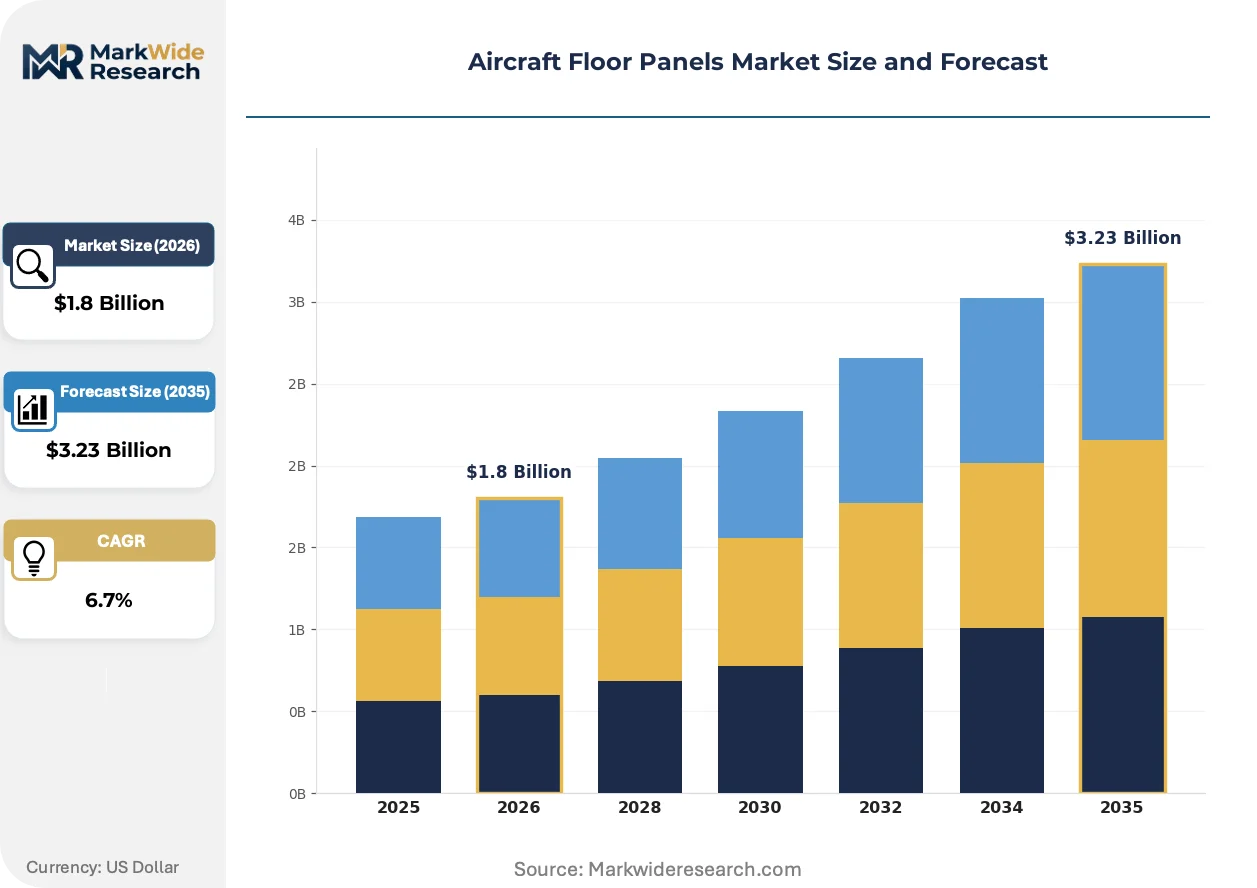
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Honeycomb Panels, Composite Panels, Ply Laminated Panels, Aluminum Panels Material: CFRP, GFRP, Aluminum, Steel End User: OEMs, MRO Providers, Airlines, Defense Contractors Installation Type: Fixed, Removable, Retrofit, Integrated |
| Companies Covered | Collins Aerospace, The Gill Corporation, Triumph Group, Safran SA, EFW GmbH, Singapore Technologies Engineering Ltd, The NORDAM Group LLC, Latecoere SA, Hexcel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Floor Panels Market Emerging Trajectories
Digital thread integration from resin formulation to final assembly is compressing design-validation loops and enabling lot-level traceability demanded by airworthiness authorities. This connectivity layer is becoming as critical as the physical panel itself.
Out-of-autoclave thermoplastic stamping is virtualizing the traditional autoclave bottleneck. Tier-one laminators in Germany and Japan are installing continuous compression molding lines that cure PEEK-impregnated fabrics in under ten minutes. This process virtualization is collapsing lead times for narrow-body programs and shifting capital allocation from batch ovens to robotic handling systems.
EASA CS-25 updates incorporating EU Green Deal sustainability criteria are mandating lifecycle carbon accounting for interior components. Panel suppliers must now document embodied carbon from raw fiber through end-of-life recycling, favoring European laminators with established environmental product declarations and circular material partnerships.
Airline engineering departments are fragmenting procurement authority across technical operations and finance functions, displacing the centralized buyer model that dominated legacy fleet decisions. This organizational shift is most visible at US and Middle Eastern carriers extending aircraft lifecycles, where condition-based replacement contracts now route through separate MRO procurement channels rather than OEM line-fit agreements.
Aircraft Floor Panels Market Segmentation
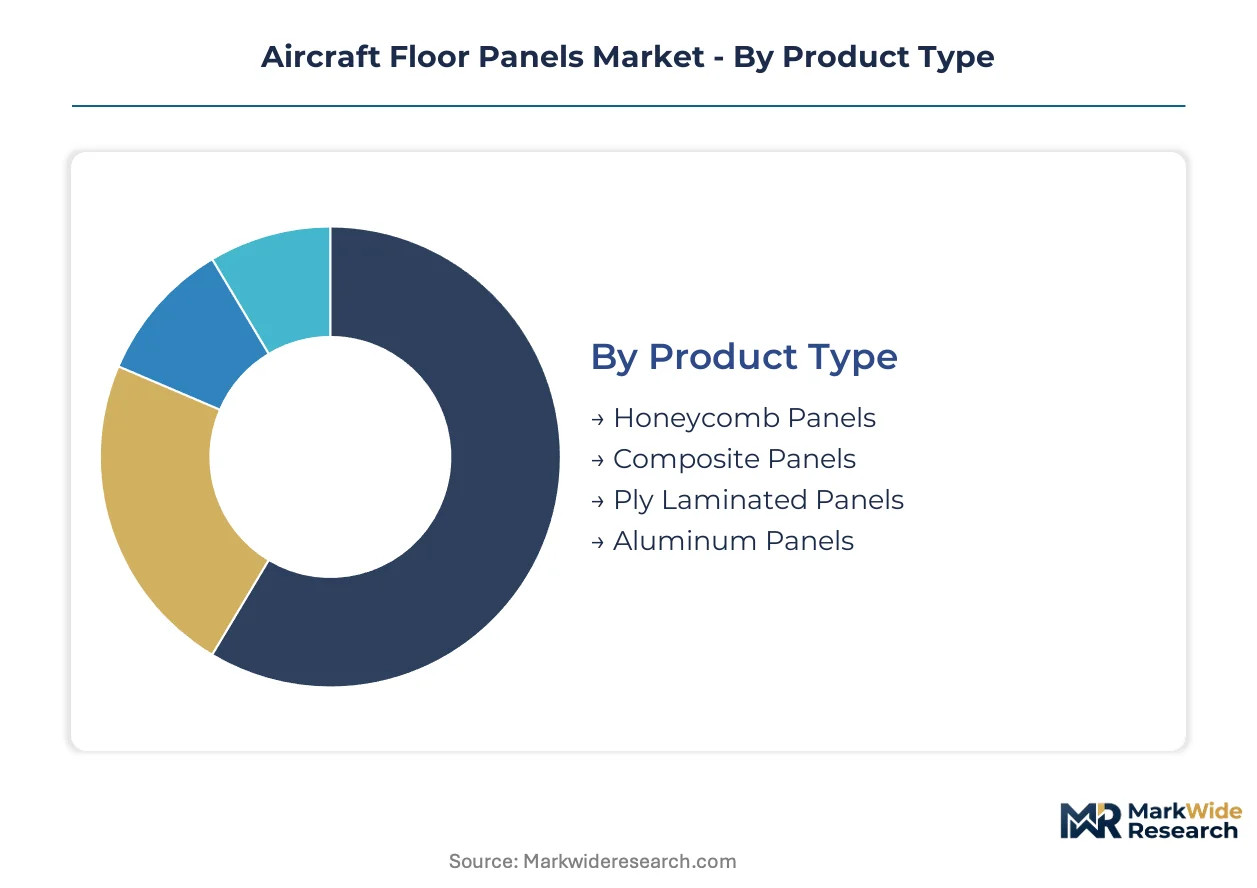
Aircraft floor panel procurement splits across four structural dimensions that determine specification, certification pathway, and margin profile. Product architecture and material selection govern airworthiness compliance, while end-user category and installation method dictate volume timing and replacement cadence.
Product Type:
Cost tier separates legacy aluminum solutions from advanced composite architectures competing on weight reduction and fire performance.
- Honeycomb Panels:Nomex or aluminum honeycomb cores bonded to phenolic-impregnated fiberglass face sheets deliver certified 16g crash-load performance. Boeing and Airbus narrow-body programs in the United States pull the majority of current procurement volume, though thermoset cure cycles constrain margin expansion.
- Composite Panels:Thermoplastic resin systems with continuous fiber reinforcement enable sub-ten-minute stamping cycles and end-of-life recyclability. German and Japanese laminators are installing continuous compression molding lines to capture narrow-body platform demand.
- Ply Laminated Panels:Multi-layer phenolic or epoxy laminates serve regional jet and turboprop applications where cost sensitivity outweighs weight optimization.
- Aluminum Panels:Solid aluminum sheet constructions persist in cargo freighter conversions and legacy fleet retrofits requiring minimal engineering change.
Honeycomb panels command the established base. The steepest expansion runs through composite panels.
Material:
Application requirements—structural loading, radar signature, and flammability—determine material selection across defense and commercial programs.
- CFRP:Carbon fiber prepreg face sheets specified for stealth platform floors deliver radar-absorbing properties and fatigue resistance. US defense contractors are accelerating CFRP adoption for next-generation fighter and bomber programs.
- GFRP:Glass fiber reinforced phenolic systems dominate commercial narrow-body line-fit installations due to established FAA Part 25.853 test libraries and lower raw material cost.
- Aluminum:Sheet and extruded aluminum alloys serve cost-optimized regional aircraft and cargo conversion programs in India and Southeast Asia.
- Steel:Stainless steel reinforcements integrate into high-load zones and galley structures requiring localized impact resistance.
GFRP retains the volume base. CFRP climbs the fastest on defense platform specifications.
End User:
Customer type fragments procurement authority between OEM line-fit engineering and aftermarket technical operations with diverging specification priorities.
- OEMs:Boeing and Airbus engineering departments set baseline specifications that cascade through tier-one aerostructure suppliers. Seat-track integration requirements and program commonality drive standardization across single-aisle platforms.
- MRO Providers:Lufthansa Technik and ST Engineering are unbundling floor panel replacement from heavy maintenance checks, creating standalone procurement channels for removable installation types.
- Airlines:US and Middle Eastern carriers extending fleet lifecycles are routing condition-based replacement contracts through separate technical operations procurement functions.
- Defense Contractors:Lockheed Martin and Northrop Grumman specify CFRP-heavy floor assemblies with radar-absorbing properties for stealth applications.
OEMs anchor the specification base. MRO Providers are gaining the fastest procurement share as fleet lifecycles extend.
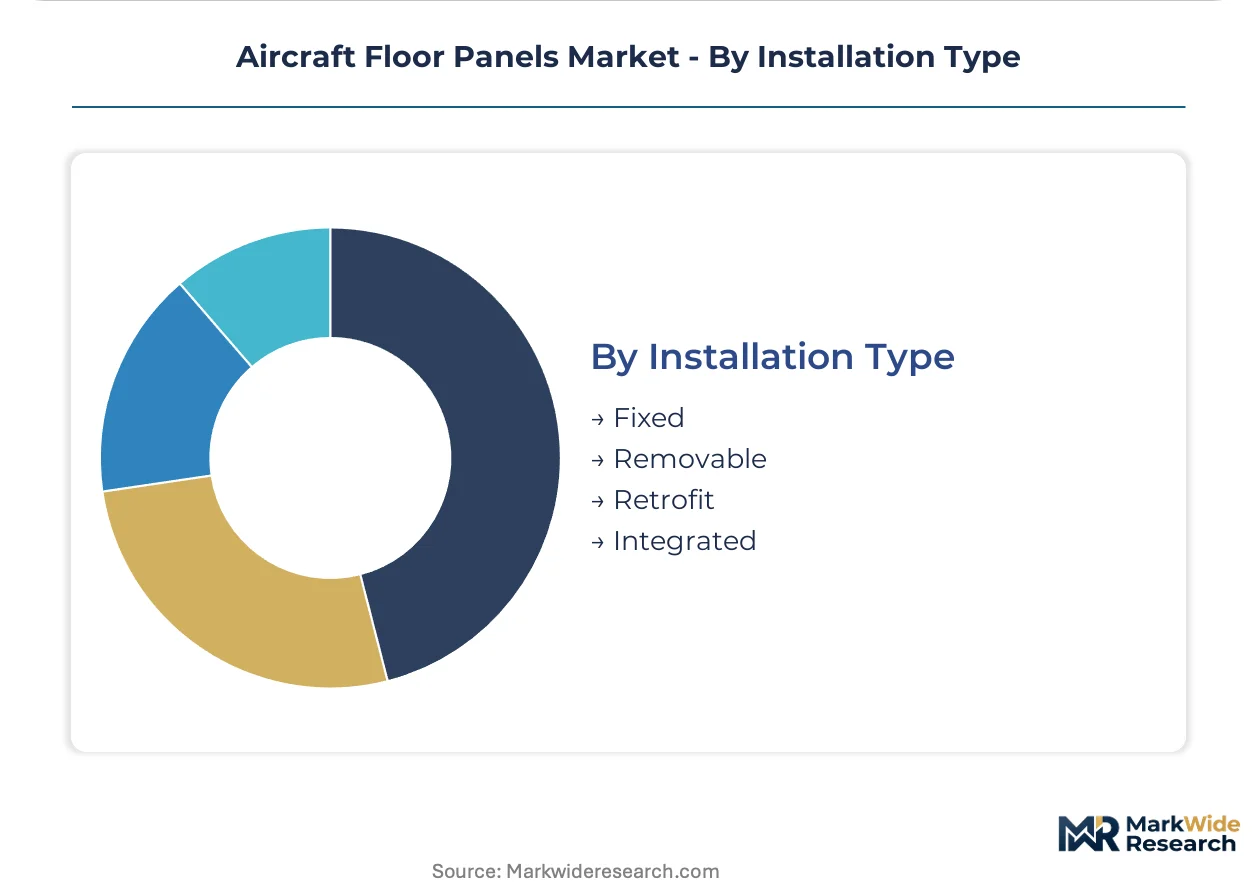
Installation Type:
Volume concentration and replacement frequency diverge sharply between permanent structural bonding and field-removable systems.
- Fixed:Adhesively bonded panels integrated during final assembly provide maximum structural continuity. Boeing's Renton and Everett facilities consume the majority of fixed-installation volume for 737 and 777 programs.
- Removable:Quick-release fastening systems enable rapid cabin reconfiguration and targeted replacement without structural disassembly. Power-by-the-hour contracts at Middle Eastern carriers are accelerating removable specification.
- Retrofit:Replacement panels engineered for 30-year-old seat-track geometries serve legacy fleet life extension programs.
- Integrated:Floor panels factory-bonded to seat tracks and utility routing channels reduce final assembly labor at OEM facilities.
Fixed installation commands the production base. Removable systems are expanding most quickly on MRO contract restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes and defense modernization programs are redistributing floor panel manufacturing capacity across multiple geographies. Boeing's final assembly dominance in the United States concentrates tier-one procurement, while European REACH compliance costs and Asian industrial policies are reshaping supplier location decisions.
United States
Boeing's 737 and 777 programs at Renton and Everett pull the majority of narrow-body floor panel volume. FAA Part 25.853 flammability mandates filter supplier qualification to established honeycomb laminators with certified test libraries. The Pacific Northwest aerospace cluster anchors tier-one panel demand, though program-specific volume shocks expose concentrated supply risk.
Germany
Continuous compression molding lines for thermoplastic stamping are installing near Hamburg and Munich to serve Airbus narrow-body programs. EASA CS-25 updates incorporating EU Green Deal sustainability criteria mandate lifecycle carbon accounting for interior components. Bavarian laminators with established environmental product declarations capture specification preference from European carriers.
Japan
Carbon fiber prepreg supply relationships anchor Japanese material suppliers to defense contractor specifications for stealth platform floors. METI industrial policy supports aerospace composite development through targeted R&D consortia. The Nagoya aerospace cluster hosts tier-two panel fabricators serving regional jet programs and Boeing supply chains.
India
The PLI scheme for aerospace components is attracting floor panel laminators to establish local stamping and bonding operations for indigenous fighter programs. DGFT import substitution policies favor domestic content in defense procurement. Hyderabad and Bangalore industrial corridors are emerging as MRO hubs driving removable installation demand.
United Kingdom
Rolls-Royce supply chain proximity sustains specialist composite fabrication for wide-body engine nacelle-adjacent structures. The Civil Aviation Authority maintains parallel validation protocols with EASA, extending certification timelines for new resin systems. Southwest England manufacturing clusters retain legacy phenolic laminating capacity for regional turboprop retrofits.
Aircraft Floor Panels Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base consolidates around aerostructure integrators with captive interiors divisions and independent honeycomb specialists with certified bonding capabilities. Two strategic archetypes dominate: vertically integrated aerospace conglomerates sustaining proprietary floor system demand, and mid-tier fabricators competing through specialized lamination and rapid-heat-press capacity. Competitive moves center on thermoplastic processing equipment investments and MRO channel partnerships for power-by-the-hour contracts.
Among the named participants, Collins Aerospace and Triumph Group exemplify contrasting strategic positions within the supply hierarchy. Collins Aerospace represents the integrated conglomerate archetype, leveraging aerostructures and interiors breadth to sustain captive demand for proprietary floor systems. Triumph Group occupies the specialist fabricator position, competing through bonded honeycomb assembly capabilities. Hexcel Corporation anchors the material supply tier, with carbon fiber prepreg relationships connecting to tier-one panel laminators across multiple OEM programs.
| Leading Market Players |
|---|
| Collins Aerospace |
| The Gill Corporation |
| Triumph Group |
| Safran SA |
| EFW GmbH |
| Singapore Technologies Engineering Ltd |
| The NORDAM Group LLC |
| Latecoere SA |
| Hexcel Corporation |
| Others |
Supply Flow & Price Mechanics
Autoclave undercapacity in the US Pacific Northwest constrains mid-tier laminator entry while concentrating pricing power among qualified incumbents serving Boeing's narrow-body programs. This utilization squeeze forces buyers into long-term offtake commitments with established honeycomb specialists, compressing negotiation leverage for tier-two procurement teams.
Pricing Analysis
Certification level (FAA Part 25.853 vs EASA CS-25 dual-qualified) creates the primary spread between premium and standard tier suppliers. Contract-based long-term offtake agreements dominate OEM line-fit procurement, while spot purchasing persists for MRO retrofit volumes. Price differentiation hinges on flammability test library depth and thermoplastic processing capability. Pricing pressure stems from REACH-driven phenolic reformulation costs, with European laminators facing margin compression. Cargo conversion operators in Southeast Asia exhibit highest price sensitivity; defense contractors specifying CFRP radar-absorbing assemblies show lowest.
Supply Chain Analysis
Aramid fiber feedstock from DuPont's Richmond, Virginia facility and carbon fiber prepreg from Hexcel's Salt Lake City, Utah operations anchor North American material flows. Japanese Toray facilities and German SGL Carbon plants provide secondary sourcing for defense-grade CFRP face sheets. The supply chain draws from petrochemical-derived Nomex honeycomb, phenolic resin systems, and thermoplastic PEEK films. Single-source vulnerability concentrates in autoclave bonding capacity for large-format panels. Distribution runs through tier-one aerostructure integrators with captive interiors divisions, supplemented by direct MRO channel partnerships for removable installation types.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic resin systems threaten to displace incumbent phenolic laminators within a single product generation, forcing established suppliers to defend their certification libraries and processing infrastructure against obsolescence.
For Market Incumbents: Pre-empt thermoplastic specialist encroachment by installing continuous compression molding lines before EASA CS-25 sustainability mandates harden specification preference. Secure backward integration into carbon fiber prepreg supply through offtake agreements with Hexcel or Toray. Defend against power-by-the-hour MRO contract unbundling by embedding proprietary fastening systems that complicate third-party replacement. For New Entrants and Emerging Players: India's PLI scheme for aerospace components represents the most penetrable entry point, with Hyderabad and Bangalore industrial corridors offering tariff-advantaged stamping capacity for indigenous fighter programs. Thermoplastic-thermoset hybrid core development for recyclability compliance offers specification differentiation in European markets. Partner with Lufthansa Technik or ST Engineering for MRO channel access rather than pursuing direct OEM qualification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermoplastic processing equipment, favoring acquisition targets with existing rapid-heat-press capabilities over greenfield development. Target mid-tier honeycomb specialists with FAA-EASA dual certification libraries and established airline MRO relationships. Watch for EASA CS-25 update implementation timelines as the signal for specification inflection toward lifecycle carbon accounting.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Processing Equipment Investment | Continuous compression molding lines at German and Japanese laminators collapse cure cycles below ten minutes. |
| Backward Integration into Carbon Fiber Prepreg | Captive supply of Toray or Hexcel materials secures defense contractor CFRP specifications for stealth platforms. |
| MRO Channel Partnership Development | Power-by-the-hour contracts with Middle Eastern carriers unbundle floor panel replacement from heavy maintenance checks. |
| Dual Certification Library Expansion | Parallel FAA-EASA validation for new resin systems extends competitive moats against unqualified entrants. |
| Sustainability Repositioning | Environmental product declarations with Bavarian circular material partners capture EU Green Deal specification preference. |
Methodological Framework
Cross-validation between primary interviews with tier-one aerostructure procurement managers, MRO technical operations directors, and defense contractor platform engineers anchors the qualitative findings. Secondary sources include FAA Part 25.853 certification databases, EASA CS-25 amendment notices, customs records for aramid fiber and carbon fiber prepreg trade flows, and SEC filings from publicly traded composite material suppliers. Bottom-up triangulation across panel fabrication capacity installations and top-down validation against narrow-body aircraft delivery schedules ensure methodological robustness.
Calibration against historical honeycomb and composite panel procurement volumes from Boeing and Airbus supply chain disclosures informs the projection framework. Segmentation dimensions span product architecture (honeycomb, composite, ply laminated, aluminum), material type (CFRP, GFRP, aluminum, steel), end-user category (OEM, MRO provider, airline, defense contractor), and installation method (fixed, removable, retrofit, integrated). CAGRs derive from elasticity modeling between aircraft production rates and floor panel content per platform, incorporating thermoplastic substitution curves and defense modernization program announcements.
Practitioners should monitor EASA CS-25 sustainability criteria implementation, REACH chemical restriction expansions, and Boeing program rate adjustments for early signals of forecast revision. Cross-checking against IHS Markit aircraft production databases and airline fleet age distributions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Aircraft Curtains Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market