
 Asia-Pacific Turboprop Aircraft Market | 2026-2036
Asia-Pacific Turboprop Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Turboprop Aircraft Market Outlook
Regional carriers across Southeast Asia and the South Pacific is rotating toward turboprop solutions for thin-route economics as fuel volatility pressures narrow-body jet margins. ATR dominates the regional aircraft segment with manufacturing scale that anchors its Asia-Pacific delivery pipeline. Aviation Industry Corporation of China leverages state-backed R&D intensity to develop indigenous turboprop platforms for domestic and export markets. DAHER competes through specialized utility-aircraft designs that sustain niche performance requirements in remote-terrain operations.
A turboprop aircraft employs a gas-turbine engine driving a propeller through a reduction gearbox, typically operating at cruise speeds of 300–400 knots and altitudes below 25,000 feet where propulsive efficiency exceeds pure-jet configurations. Its primary commercial purpose centers on cost-effective operations from short or unimproved runways with passenger loads below 80. The regional aircraft category leads current deliveries across the Asia-Pacific as infrastructure constraints persist in secondary cities. Cargo transport applications represent the fastest-growing segment as e-commerce logistics networks expand into island and mountainous territories. Twin-engine configurations occupy the dominant technology position due to regulatory safety requirements and operational redundancy demands for over-water and remote-area routes.
Civil Aviation Administration of China certification standards and Australia's Civil Aviation Safety Authority airworthiness frameworks shape product specifications and market access pathways across the region. Indonesia's Directorate General of Civil Aviation imposes operational mandates that favor turboprop performance characteristics for inter-island connectivity. Stakeholders must monitor regulatory divergence between national aviation authorities as type-certification reciprocity agreements evolve across the Asia-Pacific trading bloc.
Market Dynamics
Fuel price volatility is compressing operating margins for regional jet operators across Southeast Asia and the South Pacific, redirecting fleet planning toward turboprop economics for thin-route networks where load factors rarely exceed sixty percent.
Growth Catalysts
- India's UDAN regional connectivity scheme:The subsidy framework mandates minimum service obligations to underserved airports, creating guaranteed revenue streams for turboprop operators on routes below five hundred nautical miles.
- Indonesia's archipelagic geography:Inter-island corridors with runway lengths under 1,200 meters exclude jet operations entirely, locking in turboprop demand for the 17,000-island nation.
- Hybrid-electric propulsion development:Advancements in distributed electric architectures promise thirty-percent fuel burn reductions for next-generation regional aircraft, aligning with Australia's Civil Aviation Safety Authority emissions consultation pathways.
Market Restraints
- Aviation turbine fuel price volatility:Jet A-1 kerosene accounts for thirty-five to forty percent of direct operating costs, exposing thin-margin regional carriers to margin erosion without fuel hedging infrastructure.
- Single-source engine supply concentration:Pratt & Whitney Canada and General Electric Aviation dominate the sub-1,500 shaft horsepower segment, creating delivery queue risks for airframe manufacturers.
- Runway infrastructure limitations:Secondary airports across Papua New Guinea and the Solomon Islands lack precision approach capabilities, restricting operations to daylight visual flight rules.
Strategic Opportunities
- Myanmar and Cambodia network expansion:These underpenetrated markets maintain prohibitive road and rail infrastructure, positioning turboprops as the sole viable inter-city transport mode for premium passenger segments.
- E-commerce cargo conversion:Express logistics operators are retrofitting retired passenger turboprops for parcel networks serving island and mountainous territories beyond truck range.
- China's NMPA type-certification reciprocity:Bilateral agreements with Indonesia's Directorate General of Civil Aviation and Australia's Civil Aviation Safety Authority accelerate market access for indigenous airframe platforms.
Industry Challenges
- Airframe structural life extension certification:Operators seeking to defer capital expenditure face prolonged timeline uncertainty with national aviation authorities lacking dedicated turboprop aging-aircraft expertise.
- Propeller blade composite repair technician scarcity:The specialized skill set for carbon-fiber propeller maintenance concentrates in Singapore and Sydney, creating AOG risk for remote-base operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Turboprop Aircraft Market |
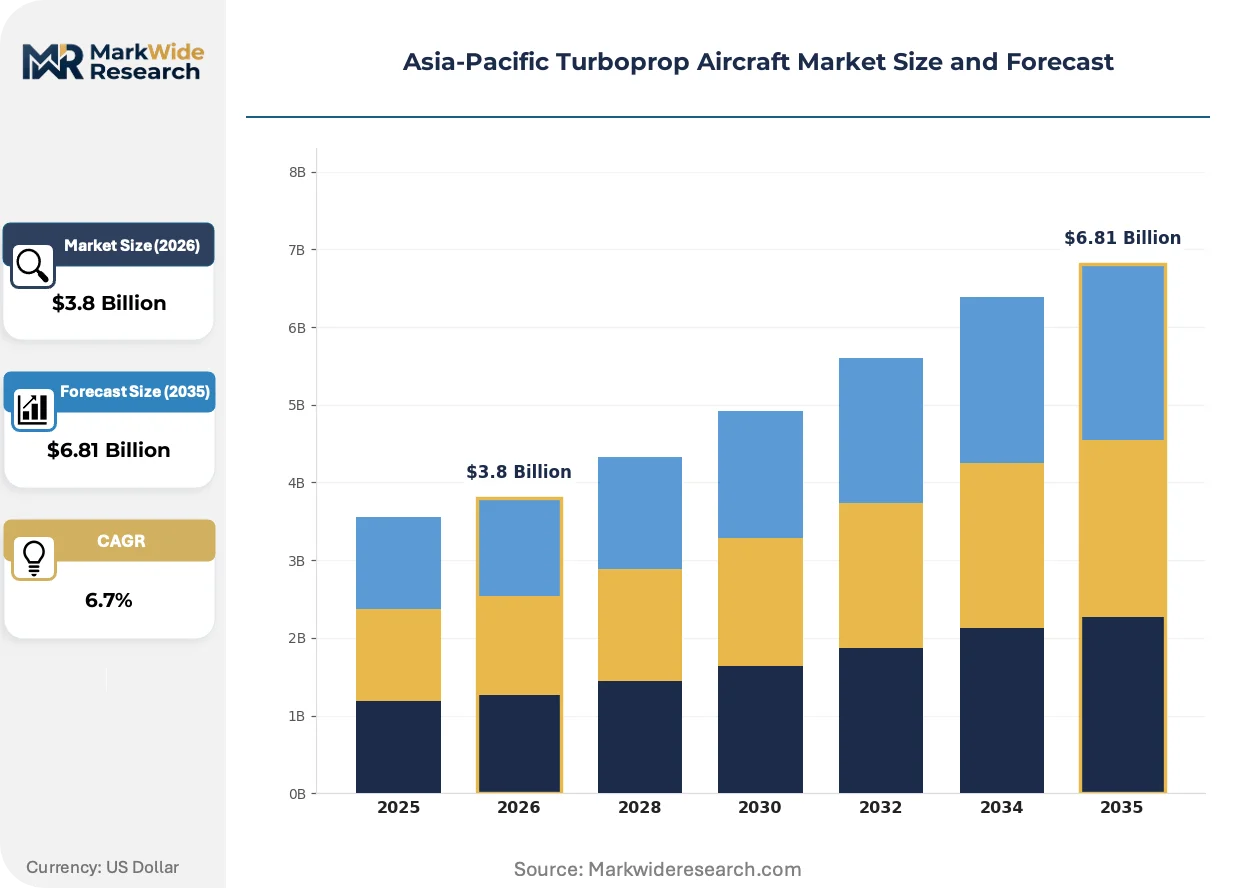
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Regional, Utility, Cargo, Passenger End User: Government, Commercial, Charter, Private Engine Type: Twin-Engine, Single-Engine, Turbofan, Turboshaft Application: Aerial Surveying, Air Ambulance, Cargo Transport, Tourism |
| Companies Covered | Aviation Industry Corporation of China, Bombardier, ATR, Airbus, Gulfstream, Textron Aviation, DAHER, Raytheon Technologies, Lockheed Martin Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Turboprop Aircraft Market Strategic Shifts
Propulsion architecture diversification is fragmenting the historically consolidated regional aircraft supply base, as airframe manufacturers evaluate hybrid-electric, hydrogen combustion, and sustainable aviation fuel compatibility pathways simultaneously.
Advanced thermoplastic composites are fragmenting traditional aluminum wing and fuselage construction in next-generation turboprop programs. ATR and emerging competitors are adopting automated fiber placement for primary structure, reducing airframe weight by twelve to fifteen percent while improving damage tolerance. Regional carriers in Australia and New Zealand are specifying these platforms for unimproved runway operations where fatigue resistance determines economic life.
Indonesia's Directorate General of Civil Aviation implemented revised extended diversion time operations rules for inter-island routes, mandating twin-engine redundancy and enhanced navigation equipment for sectors beyond sixty minutes from alternate airports. This regulatory compression is accelerating fleet retirement of aging single-turboprop utility aircraft. Papua New Guinea-based mining support operators are upgrading to compliant twin-turboprop configurations to maintain access to remote extraction sites.
Freight-forwarding intermediaries are disintermediating traditional scheduled airline cargo capacity for e-commerce flows. Platforms like Lazada and Shopee are contracting directly with turboprop operators for dedicated parcel services, bypassing incumbent passenger-cargo combi arrangements. This channel restructuring is most visible in the Philippines, where island e-commerce penetration has outpaced maritime freight reliability.
Asia-Pacific Turboprop Aircraft Market Segmentation
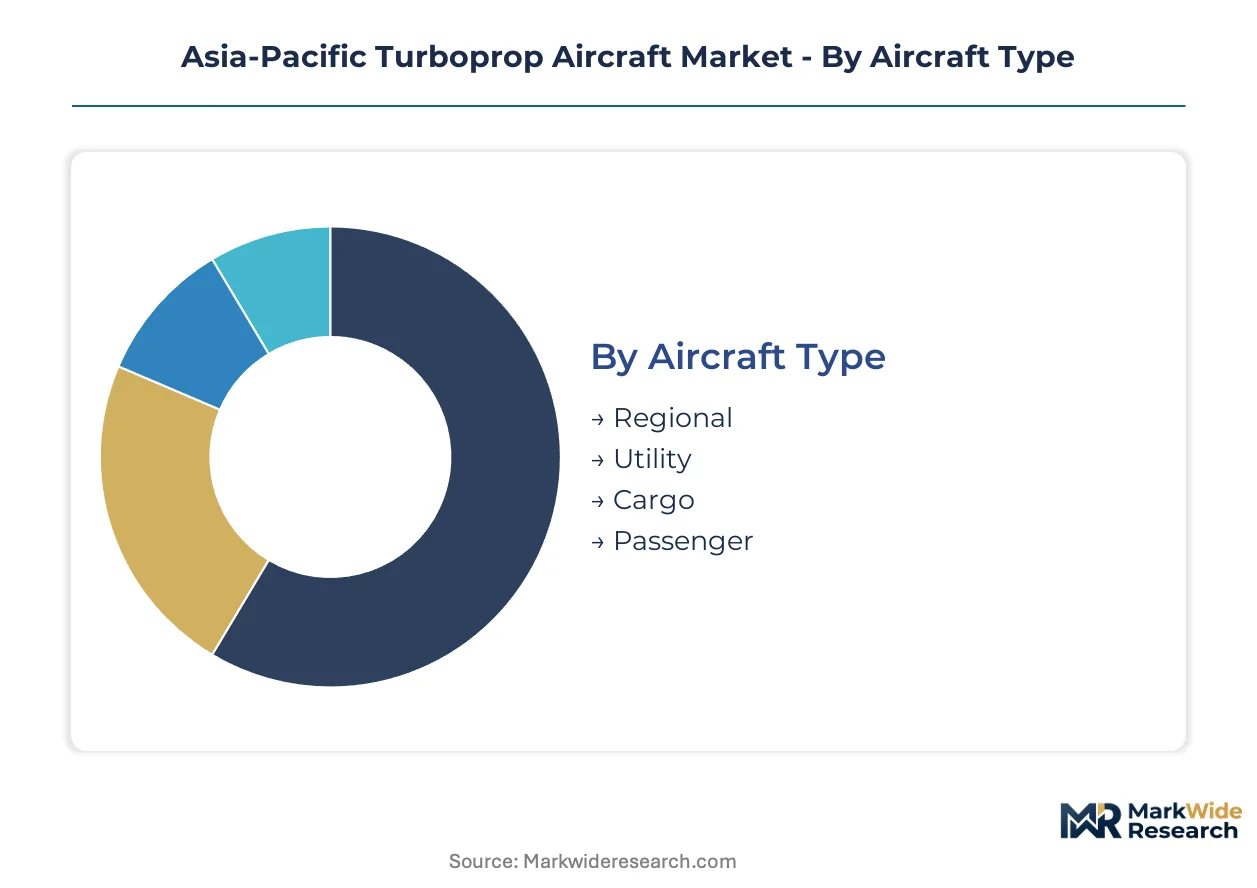
Segmentation reveals how turboprop demand fragments across operational roles and customer economics in the Asia-Pacific. Each category exposes distinct procurement patterns, regulatory exposure, and fleet replacement cycles that shape manufacturer positioning.
Aircraft Type:
Margin pools concentrate where runway limitations exclude jet competition and thin-route economics favor lower trip costs.
- Regional:These aircraft seat 50-80 passengers with pressurized cabins for scheduled services between secondary cities. India's UDAN scheme and Indonesia's inter-island networks drive procurement as fuel volatility compresses regional jet operating margins.
- Utility:Unpressurized airframes with reinforced landing gear serve mining camps, humanitarian missions, and remote airstrip operations. Papua New Guinea and Australian outback operators specify these platforms for unimproved runway access where structural durability determines economic life.
- Cargo:Converted or purpose-built freighters with large cargo doors handle express parcel networks. E-commerce logistics operators across the Philippines and Indonesia are retrofitting retired passenger turboprops for dedicated island freight services.
- Passenger:Smaller commuter configurations below 30 seats serve thin-density routes with load factors rarely exceeding sixty percent. Charter operators in Myanmar and Cambodia deploy these where road infrastructure remains prohibitive.
The dominant share belongs to Regional aircraft, while Cargo configurations are closing the gap fastest as express logistics networks expand beyond truck range.
End User:
Procurement authority concentrates with operators who control route authority and subsidy eligibility.
- Commercial:Scheduled airlines dominate fleet orders under India's UDAN minimum service obligations and Indonesia's archipelagic connectivity mandates. These operators prioritize twin-engine redundancy for over-water sectors and fuel burn efficiency on sub-five-hundred-nautical-mile stages.
- Government:Maritime patrol, border surveillance, and disaster response agencies specify missionized turboprops with extended loiter capability. Australia's Civil Aviation Safety Authority certification pathways and Indonesia's Directorate General of Civil Aviation operational rules shape specifications for these public-sector acquisitions.
- Charter:On-demand operators serving mining, tourism, and corporate transport segments require rapid reconfiguration flexibility. These customers concentrate in Australia's resource extraction corridors and Southeast Asian resort destinations.
- Private:Individual and corporate ownership remains limited to specialized utility applications and remote property access in Papua New Guinea and the Solomon Islands where commercial service is unavailable.
Commercial operators command the dominant procurement volume, while Government acquisitions are expanding most quickly through maritime security and climate response budgets.
Engine Type:
Safety regulations and route geography dictate engine count and architecture selection.
- Twin-Engine:Regulatory mandates for extended diversion time operations over water and remote terrain have made this the default configuration for scheduled services. Pratt & Whitney Canada and General Electric Aviation supply the dominant powerplants in this segment.
- Single-Engine:Restricted to visual flight rules operations and daylight utility missions where regulatory relief permits cost reduction. These airframes serve training, agricultural spraying, and short-haul cargo in less regulated airspace.
- Turbofan:Jet propulsion variants occupy niche high-speed roles where turboprop efficiency advantages diminish, primarily in executive transport and special-mission applications requiring altitude performance.
- Turboshaft:Helicopter-derived engines power specialized slow-speed platforms for aerial surveying and patrol missions requiring extended endurance at low altitude.
Twin-Engine configurations hold the dominant technology position, while Single-Engine platforms are gaining share fastest in cost-sensitive utility niches.
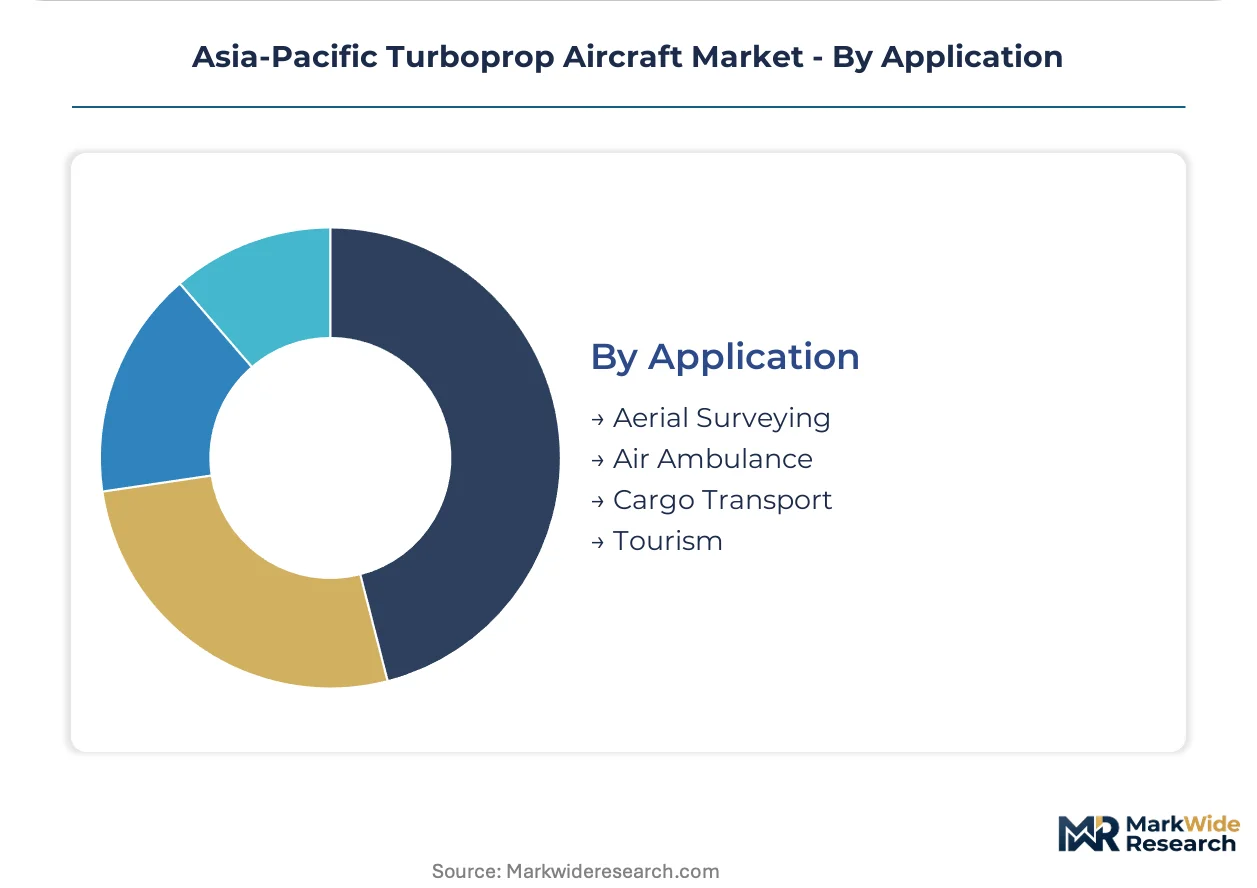
Application:
Revenue stability varies sharply between scheduled services and mission-specific contracting.
- Cargo Transport:Dedicated freighter operations serve e-commerce parcel networks across island territories where maritime reliability lags. Platforms like Lazada and Shopee contract directly with turboprop operators, bypassing traditional passenger-cargo combi arrangements.
- Air Ambulance:Medical evacuation services require pressurized cabins, stretcher configurations, and rapid dispatch capability. Australia's remote communities and Indonesia's eastern islands sustain demand for these specialized missions.
- Tourism:Scenic and access flights to remote natural attractions operate seasonal schedules with high yield per seat. New Zealand's South Island and the Maldives represent concentrated demand centers for these services.
- Aerial Surveying:Geophysical exploration, forestry mapping, and infrastructure inspection missions demand stable low-speed flight characteristics. Mining companies across Papua New Guinea and Western Australia contract these services for resource identification.
Cargo Transport commands the dominant application share, while Air Ambulance is climbing the fastest as healthcare access initiatives expand into remote territories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia exports turboprop conversion services and mining-support aviation to Papua New Guinea and Indonesia, while China supplies airframe components and indigenous platforms across Southeast Asia.
Indonesia
Inter-island connectivity mandates sustain demand for 50-seat turboprops serving 17,000 islands with runways under 1,200 meters. The Directorate General of Civil Aviation enforces extended diversion time operations rules requiring twin-engine redundancy. Jakarta-based carriers concentrate fleet procurement for eastern archipelago routes.
India
The UDAN regional connectivity scheme guarantees revenue streams on sub-500-nautical-mile routes to 70-plus underserved airports. The Ministry of Civil Aviation mandates minimum service obligations that favor turboprop economics over regional jets. Maharashtra and Karnataka host maintenance clusters supporting UDAN-subsidized operators.
Australia
Mining-support and remote-community services drive utility turboprop demand across unimproved airstrips in Western Australia and Queensland. The Civil Aviation Safety Authority shapes airworthiness frameworks that influence specifications across the Asia-Pacific. Perth and Brisbane anchor specialized maintenance capabilities for carbon-fiber propeller repair.
Papua New Guinea
Resource extraction corridors require twin-turboprop platforms for remote-site access beyond road networks. The Civil Aviation Safety Authority of Papua New Guinea restricts operations to daylight visual flight rules at secondary airports lacking precision approaches. Highlands mining camps sustain charter demand for reinforced-landing-gear configurations.
China
Domestic regional connectivity and export platform development drive indigenous turboprop programs. The Civil Aviation Administration of China certification standards shape product specifications for airframe manufacturers. Xi'an and Shanghai concentrate state-backed R&D facilities advancing composite primary structures.
Asia-Pacific Turboprop Aircraft Market Competitive Environment
Listed aerospace conglomerates compete with private specialists across manufacturing scale and mission specialization. The market structures around three tiers: European airframe integrators with established delivery pipelines, Chinese state-backed manufacturers pursuing indigenous certification, and French utility-aircraft specialists serving niche terrain requirements. Consolidation pressures favor M&A activity among component suppliers, while technology licensing agreements proliferate around hybrid-electric propulsion architectures.
Within the state-backed manufacturer tier, Aviation Industry Corporation of China exemplifies vertical integration from R&D through certification. European specialists ATR and DAHER occupy positions anchored in regional and utility segments respectively, with ATR representing manufacturing-scale dominance and DAHER exemplifying remote-terrain missionization. These three entities illustrate the competitive vectors shaping procurement decisions across archipelagic and thin-route networks.
| Leading Market Players |
|---|
| Aviation Industry Corporation of China |
| Bombardier |
| ATR |
| Airbus |
| Gulfstream |
| Textron Aviation |
| DAHER |
| Raytheon Technologies |
| Lockheed Martin Corporation |
| Others |
Value Chain & Pricing Dynamics
Composite airframe substitution for aluminum construction simultaneously redraws manufacturing geography toward Xi'an and Toulouse while compressing unit economics through twelve to fifteen percent weight reduction. This materials transition concentrates pricing power with automated fiber placement equipment owners and fragments legacy supplier relationships.
Pricing Analysis
Next-generation hybrid-electric architectures command thirty-percent fuel burn premiums over current-generation turboprops, while prior-generation aluminum airframes trade at distressed valuations in secondary markets. Three-tier pricing structure across certified-new, mid-life refurbished, and end-of-life cargo-converted platforms reflects divergence in regulatory compliance burden and residual structural life. Cost compression in the mid-life segment intensifies as Indonesian and Indian carriers defer capital expenditure through lease extensions. Charter operators in Papua New Guinea exhibit highest price sensitivity due to seasonal mining contract volatility, whereas government maritime patrol agencies accept premium positioning for missionized configurations.
Supply Chain Analysis
Pratt & Whitney Canada engine final assembly in Montreal anchors a chokepoint that propagates delivery queue risk through ATR and Viking Air production lines. Component sourcing draws from France for avionics suites, Canada for powerplants, and China for composite precursor materials. Single-source vulnerability concentrates in the sub-1,500 shaft horsepower engine segment where General Electric Aviation and Pratt & Whitney Canada dominate. Distribution runs through Jakarta and Singapore as regional distribution hubs serving archipelagic operators with limited direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Indonesia's 17,000-island network and India's UDAN-subsidized thin routes creates specialist niches that reward focused positioning over scale pursuit.
For Market Incumbents: Secure Pratt & Whitney Canada engine allocation priority through multi-year offtake commitments before hybrid-electric transition disrupts supply relationships. Defend against Chinese state-backed manufacturers by accelerating Indonesia Directorate General of Civil Aviation and Australia Civil Aviation Safety Authority certification reciprocity for next-generation composite platforms. Vertical integration into carbon-fiber propeller repair capabilities addresses technician scarcity in Sydney and Singapore.
For New Entrants and Emerging Players: Differentiate on unimproved runway performance specifications for Papua New Guinea mining corridors and Australian outback operations where ATR's manufacturing scale delivers inadequate durability. Target Myanmar and Cambodia charter markets where road infrastructure gaps sustain turboprop demand beyond scheduled airline penetration. Pursue direct e-commerce logistics contracts with Lazada and Shopee rather than incumbent passenger-cargo combi intermediation.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors hybrid-electric propulsion specialists with Australia Civil Aviation Safety Authority emissions consultation pathway access. Long-term viability hinges on certification reciprocity positioning across the Asia-Pacific trading bloc rather than manufacturing scale. Monitor China's NMPA bilateral agreement momentum with Indonesia and Australia as inflection indicator for indigenous platform export competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Development | Thirty-percent fuel burn reduction aligns with Australia Civil Aviation Safety Authority emissions pathways. |
| Composite Airframe Certification | Automated fiber placement adoption reduces weight for Indonesia's short-runway operations. |
| Cargo Conversion Retrofit | E-commerce logistics operators bypass traditional passenger-cargo combi arrangements in Philippines. |
| Engine Supply Agreement | Multi-year offtake secures Pratt & Whitney Canada allocation against delivery queue risk. |
| Regional Certification Reciprocity | China's NMPA bilateral agreements with Indonesia and Australia accelerate market access. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with turboprop fleet managers, maintenance directors at Perth and Brisbane MRO facilities, Indonesia Directorate General of Civil Aviation certification officials, and mining aviation procurement leads; and secondary validation through Civil Aviation Administration of China type certification databases, Australia Civil Aviation Safety Authority airworthiness directives, and customs records of turboprop engine imports. Bottom-up triangulation against top-down market sizing cross-checked manufacturer delivery disclosures with operator fleet registries.
Across the analysis window, the forecasting framework modeled aircraft type segmentation, end-user procurement authority concentration, engine configuration regulatory mandates, and application-specific revenue stability patterns. CAGRs derived from fitted growth curves applied to documented fleet replacement cycles and subsidy program enrollment trajectories. Hybrid-electric propulsion development timelines and composite airframe adoption rates served as technology transition inputs.
Material uncertainties — aviation turbine fuel price volatility, single-source engine supply disruption, and regulatory divergence between national aviation authorities — sit outside the modeled envelope. Forecasts reflect assumptions about UDAN scheme continuation and Indonesia archipelagic connectivity mandate stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Europe Freighter Aircraft Market
Aircraft
Aircraft Seals Market
Aircraft
Military Transport Aircraft Market
Aircraft
America Freighter Aircraft Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Airplane Brackets Market
Aircraft
Global Business Aircraft Market
Aircraft
Commercial Aircraft Fadec Market
Aircraft
Global Helicopter Market
Aircraft
Commercial Aircraft Manufacturing Market
Aircraft
Aircraft Ailerons Market
Aircraft
Turboprop Aircraft Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Strategic Bomber Market
Aircraft
North America Aviation Market
Aircraft
Winglets Market