
 APAC Advanced Building Materials Market | 2026-2036
APAC Advanced Building Materials Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Advanced Building Materials Market Insights
Specification-grade thermal performance is unwinding legacy commodity dynamics across the APAC advanced building materials sector. Saint-Gobain leverages its insulation and glass systems to anchor premium envelope specifications in Southeast Asian commercial towers. China National Building Material Group Corporation dominates cementitious advanced formulations through integrated raw-to-product control across domestic megaprojects. Toray Industries specializes in carbon fiber reinforced polymers for seismic retrofit and high-rise structural applications in Japan.
Advanced building materials encompass engineered substances and systems manufactured to exceed conventional performance thresholds for thermal resistance, mechanical strength, durability, or environmental impact, typically involving controlled composition, additive incorporation, or precision forming processes such as extrusion, curing under regulated atmospheres, or layer deposition. These materials serve primarily to reduce operational energy consumption, extend service life, or enable novel architectural geometries in commercial and infrastructure construction. Composite materials lead product type value pools due to aerospace-derived fabrication expertise transferring to construction, while nanomaterials represent the fastest-expanding technology segment as surface-functionalized additives penetrate waterproofing and self-healing concrete formulations. Prefabrication technology concentrates margin in factory-controlled quality environments, displacing site-cast methods where labor reliability fluctuates.
China's MEE enforces dual carbon compliance timelines that reshape material procurement toward low-clinker cement and recycled content verification. Japan's METI building energy codes and India's BIS performance standards for green construction materials collectively raise technical barriers to market access across the region. Stakeholders must monitor regulatory divergence between national carbon accounting protocols and harmonized product certification schemes to anticipate compliance cost allocation across multi-country project portfolios.
Market Dynamics
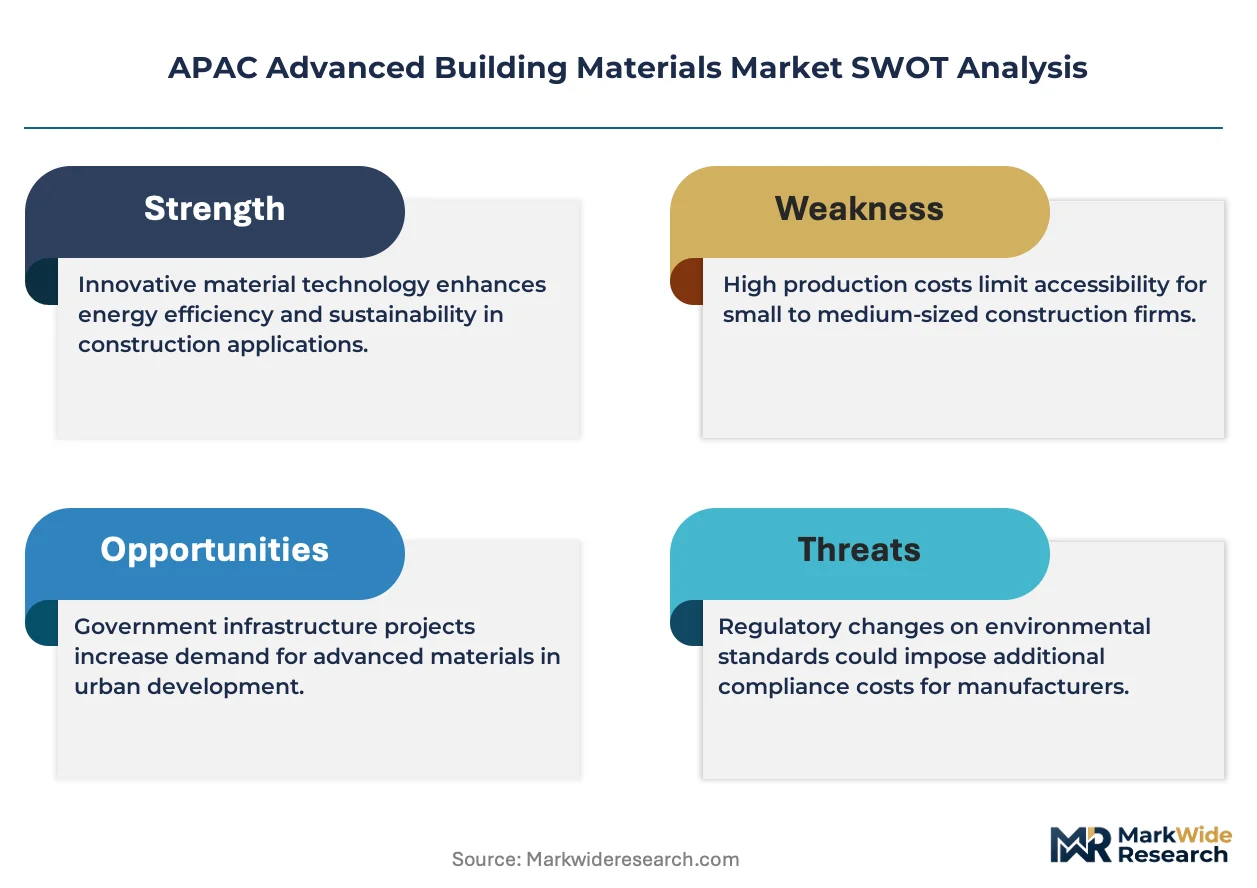
China's dual carbon mandates from MEE are compressing embodied carbon allowances for structural materials, forcing procurement shifts toward low-clinker formulations and verified recycled content across megaproject portfolios.
Growth Catalysts
- Commercial envelope specifications:Southeast Asian tower developers are specifying high-performance thermal systems to meet stringent energy codes, pulling demand away from commodity insulation.
- Seismic retrofit mandates:Japan's METI building standards are accelerating carbon fiber reinforced polymer deployment for structural reinforcement in high-rise cores.
- Industrial infrastructure corridors:India's western belt from Mumbai to Gujarat is channeling investment into advanced cementitious systems for factory and logistics construction.
Market Restraints
- Clinker input volatility:Energy-intensive cement production faces feedstock cost swings that compress margin on low-carbon formulations.
- Recycled aggregate supply concentration:Quality-controlled demolition waste streams cluster in China's eastern provinces, leaving interior projects with verification gaps.
- Cross-border certification friction:Divergent BIS and GB standards create retesting burdens for materials moving between India and China.
Strategic Opportunities
- Vietnam commercial construction:Foreign direct investment in manufacturing facilities is opening specification-grade envelope markets outside established supply chains.
- Self-healing concrete additives:Surface-functionalized nanoparticles are penetrating waterproofing applications with lifecycle cost advantages over membrane systems.
- Prefabrication channel expansion:Factory-controlled quality environments are capturing margin from site-cast methods where labor reliability fluctuates in Indonesia and Philippines.
Industry Challenges
- Carbon accounting skill gaps:Project teams lack expertise in embodied carbon measurement protocols required for MEE compliance documentation.
- Legacy system integration:Advanced material specifications clash with existing contractor procurement workflows optimized for commodity grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Advanced Building Materials Market |
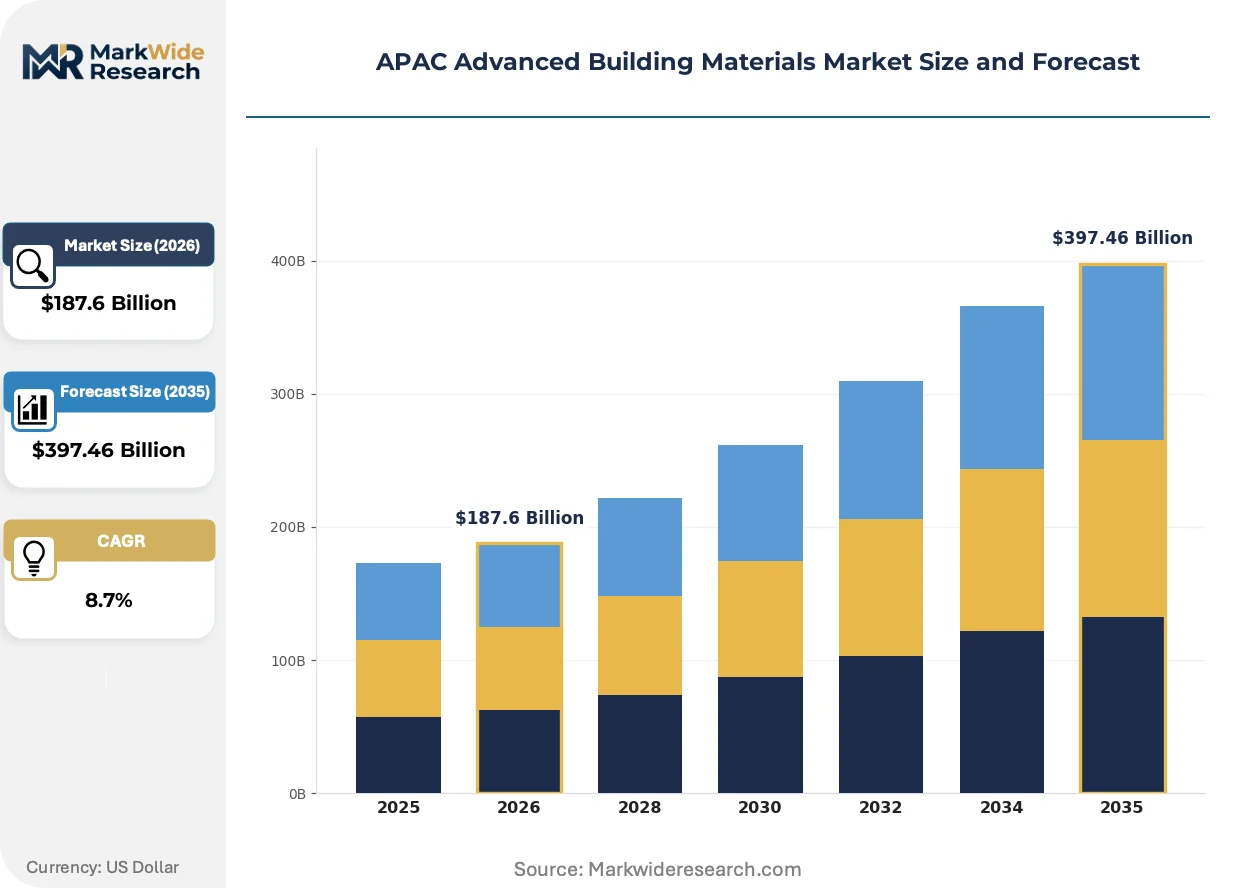
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Composite, Metal, Cement Application: Residential Construction, Commercial Construction, Industrial Construction, Infrastructure Technology: 3D Printing, Prefabrication, Smart Materials, Nanomaterials End User: Construction Companies, Architects, Engineers, Developers |
| Companies Covered | Saint-Gobain, BASF SE, LafargeHolcim, DuPont, Owens Corning, Kingspan Group, Sekisui Chemical, Toray Industries, China National Building Material Group Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Advanced Building Materials Market Trends and Innovations
Specification-grade performance requirements are fragmenting procurement patterns across the APAC advanced building materials sector, with quality verification and carbon accountability becoming decisive selection criteria.
Phase-change material integrated wall systems are displacing conventional insulation in Southeast Asian commercial towers. Property developers in Singapore and Bangkok are mandating thermal mass management for LEED-equivalent ratings. This shift is compressing specification windows for mineral wool suppliers unable to demonstrate dynamic thermal performance.
China's MEE dual carbon enforcement timelines are tightening clinker content ceilings for domestic cement production. Low-clinker formulations with verified supplementary cementitious materials are securing preferential access to state-backed infrastructure tenders. Multinational project developers are reconfiguring supply agreements to lock in compliant domestic capacity.
Performance-based material procurement is disrupting traditional commodity purchasing in Indian industrial construction. EPC contractors are contracting directly with advanced formulation producers for guaranteed thermal or seismic metrics, bypassing distributor markups. This pattern concentrates in Gujarat's chemical and pharmaceutical manufacturing zones where process continuity demands predictable envelope behavior.
APAC Advanced Building Materials Market Segmentation
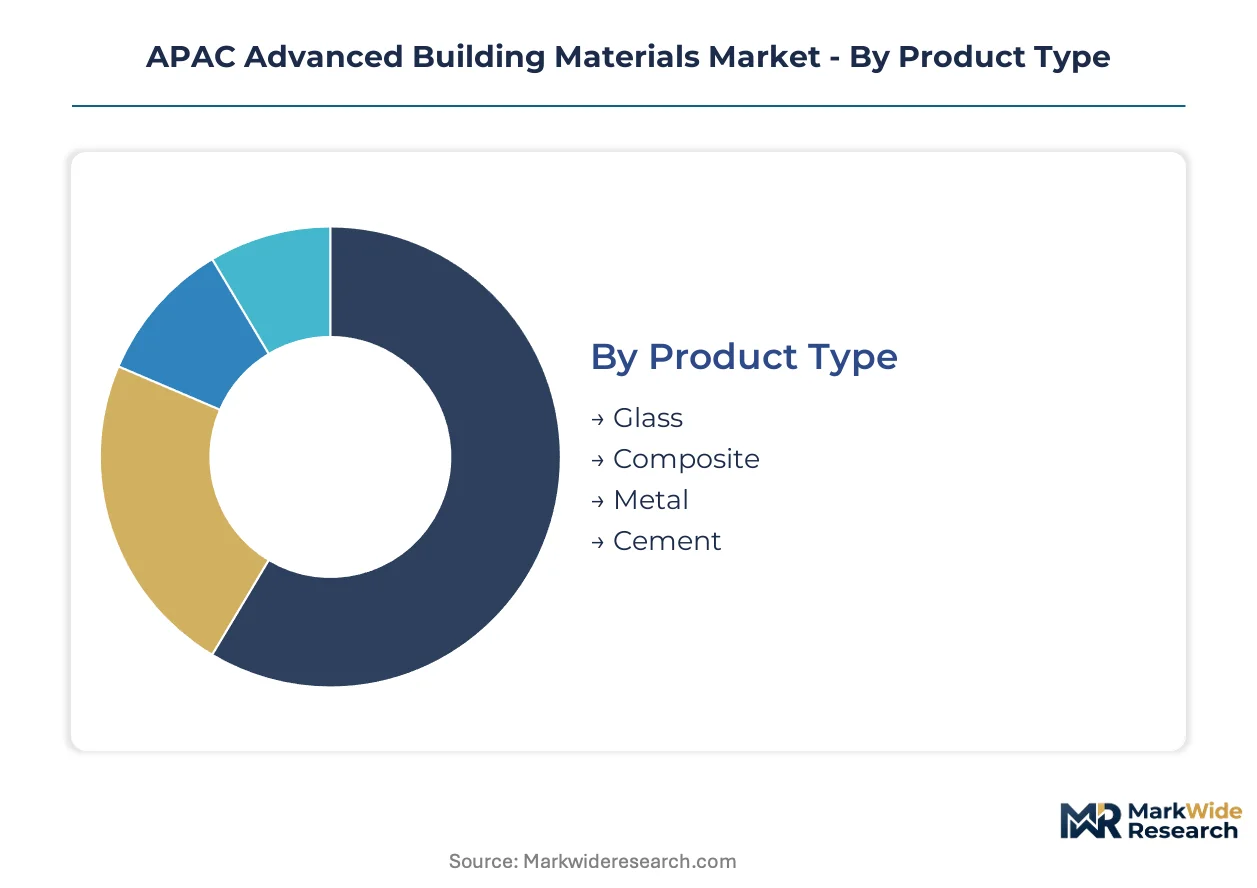
Segmentation in the APAC advanced building materials market reveals how specification-grade performance requirements are fragmenting procurement channels. Channel mix varies sharply by product maturity, with established materials flowing through distributor networks while novel formulations require direct manufacturer engagement for technical validation.
Product Type:
Channel configuration diverges by material maturity, with composites and advanced glass commanding direct specification relationships while commodity metal and cement variants retain distributor intermediation.
- Composite:Carbon fiber reinforced polymers and fiber-reinforced concrete leverage aerospace-derived fabrication expertise for seismic retrofit and high-rise structural cores. Demand concentrates in Japan's METI-mandated building reinforcement programs and Vietnam's foreign-direct-investment manufacturing facilities where specification-grade performance justifies premium positioning.
- Glass:High-performance coated and vacuum-insulated glass systems anchor envelope specifications in Southeast Asian commercial towers. Singapore and Bangkok developers mandate these for LEED-equivalent thermal mass management, compressing specification windows for mineral wool alternatives unable to demonstrate dynamic performance.
- Metal:Advanced alloys and corrosion-resistant formulations serve industrial infrastructure in India's western corridor from Mumbai to Gujarat.
- Cement:Low-clinker formulations with verified supplementary cementitious materials secure preferential access to China's state-backed infrastructure tenders under MEE dual carbon enforcement.
Composite and glass dominate installed base in premium commercial applications. Cement is where expansion concentrates as carbon compliance reshapes structural material procurement.
Application:
Cost tier stratification separates specification-grade commercial and industrial segments from price-sensitive residential mass markets.
- Commercial Construction:High-performance envelope systems command specification premiums in Southeast Asian tower developments. Phase-change material integrated wall systems displace conventional insulation as Singapore and Bangkok developers mandate thermal mass management for energy code compliance.
- Industrial Construction:Performance-based procurement disrupts commodity purchasing in Gujarat's chemical and pharmaceutical manufacturing zones. EPC contractors contract directly with advanced formulation producers for guaranteed thermal or seismic metrics, bypassing distributor markups where process continuity demands predictable envelope behavior.
- Infrastructure:Megaproject portfolios in China drive volume for low-carbon cementitious systems with verified recycled content documentation.
- Residential Construction:Mass-market housing applies advanced materials selectively, primarily in high-rise developments where code minimums intersect with developer brand positioning.
Commercial construction anchors revenue concentration. Industrial construction is climbing the fastest as performance-based contracting penetrates manufacturing facility investment.
Technology:
Supply concentration in factory-controlled environments determines which technologies capture margin from site-cast methods.
- Prefabrication:Factory-controlled quality environments displace site-cast methods where labor reliability fluctuates in Indonesia and Philippines. Panelized envelope systems and precast structural elements concentrate production in Thailand and Malaysia for regional export.
- Nanomaterials:Surface-functionalized nanoparticles penetrate waterproofing and self-healing concrete formulations with lifecycle cost advantages over membrane systems. Quality-controlled additive production clusters in China's eastern provinces.
- Smart Materials:Responsive coatings and self-monitoring structural sensors deploy primarily in Japan's high-rise seismic monitoring applications.
- 3D Printing:Construction-scale additive manufacturing remains experimental, with pilot deployments concentrated in Singapore's public housing research programs.
Prefabrication dominates near-term margin capture. Nanomaterials represent the steepest expansion trajectory as surface engineering transfers from industrial to construction applications.
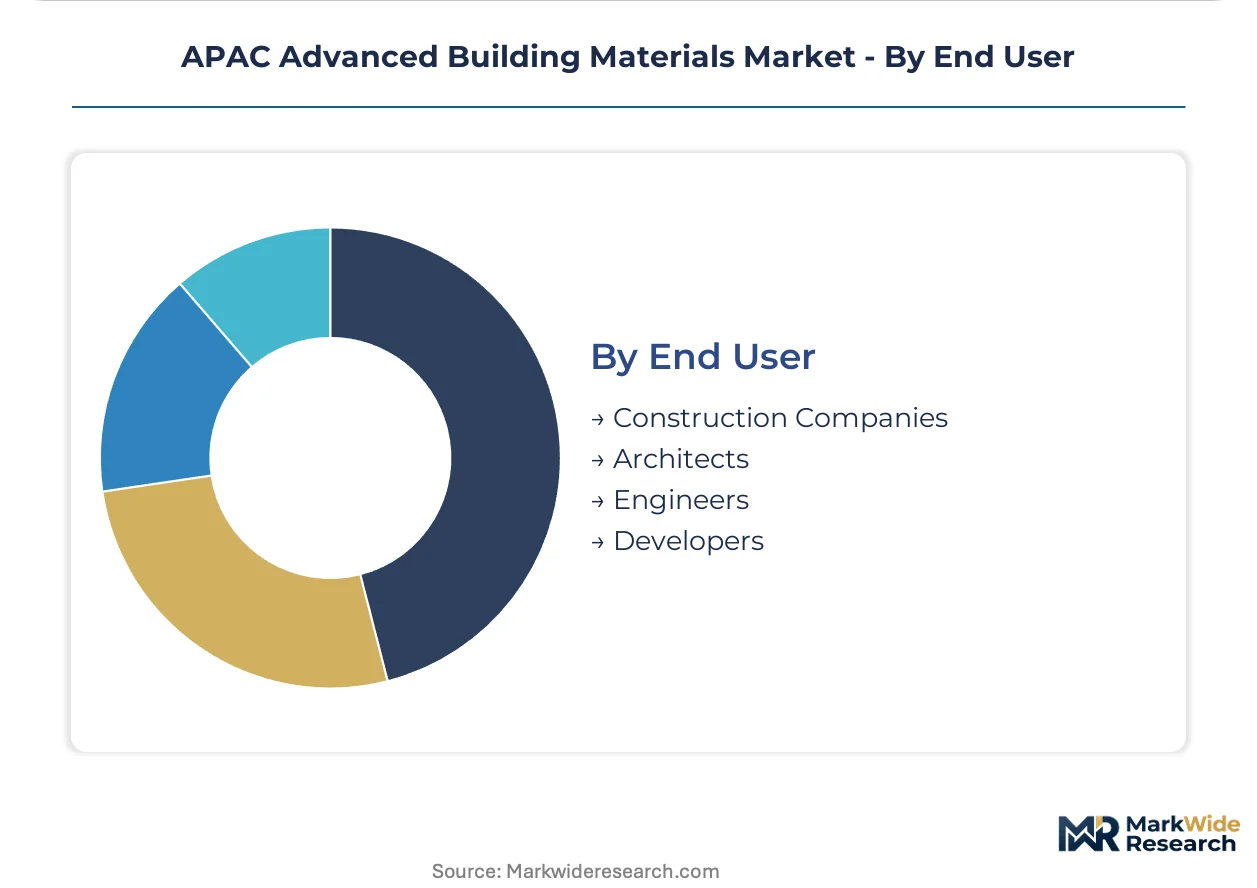
End User:
Customer type determines technical engagement depth, with architects and engineers driving specification while developers and construction companies execute procurement.
- Developers:Property developers in Southeast Asia mandate high-performance thermal systems for energy code compliance and LEED-equivalent ratings, translating regulatory pressure into material specifications.
- Construction Companies:EPC contractors in India's industrial corridors are contracting directly with advanced formulation producers, bypassing traditional distributor channels for guaranteed performance metrics.
- Architects:Design professionals specify advanced materials for novel geometries and thermal performance in Singapore and Bangkok commercial towers.
- Engineers:Structural engineers drive carbon fiber reinforced polymer deployment for seismic retrofit mandates under Japan's METI building standards.
Developers dominate specification initiation. Construction companies are where procurement pattern disruption concentrates as performance-based contracting expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in advanced building materials tilt toward import dependence for specification-grade composites and export surplus for cementitious formulations. China's integrated supply chains dominate regional raw material conversion, while Southeast Asian markets rely on cross-border procurement for high-performance envelope systems.
China
MEE dual carbon mandates compress embodied carbon allowances for structural materials across megaproject portfolios. Low-clinker cement formulations with verified supplementary cementitious materials secure preferential access to state-backed infrastructure tenders. Production clusters concentrate in the Yangtze River Delta where integrated raw-to-product control supports advanced cementitious output.
Japan
METI building energy codes and seismic retrofit mandates accelerate carbon fiber reinforced polymer deployment for high-rise structural reinforcement. Toray Industries anchors domestic fabrication expertise for seismic applications. The Kanto region around Tokyo channels demand for smart material integration in commercial tower developments.
India
BIS performance standards for green construction materials raise technical barriers to market access across industrial infrastructure investment. The western corridor from Mumbai to Gujarat concentrates advanced cementitious procurement for factory and logistics construction. EPC contractors in Gujarat's chemical zones contract directly with formulation producers for guaranteed performance metrics.
Vietnam
Foreign direct investment in manufacturing facilities opens specification-grade envelope markets outside established supply chains. Commercial tower developers in Ho Chi Minh City mandate high-performance thermal systems for energy code compliance. Panelized prefabrication systems from Thailand and Malaysia penetrate the market as factory-controlled quality displaces site-cast methods.
Singapore
Stringent thermal mass management requirements for LEED-equivalent ratings compress specification windows for conventional insulation. Phase-change material integrated wall systems displace mineral wool alternatives in commercial developments. The city-state's public housing research programs pilot construction-scale additive manufacturing for future deployment.
APAC Advanced Building Materials Market Competitive Landscape
Concentration sits with state-backed integrated materials groups and multinational envelope specialists. The market structure tiers between premium specification-grade players and commodity-scale producers serving mass construction. Three archetypes dominate: diversified industrial conglomerates with raw material control, specialized high-performance fabricators, and prefabrication technology integrators. Competitive moves center on backward integration into raw material supply and strategic partnerships for carbon compliance verification.
Among diversified industrial conglomerates, China National Building Material Group Corporation and Saint-Gobain exemplify contrasting approaches to regional positioning. China National Building Material Group Corporation represents state-anchored vertical integration across domestic megaprojects. Saint-Gobain occupies a position as the multinational envelope specialist leveraging insulation and glass systems for premium commercial specifications in Southeast Asian towers.
| Leading Market Players |
|---|
| Saint-Gobain |
| BASF SE |
| LafargeHolcim |
| DuPont |
| Owens Corning |
| Kingspan Group |
| Sekisui Chemical |
| Toray Industries |
| China National Building Material Group Corporation |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day inventory cycles for carbon fiber reinforced polymers concentrate margin with integrated producers who control precursor supply, compressing specification premiums for distributors lacking backward integration into polyacrylonitrile feedstock. This lead-time band anchors pricing power in Japan's METI-mandated seismic retrofit programs where verified performance documentation commands priority allocation.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Gujarat's chemical corridor and Vietnam's manufacturing zones. Price differentiation stratifies across certification grade and volume scale, with MEE-compliant low-clinker cement securing premiums over standard formulations. Cost compression in commodity insulation intensifies as phase-change wall systems displace mineral wool in Bangkok and Singapore tower specifications. Residential developers exhibit highest price sensitivity, while state-backed infrastructure tenders show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Sixty-day order-to-delivery windows for vacuum-insulated glass systems tether pricing to Yangtze River Delta production clusters where Saint-Gobain and domestic fabricators concentrate coated substrate capacity. Supply draws from China, Thailand, and Malaysia for prefabricated envelope components, with raw material dependencies spanning soda ash, low-iron silica, and argon gas. Single-source vulnerability concentrates in China's eastern provinces where quality-controlled recycled aggregate feeds low-carbon cement production. Distribution runs through specification-direct channels for advanced composites while commodity cement retains distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification-grade performance requirements are accelerating early-cycle expansion as MEE dual carbon enforcement and METI seismic mandates create compliance-driven replacement demand across structural and envelope applications.
For Market Incumbents: Compound specification-grade positioning by locking in supplementary cementitious material supply agreements ahead of MEE clinker ceiling tightening. Prioritize certification investment for BIS performance standards in India's western corridor to preempt emerging local formulators. Carbon accounting service bundling defends margin against commodity distributors lacking embodied carbon documentation expertise. For New Entrants and Emerging Players: Differentiate on prefabrication quality assurance for Indonesia and Philippines markets where labor reliability fluctuations displace site-cast methods. Target Vietnam's foreign-direct-investment manufacturing facilities for specification-grade envelope penetration outside established Saint-Gobain supply chains. Direct EPC contractor engagement bypasses distributor markups in Gujarat's chemical zones. For Investors and Strategic Acquirers: Carve-out targets emerge from state-backed conglomerates seeking to monetize non-core advanced formulation assets as dual carbon compliance concentrates capital in domestic capacity. Five-to-ten year viability hinges on carbon verification infrastructure ownership. Watch for BIS-GB standards harmonization announcements as inflection signal for cross-border material flow expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Supplementary Cementitious Materials | Secures feedstock for MEE-compliant low-clinker formulations ahead of tightening clinker ceilings. |
| Prefabrication Channel Expansion | Captures margin from site-cast displacement in Indonesia and Philippines labor reliability gaps. |
| Carbon Compliance Verification Partnership | Embodied carbon documentation capabilities anchor premium positioning in state-backed tenders. |
| Direct EPC Contractor Engagement | Bypasses distributor markups in Gujarat's performance-based procurement corridors. |
| Seismic Retrofit Certification Investment | METI-mandated building standards accelerate carbon fiber reinforced polymer deployment in Japan. |
Research Methodology
Operator-level perspectives from plant managers at integrated cement producers, procurement leads at Southeast Asian commercial developers, EPC contractors in Gujarat's industrial zones, and technical directors at prefabrication facilities anchored the qualitative base. Secondary validation drew from MEE enforcement documentation, BIS green construction material standards, METI building energy code filings, and customs data tracking cross-border composite material flows. Bottom-up project pipeline analysis triangulated against top-down sectoral construction spend estimates.
Sensitivity analysis across the projection horizon tested demand elasticity to MEE compliance timeline acceleration and BIS certification cost inflation. Segmentation dimensions modeled include product maturity tier, application cost sensitivity, technology factory-control level, and end-user technical engagement depth. CAGRs derived from construction spend correlation analysis and material substitution rate tracking. Industry-specific inputs encompassed clinker-to-supplementary-cementitious-material substitution curves and seismic retrofit mandate implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained MEE enforcement intensity or BIS-GB standards divergence would require recalibration. Forecasts reflect documented assumptions regarding carbon accounting protocol adoption timelines and recycled aggregate quality verification infrastructure deployment. Clinker input cost volatility and cross-border certification friction represent primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Carbon Graphite Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Cathode Active Material Market
Advanced Materials
Chemistry 4.0 Market
Advanced Materials
Hexagonal Boron Nitride (HBN) Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Curable Materials Market
Advanced Materials
Global Advanced Materials Market
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Global Next Generation Anode Materials Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Carbon Prepreg Market