
 Pancreatic Stone Protein Testing Market | 2026-2036
Pancreatic Stone Protein Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pancreatic Stone Protein Testing Market Analytics
IVDR reclassification in Europe is restructuring the cost-of-entry calculus for pancreatic stone protein test manufacturers seeking CE-marked status. Thermo Fisher Scientific leverages its global distribution infrastructure to sustain instrument placement contracts across academic medical centers. RayBiotech Life specializes in antibody pair development, anchoring its position in the upstream reagent supply chain for immunoassay kit producers.
Pancreatic stone protein testing encompasses laboratory and point-of-care methods that quantify PSP/regenerating protein levels in blood specimens, typically employing sandwich immunoassay architectures with monoclonal antibody capture and detection pairs targeting epitopes in the C-type lectin domain. These measurements serve primarily to stratify sepsis severity and predict progression to septic shock in critically ill patients. Immunoassay formats currently dominate routine clinical workflows due to throughput compatibility with automated analyzers, while mass spectrometry approaches occupy specialized reference laboratories pursuing absolute quantification against certified protein standards. ELISA technology leads hospital adoption for its cost structure and established protocols, though PCR-based methods are gaining traction in research institutions exploring gene expression correlates.
FDA biomarker qualification programs, EMA's IVDR framework, and ISO 13485 quality management standards collectively shape product development timelines and commercial access for PSP diagnostic platforms. The FDA's Breakthrough Devices pathway accelerates review for tests addressing unmet needs in sepsis management, while IVDR technical documentation requirements have extended certification cycles for European market entry. Stakeholders must monitor evolving payer coverage determinations for novel sepsis biomarkers, as reimbursement clarity will determine whether hospital laboratories expand PSP testing from research protocols into standard order sets.
Market Dynamics
The IVDR reclassification in Europe is compressing certification timelines for PSP diagnostic manufacturers while simultaneously elevating technical documentation burdens. This regulatory recalibration is redrawing competitive entry barriers and reshaping vendor economics across immunoassay platform development.
Growth Catalysts
- IVDR Technical Documentation Mandates:The European Union's In Vitro Diagnostic Regulation is accelerating quality system investments among established manufacturers, filtering out undercapitalized entrants and consolidating market share among compliant vendors.
- Sepsis Bundle Integration:Hospital laboratories in Germany are embedding PSP testing into early warning score protocols, creating institutional demand pull for standardized assay formats compatible with existing analyzer infrastructure.
- Point-of-Care Architectures:Miniaturized immunoassay cartridges are enabling bedside PSP quantification in intensive care units, reducing turnaround times from hours to minutes for septic shock risk stratification.
Market Restraints
- Monoclonal Antibody Supply Concentration:Capture and detection antibody pairs for PSP C-type lectin domain epitopes derive from a limited supplier base in North America, exposing kit manufacturers to batch-to-batch variability and allocation constraints.
- Reimbursement Indeterminacy:Payer coverage for novel sepsis biomarkers remains unsettled across major healthcare systems, forcing hospital laboratories to fund PSP testing through research budgets rather than standard order sets.
- Mass Spectrometry Substitution Threat:Reference laboratories with absolute quantification capabilities against certified protein standards threaten to displace immunoassay volumes for high-accuracy applications in academic medical centers.
Strategic Opportunities
- FDA Breakthrough Devices Pathway:The United States Food and Drug Administration's accelerated review channel for unmet sepsis management needs offers expedited market access for novel PSP platforms demonstrating clinical validity.
- Multicenter Validation Consortia:German university hospitals are pooling patient cohorts for point-of-care PSP platform studies, creating de facto standardization bodies that will shape future product specifications.
- PCR-Gene Expression Convergence:Research institutions are exploring transcriptomic correlates of PSP elevation, opening adjacent revenue streams for diagnostic developers with nucleic acid amplification expertise.
Industry Challenges
- IVDR Certification Timeline Compression:European notified body backlogs have extended CE-marking cycles from months to years, straining working capital for manufacturers with legacy product portfolios requiring recertification.
- Automated Analyzer Integration Complexity:PSP assay formats must achieve seamless interoperability with installed bases of hospital chemistry analyzers, requiring substantial firmware and protocol engineering investments.
- Antibody Pair IP Fragmentation:Epitope mapping patents for PSP detection are distributed across multiple academic and commercial holders, complicating freedom-to-operate analyses for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pancreatic Stone Protein Testing Market |
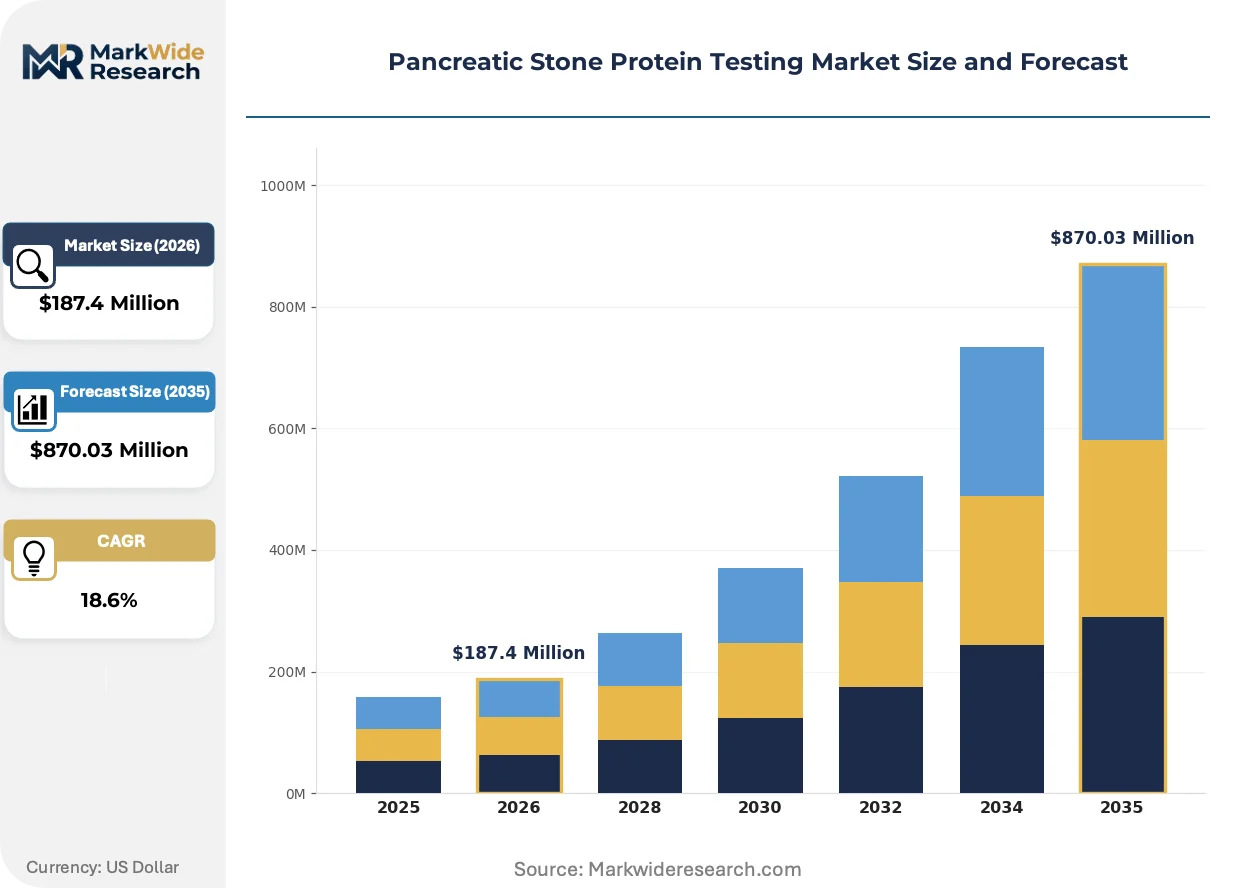
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Assays, Immunoassays, Mass Spectrometry, Liquid Chromatography Technology: ELISA, Western Blotting, PCR, Genetic Sequencing End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinics Application: Clinical Diagnostics, Research Studies, Biomarker Discovery, Personalized Medicine |
| Companies Covered | Thermo Fisher Scientific Inc, RayBiotech Life Inc, LifeSpan BioSciences Inc, Creative Diagnostics Inc, Bio-Rad Laboratories Inc, Abnova Corporation, CUSABIO TECHNOLOGY LLC, Boster Biological Technology Co Ltd, Abionic SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pancreatic Stone Protein Testing Market Evolving Landscape
Platform convergence is dissolving boundaries between centralized laboratory and point-of-care testing modalities. This architectural shift is compressing development cycles and forcing vendors to rethink instrument placement strategies.
Single-use cartridge systems integrating sample preparation, immunoreaction, and optical detection are unifying previously separate workflow steps. Intensive care units in German tertiary hospitals are piloting these platforms for 15-minute PSP turnaround. The technology is unifying sepsis risk stratification with existing blood gas analyzer footprints, reducing capital duplication and training overhead.
The FDA's biomarker qualification framework is restructuring evidentiary requirements for protein-based diagnostic submissions. Manufacturers must now demonstrate analytical validity, clinical validity, and clinical utility through prospective studies rather than retrospective chart reviews. European vendors pursuing dual-market approval are responding by harmonizing study protocols to satisfy both FDA and EMA technical documentation expectations.
Hospital procurement committees are consolidating sepsis biomarker contracts under exclusive vendor arrangements. Academic medical centers in the United States are replacing fragmented point-solution purchasing with multi-year, multi-analyte agreements that bundle PSP testing with procalcitonin and lactate assays. This concentration is most visible in integrated delivery networks spanning multiple states, where standardization incentives override individual physician preference.
Pancreatic Stone Protein Testing Market Segmentation
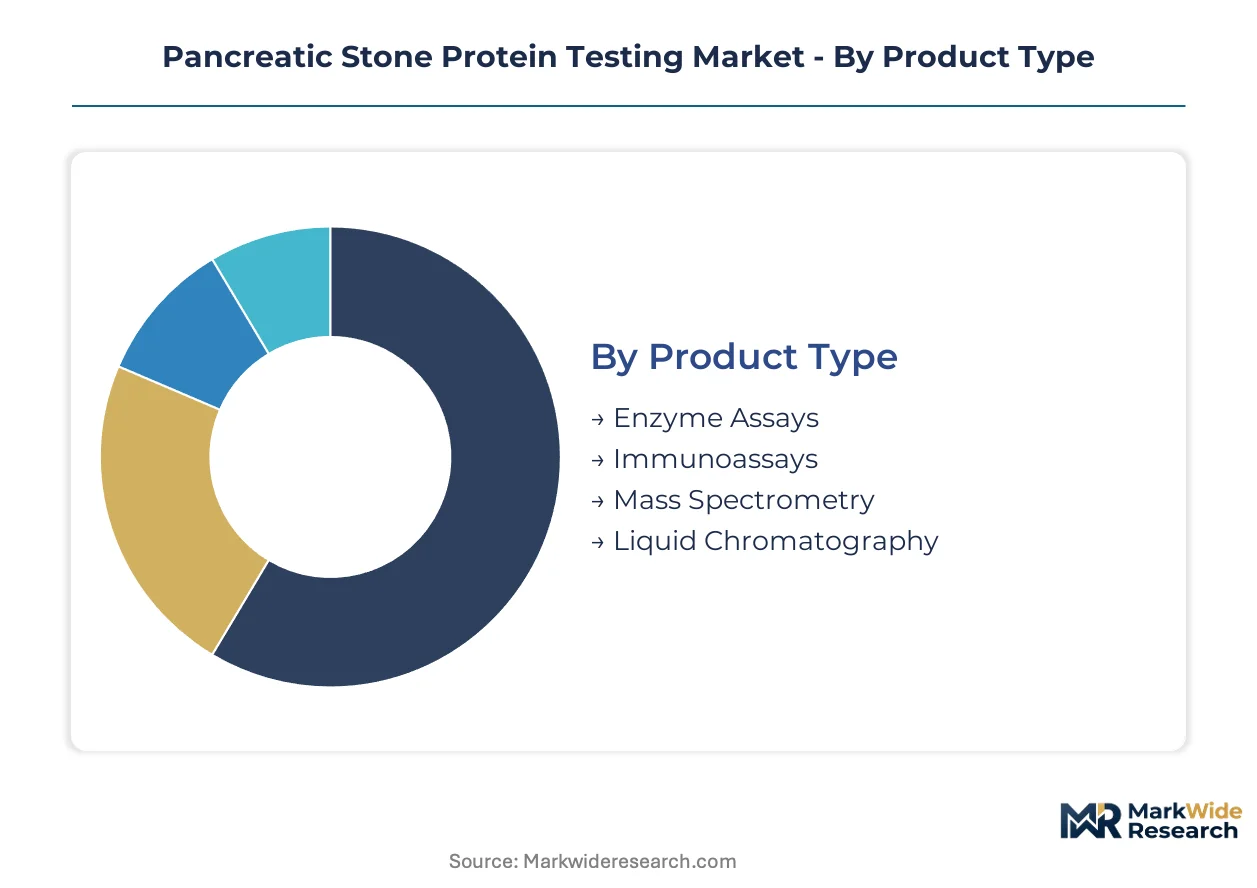
Segmentation in the pancreatic stone protein testing market reflects divergent capital requirements across technology platforms and end-use settings. Laboratory infrastructure investments, regulatory compliance burdens, and reimbursement pathways vary sharply by segment, reshaping vendor prioritization and customer procurement behavior.
Product Type:
Capital intensity escalates dramatically from benchtop enzyme assays to integrated mass spectrometry systems, with instrument costs spanning three orders of magnitude and service contracts consuming 15-20% of initial outlay annually.
- Enzyme Assays:Colorimetric and fluorometric methods quantify PSP enzymatic activity through substrate turnover kinetics, requiring minimal capital outlay and occupying compact bench space. Demand clusters in German university hospital research divisions where grant-funded pilot studies precede larger immunoassay procurement.
- Immunoassays:Sandwich ELISA and chemiluminescent architectures dominate routine clinical throughput, leveraging monoclonal antibody pairs against C-type lectin domain epitopes with automated analyzer compatibility. Hospital laboratories in the United States embed these assays into sepsis bundle protocols, though reimbursement indeterminacy constrains volume expansion.
- Mass Spectrometry:High-resolution platforms enable absolute quantification against certified protein standards with unmatched analytical specificity.
- Liquid Chromatography:HPLC-based separations support research-grade PSP characterization and metabolite correlation studies.
Immunoassays absorb the bulk of installed capacity; mass spectrometry is expanding most quickly among academic medical centers pursuing biomarker qualification-grade data.
Technology:
Technical maturity and regulatory validation status create a hierarchy of deployment readiness, with decades-old ELISA protocols offering immediate clinical utility while genetic amplification methods remain confined to exploratory research.
- ELISA:The workhorse sandwich immunoassay format employs 96-well microplates or automated analyzer cartridges with horseradish peroxidase or alkaline phosphatase detection, achieving pg/mL sensitivity for PSP quantification. Diagnostic laboratories in Germany favor this technology for its interoperability with existing chemistry analyzer footprints and established IVDR technical documentation pathways.
- PCR:Quantitative reverse transcription PCR detects PSP gene expression correlates in whole blood or tissue specimens, bridging protein-level measurements with transcriptomic signatures. Research institutions in the United States deploy this technology for sepsis endotype stratification studies, though clinical translation awaits prospective validation cohorts.
- Western Blotting:Semi-quantitative protein separation and antibody detection serves confirmatory research applications.
- Genetic Sequencing:Next-generation platforms explore PSP locus variants and epigenetic regulation in sepsis susceptibility.
ELISA commands the dominant share of commercial revenue; PCR is climbing the fastest as transcriptomic-biomarker convergence attracts venture funding.
End User:
Procurement authority and budget source—operational revenue versus research grants versus capital equipment cycles—determine technology selection and vendor relationship intensity across customer categories.
- Hospitals:Integrated delivery networks and tertiary academic centers deploy PSP testing within intensive care unit workflows, requiring point-of-care capable platforms with 15-minute turnaround for septic shock risk stratification. German university hospitals lead multicenter validation consortia that shape future product specifications.
- Diagnostic Laboratories:Centralized reference laboratories process high-volume PSP testing for health system clients, prioritizing throughput and automated quality control over bedside speed.
- Research Institutions:Academic medical centers and contract research organizations pursue biomarker discovery and clinical utility studies.
- Clinics:Outpatient and community settings represent nascent demand for PSP testing in ambulatory sepsis risk assessment.
Hospitals absorb the bulk of installed capacity; diagnostic laboratories are expanding most quickly as health system consolidation centralizes testing volumes.
Application:
Revenue model differentiation—fee-for-service clinical testing versus grant-funded research versus pharmaceutical partnership—segments the addressable opportunity and shapes product development roadmaps.
- Clinical Diagnostics:FDA-cleared and CE-marked PSP assays support sepsis severity stratification and progression monitoring in critically ill patients, with reimbursement codes determining commercial viability. The FDA's Breakthrough Devices pathway accelerates review for tests addressing unmet needs in this indication.
- Research Studies:Investigational use only products enable prospective validation cohorts and comparator studies against established sepsis biomarkers like procalcitonin.
- Biomarker Discovery:Exploratory platforms identify novel PSP isoforms and post-translational modifications with diagnostic potential.
- Personalized Medicine:Pharmacogenomic integration of PSP levels with antibiotic stewardship protocols remains early-stage.
Clinical diagnostics absorbs the bulk of commercial revenue; research studies are expanding most quickly as IVDR recertification delays redirect vendor investment toward exploratory applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biotechnology parks in Heidelberg and Munich concentrate pancreatic stone protein testing development, with tax incentives under the High-Tech Gründerfonds accelerating platform commercialization. University hospital networks in these zones drive multicenter validation demand.
Germany
Heidelberg and Munich university hospitals coordinate point-of-care PSP platform trials through the German Sepsis Society. EMA's IVDR technical documentation requirements extend certification timelines for domestic manufacturers. The Baden-Württemberg medical technology cluster houses Abionic SA's cartridge development operations.
United States
FDA Breakthrough Devices pathway accelerates review for sepsis risk stratification assays addressing unmet clinical needs. The Boston-Cambridge corridor anchors immunoassay antibody pair development through contract research organizations. California's Stanford and UCSF medical centers lead biomarker qualification studies for PSP clinical utility evidence.
Switzerland
Swissmedic's streamlined quality system assessments attract IVDR-compliant manufacturers seeking parallel European market access. Basel's pharmaceutical-biotech corridor integrates PSP testing into antibiotic stewardship protocols at University Hospital Basel. The country's diagnostic precision manufacturing base supplies optical detection components for cartridge-based platforms.
United Kingdom
NHS England's sepsis improvement program creates institutional procurement pull for standardized biomarker assays. The MHRA's post-Brexit regulatory autonomy enables tailored approval pathways for novel protein diagnostics. London's Imperial College and Guy's Hospital run comparator studies against procalcitonin for PSP clinical adoption.
China
NMPA's innovative medical device review channel prioritizes sepsis management technologies with domestic clinical data. Shanghai's Ruijin Hospital and Beijing's Peking Union Medical College Hospital lead PSP assay validation for ICU workflows. The Yangtze River Delta biotech manufacturing zone produces monoclonal antibody reagents for regional kit assemblers.
Pancreatic Stone Protein Testing Market Competitive Landscape
North American life science conglomerates anchor one tier; European point-of-care specialists and Asian reagent suppliers hold differentiated positions. The market exhibits moderate concentration with three to four dominant platform vendors and fragmented upstream antibody supply. Strategic archetypes include diversified diagnostics conglomerates, immunoassay reagent specialists, and emerging cartridge-platform developers. Competitive dynamics center on automated analyzer integration partnerships and IVDR certification race timing.
Among diversified laboratory technology providers, Thermo Fisher Scientific Inc exemplifies the scale-driven archetype through global distribution infrastructure and installed analyzer base leverage. RayBiotech Life Inc and Bio-Rad Laboratories Inc occupy positions within the immunoassay reagent and quality control tier, supplying antibody pairs and validation standards to downstream kit manufacturers. These three entities represent distinct competitive vectors: instrumentation placement, upstream biological reagents, and clinical diagnostic systems.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| RayBiotech Life Inc |
| LifeSpan BioSciences Inc |
| Creative Diagnostics Inc |
| Bio-Rad Laboratories Inc |
| Abnova Corporation |
| CUSABIO TECHNOLOGY LLC |
| Boster Biological Technology Co Ltd |
| Abionic SA |
| Others |
Value Network & Pricing Analysis
Hospital laboratory consolidation under exclusive vendor arrangements is compressing procurement timelines and forcing antibody pair suppliers to hold finished-goods inventory closer to end-use markets, elevating working capital requirements and compressing margins on spot purchases.
Pricing Analysis
Premium pricing attaches to monoclonal antibody pairs with sub-30-day lead times, while spot-market ELISA kits trade at discounts reflecting batch-to-batch variability risks. The dominant structure is three-tier pricing across premium, standard, and economy levels, with differentiation driven by IVDR certification status and automated analyzer compatibility. Pricing pressure stems from mass spectrometry substitution threats in academic medical centers. Research institutions exhibit highest price sensitivity; integrated delivery networks least.
Supply Chain Analysis
IVDR technical documentation mandates gate European market access, forcing manufacturers to qualify suppliers against ISO 13485 quality management standards. Monoclonal antibody production concentrates in the United States, China, and Switzerland, with capture-detection pair development anchored in the Boston-Cambridge corridor. Raw material dependencies include recombinant protein expression systems, horseradish peroxidase detection reagents, and optical-grade polystyrene microplates. Single-source vulnerability pervades the C-type lectin domain epitope supplier base. Distribution runs through diagnostic reagent distributors and direct hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is accelerating into a vertical-integration race, with control over monoclonal antibody pair supply emerging as the decisive margin lever.
For Market Incumbents: Cement analyzer placement contracts through multi-year, multi-analyte bundling with procalcitonin and lactate assays. Deepen backward integration into antibody pair production to neutralize batch-to-batch variability risks from North American suppliers. IVDR recertification timeline compression threatens legacy product portfolios; accelerate quality system investments to filter out undercapitalized competitors. For New Entrants and Emerging Players: Enter via point-of-care cartridge platforms for German university hospital multicenter validation consortia, where 15-minute turnaround specifications remain undersupplied. The most penetrable white space sits in PCR-gene expression convergence for sepsis endotype stratification studies. Pursue FDA Breakthrough Devices pathway submissions to bypass entrenched immunoassay incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with cartridge-platform developers possessing IVDR-compliant manufacturing given European notified body backlogs extending certification cycles. Long-term viability favors entities with nucleic acid amplification expertise bridging protein and transcriptomic biomarker convergence. Monitor FDA biomarker qualification program advancement as inflection signal for reimbursement clarity.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | EMA's extended certification cycles filter out undercapitalized manufacturers and consolidate compliant vendors. |
| Automated Analyzer Integration Partnership | Seamless interoperability with hospital chemistry analyzers requires substantial firmware engineering investments. |
| Multicenter Validation Consortium Participation | German university hospital networks shape de facto product specifications for point-of-care platforms. |
| Antibody Pair Supply Integration | Control over C-type lectin domain epitope sourcing neutralizes batch-to-batch variability and allocation constraints. |
| FDA Breakthrough Devices Pathway Submission | Accelerated review channel offers expedited market access for novel sepsis risk stratification platforms. |
Research Methodology
Independent corroboration across hospital laboratory directors, diagnostic reagent procurement managers, and biomedical engineers underwrites the qualitative findings. Primary interviews with regulatory affairs specialists at IVD manufacturers, GPO contracts managers, and point-of-care platform engineers were cross-referenced against FDA 510(k) filings, EMA IVDR technical documentation databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up installed base estimates and top-down market sizing were reconciled through iterative triangulation.
Rate-of-change decomposition across the analysis window isolates volume and price trajectories by product type, technology platform, end-user setting, and application. Segmentation dimensions modeled include immunoassay format, analyzer throughput tier, point-of-care versus laboratory deployment, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to hospital adoption data and reimbursement timeline assumptions. Forecast inputs incorporate IVDR recertification backlog projections and FDA biomarker qualification program advancement.
Forecast precision tightens around the base case; tail outcomes carry wider variance under reimbursement determination delays or monoclonal antibody supply disruptions. Forecasts reflect documented assumptions regarding hospital procurement committee consolidation and payer coverage expansion timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Apoptosis Testing Market
Testing Services
Toxicology Testing Services Market
Testing Services
United States Esoteric Testing Market
Testing Services
Biological Safety Testing Products and Services Market
Testing Services
West Nile Virus Testing Market
Testing Services
Self-Testing Market
Testing Services
Cholesterol Test Market
Testing Services
Faecal Calprotectin Testing Market
Testing Services
Thailand Point-Of-Care Testing (POCT) Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Influenza a/B Combo Testing Market
Testing Services
Large Molecule Bioanalytical Testing Services Market
Testing Services
Prothrombin Time Testing Market
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Mono Rapid Testing Market
Testing Services
Aerospace and Life Science Testing Certification Market