
 Polyglycerol Sebacate (PGS) Market | 2026-2036
Polyglycerol Sebacate (PGS) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyglycerol Sebacate (PGS) Market Analysis
Custom synthesis and formulation services is hardening as a distinct revenue layer alongside bulk polymer sales. Fuso Chemical Co., Ltd. leverages its glycerol derivative expertise to control upstream feedstock quality for medical-grade PGS production. PolySciTech (Akina, Inc.) specializes in tunable molecular weight variants that target specific degradation rates for tissue engineering clients. Evonik Industries AG anchors its position through cGMP-compliant manufacturing infrastructure that serves pharmaceutical contract development organizations.
Polyglycerol sebacate is an aliphatic polyester elastomer synthesized from glycerol and sebacic acid via polycondensation, exhibiting tunable mechanical properties with Young's moduli ranging from 0.05 to 1.5 MPa depending on crosslink density and curing conditions. The polymer degrades through surface erosion into non-toxic metabolites, making it suitable for implantable devices, drug delivery matrices, and soft tissue scaffolds where flexibility and bioresorbability coexist. Biodegradable product types command premium positioning due to batch-to-batch consistency requirements and lengthy regulatory qualification cycles. Electrospinning technology for nanofiber scaffold fabrication represents the fastest-expanding processing segment, while solvent casting maintains dominance in thin-film applications where thickness uniformity determines device performance.
FDA enforces ISO 10993 biocompatibility testing suites for permanent implant classifications involving PGS, pushing developers toward extensive cytotoxicity and sensitization documentation before clinical entry. EMA's Medical Device Regulation requires notified body involvement for class III devices incorporating novel elastomers, extending European market access timelines relative to historical benchmarks. Stakeholders must monitor evolving FDA guidance on resorbable synthetic polymers and anticipate how EMA harmonization efforts will reshape submission requirements for cross-border product registrations.
Market Dynamics
FDA 510(k) clearance tightening for implantable elastomers is forcing PGS developers to front-load material characterization investment before clinical entry, compressing early-stage funding timelines and favoring well-capitalized contract manufacturers.
Growth Catalysts
- Cardiovascular scaffold demand:Academic medical centers in the United States are validating PGS for cardiac patch applications, driving preclinical volume through contract research organizations.
- ISO 10993 harmonization:Standardized biocompatibility testing suites reduce regulatory friction for cross-border submissions, accelerating European market access timelines.
- Electrospinning maturation:Nanofiber fabrication technology enables sub-micron scaffold architectures that match native extracellular matrix morphology for neural tissue engineering.
Market Restraints
- Sebacic acid supply concentration:Castor oil derivative sourcing clusters in India and China, exposing PGS producers to agricultural commodity volatility and geopolitical friction.
- Batch-to-batch consistency costs:Medical-grade polycondensation requires tight control over molecular weight distribution, elevating quality assurance overhead relative to industrial polyester benchmarks.
- Permanent implant classification:FDA's stringent cytotoxicity and sensitization documentation requirements extend premarket notification cycles beyond resorbable polymer historical norms.
Strategic Opportunities
- Drug-eluting PGS matrices:Tunable degradation kinetics enable programmed release profiles for oncology and ophthalmology applications where mechanical flexibility and payload capacity coexist.
- EMA Medical Device Regulation readiness:Early notified body engagement for class III device classifications creates first-mover positioning in European soft tissue reconstruction markets.
- Custom synthesis services:Formulation partnerships with pharmaceutical contract development organizations capture value upstream of bulk polymer commoditization.
Industry Challenges
- Crosslinked network characterization:Quantifying gel fraction and effective crosslink density requires specialized rheometry expertise scarce among standard polymer analytical laboratories.
- Terminal sterilization validation:Gamma irradiation and ethylene oxide protocols must demonstrate minimal impact on elastomeric mechanical properties across shelf-life claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyglycerol Sebacate (PGS) Market |
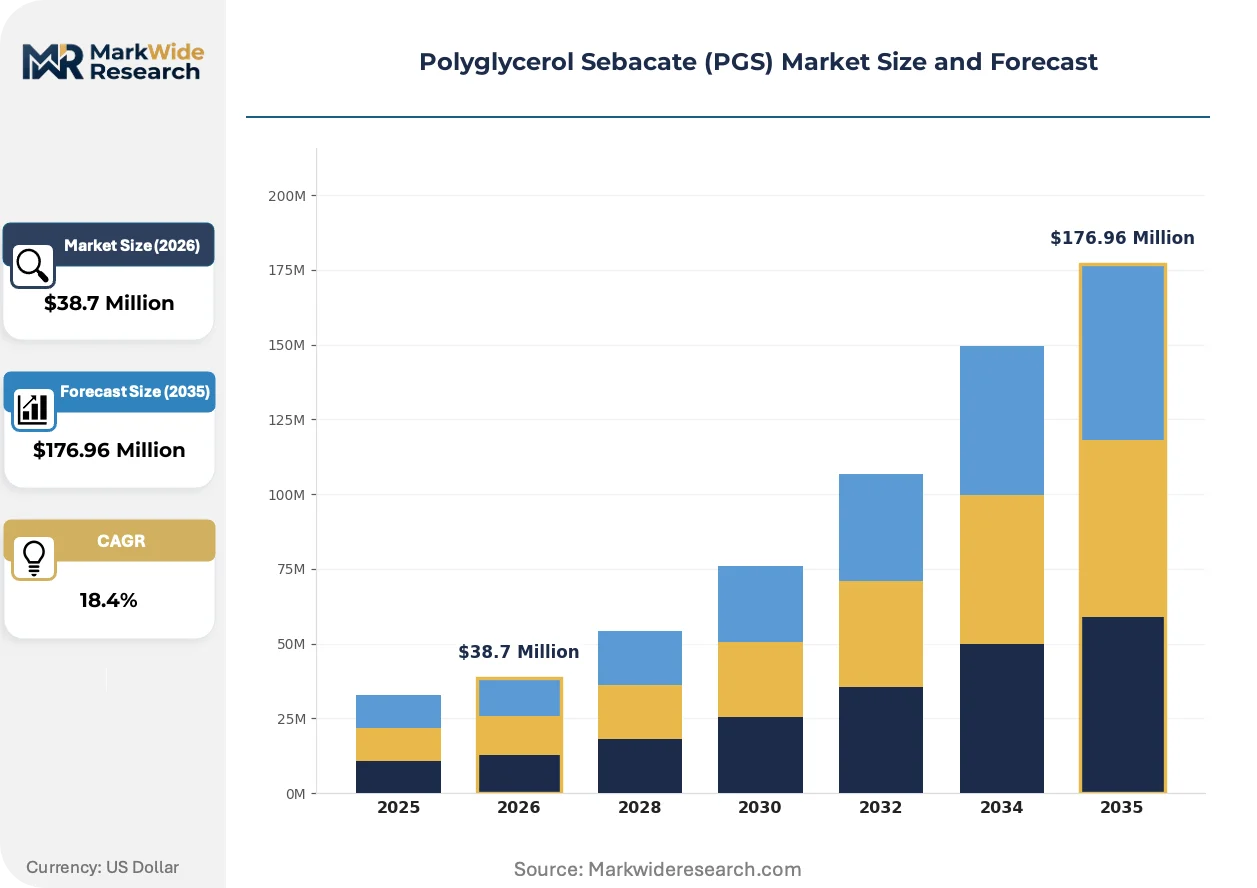
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $176.96 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester-based, Biodegradable, Thermoplastic, Elastomer Application: Biomedical, Packaging, Coatings, Adhesives End User: Pharmaceuticals, Food Industry, Consumer Goods, Manufacturing Technology: Solvent Casting, Melt Processing, Electrospinning, 3D Printing |
| Companies Covered | Fuso Chemical Co., Ltd., PolySciTech (Akina, Inc.), BASF SE, Lonza Group AG, Secant LLC, Evonik Industries AG, Sigma-Aldrich (Merck Group), Polysciences Inc., Cambridge Polymers Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyglycerol Sebacate (PGS) Market Emerging Trajectories
Processing technology convergence and regulatory pathway evolution are redrawing competitive boundaries between bulk polymer suppliers and integrated device developers.
Electrospun PGS nanofiber scaffolds is expanding into neural and musculoskeletal tissue engineering applications where topographical cues guide cell differentiation. Research hospitals in Boston and San Francisco are establishing dedicated fabrication facilities to bypass external supply constraints. The technology is compressing lead times for patient-specific scaffold geometries while elevating capital requirements for in-house electrospinning infrastructure.
EMA's Medical Device Regulation (MDR) implementation is extending notified body review timelines for class III devices incorporating novel elastomers. European manufacturers are front-loading clinical evidence generation to preempt technical documentation deficiencies. Cardiovascular patch developers are most affected, with several programs accelerating biocompatibility testing to maintain regulatory submission schedules.
Academic medical centers are consolidating procurement around pre-qualified contract manufacturers with established FDA master files. The shift displaces small-batch custom synthesis vendors unable to absorb cGMP infrastructure costs. This concentration is most visible in the United States, where National Institutes of Health funding mechanisms now require documented manufacturing scale-up pathways prior to translational grant awards.
Polyglycerol Sebacate (PGS) Market Segmentation
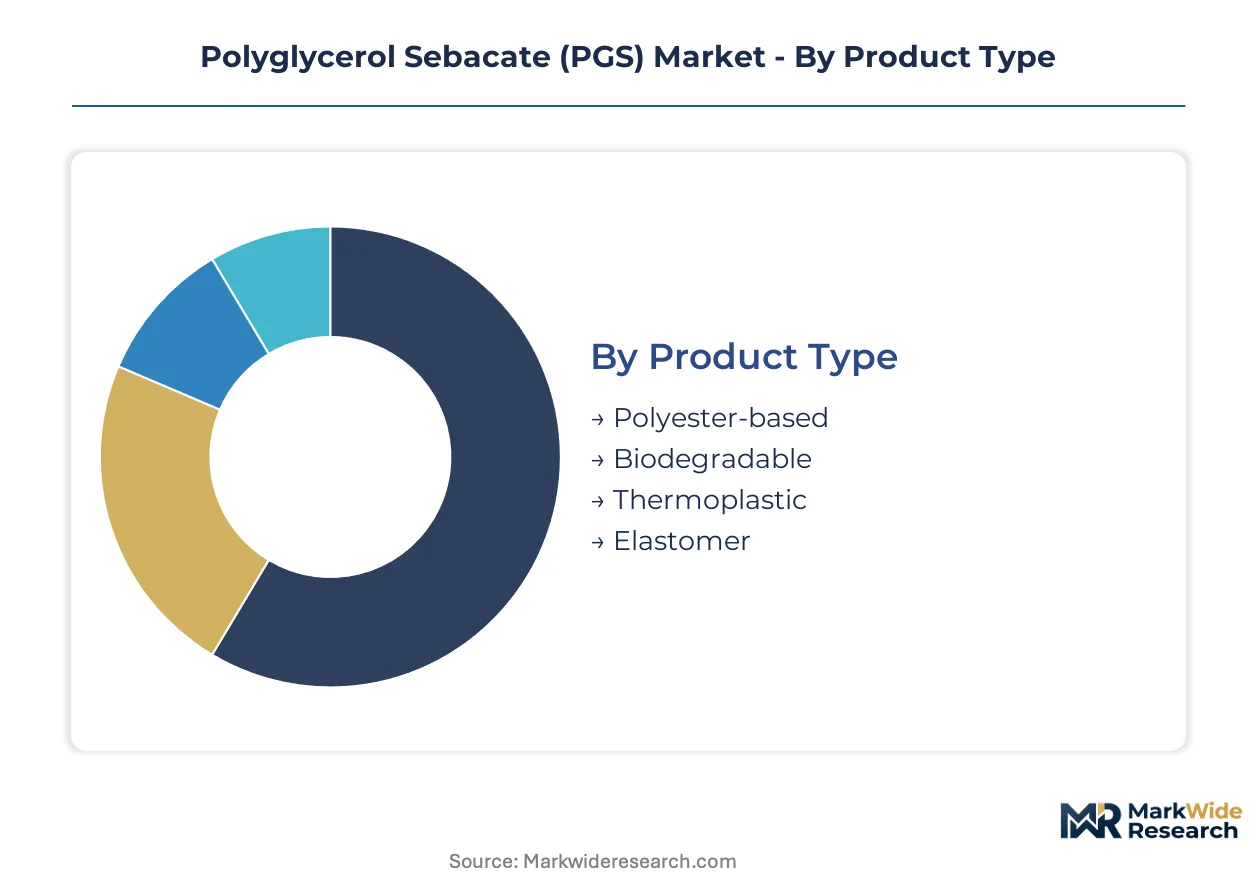
PGS segmentation reflects divergent technical requirements across implantable medical devices and industrial applications. Product form, processing method, and end-use specifications each impose distinct qualification barriers that reshape supplier economics.
Product Type:
Buyers select PGS variants based on degradation timeline requirements and mechanical property specifications for target tissue environments.
- Biodegradable:Medical-grade formulations degrade through surface erosion into non-toxic glycerol and sebacic acid metabolites. FDA 510(k) pathways for cardiovascular patches and drug-eluting matrices concentrate demand in United States academic medical centers where batch-to-batch consistency commands premium positioning.
- Elastomer:Crosslinked networks exhibit tunable Young's moduli from 0.05 to 1.5 MPa depending on curing conditions. Soft tissue scaffold applications in neural and cardiac engineering drive formulation partnerships with contract development organizations seeking patient-specific mechanical matching.
- Polyester-based:Aliphatic polyester backbone synthesized via polycondensation of glycerol and sebacic acid.
- Thermoplastic:Linear uncrosslinked variants enable melt processing for industrial coating applications.
Biodegradable grades lead on scale; elastomer variants lead on momentum.
Application:
Application selection determines regulatory pathway complexity and manufacturing infrastructure requirements.
- Biomedical:Tissue engineering scaffolds, drug delivery matrices, and implantable devices leverage PGS bioresorbability and flexibility. Cardiovascular patch validation at Boston and San Francisco research hospitals drives preclinical volume through contract research organizations.
- Coatings:Thin-film barrier applications exploit solvent-cast uniformity for controlled release kinetics.
- Packaging:Biodegradable food-contact films compete with petroleum-based alternatives on sustainability credentials.
- Adhesives:Pressure-sensitive formulations target medical device assembly where cytotoxicity constraints limit conventional acrylic options.
Biomedical applications dominate revenue concentration; coatings represent the steepest expansion trajectory.
End User:
End-user procurement patterns separate qualified medical-grade suppliers from commodity polymer vendors.
- Pharmaceuticals:Drug-eluting matrix developers require cGMP-compliant manufacturing with documented master files. Evonik Industries AG and PolySciTech anchor this segment through established FDA regulatory packages.
- Food Industry:Packaging film buyers prioritize cost parity with conventional polyesters over performance differentiation.
- Consumer Goods:Cosmetic and personal care applications drive small-batch custom synthesis volumes.
- Manufacturing:Industrial adhesive and coating formulators source thermoplastic grades for melt-compounding operations.
Pharmaceuticals lead on margin contribution; consumer goods lead on volume fragmentation.
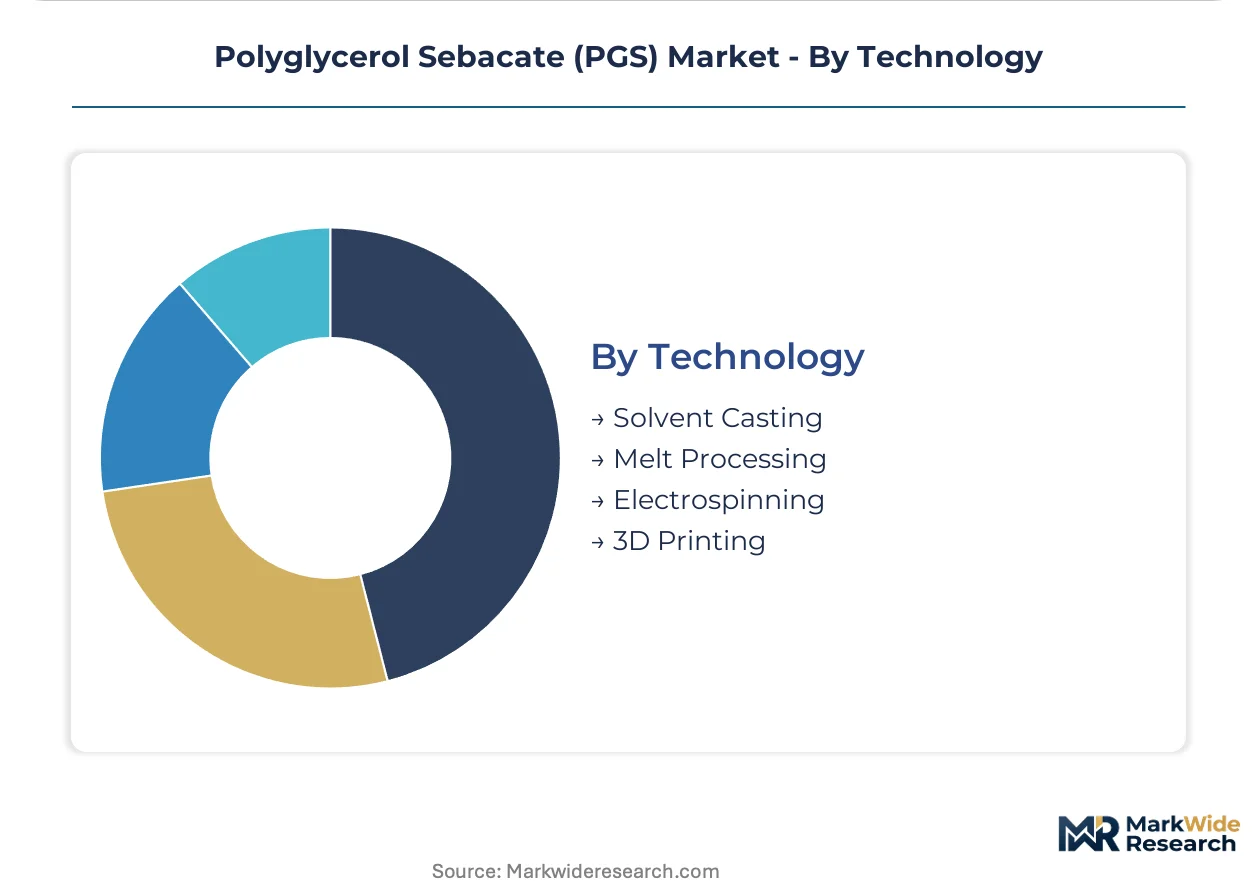
Technology:
Processing technology selection constrains achievable scaffold architecture and unit economics.
- Electrospinning:Nanofiber fabrication enables sub-micron architectures matching native extracellular matrix morphology. Neural tissue engineering applications in United States research hospitals are establishing dedicated in-house facilities to bypass external supply constraints.
- Solvent Casting:Thin-film dominance persists where thickness uniformity determines drug release kinetics and mechanical performance.
- Melt Processing:Extrusion and injection molding suit industrial thermoplastic applications without crosslink density requirements.
- 3D Printing:Patient-specific scaffold geometries emerge through direct-ink-write and stereolithography adaptations.
Solvent casting leads on installed base; electrospinning gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting PGS manufacturing toward jurisdictions with streamlined biocompatibility documentation pathways, while demand concentrates in high-reimbursement healthcare markets where cardiovascular scaffold validation commands premium pricing.
United States
FDA 510(k) clearance tightening for implantable elastomers is accelerating preclinical validation volumes through Boston and San Francisco academic medical centers. National Institutes of Health funding mechanisms now require documented cGMP manufacturing scale-up pathways prior to translational grant awards. Cardiovascular patch developers in the Greater Boston cluster are establishing dedicated electrospinning facilities to bypass external supply constraints.
Germany
EMA Medical Device Regulation implementation is extending notified body review timelines for class III devices incorporating novel elastomers. German pharmaceutical contract development organizations are front-loading clinical evidence generation to preempt technical documentation deficiencies. The Rhine-Main industrial corridor anchors cGMP-compliant polymer manufacturing infrastructure serving cross-border European submissions.
China
NMPA medical device classification rules for resorbable synthetic polymers are harmonizing with ISO 10993 biocompatibility testing suites. Castor oil derivative processing clusters in Shandong and Hebei provinces dominate sebacic acid feedstock supply. Yangtze River Delta medical device manufacturers are qualifying PGS grades for export-oriented drug-eluting matrix applications.
India
CDSCO medical device registration pathways for permanent implants are tightening material characterization requirements for novel elastomers. Gujarat and Maharashtra chemical processing hubs control castor oil derivative refining capacity for sebacic acid production. Hyderabad and Bangalore contract research organizations are expanding preclinical biocompatibility testing capacity for cardiovascular scaffold developers.
Japan
PMDA pharmaceutical affairs consultation procedures for combination products are extending review cycles for drug-eluting PGS matrices. METI industrial technology grants are supporting electrospinning equipment localization for neural tissue engineering applications. Osaka-Kobe chemical industry clusters maintain specialty polyester polymerization expertise for medical-grade production.
Polyglycerol Sebacate (PGS) Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade supply chains consolidating around cGMP-certified infrastructure while research-grade volumes fragment across custom synthesis vendors. Three archetypes dominate: upstream chemical conglomerates controlling glycerol derivative feedstocks, mid-scale polymer specialists offering tunable molecular weight variants, and integrated device developers building captive electrospinning capacity. Capacity expansion and regulatory master file accumulation represent the dominant competitive moves, as FDA documentation requirements elevate barriers to clinical-grade supply.
Within the pharmaceutical-grade tier, Evonik Industries AG and Fuso Chemical Co., Ltd. exemplify divergent strategic positions. Evonik anchors cGMP-compliant manufacturing infrastructure serving contract development organizations with established regulatory packages. Fuso Chemical occupies a feedstock-integrated position leveraging glycerol derivative expertise to control upstream quality for medical-grade production. PolySciTech (Akina, Inc.) represents the tunable-variant specialist archetype, targeting specific degradation rate requirements for tissue engineering clients through molecular weight customization.
| Leading Market Players |
|---|
| Fuso Chemical Co., Ltd. |
| PolySciTech (Akina, Inc.) |
| BASF SE |
| Lonza Group AG |
| Secant LLC |
| Evonik Industries AG |
| Sigma-Aldrich (Merck Group) |
| Polysciences Inc. |
| Cambridge Polymers Group |
| Others |
Supply Flow & Price Mechanics
Castor oil derivative costs cascade from Gujarat and Maharashtra processing hubs through sebacic acid pricing tiers into medical-grade PGS feedstock quotations. Pharmaceutical contract development organizations absorb premium positioning for cGMP-certified batches, while research-grade buyers face volatile spot pricing tethered to agricultural commodity cycles.
Pricing Analysis
Distributor markups compress as academic medical centers consolidate procurement around pre-qualified contract manufacturers with established FDA master files. Pricing stratifies across medical-grade certification tiers, with ISO 10993-compliant batches commanding substantial premiums over industrial polyester benchmarks. Cost compression in research-grade segments intensifies because small-batch custom synthesis vendors face displacement from cGMP infrastructure investments. Pharmaceutical drug-eluting matrix developers exhibit lowest price sensitivity, while industrial coating formulators demonstrate highest elasticity to sebacic acid feedstock fluctuations.
Supply Chain Analysis
ISO 10993 and FDA master file qualification gates restrict viable supplier pools to cGMP-certified manufacturers with documented biocompatibility testing suites. Feedstock concentration centers on India and China for castor oil derivative refining, with Germany and the United States anchoring medical-grade polymerization infrastructure. Raw material dependencies rest on sebacic acid, glycerol derivatives, and crosslinking catalysts. Single-source vulnerability in South Asian agricultural processing exposes PGS producers to monsoon-driven supply interruptions. Distribution runs through pharmaceutical contract development organizations and academic medical center procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Polyglycerol Sebacate market compounds steadily as cardiovascular tissue engineering validation accelerates through Boston and San Francisco research hospital clusters.
For Market Incumbents: Acquire electrospinning fabrication capabilities to preempt patient-specific scaffold geometry demand from academic medical centers establishing in-house facilities. Consolidate FDA master file documentation to defend against emerging Asian contract manufacturers investing in cGMP infrastructure. Backward integration into sebacic acid feedstock processing mitigates agricultural commodity volatility from Indian castor oil derivative sourcing. For New Entrants and Emerging Players: Capture neural tissue engineering applications where sub-micron scaffold architectures remain undersupplied relative to cardiovascular patch saturation. Target European notified body pre-engagement services for EMA Medical Device Regulation readiness, as German pharmaceutical contract development organizations front-load clinical evidence generation. Partner with National Institutes of Health-funded translational programs requiring documented manufacturing scale-up pathways as a go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where cGMP infrastructure costs exceed small-batch custom synthesis vendor absorption capacity. The five-to-ten year viability window favors acquisition targets with established FDA regulatory packages and electrospinning equipment portfolios. Watch for CDSCO and NMPA harmonization with ISO 10993 biocompatibility testing suites as the signal indicating Asian market access timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Master File Accumulation | Documentation depth determines qualification for NIH translational grant partnerships. |
| Electrospinning Capacity Expansion | In-house nanofiber fabrication bypasses external supply constraints for neural scaffold developers. |
| Sebacic Acid Backward Integration | Upstream control over castor oil derivative processing insulates margin from agricultural volatility. |
| EMA Notified Body Pre-Engagement | Early class III device consultation compresses European market access timelines. |
| Custom Synthesis Service Layering | Formulation partnerships capture value upstream of bulk polymer commoditization. |
Methodological Framework
Bottom-up biomedical application modeling reconciled against top-down polymer supply tracking forms the analytical core of this study. Primary interviews with tissue engineering researchers, biomedical engineers at academic medical centers, contract development organization procurement leads, and regulatory affairs specialists combined with secondary validation from FDA 510(k) filings, EMA Medical Device Regulation technical documentation, ClinicalTrials.gov cardiovascular scaffold entries, and customs trade data for sebacic acid derivatives. Triangulation across these sources established demand segmentation and supply concentration baselines.
Input-output matrices mapped product type, application, and processing technology dimensions against end-user procurement patterns across the projection horizon. CAGRs derived from elasticity modeling of cardiovascular patch validation volumes, electrospinning equipment installation rates, and pharmaceutical contract manufacturing outsourcing trends. Forecast inputs incorporated ISO 10993 harmonization timelines, castor oil harvest yield projections, and NIH funding mechanism requirements for cGMP scale-up documentation.
Regulatory pathway shifts, agricultural commodity price spikes, and electrospinning technology maturation delays are the dominant revision risks to the outlook. Deviation in FDA resorbable polymer guidance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Rosin Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
High-K and CVD ALD Metal Precursors Market
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Cubeb Oil Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
Ethyl Ascorbic Acid Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Global Vinyl Sulfone Market