
 Nucleotides Market | 2026-2036
Nucleotides Market Size, Share, and Industry Trends Forecast 2026-2036
Nucleotides Market Intelligence
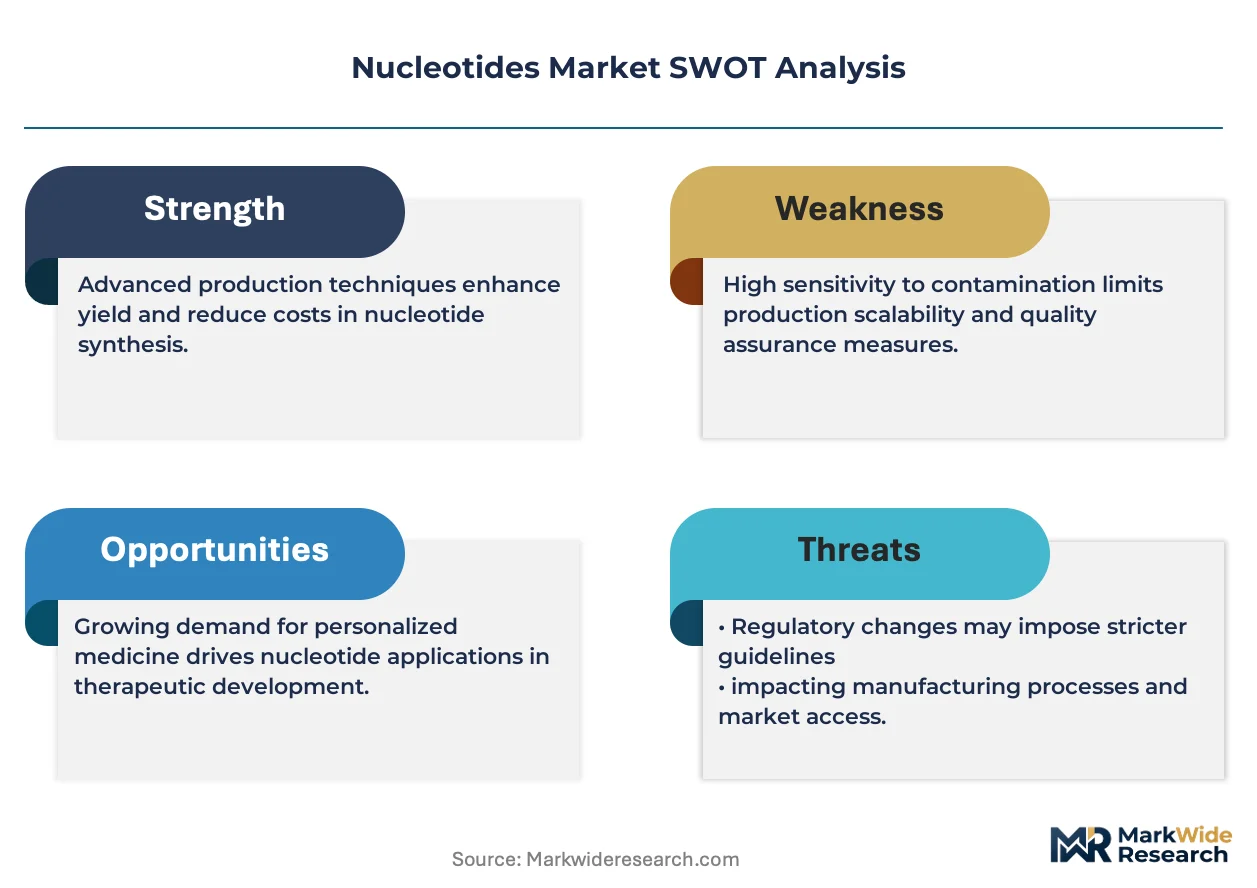
ISO 13485 certification for in vitro diagnostic-grade nucleotides is redrawing supplier eligibility across pharmaceutical supply chains. Thermo Fisher Scientific leverages its North American distribution network to sustain bulk nucleotide triphosphate availability for gene synthesis workflows. Ajinomoto Co. anchors Japanese pharmaceutical demand through fermentation-derived nucleotide production at scale. Merck differentiates via its synthetic nucleotide portfolio, competing on purity grades that meet CRISPR guide RNA manufacturing standards.
Nucleotides are nitrogenous base-sugar-phosphate monomers—adenine, guanine, cytosine, thymine, or uracil linked to ribose or deoxyribose and one to three phosphate groups—synthesized chemically or through microbial fermentation for polymerization into DNA, RNA, or therapeutic oligonucleotides. Oligonucleotides command premium positioning as antisense and siRNA therapeutics advance through clinical pipelines, while nucleotide triphosphates represent the fastest-expanding product category due to mRNA vaccine manufacturing scale-up. Pharmaceutical firms constitute the dominant application segment, though nutraceuticals gain traction as nucleotide-fortified infant formula and clinical nutrition products expand in East Asian markets.
FDA Current Good Manufacturing Practice enforcement and EMA's MDR traceability requirements are tightening nucleotide supplier qualification protocols, particularly for GMP-grade materials used in cell and gene therapies. China's NMPA now mandates registration of nucleotide raw material sources for imported biologics, reshaping cross-border procurement patterns. REACH compliance in Europe adds further chemical safety documentation burdens for synthetic nucleotide importers. Stakeholders must monitor evolving pharmacopeial monographs and dual-source qualification timelines as therapeutic nucleotide demand outpaces specialty chemical manufacturing capacity.
Market Dynamics
The nucleotides market is being restructured by the divergence between pharmaceutical-grade GMP requirements and research-grade supply chains, with mRNA therapeutic manufacturing forcing raw material qualification timelines that outpace specialty chemical production capacity expansion.
Growth Catalysts
- mRNA Platform Expansion:Gene therapy pipelines at pharmaceutical firms are pulling nucleotide triphosphate volumes upward as CRISPR-based editing programs advance toward commercial manufacturing.
- REACH Compliance Maturation:European chemical safety documentation standardization is filtering out subscale synthetic nucleotide importers and consolidating procurement toward qualified suppliers.
- Fermentation Scale-Up:Microbial production methods are displacing petrochemical synthesis for cytidine and uridine derivatives, lowering input cost volatility for bulk nucleotide manufacturing.
Market Restraints
- Phosphate Raw Material Concentration:Phosphorus supply chains concentrate in Morocco and China, exposing nucleotide manufacturers to export restriction risk and price spikes.
- GMP Facility Capital Intensity:Constructing pharmaceutical-grade nucleotide production lines requires $50-100 million per site, freezing out mid-scale entrants.
- NMPA Registration Friction:China's tightened raw material source disclosure rules for imported biologics are extending cross-border supplier qualification timelines by 12-18 months.
Strategic Opportunities
- Cell Therapy Grade White Space:ISO 13485-certified nucleotide demand for in vitro diagnostics and cell therapy manufacturing is outpacing dedicated supplier capacity in the United States.
- East Asian Nutraceutical Fortification:Infant formula and clinical nutrition manufacturers in Japan and South Korea are expanding nucleotide premix procurement for immune-support product lines.
- Dual-Source Mandate Tailwind:FDA Current Good Manufacturing Practice enforcement is forcing pharmaceutical firms to qualify secondary nucleotide suppliers, opening slots for new entrants with documented quality systems.
Industry Challenges
- Specialized Bioprocess Talent Scarcity:Fermentation-scale nucleotide production requires rare hybrid skill sets combining microbial genetics with pharmaceutical quality assurance.
- Pharmacopeial Monograph Lag:USP and EP nucleotide purity standards are evolving slower than CRISPR guide RNA manufacturing requirements, creating specification mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nucleotides Market |
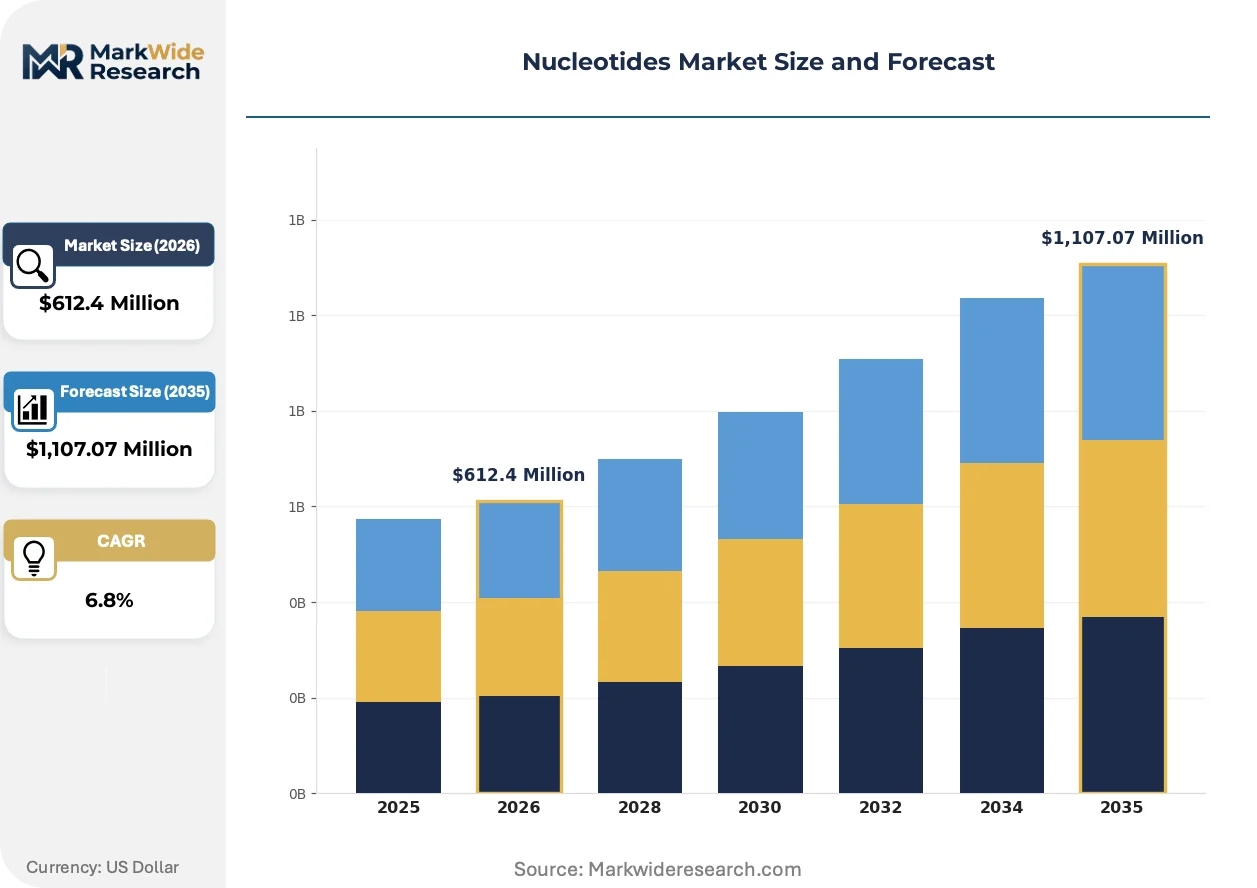
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deoxyribonucleic Acid, Ribonucleic Acid, Oligonucleotides, Nucleotide Triphosphates Application: Pharmaceuticals, Nutraceuticals, Animal Feed, Cosmetics End User: Biotechnology Companies, Academic Institutions, Pharmaceutical Firms, Research Laboratories Form: Powder, Liquid, Capsule, Tablet |
| Companies Covered | Merck, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., DAESANG, Meihua Holdings Group Co., Ltd., Ajinomoto Co., Inc., Promega Corporation, Jena Bioscience GmbH, CJ CheilJedang Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nucleotides Market Strategic Shifts & Innovations
Manufacturing technology divergence and regulatory fragmentation are splitting the nucleotides market into parallel supply chains serving research, diagnostic, and therapeutic end uses with incompatible qualification standards.
Enzymatic synthesis pathways are bifurcating nucleotide production economics. Thermostable polymerase engineering enables room-temperature triphosphate assembly without protecting-group chemistry. Contract manufacturers serving mRNA vaccine producers are adopting these biocatalytic routes, compressing synthetic nucleotide margins for legacy chemical suppliers while expanding capacity for GMP-grade material.
EMA's Medical Device Regulation traceability mandates are forcing nucleotide suppliers into serialized batch documentation systems. Diagnostic-grade nucleotide shipments to European IVD manufacturers now require end-to-end chain-of-custody records. German and Swiss pharmaceutical chemical firms are investing in blockchain-anchored quality documentation to preempt audit failures.
Long-term offtake agreements are displacing spot purchasing for nucleotide triphosphates. Boston and San Diego biotechnology clusters are locking in multi-year supply contracts directly with fermentation-scale producers, bypassing traditional chemical distributors. This channel consolidation is visible most acutely in adenosine and guanosine triphosphate procurement for gene synthesis workflows.
Nucleotides Market Segmentation
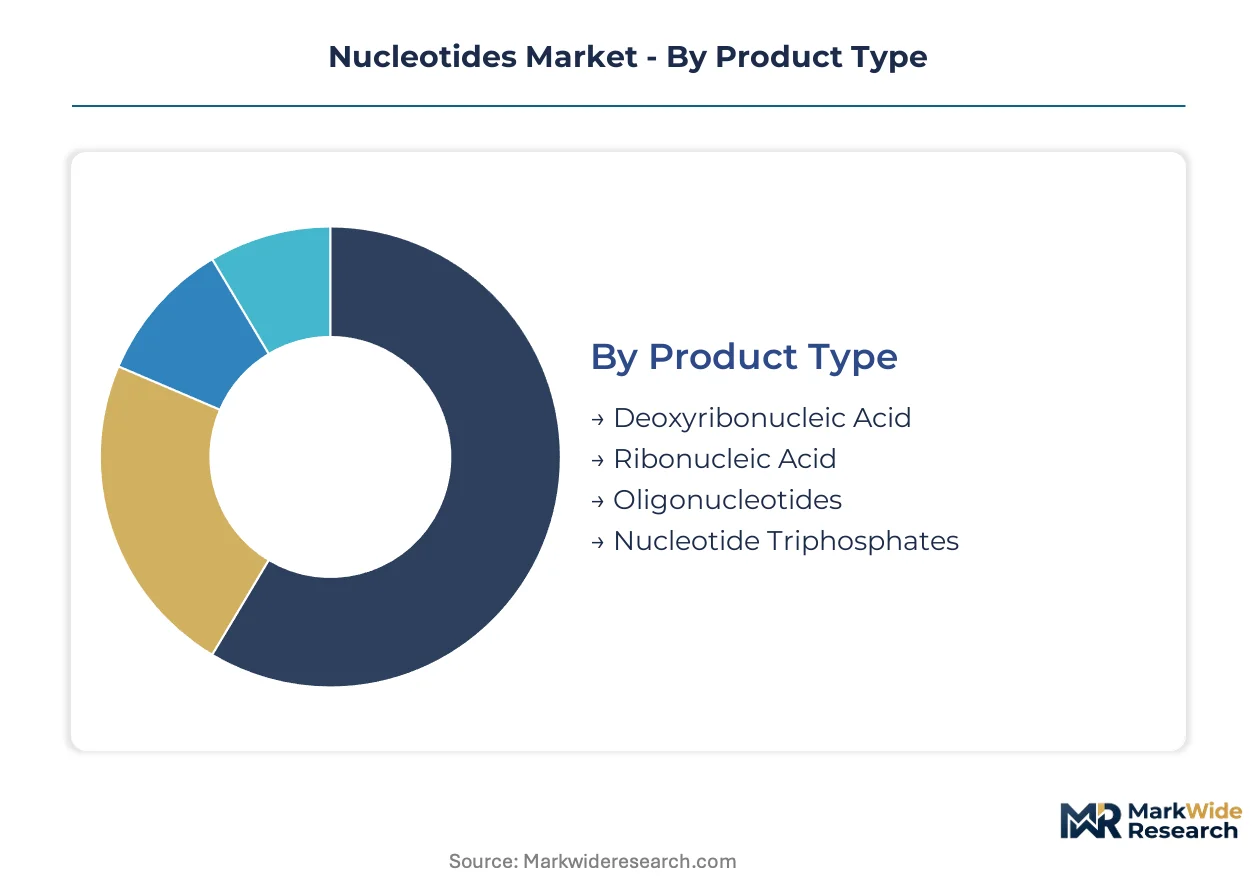
Segmentation in nucleotides separates substitutable from non-substitutable demand pools. Pharmaceutical-grade specifications now diverge so sharply from research-grade that supplier portfolios require distinct manufacturing lines for each tier.
Product Type:
Substitution pressure concentrates in synthetic nucleotide categories where enzymatic production is displacing chemical synthesis.
- Nucleotide Triphosphates:Adenosine, guanosine, cytidine, and uridine triphosphates constitute the polymerase substrate standard for mRNA manufacturing. Boston and San Diego biotechnology clusters are locking in multi-year offtake agreements directly with fermentation-scale producers, bypassing traditional chemical distributors entirely.
- Oligonucleotides:Short synthetic DNA or RNA sequences—antisense therapeutics, siRNA, and CRISPR guide RNAs—command premium purity grades. FDA GMP enforcement and EMA MDR traceability requirements are tightening supplier qualification protocols faster than manufacturing capacity can expand.
- Ribonucleic Acid:Single-stranded RNA polymers for research and diagnostic applications face margin compression as enzymatic synthesis routes mature.
- Deoxyribonucleic Acid:DNA oligos for gene synthesis and cloning workflows compete on turnaround time rather than purity differentiation.
Nucleotide triphosphates anchor the volume base while oligonucleotides gain share at the steepest rate.
Application:
Application segmentation tracks where regulatory burden creates the steepest cost tier separation.
- Pharmaceuticals:GMP-grade nucleotides for mRNA therapeutics, gene editing, and cell therapies carry the heaviest documentation burden. China's NMPA mandates registration of raw material sources for imported biologics, reshaping cross-border procurement patterns for Western suppliers.
- Nutraceuticals:Nucleotide-fortified infant formula and clinical nutrition products concentrate demand in Japan and South Korea. Immune-support positioning drives premix procurement from fermentation-derived sources at lower purity thresholds than pharmaceutical grades.
- Animal Feed:Livestock and aquaculture formulations use nucleotides for gut health and immune modulation.
- Cosmetics:Topical formulations leverage nucleotides for cellular repair claims in premium skincare.
Pharmaceuticals command the highest price tier while nutraceuticals expand volume most aggressively.
End User:
End user segmentation reflects divergent qualification timelines and batch size requirements.
- Pharmaceutical Firms:Commercial-stage mRNA vaccine and therapeutic manufacturers require ISO 13485-certified nucleotides with serialized batch documentation. Dual-source mandates under FDA Current Good Manufacturing Practice enforcement are forcing qualification of secondary suppliers.
- Biotechnology Companies:Clinical-stage gene therapy developers prioritize nucleotide triphosphate supply security over unit cost, locking in direct contracts with producers.
- Academic Institutions:Research-grade nucleotides for basic science face price sensitivity and spot purchasing patterns.
- Research Laboratories:Contract research organizations and government labs operate on flexible procurement with lower purity requirements.
Pharmaceutical firms dominate value capture while biotechnology companies drive the steepest demand expansion.
Form:
Form factor segmentation aligns with downstream processing economics and stability requirements.
- Powder:Lyophilized nucleotides offer maximum stability for long-haul shipping and ambient storage. Bulk powder dominates pharmaceutical manufacturing inputs where reconstitution protocols are standardized.
- Liquid:Ready-to-use aqueous solutions reduce preparation time for high-throughput screening and automated synthesis platforms. Cold chain requirements limit geographic reach.
- Capsule:Pre-measured unit doses serve nutraceutical and clinical nutrition applications with consumer-facing dosing convenience.
- Tablet:Compressed formulations for oral administration in fortified food and supplement markets.
Powder forms anchor industrial procurement while liquid formats climb fastest in diagnostic automation workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade nucleotide procurement concentrates in biotechnology clusters where mRNA therapeutic manufacturing and gene editing pipelines anchor demand. FDA Current Good Manufacturing Practice enforcement and EMA MDR traceability requirements are tightening supplier qualification protocols across major consumption centers.
United States
Boston and San Diego biotechnology clusters drive bulk nucleotide triphosphate consumption for gene synthesis workflows. FDA enforcement of dual-source mandates under Current Good Manufacturing Practice rules is extending supplier qualification timelines. Thermo Fisher Scientific leverages its North American distribution network to sustain availability for mRNA vaccine manufacturers operating in these coastal hubs.
Germany
REACH compliance maturation is filtering out subscale synthetic nucleotide importers and consolidating procurement toward qualified suppliers. EMA Medical Device Regulation traceability mandates force suppliers into serialized batch documentation systems. German pharmaceutical chemical firms are investing in blockchain-anchored quality documentation to preempt audit failures for diagnostic-grade nucleotide shipments.
China
NMPA has tightened nucleotide raw material registration rules for imported biologics, raising compliance barriers for cross-border suppliers. The regulator now mandates registration of raw material sources, reshaping procurement patterns for Western suppliers. Yangtze River Delta pharmaceutical manufacturing zones are expanding fermentation-derived nucleotide production capacity to reduce import dependency.
Japan
PMDA oversight of cell and gene therapy raw materials is driving ISO 13485 certification requirements for nucleotide suppliers serving the domestic market. Ajinomoto Co. anchors Japanese pharmaceutical demand through fermentation-derived production at scale. Kanto region biotechnology facilities are locking in long-term offtake agreements for adenosine and guanosine triphosphates.
Switzerland
Swissmedic pharmacovigilance standards for therapeutic nucleotides exceed baseline EU requirements, creating a premium compliance tier. Basel-area pharmaceutical headquarters are sourcing GMP-grade materials for CRISPR-based editing programs advancing toward commercial manufacturing. Swiss contract manufacturers are adopting enzymatic synthesis pathways to serve European mRNA vaccine producers.
Nucleotides Market Key Industry Players
Player mix skews toward diversified life science conglomerates with captive nucleotide production capabilities and specialized fermentation-scale suppliers serving regional pharmaceutical demand. Market structure shows moderate consolidation at the GMP-grade tier alongside fragmentation in research-grade supply chains. Two strategic archetypes dominate: integrated chemical-pharmaceutical conglomerates leveraging synthetic portfolios, and fermentation specialists competing on input cost stability. Competitive moves center on capacity expansion for pharmaceutical-grade lines and technology licensing for enzymatic synthesis routes.
Among diversified conglomerates, Merck and Thermo Fisher Scientific occupy positions exemplifying the integrated archetype with North American distribution depth. Ajinomoto Co. represents the fermentation-specialist model anchoring East Asian supply security. F. Hoffmann-La Roche Ltd sits within the premium-tier diagnostic-grade segment where Swiss regulatory proximity confers qualification advantages.
| Leading Market Players |
|---|
| Merck |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| DAESANG |
| Meihua Holdings Group Co., Ltd. |
| Ajinomoto Co., Inc. |
| Promega Corporation |
| Jena Bioscience GmbH |
| CJ CheilJedang Corp. |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Boston biotechnology clusters and fermentation-scale producers lock in multi-year supply access while anchoring price visibility against phosphate feedstock volatility. These contracts insulate mRNA vaccine manufacturers from spot market swings in cytidine and uridine triphosphate pricing.
Pricing Analysis
Cost-plus contracts indexed to Moroccan phosphate rock benchmarks dominate GMP-grade nucleotide procurement. Three-tier pricing structure across pharmaceutical-grade, diagnostic-grade, and research-grade levels separates ISO 13485-certified materials from standard offerings. Cost compression in synthetic nucleotide categories is intensifying as enzymatic synthesis routes mature. Academic institutions exhibit the highest price sensitivity, while commercial-stage gene therapy developers prioritize supply security over unit economics.
Supply Chain Analysis
Phosphate rock export licensing through Moroccan customs authorities concentrates upstream input access for nucleotide triphosphate manufacturers. China and Morocco anchor global phosphorus sourcing, while South Korea and Japan host fermentation-derived production capacity. Supply chains draw from petrochemical synthesis for specialty modified bases and microbial fermentation for standard ribonucleotides. Single-source vulnerability in phosphorus concentrate exposes manufacturers to export restriction risk. Distribution runs through direct producer-to-pharma contracts that bypass traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Boston and San Diego biotechnology clusters, forcing suppliers into multi-year offtake negotiations that compress margins for mid-scale entrants.
For Market Incumbents: Compound certification advantages by securing dual-source qualification status under FDA Current Good Manufacturing Practice enforcement. Expand fermentation capacity in the Yangtze River Delta to preempt NMPA localization preferences. Invest in enzymatic synthesis technology licensing to defend against biocatalytic route displacement of chemical synthesis. For New Entrants and Emerging Players: Anchor in ISO 13485-certified diagnostic-grade supply gaps where dedicated capacity lags demand in the United States. Target cell therapy manufacturing nucleotide requirements as the most penetrable segment given qualification timeline mismatches. Pursue direct contracting with mid-tier biotechnology companies bypassed by conglomerate distribution networks. For Investors and Strategic Acquirers: Fermentation-scale specialists with captive phosphate supply agreements represent the highest-conviction acquisition archetype for the therapeutic nucleotide value chain. Monitor NMPA raw material registration approval velocity as the critical inflection signal for Western supplier market access in China. Long-term viability hinges on positioning upstream of enzymatic synthesis transition curves rather than legacy chemical synthesis assets.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Technology Licensing | Biocatalytic routes displace protecting-group chemistry for GMP-grade triphosphate production. |
| Dual-Source Supplier Qualification | FDA enforcement opens secondary supplier slots for documented quality system entrants. |
| Phosphate Supply Backward Integration | Captive phosphorus sourcing insulates margins against Moroccan export restriction risk. |
| ISO 13485 Certification Investment | Diagnostic-grade nucleotide demand outpaces qualified supplier capacity in the United States. |
| East Asian Fermentation Capacity Expansion | NMPA localization preferences reshape procurement patterns for Western biologics manufacturers. |
Research Approach
Cross-validation between regulatory filing analysis and primary stakeholder interviews anchors the qualitative findings in documented compliance trajectories. Conversations with fermentation plant managers, pharmaceutical procurement leads, regulatory affairs directors at nucleotide suppliers, and gene therapy manufacturing heads combined with FDA 483 observation databases, EMA inspection reports, NMPA registration disclosures, and USP pharmacopeial revision notices. Bottom-up capacity modeling triangulates against top-down therapeutic pipeline nucleotide demand estimates.
Sensitivity analysis across phosphate price scenarios, enzymatic synthesis adoption curves, and NMPA approval velocity assumptions stress-tests projection robustness. Segmentation dimensions span product type, application tier, end-user qualification requirements, and geographic regulatory cluster. CAGRs derive from fitted growth curves against historical therapeutic nucleotide consumption patterns and mRNA platform expansion trajectories. Modeled inputs include CRISPR clinical trial advancement rates and cell therapy manufacturing scale-up timelines.
Material uncertainties — NMPA regulatory enforcement intensity, phosphorus export policy shifts, enzymatic synthesis cost crossover timing — sit outside the modeled envelope. Forecasts reflect assumptions about sustained mRNA therapeutic pipeline investment and stable GMP facility capital availability. Practitioners should keep alternative scenarios live as CRISPR commercial manufacturing requirements and pharmacopeial monograph evolution trajectories shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
Global Non-Halogenated Flame Retardants Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
UK Insect Repellent Market
Specialty Chemicals
Silanes and Silicones Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Biodegradable Chelating Agents Market
Specialty Chemicals
Global Spray Polyurethanes Foam Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Epoxidized Soybean Oil Market