
 Asia-Pacific Pigments Market | 2026-2036
Asia-Pacific Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pigments Market Analysis
Waterborne dispersion technology is tilting formulation priorities across coatings and plastics applications throughout Asia-Pacific. BASF SE leverages its integrated pigment and additive portfolio to anchor supply relationships with multinational coatings producers operating in China and India. DIC Corporation sustains dominance in high-performance organic pigments for packaging inks through proprietary azo and phthalocyanine chemistries developed at its Japanese R&D centers. Sudarshan Chemical Industries Limited specializes in effect pigments and competes aggressively on cost from its Maharashtra manufacturing base.
Pigments are finely ground insoluble particles that impart color, opacity, or functional properties to substrates through selective light absorption and scattering; titanium dioxide achieves refractive indices above 2.5, while organic variants rely on conjugated molecular structures for chromatic intensity. Inorganic pigments, led by titanium dioxide and iron oxide families, occupy the largest value share due to their dominance in architectural coatings and plastics compounding across the region. Specialty pigments represent the fastest-expanding category as automotive OEMs in South Korea and Japan specify effect pigments with angular-dependent color travel for premium vehicle finishes. Powder form leads volume throughput in bulk coatings and plastics applications, though liquid dispersions gain ground in waterborne architectural systems where mill-base consistency reduces manufacturing variability.
China's MEE enforces emission caps on titanium dioxide sulfate-process plants, forcing capacity consolidation in Shandong and Sichuan provinces while favoring chloride-route investments. India's BIS certification requirements for construction-grade iron oxide pigments restrict informal supply channels and elevate quality benchmarks for infrastructure projects. REACH-equivalent frameworks under development across ASEAN member states will tighten heavy metal content limits in toys and consumer goods, redirecting formulation choices toward compliant organic alternatives. Stakeholders must monitor regulatory divergence between China's dual carbon enforcement trajectory and India's slower-rolling environmental compliance deadlines to position manufacturing investments and product registrations accordingly.
Market Dynamics
China's MEE emission caps on titanium dioxide sulfate-process plants are forcing capacity consolidation in Shandong and Sichuan provinces while accelerating chloride-route investments, restructuring the entire Asia-Pacific pigment supply base.
Growth Catalysts
- Automotive OEM specification:Premium vehicle manufacturers in South Korea and Japan are mandating effect pigments with angular-dependent color travel for luxury finishes, pulling high-performance organic and pearlescent materials through the supply chain.
- Dual carbon enforcement:China's MEE regulations are accelerating waterborne pigment system adoption across coatings manufacturers serving construction and automotive sectors in eastern China's chemical corridor.
- Infrastructure buildout:India's BIS certification requirements for construction-grade iron oxide pigments are formalizing procurement channels for national highway and urban housing projects, displacing informal supply.
Market Restraints
- Titanium feedstock concentration:Chloride-process titanium dioxide production depends on imported rutile and synthetic feedstocks concentrated among Australian and South African suppliers, exposing margin volatility to mining output fluctuations.
- Sulfate process legacy capacity:Shandong and Sichuan provinces retain substantial sulfate-route titanium dioxide infrastructure now operating under MEE emission caps, creating stranded asset risk and uneven compliance costs.
- Heavy metal substitution pressure:REACH-equivalent frameworks under development across ASEAN member states are tightening lead and cadmium content limits in toys and consumer goods, forcing reformulation away from certain inorganic colorants.
Strategic Opportunities
- Vietnam manufacturing expansion:Coatings producers are diversifying pigment procurement toward Vietnamese chemical parks to reduce concentration risk in eastern China while accessing ASEAN tariff preferences.
- Digital color matching platforms:Cloud-based spectrophotometry and AI-driven formulation tools are enabling remote technical service for dispersed coatings manufacturers, reducing reliance on centralized R&D support.
- PLI scheme alignment:India's production-linked incentive schemes for specialty chemicals offer capital cost offsets for domestic pigment manufacturing investments serving infrastructure and automotive coatings demand.
Industry Challenges
- Color chemist scarcity:Formulation expertise for effect pigments and waterborne dispersion systems concentrates among senior technicians at Japanese and German multinational R&D centers, constraining knowledge transfer to emerging market operations.
- Dual certification burden:Pigment suppliers must simultaneously maintain China's GB standards compliance and India's BIS registrations while awaiting harmonized ASEAN technical regulations, duplicating testing and documentation expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pigments Market |
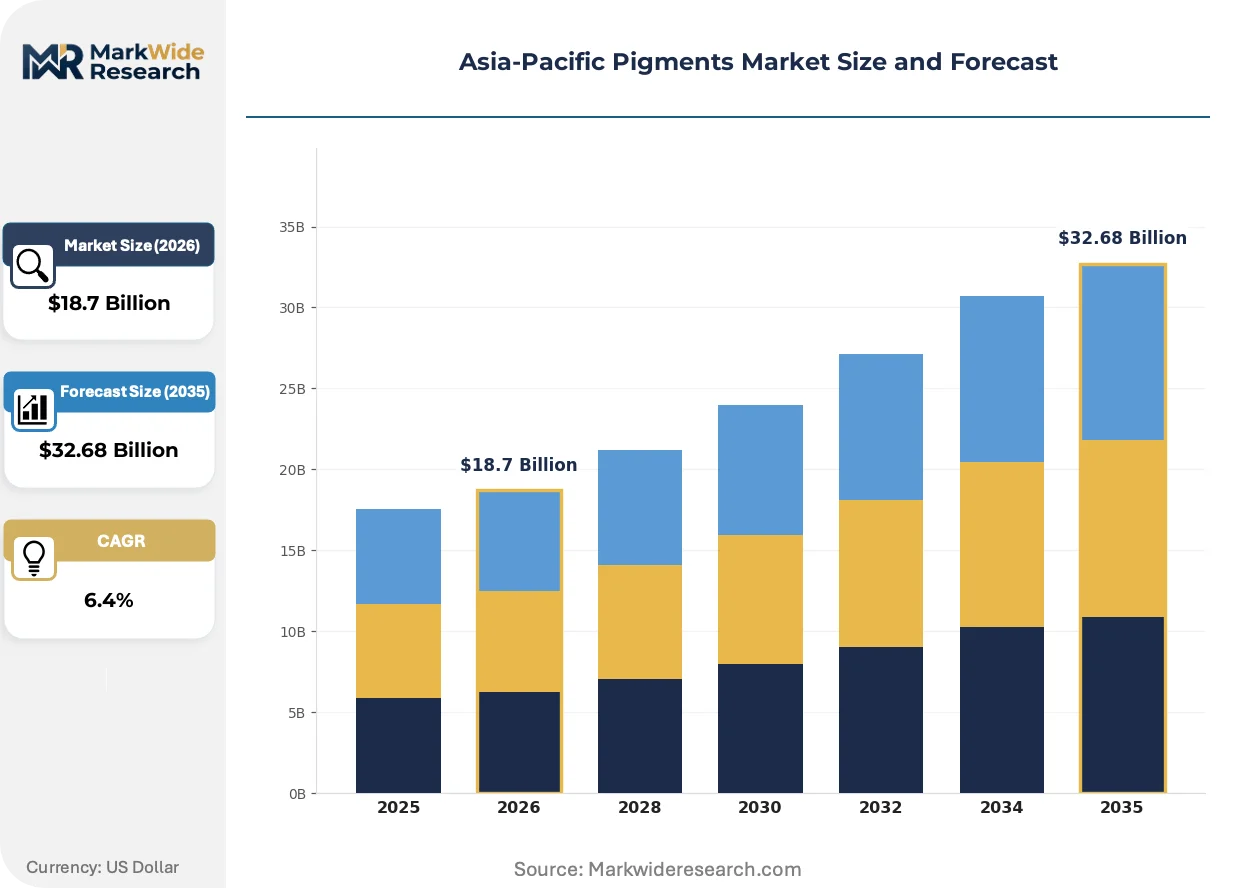
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Pigments, Inorganic Pigments, Specialty Pigments, Permenant Pigments Application: Coatings, Plastics, Inks, Textiles End User: Manufacturing, Art & Crafts, Construction, Automotive Form: Powder, Liquid, Granular, Paste |
| Companies Covered | BASF SE, DIC Corporation, Sudarshan Chemical Industries Limited, The Chemours Company, Venator Materials PLC, Clariant, Lanxess, Tronox Holdings PLC, Cathay Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pigments Market Emerging Trajectories
Formulation science is converging with environmental compliance mandates across Asia-Pacific coatings and plastics value chains, compressing development cycles while expanding performance requirements for colorant systems.
Digital color formulation platforms are virtualizing traditional laboratory matching workflows. Automotive coatings manufacturers in Japan and South Korea are deploying cloud-based spectrophotometry to accelerate OEM approval timelines from weeks to days. This virtualization is compressing technical service headcount requirements while raising precision standards for batch-to-batch consistency.
China's MEE emission caps on sulfate-process titanium dioxide plants are forcing industrial restructuring. Shandong and Sichuan province facilities face closure or costly abatement retrofits while greenfield chloride-route investments concentrate in coastal chemical parks. Pigment suppliers serving architectural coatings are responding by diversifying sourcing relationships and accelerating waterborne dispersion qualification programs.
Coatings manufacturers are consolidating pigment procurement through integrated supply agreements rather than spot purchasing. Bulk consumers in China's Yangtze River Delta are negotiating multi-year contracts with technical service attachments, displacing traditional distributor relationships. This concentration is most visible among multinational automotive coatings producers operating joint ventures with Chinese partners, who now demand captive inventory and just-in-time delivery guarantees.
Asia-Pacific Pigments Market Segmentation
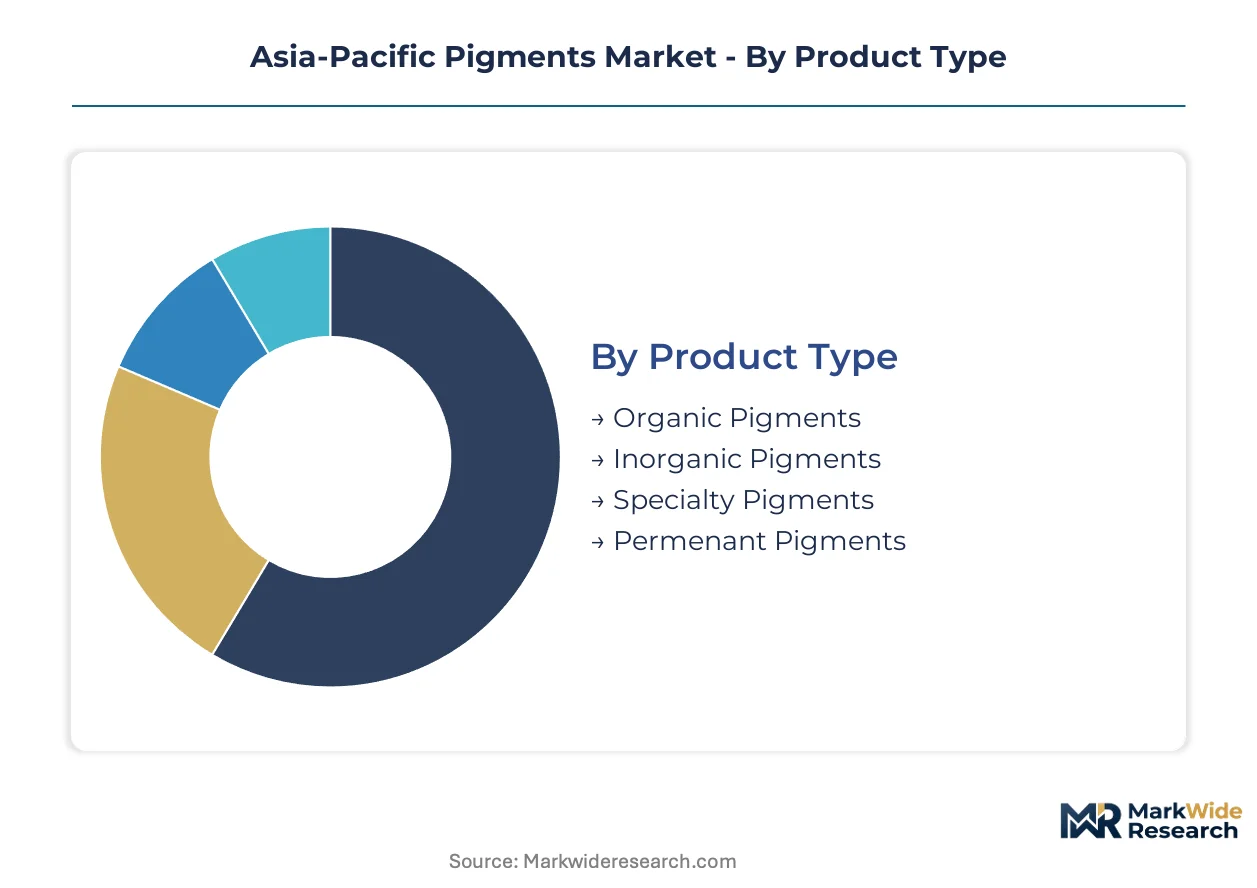
Pigment segmentation across Asia-Pacific reflects divergent technical requirements between mass-market coatings and specialized automotive finishes. Formulation choices cascade through supply chain configurations, with waterborne systems favoring liquid dispersions while powder coatings sustain dry pigment throughput.
Product Type:
Cost tiers separate commodity colorants from performance-engineered alternatives, with raw material chemistry determining margin structures and regulatory exposure.
- Inorganic Pigments:Titanium dioxide and iron oxide families dominate architectural coatings and plastics compounding through superior opacity and weathering resistance. China's MEE emission caps on sulfate-process plants are consolidating capacity in Shandong and Sichuan while favoring chloride-route investments.
- Specialty Pigments:Effect pigments with angular-dependent color travel command premium positioning in automotive OEM specifications from South Korean and Japanese manufacturers. Pearlescent and interference formulations require proprietary substrate coating technologies concentrated among Japanese and German suppliers.
- Organic Pigments:Azo and phthalocyanine chemistries serve packaging inks and consumer goods with high chromatic intensity but lower opacity than inorganic alternatives.
- Permanent Pigments:Lightfast formulations withstand prolonged UV exposure in exterior architectural and automotive applications where color retention is specified.
The dominant share belongs to Inorganic Pigments, while Specialty Pigments are closing the gap fastest.
Application:
Volume concentration tracks construction cycles and automotive production schedules across the region's manufacturing corridors.
- Coatings:Architectural and industrial finishes absorb the largest pigment volumes, with waterborne system adoption accelerating under China's dual carbon enforcement. Eastern China's chemical manufacturing corridor hosts integrated pigment-to-coating supply chains serving domestic and export markets.
- Plastics:Masterbatch compounding for packaging and consumer durables requires heat-stable pigments capable of withstanding polymer processing temperatures. India's BIS certification requirements are formalizing procurement channels for infrastructure-grade applications.
- Inks:Publication and packaging gravure systems demand high-strength organic pigments with controlled particle size distribution.
- Textiles:Disperse and vat dye applications in synthetic fiber processing utilize pigment preparations with specific fastness properties.
Coatings maintains the volume lead, though Plastics is expanding most quickly as packaging demand intensifies across Southeast Asia.
End User:
Customer sophistication ranges from specification-driven automotive OEMs to price-sensitive construction contractors.
- Automotive:OEM coatings specifications in Japan and South Korea mandate effect pigments with precise color travel metrics, pulling high-performance materials through tiered supply chains. Technical service requirements favor suppliers with integrated R&D and manufacturing footprints.
- Construction:India's national highway and urban housing projects are displacing informal iron oxide supply channels through mandatory BIS certification, elevating quality benchmarks and procurement formalization.
- Manufacturing:Industrial coatings and plastics processors balance cost optimization with regulatory compliance across diverse application environments.
- Art & Crafts:Specialty and permanent pigments serve professional and educational markets with emphasis on lightfastness and safety certification.
Construction holds the broadest geographic footprint, while Automotive commands the steepest value-per-kilogram premium.
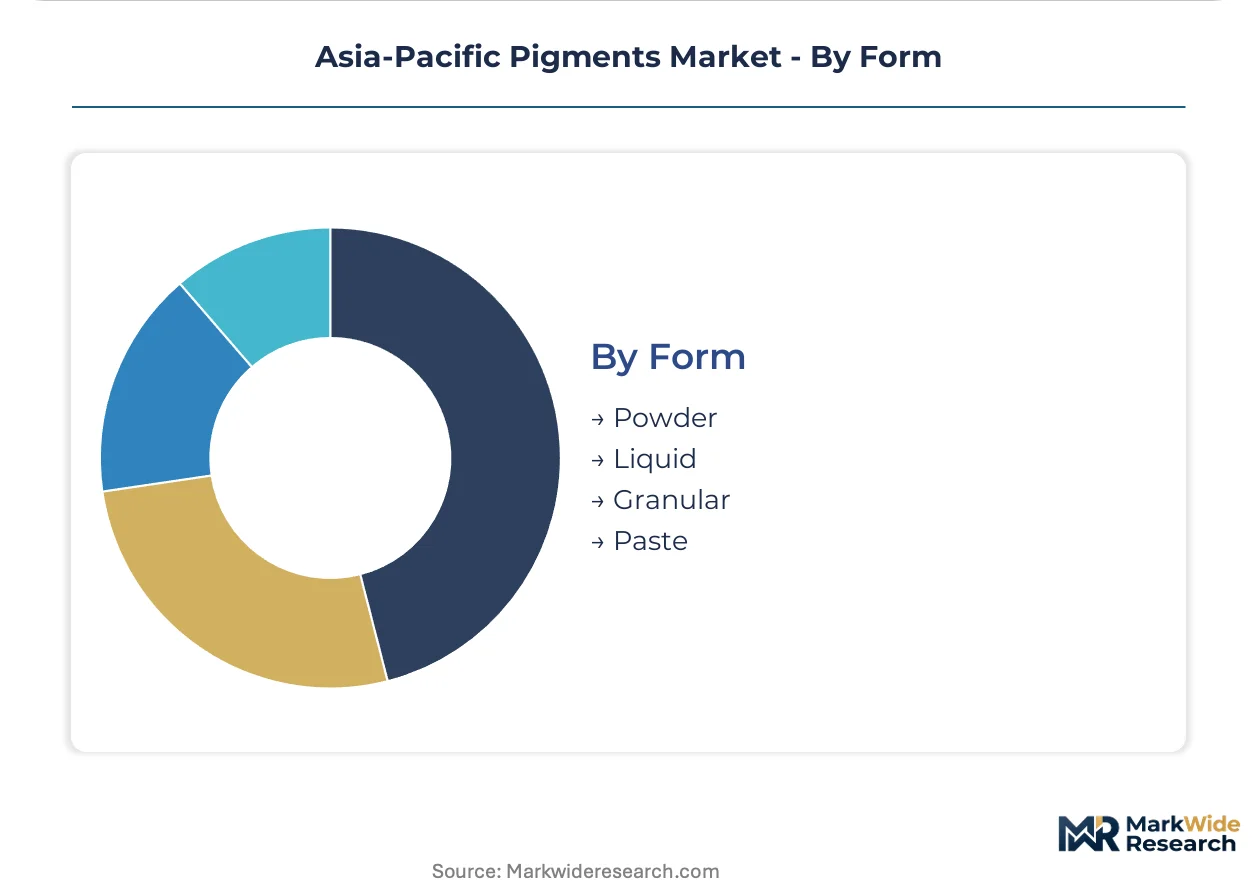
Form:
Supply concentration favors powder throughput in bulk applications, though dispersion technology is tilting formulation priorities.
- Powder:Dry pigment remains the default for high-volume coatings and plastics compounding, with bulk handling infrastructure concentrated in eastern China's chemical parks and India's Maharashtra manufacturing base.
- Liquid:Pre-dispersed aqueous systems reduce manufacturing variability in waterborne architectural coatings, aligning with MEE-driven VOC reduction mandates. Mill-base consistency requirements favor suppliers with integrated dispersion capabilities.
- Granular:Dust-free handling forms serve specific plastics and masterbatch applications where workplace exposure controls are prioritized.
- Paste:High-solids preparations target specialty coatings and inks requiring precise viscosity control.
Powder retains volume dominance, yet Liquid dispersions are gaining share fastest as waterborne system adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coatings manufacturers and plastics compounders across Asia-Pacific exhibit divergent procurement sophistication, with automotive OEMs in Japan and South Korea demanding specification-grade effect pigments while construction contractors in India and Southeast Asia prioritize certified commodity grades.
China
Automotive production in the Yangtze River Delta and construction coatings demand in the Pearl River Delta absorb the largest pigment volumes. MEE emission caps on sulfate-process titanium dioxide plants are consolidating capacity in Shandong and Sichuan provinces. Chloride-route investments are concentrating in Ningbo and Shanghai chemical parks where integrated pigment-to-coating supply chains serve export markets.
India
National highway construction and urban housing projects are formalizing iron oxide procurement through mandatory BIS certification. The PLI scheme for specialty chemicals offers capital cost offsets for domestic pigment manufacturing. Maharashtra's chemical corridor around Mumbai and Pune hosts masterbatch compounders serving packaging demand across western India.
Japan
Automotive OEMs in Toyota City and Yokohama specify effect pigments with precise angular-dependent color travel metrics. METI guidelines on chemical substance management influence formulation choices for consumer goods applications. Osaka-based ink manufacturers sustain demand for high-performance organic pigments in packaging gravure systems.
South Korea
Hyundai Motor Group and Kia Corporation specifications pull pearlescent and interference pigments through tiered supply chains. MFDS regulations on heavy metal content in toys and consumer goods are redirecting formulation choices toward compliant organic alternatives. Ulsan and Pyeongtaek chemical complexes host integrated coatings manufacturing for domestic and export vehicle production.
Vietnam
Multinational coatings producers are diversifying procurement toward Vietnamese chemical parks to reduce concentration risk in eastern China. ASEAN tariff preferences support re-export manufacturing for regional markets. Ho Chi Minh City and Hai Phong industrial zones attract pigment distribution hubs serving Southeast Asian packaging and construction sectors.
Asia-Pacific Pigments Market Vendor Landscape
Channel-controlling players compete with product-specialist players across formulation-driven and commodity segments. The vendor base organizes into three tiers: integrated chemical conglomerates with captive titanium dioxide supply, mid-scale pigment specialists with regional manufacturing footprints, and formulation technology providers with embedded technical service capabilities. Competitive moves center on multi-year procurement contracts with just-in-time delivery guarantees and waterborne dispersion qualification programs aligned with MEE compliance timelines.
Among Germany-based chemical conglomerates, BASF SE and Lanxess occupy positions exemplifying integrated pigment and additive portfolio strategies. Japanese specialists DIC Corporation represent the high-performance organic pigment archetype through proprietary azo and phthalocyanine chemistries. Indian manufacturer Sudarshan Chemical Industries Limited anchors the cost-competitive effect pigment segment from its Maharashtra production base. These three entities illustrate the geographic and technical stratification defining competitive positioning across the region.
| Leading Market Players |
|---|
| BASF SE |
| DIC Corporation |
| Sudarshan Chemical Industries Limited |
| The Chemours Company |
| Venator Materials PLC |
| Clariant |
| Lanxess |
| Tronox Holdings PLC |
| Cathay Industries |
| Others |
Supply Flow & Price Mechanics
Rutile and synthetic feedstock concentration among Australian and South African mining operations anchors margin volatility downstream, with chloride-process titanium dioxide producers absorbing commodity swings while architectural coatings manufacturers negotiate cost-pass-through mechanisms.
Pricing Analysis
Cost-plus contracts with rutile and ilmenite indexation dominate titanium dioxide procurement, with sulfate-route producers in Shandong and Sichuan facing steeper cost compression than chloride-route operators in coastal chemical parks. Price differentiation rests on certification grade and volume scale, with BIS-certified iron oxide pigments commanding premiums over informal supply in India. Pricing pressure stems from MEE compliance retrofits forcing stranded asset write-downs among legacy sulfate producers. Construction contractors exhibit highest price sensitivity, while automotive OEMs in Japan and South Korea prioritize color travel precision over unit economics.
Supply Chain Analysis
Upstream feedstock sourcing draws from Australian rutile mines, South African synthetic rutile facilities, and domestic ilmenite processors in India and Vietnam. Chloride-process plants depend on high-grade feedstocks, while sulfate-route operations consume lower-grade ilmenite with higher waste generation. Single-source vulnerability concentrates in titanium feedstock, with four suppliers controlling global rutile output. Distribution runs through integrated pigment-to-coating supply chains in eastern China's Yangtze River Delta, with bulk consumers negotiating multi-year contracts displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
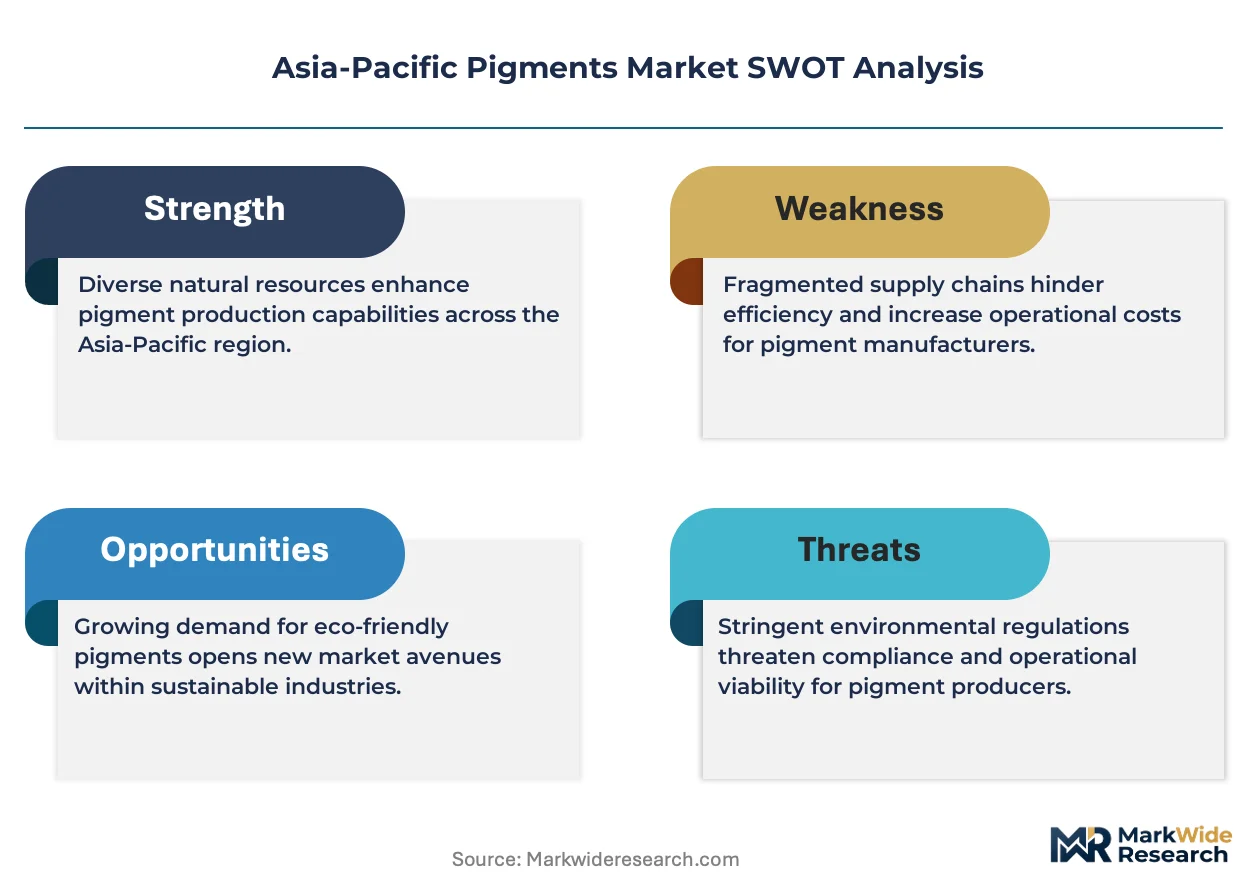
Fragmentation across waterborne dispersion qualification programs and effect pigment technical service capabilities creates niche opportunities, with China's dual carbon enforcement splintering procurement relationships away from consolidated sulfate-route suppliers.
For Market Incumbents: Pre-empt chloride-route capacity consolidation by securing captive rutile offtake agreements with Australian suppliers before feedstock allocation tightens. Accelerate waterborne dispersion qualification programs with coatings manufacturers in eastern China's chemical corridor to lock in technical service relationships ahead of MEE compliance deadlines. Backward integration into synthetic rutile production reduces exposure to mining output fluctuations. For New Entrants and Emerging Players: Vietnamese chemical parks serving ASEAN re-export manufacturing represent the most penetrable entry point, with tariff preferences supporting regional packaging and construction coatings demand. India's PLI scheme for specialty chemicals offers capital cost offsets for domestic effect pigment manufacturing targeting automotive OEM specifications. A technical service partnership model with Japanese R&D centers addresses color chemist scarcity while avoiding fixed manufacturing investment. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale pigment specialists with regional manufacturing footprints and existing waterborne dispersion capabilities, as these assets capture procurement diversification away from eastern China concentration. Long-term viability hinges on regulatory alignment across China's GB standards, India's BIS requirements, and emerging ASEAN REACH-equivalent frameworks. The signal to watch is chloride-route capacity announcements in coastal Chinese chemical parks, which would confirm feedstock security and margin sustainability for integrated operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rutile | Captive feedstock supply insulates margin volatility from Australian mining output fluctuations. |
| Waterborne Dispersion Qualification Programs | MEE compliance timelines favor suppliers with pre-certified low-VOC pigment systems. |
| Vietnam Manufacturing Expansion | ASEAN tariff preferences support re-export positioning for regional coatings demand. |
| Long-term Supply Agreement with Automotive OEMs | Effect pigment specifications from Hyundai and Toyota lock in multi-year offtake commitments. |
| Joint Venture with Japanese R&D Centers | Proprietary azo and phthalocyanine chemistry access addresses color chemist scarcity. |
Methodological Framework
A standing panel of coatings procurement managers, pigment plant engineers, automotive OEM specification engineers, and chemical distribution channel heads provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with downstream formulation technicians and upstream mining operations planners. Secondary validation drew from China customs trade data, India BIS certification registries, ACC and Cefic chemical industry reports, and SEC 10-K filings from listed titanium dioxide producers. Bottom-up volume modeling triangulated against top-down value estimates from regional production cluster analysis.
Scenario bracketing around MEE enforcement intensity and chloride-route investment pace shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include pigment chemistry family, application end-use, form factor, and regional regulatory cluster. CAGRs derived from production capacity utilization trajectories and substitution elasticity estimates between waterborne and solvent-borne systems. Industry-specific forecast inputs incorporated automotive production schedules from IHS Markit vehicle registration data and construction coatings demand from national housing project pipelines.
Macroeconomic conditions sit as an overlay; deviation in Chinese construction investment intensity or Indian infrastructure disbursement timing would shift the trajectory. Forecasts reflect documented assumptions regarding MEE compliance deadlines and PLI scheme continuation. Cross-checking against China TiO2 producer association output statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Cadmium Pigments Market
Dyes and Pigments
Basic Violet 10 Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Inorganic Pigments Market
Dyes and Pigments
Aluminum Pigments Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Pharmaceutical Dyes Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Metal Complex Dyes Market
Dyes and Pigments
Photochromic Pigments Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Zinc Oxide Pigments Market