
 Azo Pigments Market | 2026-2036
Azo Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Azo Pigments Market Intelligence
Specialty chemical distribution is tilting toward direct technical partnerships between pigment manufacturers and downstream compounders. DIC Corporation leverages its integrated ink and pigments portfolio to secure captive demand across Asia. Heubach GmbH anchors European supply through specialized colorant formulations that meet stringent environmental compliance. BASF SE competes on global manufacturing scale, operating production networks that sustain cost discipline across monoazo and disazo product lines.
Azo pigments are synthetic organic colorants characterized by nitrogen-nitrogen double bonds (N=N) linking aromatic systems, typically manufactured through diazotization and coupling reactions with defined particle sizes between 0.1 and 0.5 micrometers for optimal dispersion. These compounds deliver high tinting strength, lightfastness, and thermal stability for industrial coloring applications across plastics, printing inks, and surface coatings. Benzimidazolone pigments command premium positioning due to superior heat and migration resistance in engineered polymers. Naphthol segments occupy mature volume pools in textile dyeing where price sensitivity constrains margin expansion. Diarylide grades dominate plastic coloring applications, though regulatory pressure on aromatic amine content is reshaping formulation roadmaps.
REACH registration requirements and the EU Green Deal framework restrict certain azo dye metabolites in consumer goods, forcing reformulation investments across European supply chains. The EPA and state-level California Proposition 65 regulations impose parallel disclosure obligations for pigments entering US consumer electronics and home furnishings channels. China's MEE enforces wastewater discharge standards that elevate compliance costs for domestic diazotization operations. Stakeholders must monitor regulatory divergence across jurisdictions to determine where certification investments yield durable market access versus stranded asset risk.
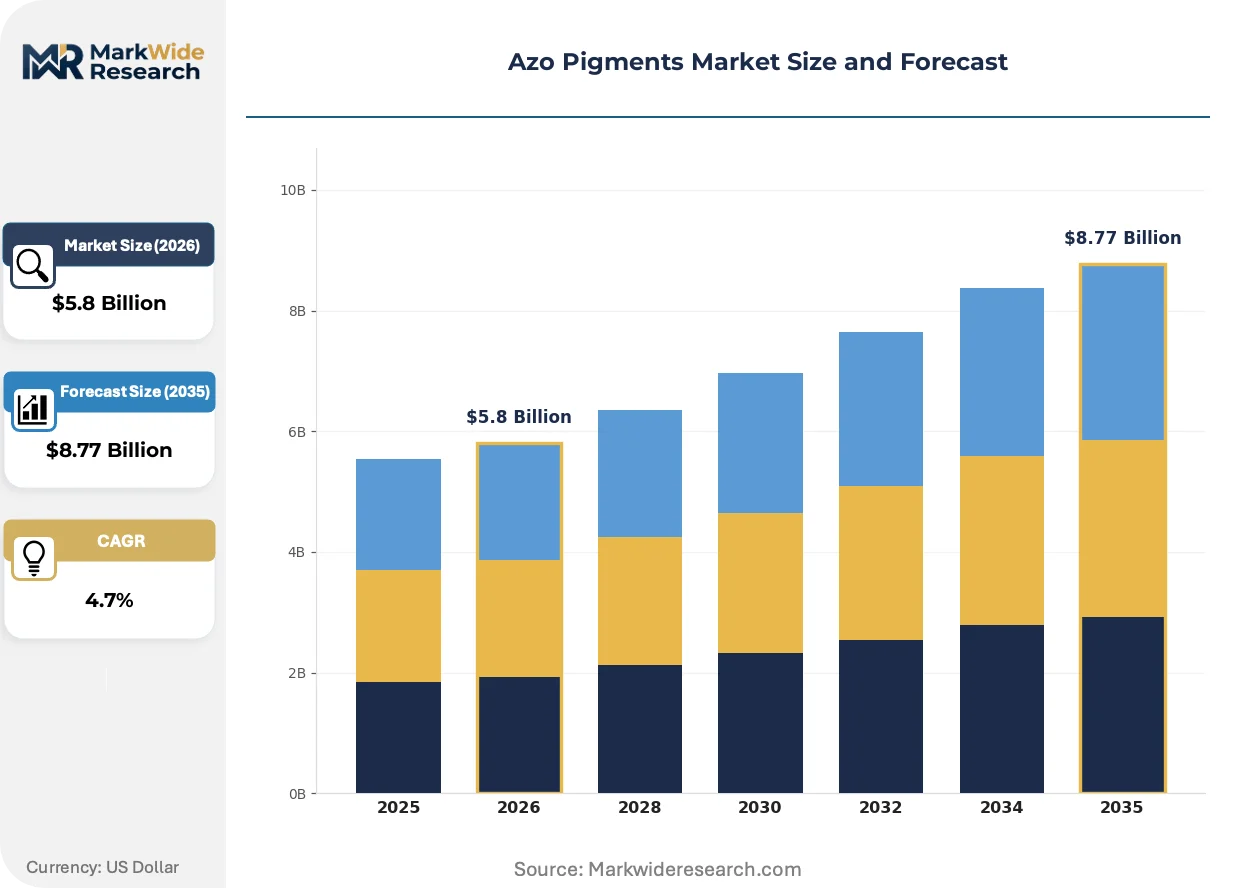
Market Dynamics
REACH registration requirements and the EU Green Deal framework are forcing reformulation investments across European supply chains, while China's MEE wastewater discharge standards elevate compliance costs for domestic diazotization operations. These regulatory pressures are compressing margins for commodity-grade producers and accelerating technical partnerships between pigment manufacturers and downstream compounders.
Growth Catalysts
- Food packaging safety mandates:Benzimidazolone-based pigments gain preference in beverage and food-contact applications due to superior migration resistance under EFSA guidelines.
- REACH compliance deadlines:European formulators face phased restrictions on aromatic amine metabolites, driving substitution demand for compliant diarylide alternatives.
- Engineered polymer expansion:China's domestic automotive and electronics sectors require heat-stable colorants for polyamide and ABS processing.
Market Restraints
- Aniline feedstock volatility:Crude oil-linked benzene derivatives expose diazotization operations to input cost swings that squeeze working capital.
- Specialty supplier concentration:European benzimidazolone production clusters in Germany and Switzerland, creating single-source vulnerability for heat-resistant grades.
- Heavy metal disclosure thresholds:California Proposition 65 and EPA reporting obligations add compliance overhead for pigments entering US consumer channels.
Strategic Opportunities
- Bio-based coupling chemistry:Enzymatic diazotization pathways under development could bypass traditional nitrous acid routes and reduce MEE-regulated effluent.
- India PLI scheme alignment:Domestic plastics processing incentives create localized demand for naphthol pigments in textile and packaging clusters.
- Digital inkjet convergence:Narrow particle distribution technologies enable azo pigment penetration into high-speed commercial printing.
Industry Challenges
- Colorimetric formulation expertise gap:Compounders lack technicians trained in dispersibility optimization for sub-micron particle systems.
- Multi-jurisdiction certification timelines:Parallel REACH, EPA, and GB standard registrations extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Azo Pigments Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoazo, Disazo, Naphthol, Diarylide, Benzimidazolone Application: Inks, Plastic Coloring, Coatings, Textiles, Paper Dyeing End Use Industry: Packaging, Automotive Components, Consumer Electronics, Construction Materials, Home Furnishings Packaging Type: Powder, Paste, Flakes, Granules, Liquid Dispersion |
| Companies Covered | DIC Corporation, Heubach GmbH, Clariant, Lanxess AG, Ferro Corporation, Sudarshan Chemical Industries Limited, Trust Chem Co Ltd, Pidilite Industries Ltd, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Azo Pigments Market Strategic Shifts & Innovations
Particle engineering and regulatory chemistry are converging to reshape competitive positioning in azo pigments. Manufacturers are investing in controlled crystallization and surface treatment technologies that address both performance specifications and environmental compliance thresholds.
Encapsulated pigment technologies are collapsing the traditional trade-off between dispersion stability and migration resistance. Automotive interior suppliers in Germany and Japan are adopting silicone-resin encapsulated diarylide grades for polyolefin coloring. This encapsulation approach is collapsing reformulation cycles by enabling single-pigment solutions where blends were previously required.
ECHA's restriction roadmap on polycyclic aromatic hydrocarbon contaminants is tightening purity specifications for naphthol-based colorants. Italian and Spanish textile dye houses face elevated testing costs for export-bound shipments. The leather and apparel sectors are responding by consolidating supplier bases toward REACH-registered manufacturers with certified impurity controls.
Brand-owner sustainability scorecards are reconfiguring procurement criteria for packaging colorants. Major beverage retailers in France and the Netherlands now mandate third-party verified absence of restricted aromatic amines. This specification shift is most visible in Northern European markets where private-label packaging contracts increasingly exclude non-certified pigment sources.
Azo Pigments Market Segmentation
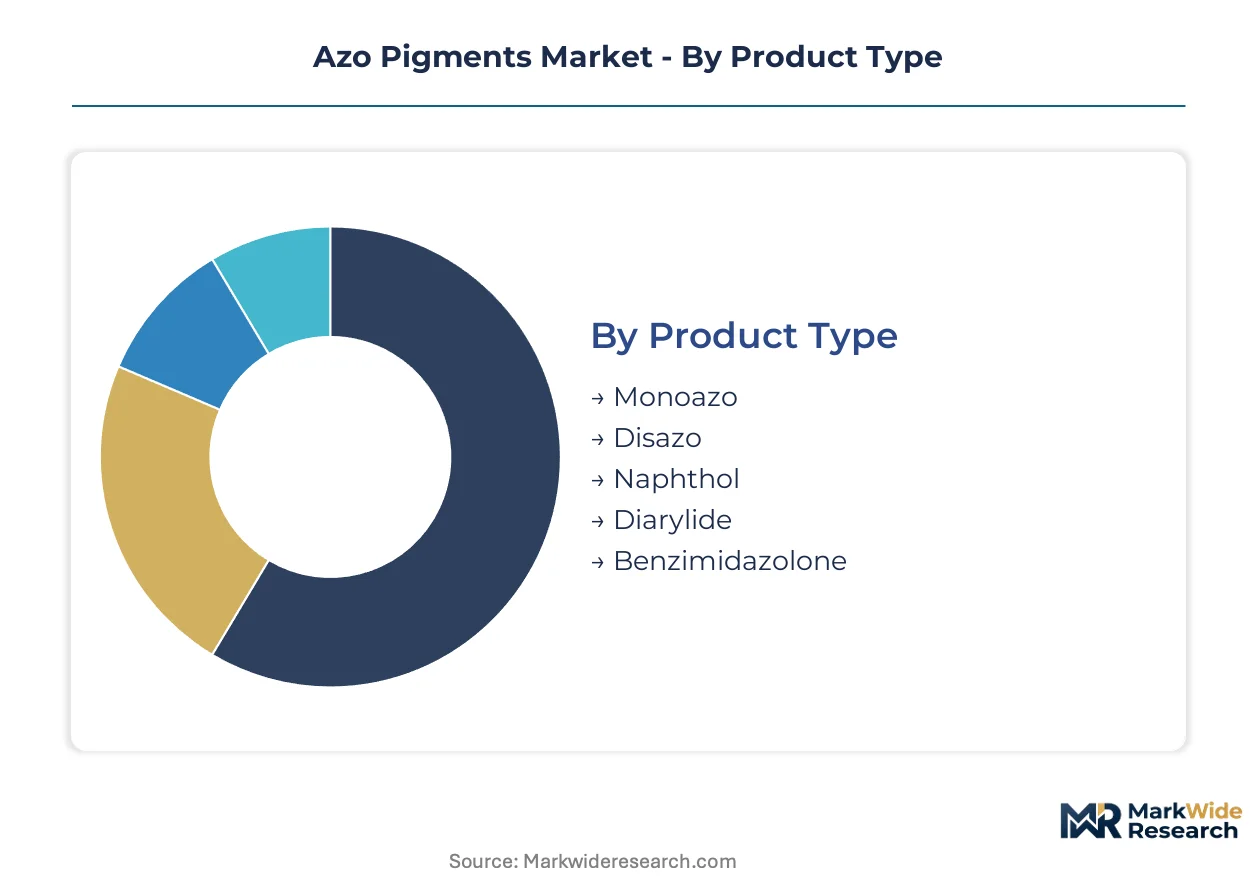
Azo pigment purchasing decisions hinge on dispersion requirements and regulatory compliance intensity across downstream applications. Technical service demands vary sharply between commodity diarylide volumes and specialty benzimidazolone formulations requiring colorimetric support.
Product Type:
After-sales technical intensity separates pigment categories, with heat-resistant grades demanding formulation troubleshooting and regulatory documentation support.
- Benzimidazolone:These pigments incorporate cyclic amide structures that deliver thermal stability above 280°C for polyamide and ABS processing. Automotive interior suppliers in Germany and Japan specify these grades for dashboard and trim applications where migration resistance under ECHA guidelines is mandatory. Color matching services and REACH certification support drive supplier stickiness in this tier.
- Diarylide:Diarylide pigments utilize acetoacetarylide coupling components to achieve bright yellow and orange hues with moderate heat resistance. Plastic compounders in China source these volumes for polyolefin masterbatch production where price sensitivity limits service overhead. EPA and California Proposition 65 disclosure obligations are reshaping formulation roadmaps for US-bound shipments.
- Monoazo:Single azo bond structures dominate textile dyeing applications with straightforward dispersion requirements.
- Disazo:Double azo configurations extend conjugation for deeper shades in packaging inks.
- Naphthol:Hydroxynaphthoic acid-based pigments serve mature textile markets with established supply chains.
By volume, Diarylide leads. By growth pace, Benzimidazolone is ahead.
Application:
Cost tier differentiation separates commodity coating volumes from premium inkjet formulations requiring narrow particle distribution control.
- Inks:Offset, gravure, and flexographic printing demand pigments with defined particle sizes between 0.1 and 0.5 micrometers for optimal transfer. Commercial printers in France and the Netherlands now mandate third-party verified absence of restricted aromatic amines under brand-owner sustainability scorecards. Digital inkjet convergence is accelerating technical partnerships between pigment manufacturers and ink formulators.
- Plastic Coloring:Masterbatch compounders require heat-stable colorants compatible with twin-screw extrusion at elevated temperatures. China's domestic automotive and electronics sectors drive procurement of benzimidazolone and diarylide grades for polyamide and ABS processing. MEE wastewater discharge standards elevate compliance costs for domestic diazotization operations serving this channel.
- Coatings:Architectural and industrial paint applications prioritize weatherfastness over thermal stability.
- Textiles:Fiber dyeing operations concentrate in India and Bangladesh with price-sensitive procurement patterns.
- Paper Dyeing:Specialty paper grades utilize azo pigments for security and decorative applications.
Plastic Coloring commands the largest volume share. Inks demonstrate the steepest expansion trajectory.
End Use Industry:
Customer type determines specification stringency, with automotive and electronics sectors imposing the most demanding certification requirements.
- Packaging:Food and beverage contact applications drive preference for benzimidazolone-based pigments under EFSA migration resistance guidelines. Northern European private-label contracts increasingly exclude non-certified pigment sources. Beverage retailers in France and the Netherlands now require verified absence of restricted aromatic amine metabolites.
- Automotive Components:Interior and under-hood applications demand heat stability and low volatile organic compound emissions. German and Japanese OEMs specify silicone-resin encapsulated diarylide grades for polyolefin coloring where single-pigment solutions replace previous blends. REACH registration requirements force reformulation investments across European supply chains.
- Consumer Electronics:Housing and accessory coloring requires compliance with RoHS and REACH substance restrictions.
- Construction Materials:PVC profiles and siding applications prioritize cost-efficient coloration with moderate durability.
- Home Furnishings:Upholstery and decorative surfaces face California Proposition 65 disclosure obligations for US market access.
Packaging dominates current procurement volumes. Automotive Components is gaining share fastest.
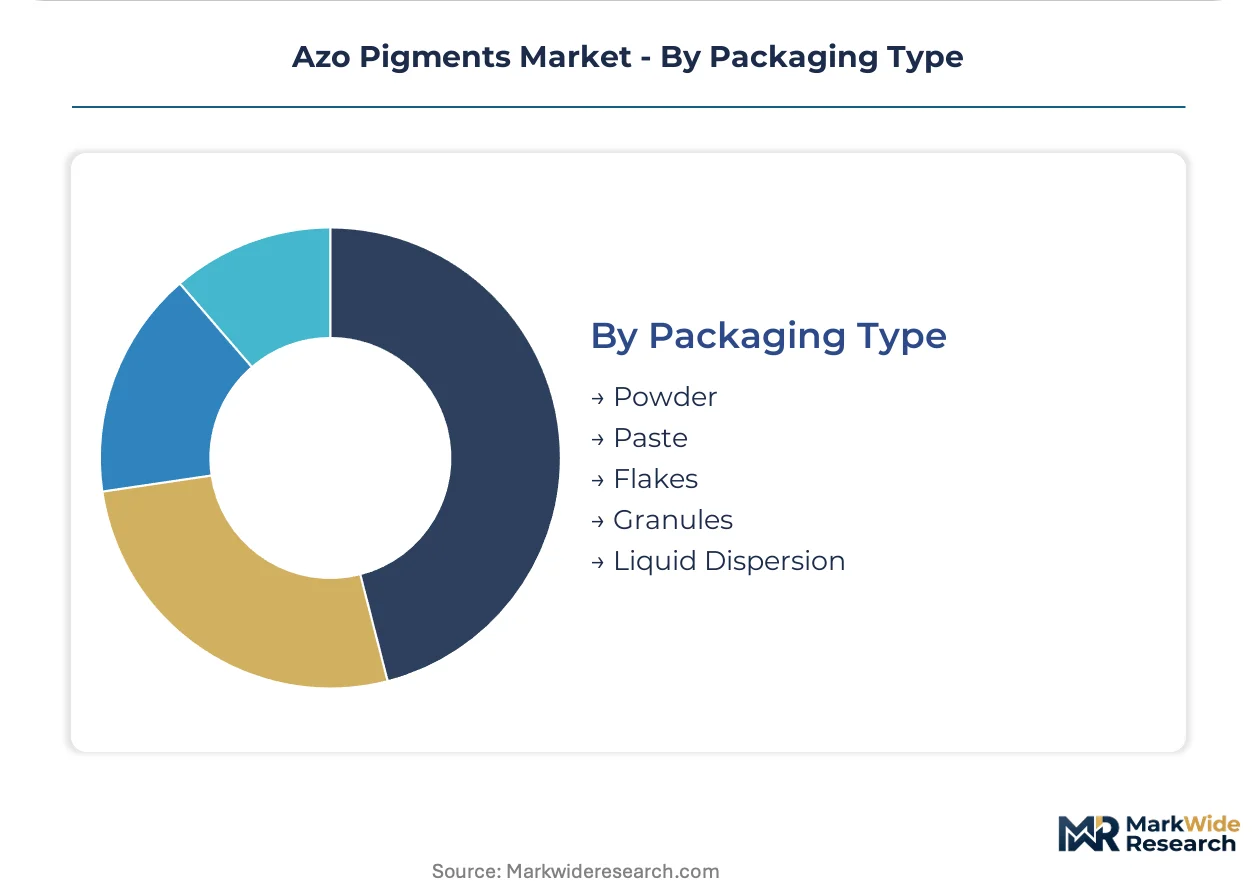
Packaging Type:
Supply concentration in powder processing creates margin differentiation against liquid dispersion formats requiring specialized equipment investments.
- Powder:Dry pigment powders remain the standard format for masterbatch compounders and ink manufacturers with in-house dispersion capabilities. Chinese ink manufacturers and plastics processors drive volume procurement of diarylide and naphthol grades in this format. Dust exposure controls and occupational safety compliance add handling costs.
- Liquid Dispersion:Pre-dispersed pigment concentrates eliminate milling steps for coating and ink formulators lacking particle size control equipment. European specialty distributors favor this format for just-in-time delivery to mid-sized compounders. Premium positioning reflects technical service intensity in color matching and stability optimization.
- Paste:Semi-solid concentrates serve niche textile and leather dyeing applications.
- Flakes:Low-dust handling format for specific coating and plastics applications.
- Granules:Dust-free processing option for automated handling systems in high-volume operations.
Powder leads by shipment volume. Liquid Dispersion expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE wastewater discharge standards and India's PLI scheme for plastics processing are redirecting investment flows across Asian manufacturing clusters. European REACH compliance deadlines and US EPA reporting obligations create divergent certification burdens that reshape procurement geography.
China
Domestic ink manufacturers and plastics processors in the Yangtze River Delta drive volume procurement of diarylide and naphthol grades. The MEE enforces stringent wastewater discharge standards that elevate compliance costs for diazotization operations. Shanghai and Zhejiang province host concentrated pigment production serving automotive and electronics sectors.
Germany
Automotive interior suppliers specify benzimidazolone pigments for dashboard and trim applications requiring ECHA-compliant migration resistance. REACH registration requirements force reformulation investments across Bavarian and North Rhine-Westphalian supply chains. The Stuttgart and Munich industrial corridors anchor European heat-resistant grade production.
United States
California Proposition 65 disclosure obligations and EPA reporting requirements add compliance overhead for pigments entering consumer electronics and home furnishings channels. The Southeast plastics processing belt and Texas chemical corridor concentrate masterbatch compounder demand. Midwest ink formulation hubs serve commercial printing markets.
India
The PLI scheme for domestic plastics processing creates localized demand for naphthol pigments in Gujarat and Maharashtra textile and packaging clusters. BIS standards alignment pressures reformulation investments for export-bound shipments. The Mumbai-Pune industrial corridor and Ahmedabad chemical belt concentrate procurement activity.
Japan
METI guidelines on chemical substance management intersect with automotive OEM specifications for low-VOC interior colorants. The Nagoya and Osaka manufacturing basins demand silicone-resin encapsulated grades for polyolefin applications. Kanto region inkjet formulators drive technical partnerships for narrow particle distribution technologies.
Azo Pigments Market Key Industry Players
On the supply side, the industry is structured around three distinct capability tiers. Integrated chemical conglomerates with captive ink and coatings portfolios compete against specialized colorant formulators and regional volume producers. Strategic archetypes include: full-spectrum pigment-to-ink integrators, regulatory compliance specialists, and cost-optimized Asian commodity suppliers. Dominant competitive moves center on backward integration into aniline feedstocks and technical service partnerships with downstream compounders.
Among the integrated chemical majors, DIC Corporation, BASF SE, and Heubach GmbH occupy anchor positions that exemplify contrasting geographic and strategic orientations. DIC Corporation represents the Asia-Pacific integrated model combining pigment production with captive ink demand. BASF SE exemplifies global manufacturing scale across multiple product chemistries. Heubach GmbH occupies the European specialty niche focused on compliance-intensive formulations.
| Leading Market Players |
|---|
| DIC Corporation |
| Heubach GmbH |
| Clariant |
| Lanxess AG |
| Ferro Corporation |
| Sudarshan Chemical Industries Limited |
| Trust Chem Co Ltd |
| Pidilite Industries Ltd |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Aniline feedstock concentration in China's Shandong and Jiangsu provinces anchors cost structures for diarylide and naphthol pigment grades, compressing margin pools for European benzimidazolone specialists facing REACH compliance investments. Price formation splits between volume-driven spot markets for textile-grade monoazo pigments and contract-negotiated premiums for automotive-certified heat-resistant formulations.
Pricing Analysis
Volume-discount tiering separates benzimidazolone premiums from diarylide commodity floors. Three-tier pricing structure across REACH-certified specialty, standard industrial, and economy textile grades reflects certification burden and thermal performance differentiation. Cost compression in Chinese naphthol volumes is intensifying because MEE wastewater compliance elevates domestic diazotization costs. Masterbatch compounders in Asia demonstrate highest price sensitivity, while German automotive interior suppliers accept premium positioning for ECHA-compliant migration resistance.
Supply Chain Analysis
Upstream aniline and nitrobenzene feedstock availability centers on China, Germany, and the United States, with benzene derivative costs tethered to crude oil volatility. Pigment manufacturing draws from acetoacetarylide coupling components, hydroxynaphthoic acid precursors, and cyclic amide intermediates. Single-source vulnerability concentrates in Swiss and German benzimidazolone production clusters serving heat-resistant grades. Distribution runs through specialty chemical distributors in Europe, direct mill relationships in China, and masterbatch compounder networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory chemistry disruption from ECHA's polycyclic aromatic hydrocarbon restriction roadmap and China's MEE wastewater standards is accelerating technical partnerships and reformulation investments across pigment supply chains.
For Market Incumbents: Insulate benzimidazolone margin pools through captive aniline supply agreements and REACH-registered impurity control investments. DIC Corporation's integrated ink-pigment model demonstrates defensive value against specialty distributor consolidation. BASF SE's global manufacturing scale provides buffer against regional feedstock volatility. For New Entrants and Emerging Players: India's PLI-aligned plastics processing clusters offer the most penetrable geographic white space for naphthol pigment localization. Gujarat and Maharashtra textile packaging demand lacks sufficient domestic REACH-certified supply. Target technical service partnerships with mid-sized masterbatch compounders seeking just-in-time liquid dispersion formats. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European colorant specialists holding stranded REACH registration portfolios without downstream ink integration. Five-to-ten-year viability hinges on successful bio-based coupling chemistry commercialization. The signal to watch is enzymatic diazotization pathway patent filings from incumbent R&D labs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Feedstocks | Captive benzene derivative supply insulates margin against crude-linked volatility for Chinese diarylide producers. |
| REACH-Registered Impurity Control Investment | ECHA compliance certification unlocks Northern European beverage packaging procurement under sustainability scorecards. |
| Enzymatic Diazotization Pathway Development | Bio-based coupling chemistry reduces MEE-regulated effluent and bypasses traditional nitrous acid routes. |
| Silicone-Resin Encapsulation Scale-Up | Automotive interior suppliers in Germany and Japan adopt single-pigment solutions for polyolefin coloring applications. |
| India PLI Scheme Alignment Partnership | Domestic plastics processing incentives create localized demand for naphthol pigments in Gujarat textile clusters. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, Cefic chemical industry reports, SEC 10-K filings, and ECHA substance restriction roadmaps. Technical discussions with plant managers at diazotization facilities, procurement leads at automotive masterbatch compounders, distribution channel partners, and regulatory affairs directors informed supply chain and compliance assessments. Bottom-up volume modeling from pigment grade shipments triangulates against top-down value estimates from end-use industry consumption patterns.
Forecast inputs span benzimidazolone and diarylide product chemistries, plastic coloring and ink application channels, packaging and automotive end-use industries, and powder versus liquid dispersion packaging formats across the projection horizon. CAGRs derive from regression analysis against automotive production indices, packaging volume trends, and regulatory implementation timelines. Aniline feedstock cost trajectories and REACH registration deadline phasing serve as industry-specific sensitivity variables.
Macroeconomic conditions sit as an overlay; deviation in crude oil price bands, automotive sector output, or European regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on substitution elasticity between pigment chemistries and geographic demand migration. Material shifts in bio-based coupling technology viability or India PLI scheme expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
South America Hair Colorants Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
Thermochromic Labels Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Mulch Colorants Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Europe Pigments Market
Dyes and Pigments
Brilliant Blue FCF Colors Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Inorganic Pigments Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Resin Pigments Market