
 Photoluminescent Paints Market | 2026-2036
Photoluminescent Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Photoluminescent Paints Market Outlook
Buyer concentration in commercial construction is shifting as general contractors consolidate safety procurement across multi-site portfolios. Rust-Oleum Corporation leverages its distribution network to dominate specification channels for large infrastructure projects. Sherwin-Williams sustains R&D intensity in low-VOC photoluminescent formulations. PPG Industries anchors its position through captive supply of strontium aluminate pigments.
Photoluminescent paints are coatings containing phosphorescent pigments, typically strontium aluminate doped with europium and dysprosium, that absorb ambient light and emit visible glow for hours without electrical power, serving critical safety marking and decorative functions. Water-based formulations lead volume due to tightening solvent regulations, while powder coatings represent the fastest-growing category as automotive and appliance OEMs seek zero-VOC process compatibility. Spray formats occupy a premium niche in aftermarket automotive and custom artwork applications where field-applied precision matters.
The EPA regulates VOC content under architectural coating standards, while REACH and the EU Green Deal impose substance restrictions and carbon footprint disclosure requirements on European imports. ASTM E2072 and ISO 17398 govern photometric performance for safety applications, creating certification barriers that favor established testing relationships. Stakeholders must monitor divergence between regional chemical registries as dual-registration costs reshape competitive access.
Market Dynamics
Strontium aluminate pigment supply concentration is compressing formulation economics as three producers control europium and dysprosium doping capacity, forcing coaters to negotiate long-term offtake or absorb volatile rare-earth pricing.
Growth Catalysts
- EU Green Deal retrofit mandates:Germany's public building safety signage overhaul is accelerating specification rates for water-based egress markings in municipal facilities.
- Passive safety system integration:Commercial construction builders are embedding photoluminescent pathways into multi-site portfolios to reduce electrical backup infrastructure.
- Powder coating process compatibility:Automotive OEMs are adopting zero-VOC application methods to meet EPA architectural coating standards without solvent handling costs.
Market Restraints
- Rare-earth input volatility:Europium and dysprosium prices fluctuate with Chinese export quotas, squeezing margin stability for strontium aluminate formulators.
- REACH dual-registration costs:European substance notification requirements create competitive access barriers for non-EU manufacturers seeking import positioning.
- LED emergency lighting substitution:Battery-backed LED systems compete for safety marking budgets in cost-sensitive commercial retrofits.
Strategic Opportunities
- India building code evolution:BIS fire safety standards are expanding to include photoluminescent egress requirements in high-occupancy structures.
- Smart coating convergence:Integration with IoT-enabled building management systems creates premium positioning for responsive luminescence products.
- Direct contractor procurement:General contractor consolidation across multi-site portfolios enables bypass of traditional distribution markups.
Industry Challenges
- ASTM E2072 certification timelines:Photometric performance testing delays product launches by six to twelve months for new entrants.
- Water-based formulation skill scarcity:Solvent-to-aqueous transition requires retraining application technicians in viscosity control and substrate adhesion.
- Legacy inventory integration:Existing zinc sulfide installations complicate upgrade specifications due to incompatible glow-duration performance profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoluminescent Paints Market |
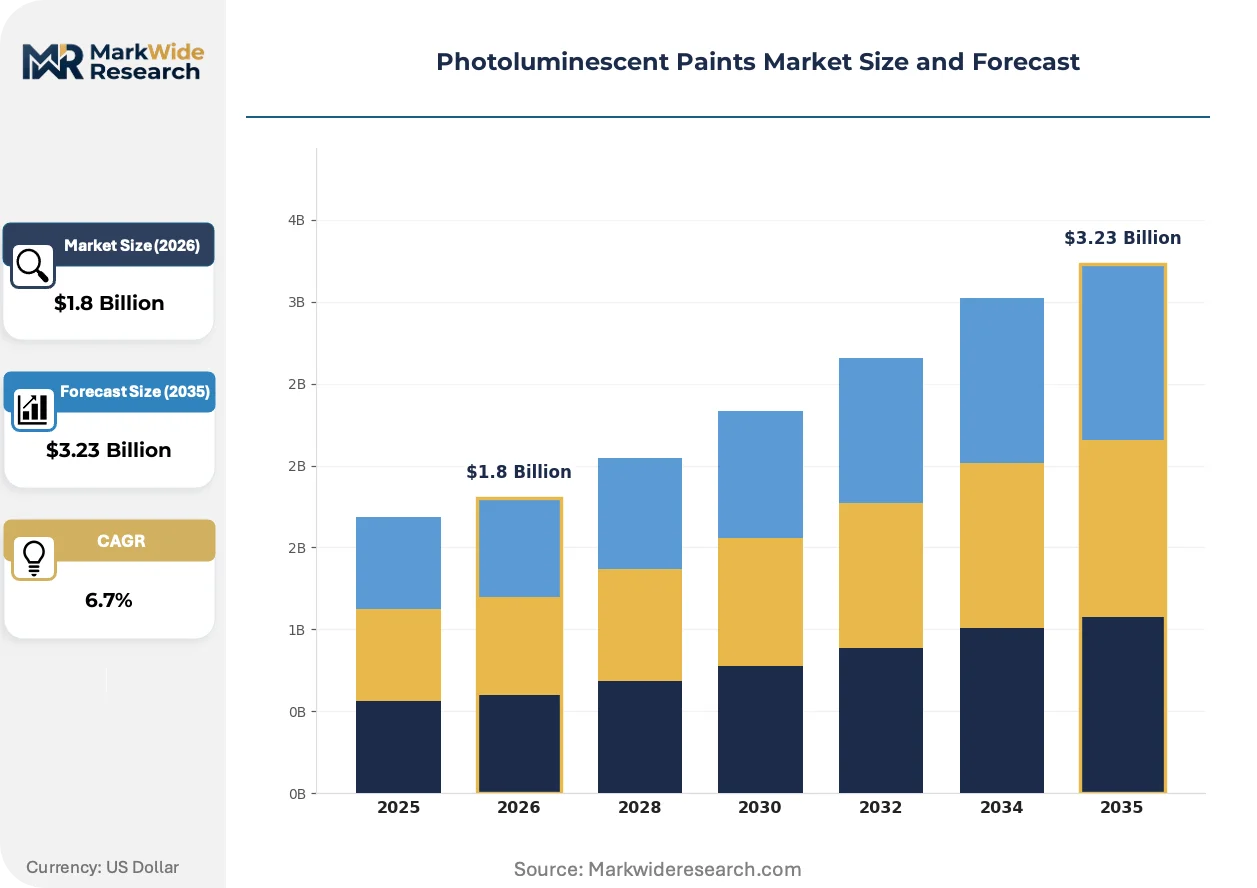
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based, Solvent-based, Powder, Spray End Use: Construction, Automotive, Aerospace, Home Decor Application: Road Markings, Safety Signs, Interior Walls, Artworks Certification: ASTM, ISO, EN, CE |
| Companies Covered | Rust-Oleum Corporation, Benjamin Moore & Co, Sherwin-Williams, PPG Industries, LumiNova (Nemoto & Co., Ltd.), Indra Glowtech Private Limited, Allureglow USA, Glow Inc., Protech Powder Coating, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoluminescent Paints Market Strategic Shifts
Formulation chemistry is pivoting toward aqueous systems while application equipment digitizes, reshaping how specifications are won and margins are defended across safety and decorative segments.
Strontium aluminate doped with europium and dysprosium is consolidating market positioning as the dominant phosphorescent pigment technology. Commercial construction specifiers are rejecting zinc sulfide alternatives due to inferior afterglow duration. This pigment transition is compressing the addressable market for legacy chemistries while concentrating supplier power among rare-earth processors.
REACH substance restrictions and EU Green Deal carbon footprint disclosure requirements are tightening VOC thresholds for European imports. Coatings manufacturers are reformulating solvent-based products to water-based alternatives to maintain market access. German retrofit mandates for public building safety signage are accelerating this regulatory response among regional formulators.
Buyer concentration among consolidated general contractors is compressing procurement cycles and demanding portfolio-level pricing agreements. Traditional distribution channels face disintermediation as contractors centralize safety procurement across multi-site developments. This behavioral shift is most visible in German commercial construction, where specification authority has shifted from local painters to national procurement teams.
Photoluminescent Paints Market Segmentation
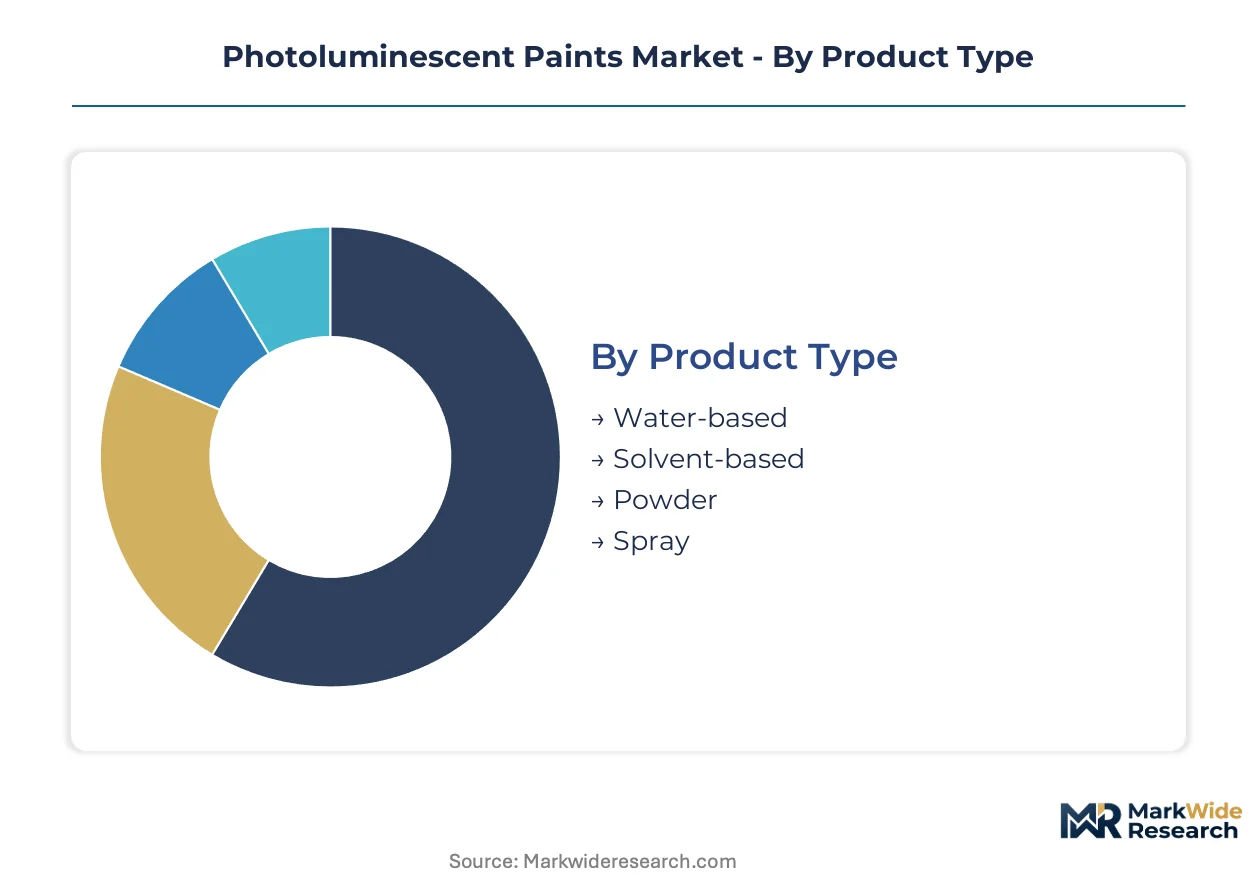
Segmentation in photoluminescent paints reveals how formulation chemistry, application method, and regulatory compliance intersect to determine procurement decisions. Buyers navigate trade-offs between VOC compliance, substrate compatibility, and certification requirements that vary sharply across end-use environments.
Product Type:
Formulation selection hinges on regulatory jurisdiction and application infrastructure, with water-based systems commanding specification priority in jurisdictions with stringent VOC thresholds.
- Water-based:Aqueous dispersions of strontium aluminate pigments suspended in polymer emulsions, formulated for brush, roller, or spray application. Commercial construction specifiers in Germany and France are mandating these systems for public building egress markings under EU Green Deal retrofit programs. REACH substance restrictions and carbon footprint disclosure requirements are accelerating solvent-to-water transitions among European formulators.
- Powder:Thermosetting resin systems incorporating phosphorescent pigments for electrostatic application and oven cure. Automotive OEMs in Stuttgart and Wolfsburg are adopting zero-VOC powder processes to eliminate solvent handling costs while meeting EPA architectural coating standards for imported components. This format eliminates wet waste and enables reclaim of overspray.
- Solvent-based:Alkyd and acrylic solutions carrying phosphorescent pigments in organic carriers, retained for exterior durability applications where water sensitivity poses substrate risks. Regulatory pressure is compressing addressable volume.
- Spray:Aerosol or compressed-air delivery formats packaged for field application precision. Aftermarket automotive customizers and mural artists in Los Angeles and Miami specify these for gradient control and stencil work.
Water-based leads on scale; powder leads on momentum.
End Use:
Demand concentration tracks building code evolution and transportation safety mandates, with construction commanding procurement volume through passive safety system integration.
- Construction:Egress pathway marking, stair nosing, and safety signage in commercial and institutional buildings. General contractors across multi-site portfolios in Germany are consolidating procurement of photoluminescent systems to reduce electrical backup infrastructure. BIS fire safety standards in India are expanding to include photoluminescent egress requirements in high-occupancy structures.
- Automotive:Interior trim accents, instrument panel illumination, and emergency release markings. OEMs specify powder coatings for zero-VOC compliance.
- Aerospace:Cabin floor path marking and emergency exit signage meeting FAA visibility requirements. Certification timelines for ASTM E2072 photometric performance create specification barriers favoring established testing relationships.
- Home Decor:Decorative wall treatments, children's room accents, and artistic applications. Spray formats dominate this discretionary segment.
Construction dominates procurement volume; aerospace commands premium pricing through certification intensity.
Application:
Application method determines pigment loading requirements, substrate preparation protocols, and performance testing regimes that shape supplier selection.
- Road Markings:Thermoplastic and paint-based lane markings, crosswalks, and curb identifiers incorporating phosphorescent pigments for nighttime visibility. Municipal transportation departments in Munich and Hamburg are specifying these for unlit pedestrian zones.
- Safety Signs:Exit signage, fire equipment locators, and hazard warnings requiring ISO 17398 photometric compliance. German public building retrofit mandates are accelerating specification rates.
- Interior Walls:Egress pathway striping and directional markings in commercial and institutional buildings. Water-based formulations prevail due to indoor air quality regulations.
- Artworks:Murals, installations, and decorative pieces leveraging luminescence for aesthetic effect. Spray formats enable field-applied precision for custom commissions.
Safety signs anchor regulatory-driven demand; artworks expand addressable market through discretionary adoption.
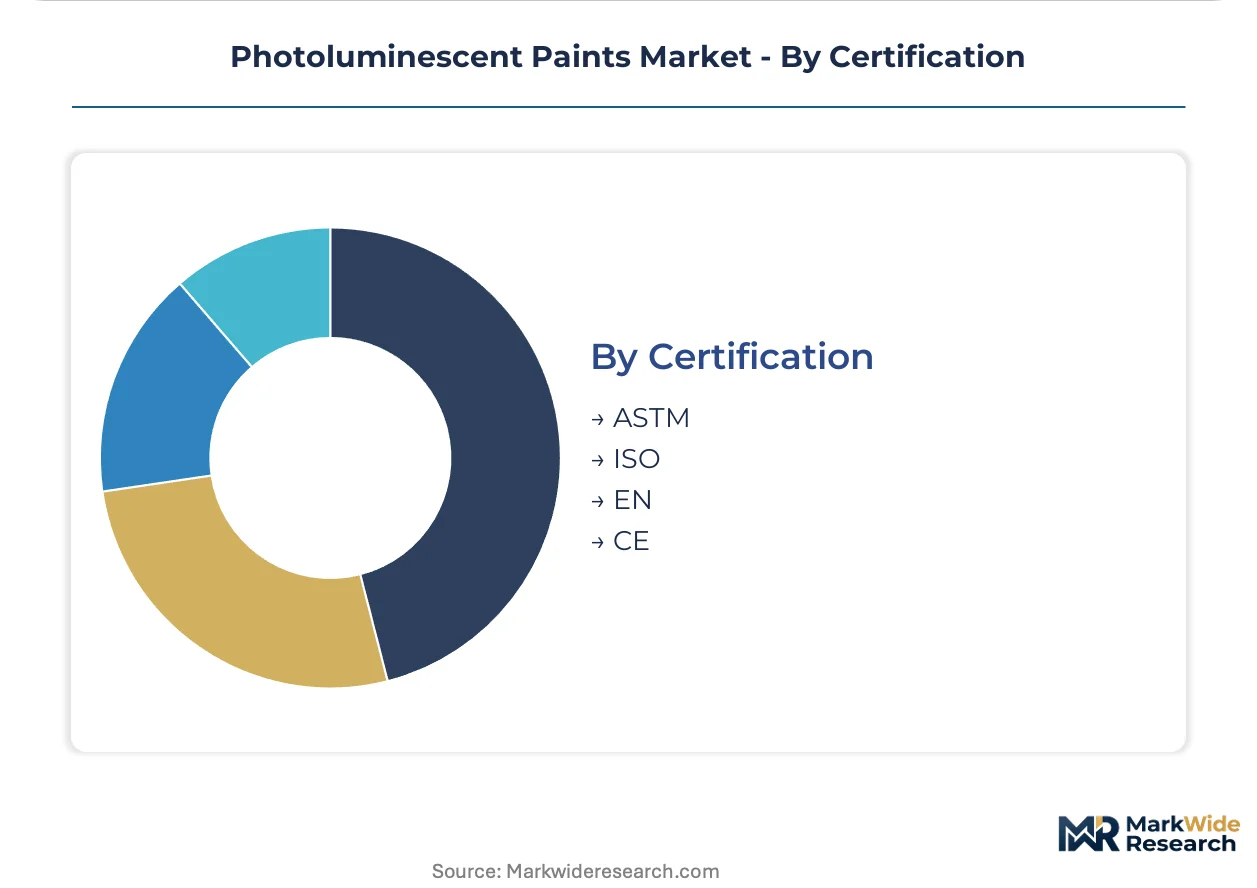
Certification:
Certification selection gates market access, with regional standards bodies imposing divergent testing protocols that fragment supplier compliance investments.
- ASTM:American Society for Testing and Materials standards, notably ASTM E2072 for photoluminescent safety markings. Six-to-twelve month testing timelines delay product launches for new entrants seeking US market positioning.
- ISO:International Organization for Standardization protocols including ISO 17398 for safety colors and safety signs. Global manufacturers leverage ISO certification for multi-jurisdiction efficiency.
- EN:European Norm standards harmonized across EU member states. REACH substance restrictions are tightening compliance scope.
- CE:Conformité Européenne marking mandatory for products sold within the European Economic Area. Carbon footprint disclosure requirements under EU Green Deal are expanding documentation obligations.
ASTM governs North American access; ISO enables cross-border efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in retrofit specification volume, while India accelerates code adoption faster than any Asia-Pacific peer.
Germany
Municipal building renovation programs and consolidated general contractor procurement are driving specification rates for water-based egress markings. The EU Green Deal and REACH substance restrictions mandate carbon footprint disclosure and low-VOC compliance. Stuttgart and Wolfsburg automotive clusters are integrating powder coating processes for zero-VOC interior trim applications.
United States
Commercial construction portfolios and aftermarket automotive customization sustain demand across formulation types. EPA architectural coating standards regulate VOC content for architectural applications. Los Angeles and Miami serve as concentration points for spray-format artistic and custom automotive applications requiring field-applied precision.
India
High-occupancy building construction and evolving fire safety infrastructure are expanding addressable volume. BIS fire safety standards are incorporating photoluminescent egress requirements for public structures. Maharashtra and Gujarat industrial corridors are seeing specification adoption in new commercial developments ahead of national code harmonization.
Japan
Aerospace cabin safety marking and precision manufacturing quality requirements sustain premium-tier demand. METI industrial standards and JIS certification protocols govern photometric performance for safety applications. Nagoya aerospace cluster and Osaka manufacturing belt concentrate specification authority for export-oriented production.
China
Domestic rare-earth processing capacity and construction safety investment are reshaping supply-side positioning. GB standards and MIIT industrial policy guide product quality and environmental compliance. Yangtze River Delta manufacturing hubs are consolidating strontium aluminate pigment production for regional coating formulators.
Photoluminescent Paints Market Competitive Environment
North American producers anchor one tier; European and Asian specialists hold differentiated positions in pigment supply and regional formulation. The market exhibits moderate concentration with three archetypes: diversified coatings conglomerates, captive pigment suppliers, and regional application specialists. Strategic moves center on long-term rare-earth offtake agreements and water-based formulation R&D to secure regulatory compliance positioning.
Within the diversified coatings tier, Rust-Oleum Corporation and Sherwin-Williams represent North American market presence through distribution scale and formulation breadth. PPG Industries occupies a position linking captive strontium aluminate supply to integrated coating production. LumiNova, operating as Nemoto & Co., Ltd., exemplifies the pigment-specialist archetype with rare-earth doping capabilities concentrated in Japanese production.
| Leading Market Players |
|---|
| Rust-Oleum Corporation |
| Benjamin Moore & Co |
| Sherwin-Williams |
| PPG Industries |
| LumiNova (Nemoto & Co., Ltd.) |
| Indra Glowtech Private Limited |
| Allureglow USA |
| Glow Inc. |
| Protech Powder Coating |
| Others |
Value Chain & Pricing Dynamics
Rare-earth oxide price indices for europium and dysprosium cascade through strontium aluminate pigment production into three distinct coating price tiers, with volatility at the mine gate compressing margin buffers for formulators lacking long-term offtake agreements.
Pricing Analysis
Capacity additions in China's rare-earth processing corridors are reshaping price floors for strontium aluminate pigments, yet concentrated doping capability sustains premium tier stability. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17398-certified safety coatings from uncertified decorative grades, with certification tier and volume scale as primary differentiation drivers. Cost compression in economy-grade decorative paints is intensifying because Indian imports compete on spot pigment purchases. Municipal procurement teams exhibit lowest price sensitivity due to retrofit mandate deadlines, while aftermarket automotive customizers drive hardest bargain on spray format premiums.
Supply Chain Analysis
Freight cost differentials between containerized pigment shipments and bulk resin deliveries favor regional formulation hubs over import-dependent coaters. Supply concentrates in China for rare-earth processing, Germany for water-based formulation R&D, and the United States for distribution network density. The chain draws from europium-doped strontium aluminate, aqueous polymer emulsions, and electrostatic spray equipment as critical inputs. Single-source vulnerability in dysprosium supply creates structural risk for premium afterglow duration specifications. Distribution runs through consolidated general contractor procurement desks and specialized safety equipment distributors serving commercial construction portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The photoluminescent paints market functions as a stable compounder where regulatory retrofit mandates in public building safety create predictable specification pipelines across economic cycles.
For Market Incumbents: Extend certification coverage to preempt emerging BIS fire safety standards in Indian high-occupancy construction before code harmonization closes first-mover windows. Deepen backward integration into rare-earth offtake agreements to defend margin position against Chinese export quota volatility. Prioritize water-based formulation capacity in Stuttgart and Wolfsburg to capture automotive OEM powder coating transitions.
For New Entrants and Emerging Players: The gap between premium ASTM E2072-certified aerospace coatings and economy-grade decorative sprays offers white-space entry for mid-tier performance positioning. Target Indian commercial construction ahead of national BIS code expansion, where specification authority remains fragmented across state-level contractors. Pursue direct contractor procurement relationships to bypass established distribution markups in German municipal retrofit programs.
For Investors and Strategic Acquirers: Consolidation pressure builds where rare-earth doping capability concentrates among three Japanese and Chinese pigment specialists, suggesting rollup opportunity in regional formulation tiers. The 5-10 year viability window favors captive pigment supply over pure-play coating assets. Monitor Chinese MIIT industrial policy signals for rare-earth export licensing shifts as inflection indicator for input cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Offtake | Secures dysprosium supply for premium afterglow formulations against Chinese quota volatility. |
| Water-Based Formulation Capacity Expansion | Positions German facilities to capture EU Green Deal retrofit mandate volume in municipal construction. |
| ASTM E2072 Certification Investment | Opens FAA-aligned aerospace cabin marking specifications requiring established testing relationships. |
| Direct Contractor Procurement Channel | Bypasses distribution markups as general contractors consolidate multi-site safety procurement. |
| Joint Venture with Pigment Specialist | Combines coating formulation expertise with Nemoto's LumiNova rare-earth doping capabilities. |
Study Parameters
Bottom-up construction and automotive demand modeling reconciled against top-down strontium aluminate pigment supply tracking forms the analytical core of this study. Primary interviews with plant managers at coating production facilities, procurement leads at German general contractors, technical R&D directors at pigment processors, and distribution channel partners in safety equipment supply informed volume assumptions. Secondary validation drew from EPA architectural coating standard filings, REACH substance restriction updates, BIS fire safety code drafts, and SEC 10-K disclosures from diversified coatings conglomerates. Triangulation between end-use specification rates and raw material trade flows anchored market sizing integrity.
The input-output matrix maps formulation chemistry transitions, application method adoption curves, and certification requirement evolution across the projection horizon. Segmentation dimensions include product type (water-based, powder, solvent-based, spray), end-use industry (construction, automotive, aerospace, home decor), and regional regulatory cluster (EPA-governed, REACH-aligned, BIS-emerging, GB-standardized). CAGRs derive from installed base replacement cycles for zinc sulfide legacy systems and new build specification penetration rates. Forecast inputs incorporate rare-earth price elasticity coefficients and municipal retrofit budget allocation patterns.
Caveats apply where Chinese export licensing reforms or EU Green Deal carbon border adjustments could materially shift the outlook for formulation cost structures and competitive access. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Asia Pacific Hair Colorants Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Pearlescent Pigments Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Thermochromic Pigments Market
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Dyestuff (Black Color) Market
Dyes and Pigments
Mulch Colorants Market
Dyes and Pigments
Thermochromic Labels Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Reactive Dyes Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Pearl Pigment Market
Dyes and Pigments
Erythrosine Market