
 Global Rubber Additives Market | 2026-2036
Global Rubber Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rubber Additives Market Foresight
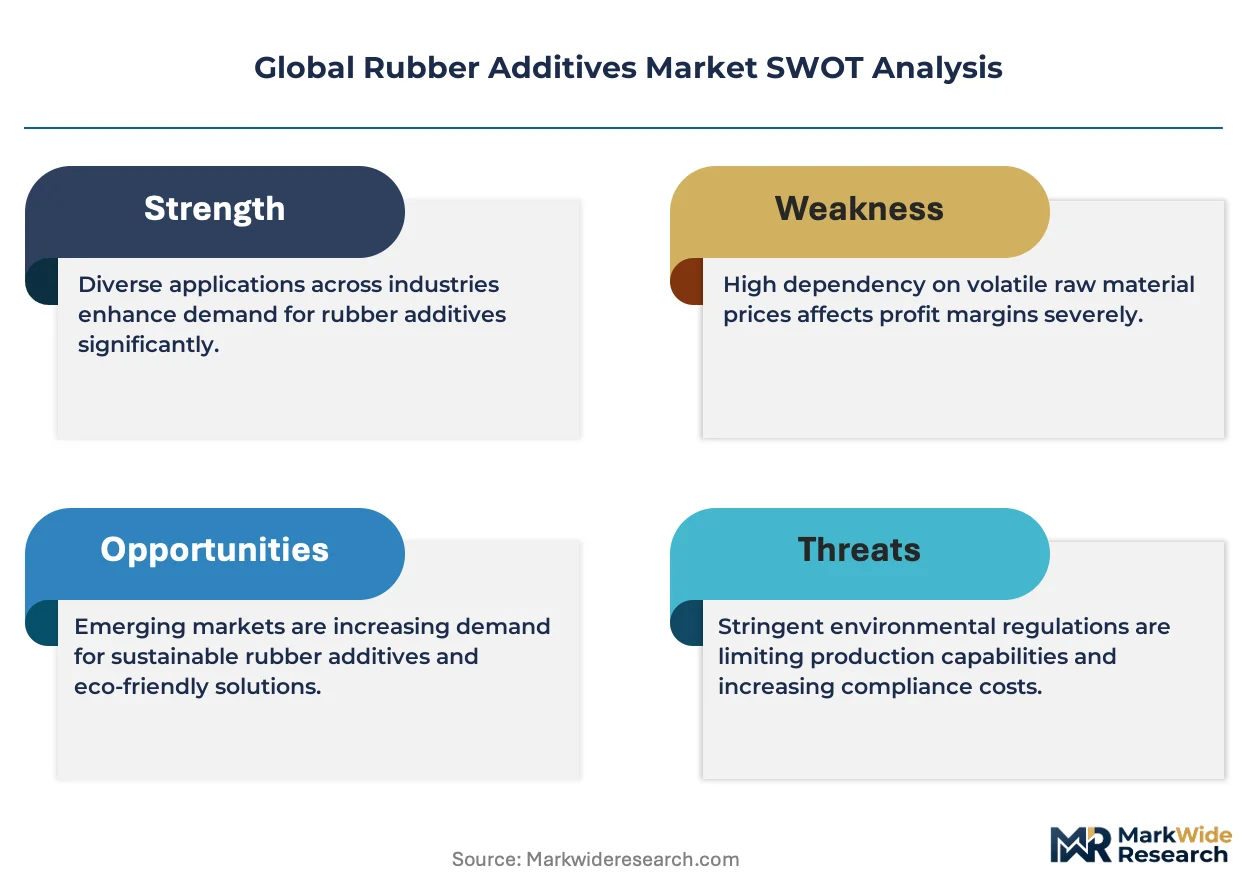
The EU Green Deal is broadening sustainability requirements across European tire supply chains. BASF SE leverages its integrated chemical complexes to supply low-PAH antioxidant packages. LANXESS anchors its position through backward integration into key rubber chemical intermediates. Arkema competes via specialized resin and functional additive portfolios for high-durability applications.
Rubber additives comprise chemical agents and fillers that modify vulcanization kinetics, oxidative stability, and mechanical properties of natural and synthetic rubber compounds; sulfur-based vulcanization agents typically constitute 1–3 phr (parts per hundred rubber) while carbon black and silica fillers dominate volume at 30–60 phr loadings. Antioxidants command premium margins due to stringent durability specifications in tire manufacturing, while accelerators represent the fastest-growing product category as tire makers reformulate for lower rolling resistance. Processing aids attract growing interest from footwear producers seeking to reduce energy consumption during calendering and extrusion operations.
The EPA regulates aromatic oil extender limits in US tire production, while REACH restricts polycyclic aromatic hydrocarbon content in European rubber goods. China's MEE enforces emission controls on rubber chemical manufacturing clusters, compelling domestic producers to upgrade effluent treatment. Stakeholders must monitor evolving chemical hazard classifications across FDA, ECHA, and SAMR jurisdictions to preempt formulation disruption and secure continued market access.
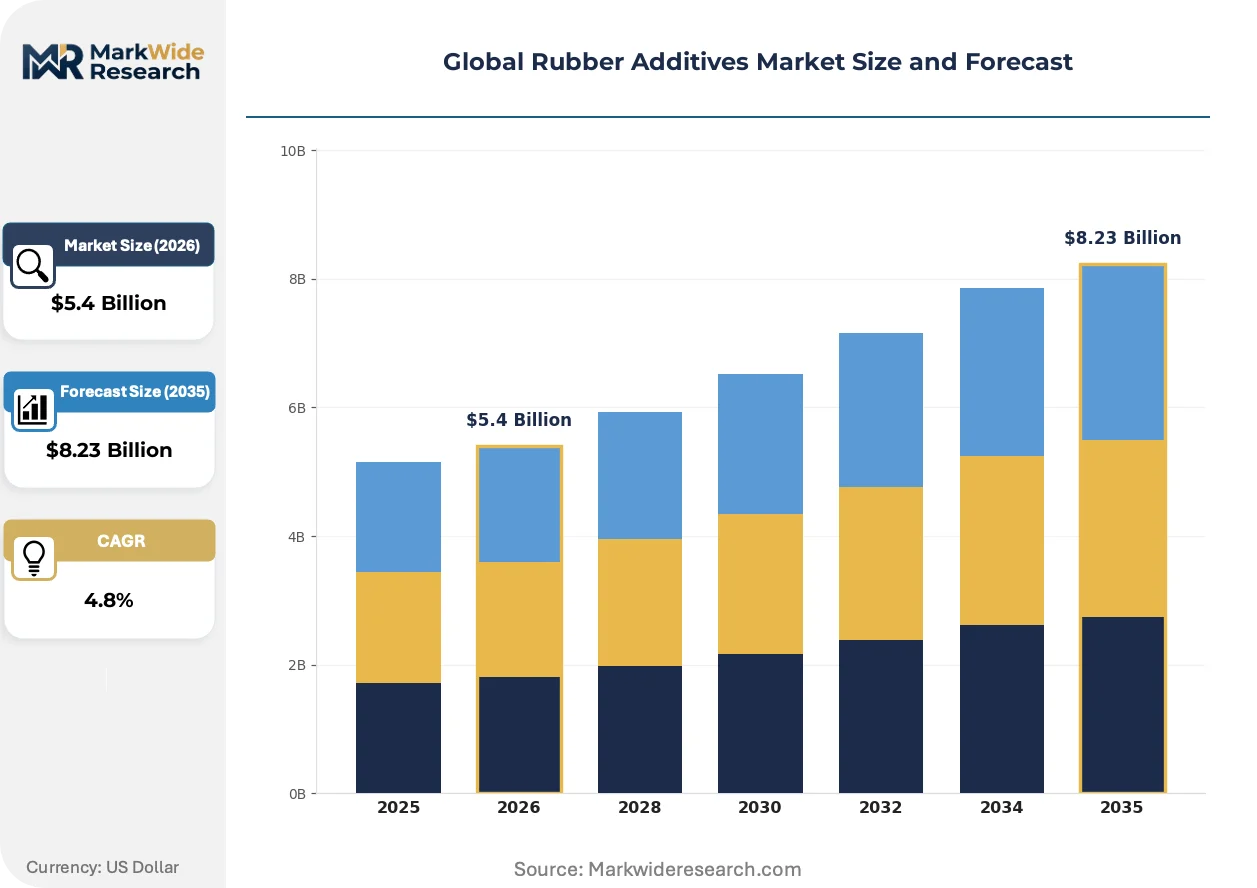
Market Dynamics
Tire manufacturers in China, India, and Indonesia are reformulating compounds to meet dual carbon goals and REACH-aligned export standards, compressing additive specification cycles from 18 months to under 12 months.
Growth Catalysts
- EU Green Deal implementation:REACH compliance requirements are broadening formulation specifications across European tire supply chains, forcing additive upgrades that improve durability and reduce polycyclic aromatic hydrocarbon content.
- Low rolling resistance tire demand:Accelerators are commanding expanded volumes as tire makers reformulate tread compounds to meet NHTSA fuel economy standards and consumer efficiency expectations in North America and Europe.
- Asia-Pacific manufacturing expansion:Procurement of high-performance antioxidants and processing aids is concentrating in China, India, and Indonesia as domestic tire production capacity scales for regional and export markets.
Market Restraints
- Petrochemical feedstock volatility:Carbon black and synthetic rubber precursor costs fluctuate with crude oil indices, compressing margins for additive compounders serving price-sensitive footwear and industrial rubber segments.
- Effluent treatment capex burden:China's MEE emission controls on rubber chemical manufacturing clusters are forcing domestic producers to redirect capital toward wastewater and air treatment upgrades rather than capacity expansion.
- Alternative filler substitution:Silica-silane systems are partially displacing traditional carbon black loadings in premium tire segments, reducing volume demand for conventional reinforcing fillers.
Strategic Opportunities
- India tire export acceleration:PLI scheme incentives for domestic manufacturing are attracting global tire makers to establish compounding facilities, creating localized demand for antioxidant and accelerator packages.
- Bio-based processing aid development:Footwear producers in Vietnam and Indonesia are piloting plant-derived plasticizers and peptizers to reduce energy consumption during calendering operations.
- Dual carbon alignment in China:GB standards for low-carbon rubber products are creating preferential procurement channels for additive suppliers with verified carbon footprint reductions.
Industry Challenges
- Formulation chemistry expertise scarcity:Compound development teams with deep knowledge of sulfur vulcanization kinetics and silica dispersion are concentrated among retiring specialists at legacy tire makers.
- Multi-jurisdiction hazard classification synchronization:Stakeholders must simultaneously track ECHA REACH amendments, EPA TSCA reviews, and SAMR chemical inventory updates to preempt formulation disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rubber Additives Market |
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Accelerators, Fillers, Plasticizers, Vulcanization Agents, Processing Aids Application: Tire Manufacturing, Footwear Production, Conveyor Belts, Wire & Cable, Automotive Components, Adhesives End User: Tire Manufacturers, Footwear Brands, Conveyor System Producers, Wire Manufacturers, Vehicle Component Fabricators, Adhesive Suppliers Packaging Type: Bulk Bags, FIBC Bags, Drums, Paper Bags, Plastic Containers, Carboys |
| Companies Covered | BASF SE, LANXESS, Arkema, Eastman Chemical Company, Solvay, China Petrochemical Corporation, Behn Meyer, Akzo Nobel, Struktol Company of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rubber Additives Market Shifts & Advancements
Functional additive portfolios are fragmenting as tire durability specifications diverge between premium electric vehicle platforms and cost-optimized internal combustion vehicle replacement tires.
Silica-silane coupling systems are overtaking conventional carbon black reinforcing packages in high-performance tire tread formulations. Tire makers serving European and North American original equipment channels are adopting these systems at accelerated rates to achieve sub-7.0 kg/t rolling resistance coefficients. This transition is compressing demand for traditional high-structure carbon black grades while expanding specialty silane modifier volumes.
REACH restrictions on polycyclic aromatic hydrocarbon content in rubber goods are forcing reformulation of aromatic oil extenders and softeners across European tire supply chains. Compounders are substituting treated distillate aromatic extracts with alternative plasticizers that meet ECHA hazard classifications. Premium tire segments in Germany, France, and Italy are absorbing the highest compliance costs, with some producers qualifying low-PAH antioxidant packages through accelerated stability testing protocols.
Specification-driven procurement consolidation is concentrating additive purchasing decisions among fewer tire maker technical centers. Tier-1 suppliers are bypassing traditional distributor channels to contract directly with BASF SE, LANXESS, and Arkema for multi-year antioxidant and accelerator supply agreements. This pattern is most visible in China, where domestic tire makers are consolidating from over 500 producers toward 50 major compounders with integrated technical development capabilities.
Global Rubber Additives Market Segmentation
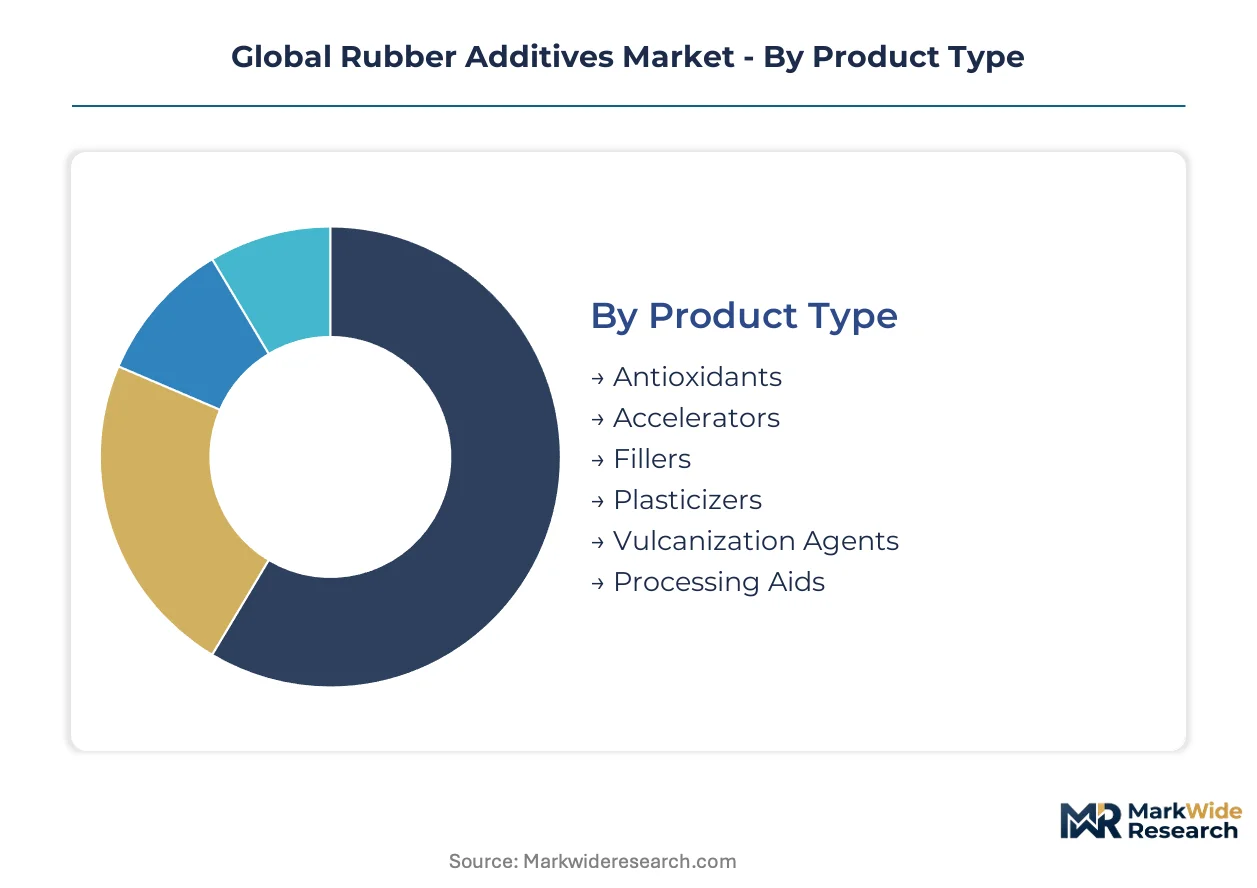
Rubber additives serve divergent performance requirements across tire durability, footwear flexibility, and industrial mechanical specifications. Segmentation reveals how formulation chemistry, packaging logistics, and end-use certification standards reshape procurement patterns and supplier positioning.
Product Type:
Standardization dominates commodity fillers and vulcanization agents, while antioxidants and accelerators command bespoke specification development.
- Antioxidants:These stabilizers protect rubber compounds against thermal oxidation and ozone degradation through hindered phenol or amine chemistries. Demand concentrates among tire manufacturers in Germany, Japan, and South Korea as REACH and dual carbon goals tighten durability specifications. Premium margins reflect accelerated stability testing protocols and low-PAH compliance requirements.
- Accelerators:Thiazole, sulfenamide, and guanidine compounds control vulcanization kinetics and cross-link density. Procurement is climbing fastest in China and India as domestic tire makers reformulate tread compounds for lower rolling resistance coefficients. This category is expanding most quickly among all product types.
- Fillers:Carbon black and silica reinforce mechanical properties at 30–60 phr loadings.
- Plasticizers:Aromatic and naphthenic oils modify compound viscosity and processing behavior.
- Vulcanization Agents:Sulfur and peroxide systems initiate cross-linking at 1–3 phr concentrations.
- Processing Aids:Peptizers and homogenizing agents reduce mixing energy and improve filler dispersion.
Most installed capacity flows through Fillers. Expansion is steepest in Accelerators.
Application:
Volume concentrates in tire manufacturing, while margin capture diverges across footwear efficiency programs and industrial durability specifications.
- Tire Manufacturing:Tread, sidewall, and inner liner compounds consume antioxidants, accelerators, and silica-silane systems for rolling resistance and wear performance. Procurement in China, India, and Indonesia is scaling as domestic capacity serves regional and export markets. EPA fuel economy standards and NHTSA regulations in the US reinforce specification stringency.
- Footwear Production:Soling compounds employ plasticizers and processing aids to reduce calendering energy and improve flex resistance. Vietnamese and Indonesian producers are piloting bio-based peptizers to meet sustainability procurement criteria from European brands.
- Conveyor Belts:Heavy-duty rubber compounds require high-structure carbon black and heat-resistant antioxidant packages.
- Wire & Cable:Insulation and jacketing formulations prioritize electrical resistivity and aging stability.
- Automotive Components:Hoses, seals, and mounts demand dynamic fatigue resistance and fluid compatibility.
- Adhesives:Tackifiers and curing modifiers bond rubber-to-metal and rubber-to-fabric substrates.
Revenue concentration sits with Tire Manufacturing. Technical differentiation is widening fastest in Footwear Production.
End User:
Procurement sophistication separates integrated tire compounders from fragmented footwear and industrial rubber fabricators.
- Tire Manufacturers:Technical centers in China, Germany, Japan, and the US specify multi-year antioxidant and accelerator supply agreements directly with BASF SE, LANXESS, and Arkema. Consolidation from over 500 domestic Chinese producers toward 50 major compounders is compressing distributor channels.
- Footwear Brands:Sustainability mandates from European and North American retailers are driving qualification of plant-derived plasticizers.
- Conveyor System Producers:Mining and bulk material handling operations specify abrasion-resistant formulations.
- Wire Manufacturers:Electrical insulation compounders prioritize thermal aging and dielectric performance.
- Vehicle Component Fabricators:Under-the-hood applications require heat and fluid resistance.
- Adhesive Suppliers:Construction and industrial bonding applications demand consistent cure kinetics.
Contract value aggregates with Tire Manufacturers. Procurement reform is advancing fastest among Footwear Brands.
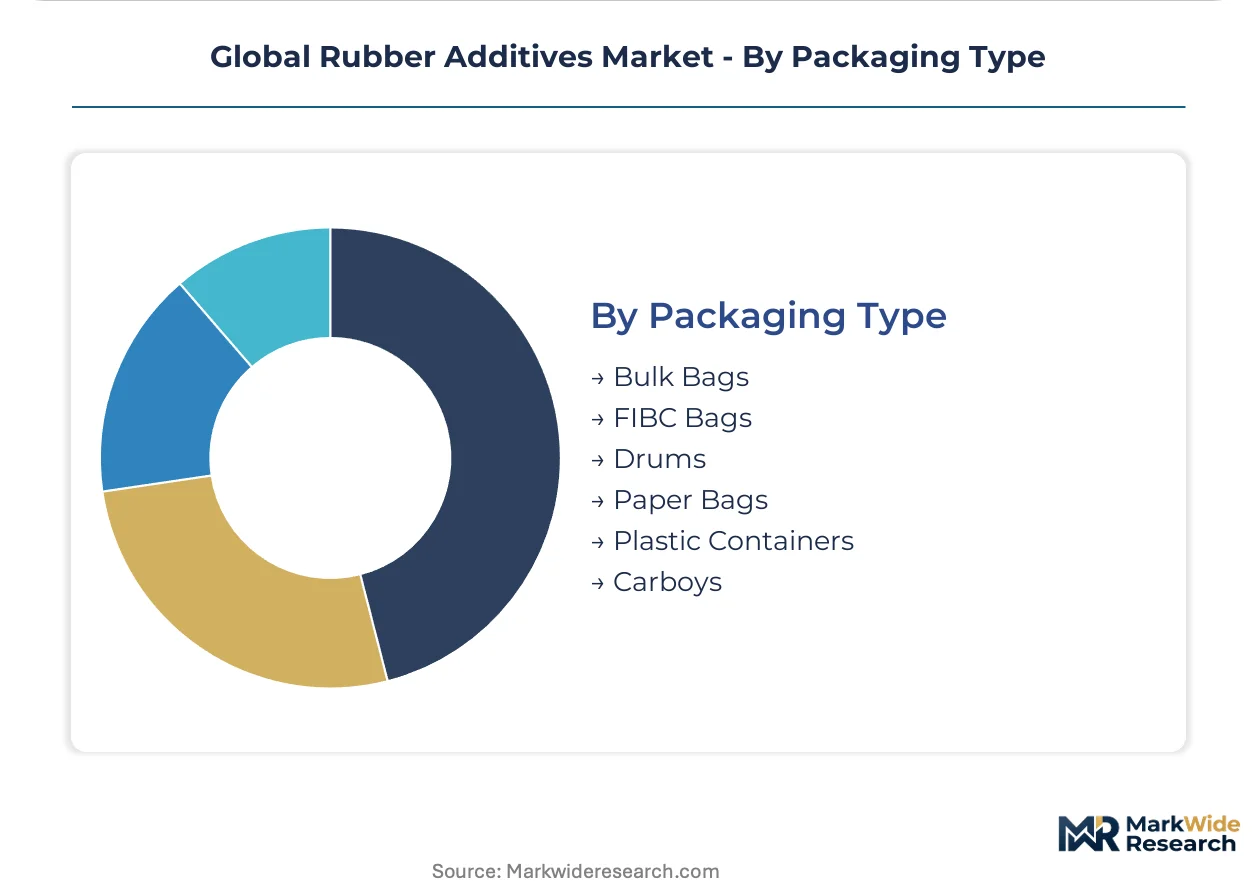
Packaging Type:
Logistics economics and handling automation separate bulk industrial formats from precision dosing containers.
- Bulk Bags:One-ton flexible intermediate bulk containers serve high-volume carbon black and silica shipments to integrated tire plants. Chinese and Indian manufacturing clusters favor this format for rail and truck efficiency.
- FIBC Bags:Type-A and Type-C conductive designs prevent electrostatic ignition during resin and chemical handling.
- Drums:Steel and fiber containers protect liquid plasticizers and antioxidants from moisture ingress.
- Paper Bags:Multi-wall kraft constructions package powdered accelerators and vulcanization agents.
- Plastic Containers:Pails and totes serve specialty additive blends with moisture sensitivity.
- Carboys:Glass and plastic demijohns handle laboratory-scale and sampling quantities.
Shipment volume concentrates in Bulk Bags. Automation adoption is rising fastest in FIBC Bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineering established the foundation for modern rubber additive synthesis during the early twentieth century, with Bayer and BASF pioneering antioxidant and accelerator chemistries that remain industry benchmarks. This technical lineage continues to shape formulation standards across automotive supply chains worldwide.
China
Domestic tire production capacity expansion in Shandong and Jiangsu provinces drives procurement of silica-silane coupling systems and low-PAH antioxidant packages. MEE emission controls on rubber chemical manufacturing clusters compel producers in Qingdao and Zibo to upgrade effluent treatment infrastructure. Procurement consolidation among 50 major compounders is compressing traditional distributor channels.
Germany
Premium tire original equipment specifications from Stuttgart and Munich technical centers sustain demand for high-durability antioxidant formulations. ECHA REACH amendments restricting polycyclic aromatic hydrocarbon content force reformulation of aromatic oil extenders across European supply chains. Lanxess leverages backward integration into rubber chemical intermediates at its Leverkusen and Krefeld sites.
United States
NHTSA fuel economy standards and EPA aromatic oil extender limits reshape tread compound specifications for domestic tire makers. Detroit-area automotive technical centers specify multi-year accelerator supply agreements directly with integrated chemical suppliers. Carbon black and synthetic rubber precursor costs fluctuate with crude oil indices, compressing margins for compounders serving industrial rubber segments.
India
PLI scheme incentives for domestic manufacturing attract global tire makers to establish compounding facilities in Gujarat and Tamil Nadu. BIS standards alignment with REACH specifications creates qualification pathways for export-oriented producers. Procurement of high-performance antioxidants and processing aids concentrates in Chennai and Ahmedabad as regional production capacity scales.
Japan
Automotive original equipment durability specifications from Tokyo and Nagoya sustain premium demand for hindered phenol antioxidant systems. METI carbon neutrality roadmaps accelerate reformulation toward lower rolling resistance coefficients. Tire makers in Kanto and Kansai regions contract directly with specialty chemical suppliers for technical development partnerships.
Global Rubber Additives Market Competitive Landscape
Capital-heavy producers compete with asset-light formulators across distinct capability tiers. Integrated chemical complexes with captive intermediate supply command pricing power in antioxidant and accelerator categories. Three archetypes dominate: multinational diversified chemical conglomerates with rubber specialty divisions, regional integrated producers serving domestic tire clusters, and niche functional additive specialists. Consolidation through multi-year supply agreements and backward integration into key intermediates represents the primary competitive dynamic.
Within the multinational tier, BASF SE anchors integrated supply of low-PAH antioxidant packages through its Ludwigshafen chemical complex. LANXESS exemplifies backward integration strategy with captive production of rubber chemical intermediates. Arkema occupies a position among functional additive specialists, with its Colombes headquarters reflecting French chemical engineering heritage. These three represent divergent approaches to formulation partnership and technical service depth.
| Leading Market Players |
|---|
| BASF SE |
| LANXESS |
| Arkema |
| Eastman Chemical Company |
| Solvay |
| China Petrochemical Corporation |
| Behn Meyer |
| Akzo Nobel |
| Struktol Company of America |
| Others |
Supply & Pricing Matrix
Tire manufacturer technical centers in China, Germany, and Japan command contract-based long-term offtake agreements that compress spot market liquidity and anchor pricing power among integrated chemical suppliers. This buyer concentration forces additive compounders to absorb feedstock volatility while defending margin positions through specification lock-in and multi-year volume commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs antioxidant and accelerator procurement, with premium tiers capturing margin from REACH-compliant low-PAH formulations and accelerated stability testing protocols. Price differentiation rests on certification grade and volume scale, with integrated tire compounders extracting scale discounts unavailable to fragmented footwear producers. Cost compression in standard-grade accelerators is intensifying because crude-linked petrochemical feedstock volatility erodes compounder margins. Footwear brands in Vietnam and Indonesia exhibit highest price sensitivity due to energy-cost-driven processing aid substitution programs, while German premium tire OEMs demonstrate lowest sensitivity given durability-specification premiums.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for export-oriented tire compounders in Gujarat and Tamil Nadu. Manufacturing gravity draws from China, Germany, and India, with carbon black and synthetic rubber precursors feeding from crude oil indices and specialty silane modifiers sourcing from South Korean chemical complexes. Single-source vulnerability concentrates in high-structure carbon black grades for conveyor belt applications, where limited qualified suppliers create qualification bottlenecks. Distribution runs through direct technical-center contracting for tire manufacturers, bypassing traditional distributor channels, while footwear and industrial segments retain regional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH amendments restricting polycyclic aromatic hydrocarbon content drive sustained additive reformulation demand across European tire supply chains.
For Market Incumbents: Anchor backward integration into rubber chemical intermediates to defend against silica-silane substitution threats in premium tire tread formulations. Prioritize captive production of hindered phenol antioxidant systems at Ludwigshafen and Leverkusen-scale complexes to secure specification lock-in with consolidating Chinese tire compounders. Channel control through direct technical-center relationships represents the critical lever for margin defense as distributor networks compress. For New Entrants and Emerging Players: Bio-based processing aid buyers in Vietnamese and Indonesian footwear production represent the most penetrable white-space target, with plant-derived peptizer qualification pathways opening through European brand sustainability procurement criteria. Target this segment through pilot-scale toll manufacturing partnerships with established compounders, leveraging carbon footprint verification as the primary go-to-market angle against petroleum-derived incumbent offerings. For Investors and Strategic Acquirers: Integrated tire manufacturers are the most active acquirer in this space, seeking captive additive supply to secure formulation autonomy amid specification cycle compression. Long-term viability frames around dual carbon alignment capabilities and REACH compliance infrastructure as durable competitive moats. Acquisition target archetypes include regional rubber chemical producers with MEE-compliant effluent treatment infrastructure in Shandong and Jiangsu provinces. The signal to watch is procurement consolidation velocity among Chinese tire compounders, with technical-center integration rates indicating inflection toward direct-supply dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive intermediate production at Leverkusen and Ludwigshafen complexes secures antioxidant margin control against feedstock volatility. |
| Long-term Supply Agreement | Multi-year accelerator contracts with Stuttgart and Munich technical centers lock in specification-driven procurement consolidation. |
| Green Manufacturing Transition | Low-PAH formulation upgrades align with ECHA REACH amendments and EU Green Deal sustainability mandates. |
| Joint Venture | Localized compounding partnerships in Gujarat and Tamil Nadu capture PLI scheme incentives for India tire export acceleration. |
| Capacity Expansion | Silica-silane coupling system scale-up serves NHTSA fuel economy standards and sub-7.0 kg/t rolling resistance coefficients. |
Research Methodology
Bottom-up tire manufacturing modeling reconciled against top-down rubber chemical production tracking forms the analytical core of this study. Primary interviews with plant managers at Shandong and Jiangsu manufacturing clusters, procurement leads at integrated tire compounders, distribution channel partners in European chemical distribution networks, and technical R&D directors at antioxidant and accelerator suppliers were validated against secondary sources including customs and trade data from China and India, ACC and Cefic industry reports, SEC 10-K filings from diversified chemical conglomerates, and ECHA REACH amendment documentation.
Historical trendline analysis across the projection horizon established baseline growth patterns for each segmentation dimension modeled: product type tier, end-use application, packaging format, and regional production hub. CAGRs were derived through elasticity modeling of tire production capacity expansion against additive intensity per compound ton, with silica-silane substitution rates and dual carbon policy implementation timelines serving as key forecast inputs.
Underlying measurement precision varies by segment; tire manufacturing application data carry tighter precision than fragmented footwear and industrial rubber segments due to concentrated technical-center reporting. Forecasts reflect documented assumptions regarding REACH compliance timelines, MEE enforcement intensity, and PLI scheme disbursement rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Styrene Butadiene (SB) Latex Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Polybutadiene Market
Rubber
Global Styrene Butadiene Styrene Market
Rubber
Chloroprene Rubber Tape Market
Rubber
Tire Recycling Downstream Products Market
Rubber
Rubber Molding Market
Rubber
Gum Rosin Market
Rubber
Natural Rubber Market
Rubber
Global Cast Elastomers Market
Rubber
Isobutylene Market
Rubber
Rubber Carbon Black Market
Rubber
Polyacrylate Rubber Market
Rubber
Rubber Foam Materials Market
Rubber
Rubber Ropes Market
Rubber
Global Hydraulic Rubber Hose Market