
 Acrylamide Reduction Market | 2026-2036
Acrylamide Reduction Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylamide Reduction Market Analytics
Snack food manufacturing is realigning toward enzymatic acrylamide control as fried and baked product portfolios expand. BASF SE leverages its specialty chemical portfolio to supply food-grade acrylamide inhibitors for industrial fryer operations. Novozymes A/S anchors the enzymatic solutions segment with asparaginase technologies that reduce precursor formation in potato and cereal processing. Kerry Group competes through integrated ingredient systems that combine enzyme blends with process optimization protocols for contract manufacturers.
Acrylamide reduction encompasses technologies and treatments that lower formation of the probable human carcinogen 2-propenamide during high-temperature cooking of starchy foods, primarily through enzymatic hydrolysis of asparagine, chemical intervention with divalent cations, or modified thermal profiles below the Maillard reaction threshold. Enzymatic solutions lead product type demand due to clean-label compatibility and minimal sensory impact on finished foods. Chemical solutions sustain margin pools in commodity snack production where cost sensitivity overrides label positioning. Thermal treatments occupy niche applications in artisanal bakery segments where equipment retrofit constraints limit enzyme adoption.
The European Commission's benchmark regulation and FDA guidance on acrylamide mitigation establish compliance baselines that shape product development priorities for ingredient suppliers and food manufacturers. EFSA risk assessments and California Proposition 65 litigation exposure in the United States create dual jurisdictional pressure for preemptive reformulation across multinational portfolios. Stakeholders must monitor evolving maximum level proposals and enzyme cost curves to determine timing for process conversion investments versus regulatory penalty risk.
Market Dynamics
The European Commission's benchmark levels for acrylamide in food products are forcing snack manufacturers to reformulate production lines and source enzymatic mitigation solutions, compressing decision timelines from years to quarters.
Growth Catalysts
- EFSA Risk Assessments:The European Food Safety Authority's ongoing evaluations of acrylamide dietary exposure are compelling food manufacturers across Germany, France, and the United Kingdom to adopt asparaginase-based treatments before mandatory maximum limits take effect.
- Fried Snack Portfolio Expansion:Industrial fryer operations in potato chip and crisp manufacturing are scaling enzymatic pre-treatment baths to maintain output volumes while meeting contaminant thresholds for export markets.
- Clean-Label Positioning:Consumer packaged goods brands are replacing chemical acrylamide inhibitors with enzyme-based alternatives to preserve front-of-package claims and avoid ingredient list complexity.
Market Restraints
- Asparagine Analytical Costs:Real-time monitoring of precursor amino acid levels in incoming potato and cereal batches requires capital investment in chromatography equipment that commodity snack producers resist.
- Enzyme Supply Concentration:Food-grade asparaginase production concentrates among Danish and Dutch biotechnology suppliers, creating vulnerability for manufacturers dependent on just-in-time enzyme delivery.
- Thermal Profile Trade-offs:Modified frying and baking temperatures that suppress Maillard reaction pathways often extend cook times and reduce throughput, conflicting with line efficiency targets.
Strategic Opportunities
- Bakery Segment Penetration:Artisanal bread and biscuit producers in Italy and Spain remain underpenetrated by enzymatic solutions due to equipment retrofit constraints, presenting white space for portable thermal treatment units.
- California Proposition 65:Litigation exposure in the United States is creating preemptive reformulation demand among multinational snack portfolios before federal maximum levels materialize.
- Enzyme-Mineral Convergence:Blended solutions combining asparaginase with calcium or magnesium interventions are opening dual-mechanism positioning for mid-tier price points between premium enzymes and commodity chemicals.
Industry Challenges
- Process Validation Timelines:Food manufacturers face extended certification cycles when retrofitting existing fryer lines with enzymatic pre-treatment stages, delaying revenue recognition on reformulation investments.
- Sensory Panel Integration:Enzyme-treated products require expanded consumer testing protocols to detect off-notes in finished foods, straining quality assurance functions already compressed by regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylamide Reduction Market |
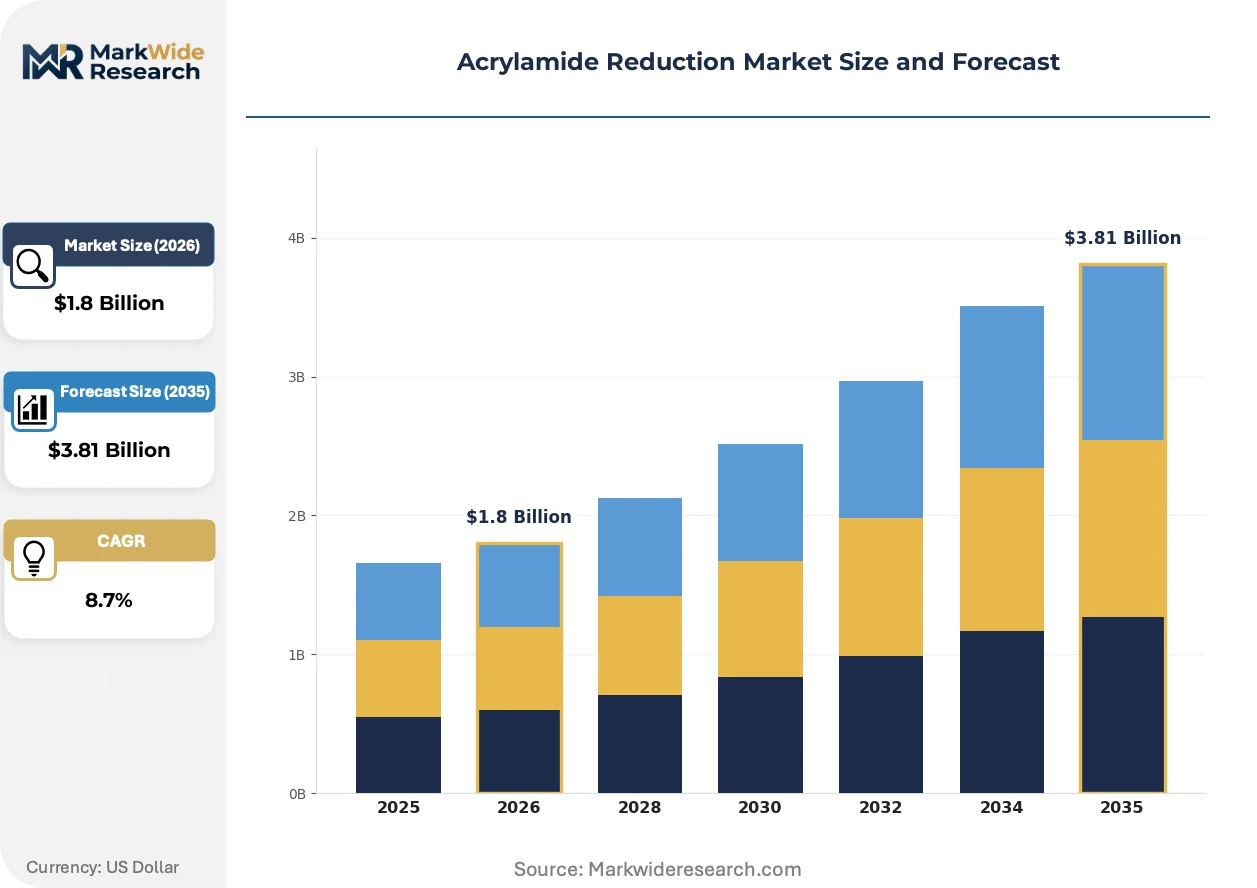
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymatic Solutions, Chemical Solutions, Thermal Treatments, Adsorbents Application: Snack Foods, Beverages, Bakery Products, Convenience Foods End User: Food Manufacturers, Beverage Producers, Restaurants, Retail Chains Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, Kemira Oyj, SNF Group, Ashland Global Holdings Inc., DSM N.V., Novozymes A/S, Kerry Group, DuPont de Nemours, Inc., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylamide Reduction Market Evolving Landscape
Enzymatic acrylamide control is expanding from potato processing into cereal-based applications, reshaping supplier R&D priorities and forcing ingredient companies to reformulate enzyme stability for broader pH and temperature ranges.
Second-generation asparaginase variants are expanding into wheat-based bakery and breakfast cereal manufacturing, where higher thermal loads and variable moisture content previously excluded enzymatic intervention. Major biscuit producers in Belgium and the Netherlands are piloting these treatments at commercial scale. The technology is expanding into product categories historically dependent on chemical inhibitors or thermal modification alone.
REACH authorization procedures for food-contact enzyme preparations are tightening purity documentation requirements for suppliers seeking European market access. Industrial enzyme manufacturers must now submit expanded toxicological dossiers to ECHA before commercial distribution. Snack ingredient divisions with existing pharmaceutical-grade enzyme capabilities are capturing share from commodity chemical suppliers lacking equivalent regulatory infrastructure.
Contract manufacturers are consolidating acrylamide mitigation procurement under single-source enzyme supply agreements with technical service attachments, displacing spot purchasing of chemical additives. This bundling concentrates buying power among large co-manufacturers serving multiple branded snack portfolios. Germany's private-label snack sector exhibits the most pronounced shift toward integrated enzyme-plus-process-optimization contracts.
Acrylamide Reduction Market Segmentation
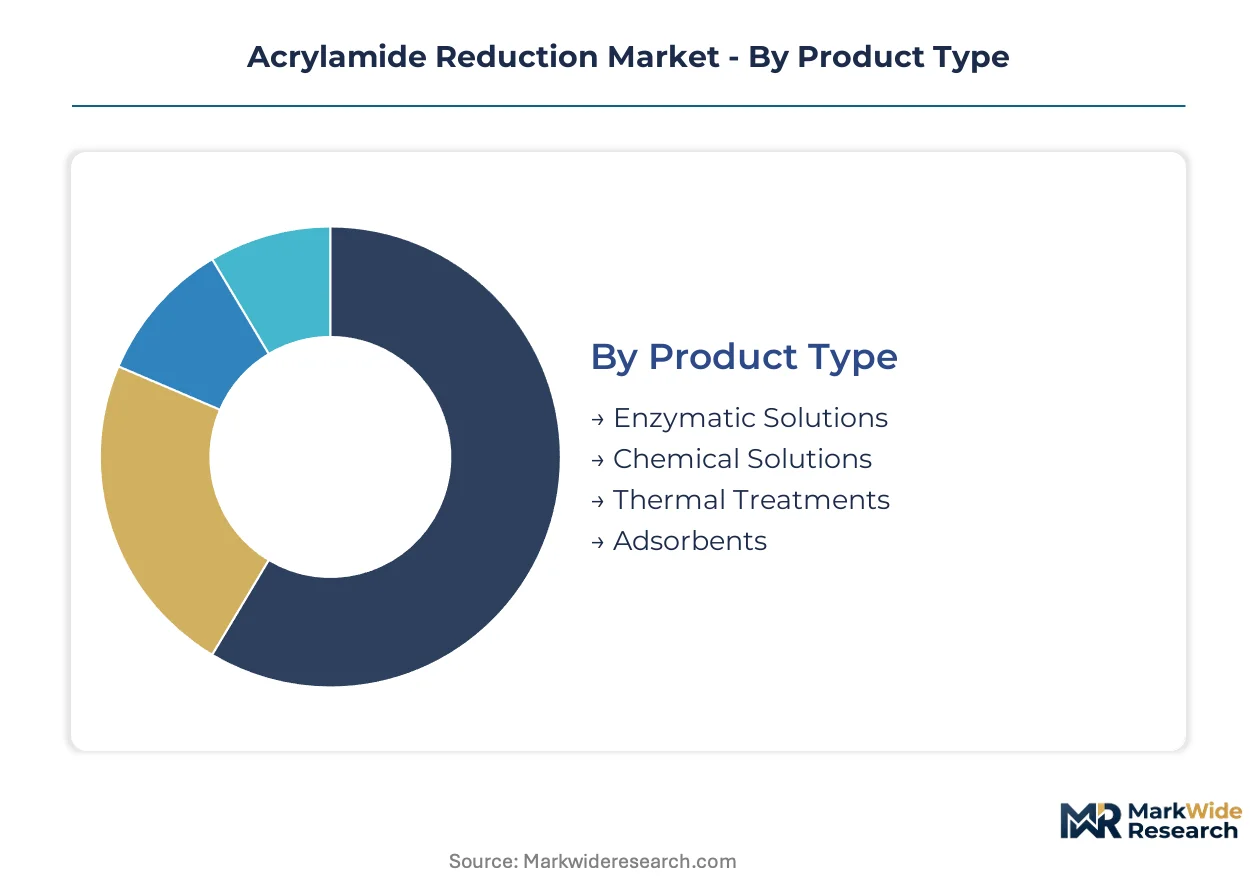
Segmentation in acrylamide reduction technologies separates capital-intensive enzymatic infrastructure from lower-barrier chemical and thermal alternatives. Procurement patterns diverge sharply between multinational snack manufacturers investing in integrated pre-treatment systems and smaller bakeries seeking point-of-use additives.
Product Type:
Capital intensity varies dramatically across product categories, with enzymatic solutions requiring dedicated pre-treatment baths and real-time monitoring equipment while chemical alternatives demand minimal retrofit.
- Enzymatic Solutions:Asparaginase-based treatments hydrolyze free asparagine before Maillard reaction conditions occur. Industrial fryer operations in Germany and the Netherlands are scaling immersion-stage enzyme baths to maintain throughput while meeting EFSA contaminant thresholds.
- Chemical Solutions:Divalent cation interventions using calcium or magnesium salts compete on upfront cost. Commodity potato chip producers in the United Kingdom favor these for legacy fryer lines where enzyme retrofit timelines conflict with quarterly compliance deadlines.
- Thermal Treatments:Modified temperature profiles below acrylamide formation thresholds suit artisanal bakeries with batch equipment constraints.
- Adsorbents:Activated carbon and clay-based filtration systems occupy niche positions in beverage applications where enzymatic intervention is impractical.
Enzymatic Solutions absorb the bulk of installed capacity; Chemical Solutions are expanding most quickly among cost-constrained manufacturers.
Application:
Application segmentation tracks where precursor amino acid concentrations and thermal processing intensity create the highest regulatory risk.
- Snack Foods:Potato chips, crisps, and extruded snacks face the strictest EFSA benchmark levels. Fried snack portfolios in Belgium and France are converting to enzymatic pre-treatment at commercial scale.
- Bakery Products:Bread, biscuits, and breakfast cereals present variable moisture and pH challenges that second-generation asparaginase variants are engineered to address.
- Beverages:Coffee and malt-based drinks require adsorbent or thermal intervention where enzyme stability is compromised by liquid matrices.
- Convenience Foods:Frozen and ready-to-eat meals combine multiple ingredient categories, complicating unified mitigation strategies.
Snack Foods command the largest reformulation investment pool; Bakery Products are gaining share fastest as enzyme stability expands into wheat-based applications.
End User:
End user segmentation reflects divergent technical capabilities, with integrated manufacturers deploying in-house enzymatic systems while smaller operators rely on supplier-managed programs.
- Food Manufacturers:Multinational snack and bakery producers operate captive pre-treatment lines with direct enzyme procurement from Danish and Dutch biotechnology suppliers.
- Beverage Producers:Coffee roasters and malt beverage manufacturers prioritize adsorbent technologies compatible with liquid processing infrastructure.
- Restaurants:Commercial kitchen operators lack capital for enzymatic systems and depend on supplier-formulated ingredient blends.
- Retail Chains:Private-label snack programs in Germany are consolidating procurement under co-manufacturer enzyme supply agreements with technical service attachments.
Food Manufacturers deploy the most sophisticated mitigation infrastructure; Retail Chains are converting fastest through co-manufacturer consolidation.
Distribution Channel:
Channel segmentation tracks how technical complexity and regulatory documentation requirements shape procurement relationships.
- Direct Sales:Enzyme suppliers maintain technical service teams for large food manufacturers requiring process validation and regulatory dossier support.
- Distributors:Regional chemical and ingredient distributors serve mid-tier snack producers with standardized inhibitor formulations.
- Online Retail:Small-scale bakery operators purchase point-of-use additives through specialized ingredient platforms.
- Wholesalers:Broad-line food service distributors supply restaurants with blended mitigation products.
Direct Sales capture the highest-value contracts; Distributors are expanding fastest among mid-tier manufacturers seeking technical support without dedicated supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for food processing in Germany, the Netherlands, and Belgium concentrate enzymatic acrylamide mitigation infrastructure. EFSA regulatory pressure shapes investment patterns across European snack manufacturing corridors.
Germany
Private-label snack producers in Bavaria and North Rhine-Westphalia drive enzymatic pre-treatment adoption. The country's national food safety regulator enforces strict contaminant thresholds for processed potato exports. Industrial fryer clusters around Munich and Cologne retrofit immersion-stage enzyme baths to maintain throughput compliance.
Netherlands
Biotechnology suppliers in the Randstad region anchor asparaginase production capacity for European food manufacturers. REACH authorization procedures for food-contact enzymes tighten purity documentation requirements. Major biscuit producers in Eindhoven pilot second-generation enzyme variants for wheat-based applications.
France
Fried snack portfolios in Île-de-France and Hauts-de-France convert to enzymatic mitigation at commercial scale. ANSM oversight of food-grade chemical imports shapes procurement patterns for divalent cation alternatives. Potato processing facilities near Lille deploy real-time asparagine monitoring to optimize enzyme dosing.
Belgium
Contract manufacturers serving multinational snack brands consolidate enzyme supply agreements with technical service attachments. The country's national food agency aligns enforcement with EFSA benchmark levels for acrylamide in crisps and extruded snacks. Industrial zones around Brussels and Antwerp host integrated pre-treatment lines for co-manufactured private-label programs.
United Kingdom
Commodity potato chip producers favor chemical inhibitors for legacy fryer lines facing compressed compliance timelines. The Food Standards Agency implements EFSA-aligned guidance on acrylamide mitigation for processed food exports. Manufacturing clusters in the Midlands and Yorkshire balance cost sensitivity against quarterly reformulation deadlines.
Acrylamide Reduction Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enzymatic solution providers capturing premium positioning against commodity chemical suppliers. The vendor base concentrates around Danish and Dutch biotechnology clusters serving integrated food manufacturers. Three archetypes dominate: pharmaceutical-grade enzyme specialists, diversified ingredient conglomerates with food divisions, and regional chemical distributors. Competitive moves center on regulatory dossier expansion and single-source supply bundling with technical service attachments.
Within the pharmaceutical-grade enzyme tier, Novozymes A/S and DSM N.V. exemplify suppliers leveraging toxicological documentation infrastructure for REACH market access. BASF SE anchors the diversified chemical conglomerate position. These three entities represent distinct strategic postures—pure-play biotechnology, life sciences diversification, and specialty chemicals breadth—without overlapping segment focus.
| Leading Market Players |
|---|
| BASF SE |
| Kemira Oyj |
| SNF Group |
| Ashland Global Holdings Inc. |
| DSM N.V. |
| Novozymes A/S |
| Kerry Group |
| DuPont de Nemours, Inc. |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up enzyme specialists in Denmark and the Netherlands have consolidated food-grade asparaginase production, tightening supply discipline and anchoring premium pricing for manufacturers facing EFSA compliance deadlines. This ownership concentration aligns pricing power with regulatory urgency, forcing snack producers to accept longer-term supply contracts or absorb spot-market premiums.
Pricing Analysis
Short lead-time premiums dominate enzyme procurement, with manufacturers paying 15-25% markups for just-in-time asparaginase delivery against quarterly compliance deadlines. Three-tier pricing structure across pharmaceutical-grade, food-grade, and commodity chemical tiers separates validated enzyme dossiers from unverified imports. Pricing pressure stems from REACH documentation costs transferring downstream to mid-tier snack producers. Commodity potato chip manufacturers in the United Kingdom exhibit highest price sensitivity, while multinational private-label programs in Germany absorb premiums for bundled technical service.
Supply Chain Analysis
Reverse-logistics flows for expired or temperature-compromised enzyme batches concentrate returns processing in Rotterdam and Hamburg cold-chain hubs. Active pharmaceutical ingredient manufacturers in Denmark, industrial biotechnology clusters in the Netherlands, and specialty chemical distributors in Germany anchor regional supply. Production draws from fermentation-derived asparaginase, food-grade stabilizer chemistries, and chromatography purification resins. Single-source vulnerability concentrates in Danish biotechnology suppliers, with distribution running through integrated direct-sales teams for large manufacturers and regional chemical distributors for mid-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acrylamide reduction market functions as a cost-of-compliance story where REACH authorization procedures and EFSA benchmark levels erect regulatory moats favoring dossier-complete enzyme specialists over commodity chemical suppliers.
For Market Incumbents: Cement market position by deepening captive asparaginase fermentation capacity in Randstad biotechnology corridors and pre-submission of expanded toxicological dossiers to ECHA ahead of competitor filings. Threat substitution from second-generation enzyme variants in wheat-based applications demands accelerated R&D in pH-stable formulations. Certification investment in pharmaceutical-grade enzyme infrastructure remains the critical lever against diversified chemical conglomerates lacking equivalent regulatory documentation capabilities. For New Entrants and Emerging Players: Launch via portable thermal treatment units targeting artisanal biscuit producers in Italy and Spain where equipment retrofit constraints exclude enzymatic adoption. Underpenetrated bakery segments in Southern Europe offer the most accessible white space, with point-of-use additive distribution through specialized ingredient platforms providing lowest-friction go-to-market entry. Avoid direct confrontation with established enzyme suppliers in saturated potato-chip processing corridors. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier enzyme distributors in Germany with existing REACH compliance infrastructure and stranded technical service capabilities. Long-term viability across the analysis window hinges on regulatory enforcement intensity rather than technology substitution risk. Watch EFSA maximum limit proposals and California Proposition 65 litigation volume as early signals of compliance-cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Expansion | Pre-submission of toxicological data to ECHA secures market access ahead of regulatory deadlines. |
| Enzyme-Mineral Blending | Dual-mechanism formulations capture mid-tier price points between premium enzymes and commodity chemicals. |
| Co-manufacturer Consolidation | Single-source supply agreements with technical attachments concentrate procurement power among large contract manufacturers. |
| Second-Generation Enzyme R&D | pH-stable asparaginase variants unlock wheat-based bakery applications previously excluded from enzymatic intervention. |
| Real-Time Monitoring Integration | Chromatography equipment bundling with enzyme supply contracts deepens customer switching costs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across food safety officers at snack manufacturers, procurement leads at contract manufacturers, regulatory affairs managers at enzyme suppliers, and technical directors at ingredient distributors. EFSA risk assessment documents, REACH authorization dossiers, FDA guidance publications, and national food agency enforcement records provided secondary validation. Bottom-up volume modeling and top-down value reconciliation triangulated market estimates across the analysis window.
Data-stream reconciliation integrated shipment volumes from Dutch and Danish biotechnology exporters, production capacity disclosures from specialty chemical manufacturers, and import records from German and French customs authorities. Segmentation modeling tracked enzymatic, chemical, and thermal treatment modalities; snack food, bakery, beverage, and convenience food applications; and direct sales versus distributor channel structures. CAGRs derived from regression analysis of historical adoption curves against regulatory enforcement intensity, with forecast inputs including EFSA maximum limit proposal timelines and enzyme cost curve projections.
Regulatory enforcement delays, enzyme production capacity constraints, and alternative mitigation technology breakthroughs are the dominant revision risks to modeled outcomes. Practitioners should monitor EFSA maximum level adoption schedules, REACH authorization processing timelines, and second-generation enzyme stability claims for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
United Kingdom Anti Caking Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Lipase Food Enzymes Market
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Argentina Gellan Gum Market