
 North America Food Starch Market | 2026-2036
North America Food Starch Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Starch Market Analytics
The U.S. EPA's renewable fuel standards and parallel sustainability mandates from major quick-service restaurant chains are broadening demand for non-GMO and organically sourced food starches across North America. Ingredion Incorporated leverages its ingredient innovation centers in Illinois and Canada to develop clean-label texturizers for plant-based meat alternatives. Cargill Incorporated anchors regional supply security through its vertically integrated corn wet milling network spanning Minnesota, Nebraska, and Ontario. Archer Daniels Midland Company competes on fermentation-derived specialty starches for industrial food processing customers.
Food starch encompasses carbohydrate polymers extracted from cereal grains, tubers, and legumes through wet milling, drying, and physical or enzymatic modification to achieve specific viscosity, gel strength, and freeze-thaw stability profiles for commercial food manufacturing. Modified starch dominates value generation due to its engineered functionality in high-shear processing environments, while resistant starch captures accelerated growth from gut-health positioning in functional food formulations. Native starch from corn sustains volume leadership across the baking and sauces applications where cost efficiency and neutral flavor remain paramount.
The U.S. FDA governs starch labeling and health claim substantiation, while Health Canada and PMRA coordinate cross-border standards for genetically modified organism disclosure and pesticide residue limits in starch crops. The USDA's BioPreferred program and Canada's Clean Fuel Regulations indirectly shape procurement criteria by rewarding bio-based processing inputs. Stakeholders must monitor pending FDA guidance on resistant starch fiber quantification methods and provincial GMO labeling harmonization between Ontario and Quebec to anticipate reformulation requirements and avoid supply chain disruption.
Market Dynamics
Clean-label reformulation mandates from major quick-service restaurant chains are restructuring procurement priorities across the North American food starch value chain, forcing manufacturers to pivot from commodity modified starches toward native and resistant starch alternatives.
Growth Catalysts
- Resistant starch fiber reclassification:The U.S. FDA's updated guidance on dietary fiber classification is accelerating incorporation into processed foods targeting digestive health claims.
- Plant-based meat texturization:Clean-label adoption across the alternative protein sector is broadening demand for native corn starches that replicate animal fat mouthfeel without chemical modification.
- Corn processing cluster proximity:Demand concentrates in the U.S. Midwest where Iowa and Illinois wet milling infrastructure anchors regional supply security for food-grade derivatives.
Market Restraints
- Input cost volatility:Corn futures price swings and fertilizer cost spikes transmit directly into native starch production economics, squeezing margin predictability for contract manufacturers.
- Supply concentration risk:The U.S. corn belt's dominance in food-grade starch feedstock creates geographic vulnerability to drought-induced yield compression and rail logistics bottlenecks.
- Enzymatic modification limits:Current industrial biocatalysts cannot achieve the full viscosity spectrum required for high-shear extrusion applications without chemical cross-linking.
Strategic Opportunities
- Canadian organic starch cultivation:Saskatchewan and Manitoba prairie expansion offers untapped non-GMO corn and pulse starch sourcing for clean-label export markets.
- Resistant starch gut-health positioning:Functional food formulations targeting prebiotic benefits represent white-space growth beyond traditional thickening applications.
- BioPreferred program procurement:The USDA's federal purchasing preference for bio-based processing inputs creates mandated demand pull from institutional foodservice channels.
Industry Challenges
- Clean-label reformulation timelines:Removing modified starches while maintaining freeze-thaw stability and shear resistance requires 18-24 month product development cycles that strain R&D bandwidth.
- Cross-border GMO disclosure harmonization:Divergent provincial labeling requirements between Ontario and Quebec complicate unified packaging strategies for pan-Canadian distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Starch Market |
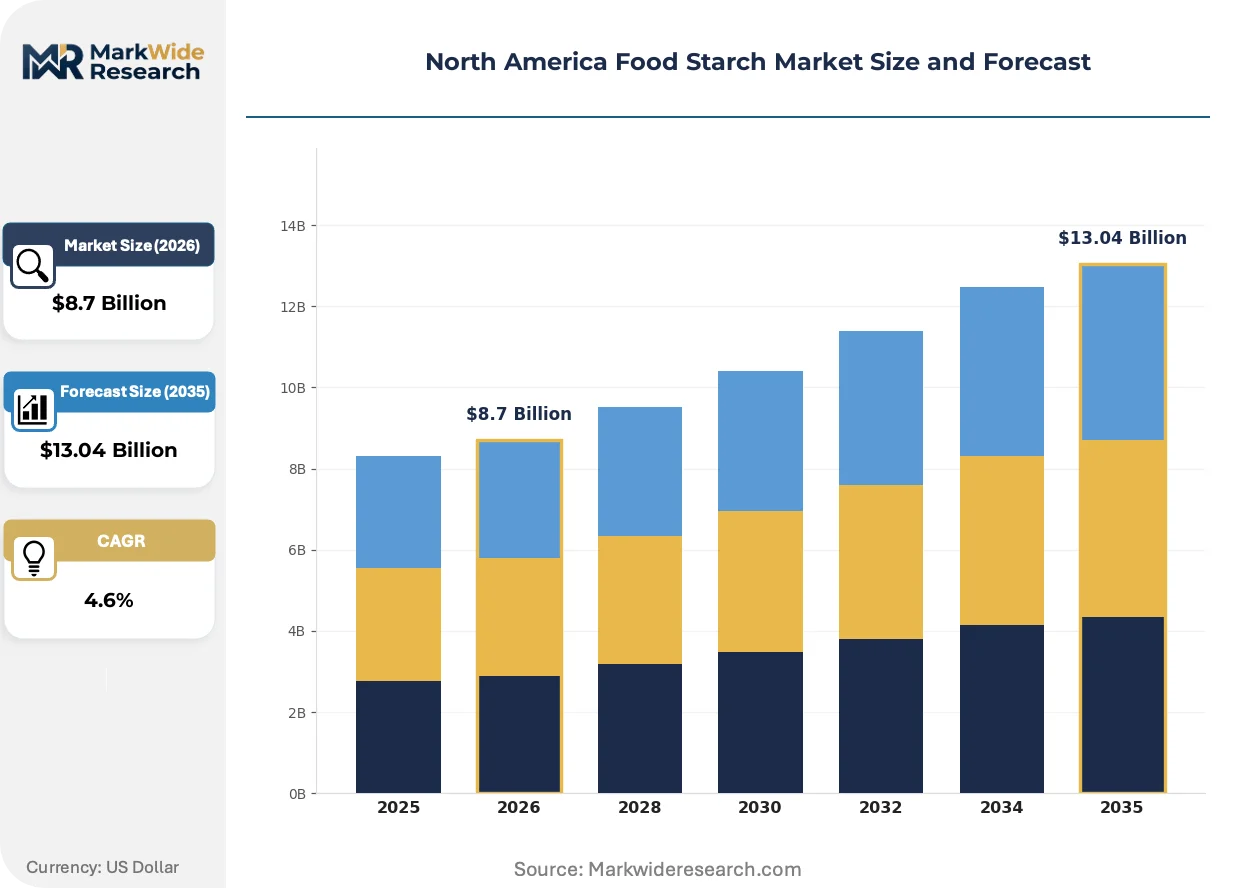
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Native Starch, Resistant Starch, Gelatinized Starch Application: Baking, Sauces, Confectionery, Dairy Source: Corn, Potato, Tapioca, Wheat End User: Food Processing, Retail, Hospitality, Industrial |
| Companies Covered | Archer Daniels Midland Company, Ingredion Incorporated, Cargill Incorporated, AGRANA Beteiligungs-AG, Tate & Lyle, Roquette Frères, Grain Processing Corporation, Emsland Group, MGP Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Starch Market Evolving Landscape
Physical and enzymatic starch modification techniques are converging with precision fermentation to unlock functionality previously achievable only through chemical processing, compressing the traditional trade-off between clean-label positioning and industrial performance.
Enzymatic debranching technology is modularizing how manufacturers achieve specific viscosity profiles without resorting to chemical cross-linking agents. Large-scale bakery and sauce producers in the U.S. Southeast are piloting these systems at commercial scale. The approach is modularizing equipment investment decisions, allowing plants to reconfigure output specifications through biocatalyst swaps rather than dedicated process lines.
The U.S. FDA's pending resistant starch fiber quantification guidance is forcing reformulation transparency across the functional food segment. Manufacturers must substantiate digestive health claims with validated analytical methods rather than supplier certificates. The baking sector is responding by building in-house resistant starch testing capability to preempt compliance gaps.
Quick-service restaurant chains are consolidating starch procurement through direct supplier partnerships that bypass traditional ingredient distributors. This channel compression is most visible in the U.S. Southwest where regional chains are negotiating multi-year native starch supply agreements with Iowa wet millers, displacing the historical role of foodservice brokers in price discovery and logistics coordination.
North America Food Starch Market Segmentation
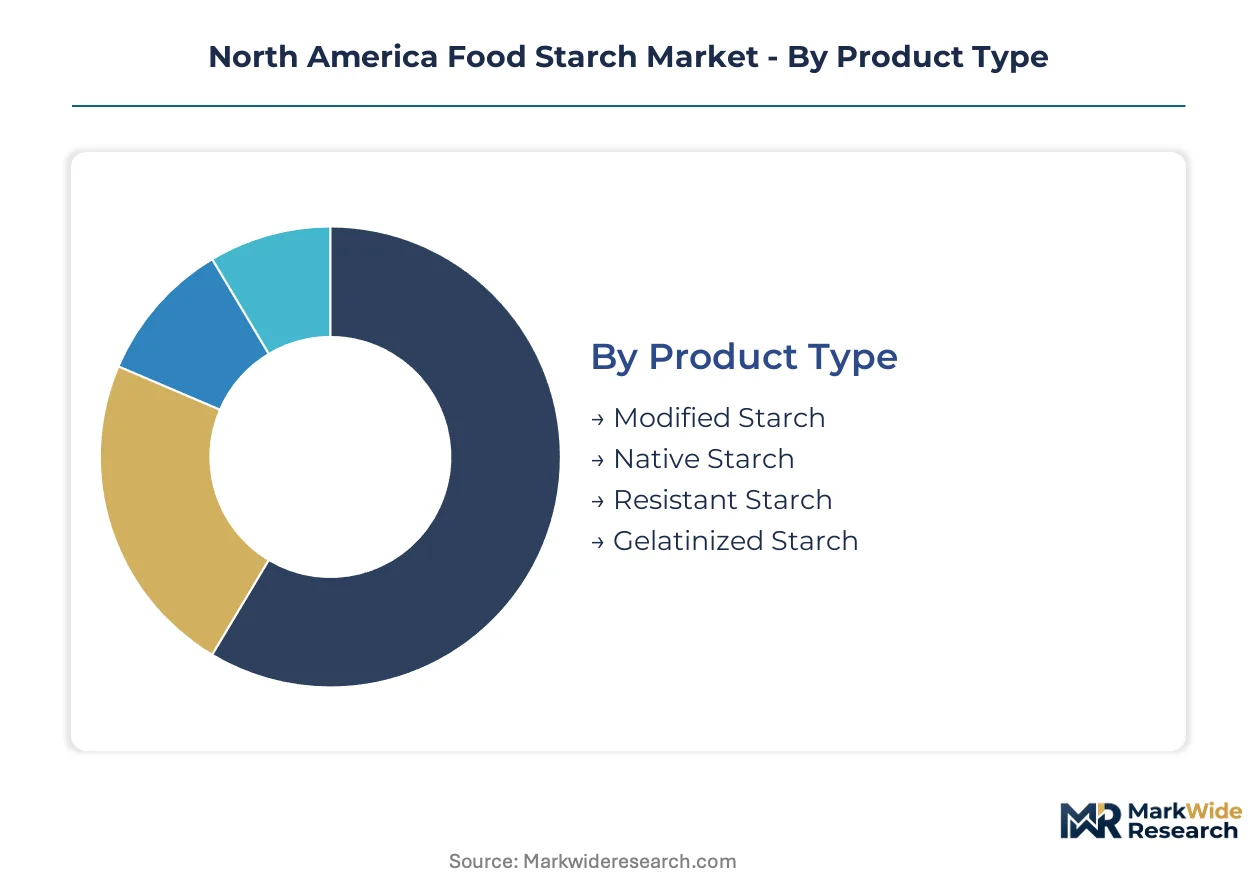
Food starch segmentation reveals divergent capital requirements across processing technologies, with enzymatic and chemical modification infrastructure demanding substantially higher upfront investment than native extraction operations. Understanding these cost structures helps manufacturers align capacity decisions with end-use profitability and regulatory exposure.
Product Type:
Modified starch commands the heaviest capital burden through cross-linking reactors and continuous cooking systems, while native extraction requires simpler wet milling infrastructure.
- Modified Starch:Chemically or physically altered polymers engineered for specific viscosity, stability, and texture profiles under high-shear industrial conditions. Demand concentrates in U.S. Southeast baking operations where extended shelf life and freeze-thaw resistance justify premium positioning. The U.S. FDA's evolving clean-label scrutiny is forcing reformulation timelines that strain R&D amortization across multi-year equipment cycles.
- Native Starch:Unmodified carbohydrate polymers extracted through conventional wet milling, drying, and classification without structural alteration. Sauces and gravies in the U.S. Midwest absorb the largest volumes where cost efficiency and neutral flavor profiles dominate procurement specifications. Corn processing clusters in Iowa and Illinois provide feedstock proximity that compresses logistics costs for regional contract manufacturers.
- Resistant Starch:Enzyme-resistant fractions delivering prebiotic fiber functionality and reduced glycemic impact in functional food formulations.
- Gelatinized Starch:Pre-cooked polymers offering instant thickening without heat activation, serving ready-to-eat and cold-process applications.
Most installed capacity flows through modified starch. Expansion is steepest in resistant starch.
Application:
Volume concentration and margin structure diverge sharply across end-use categories, with industrial-scale baking commanding throughput efficiencies that smaller segments cannot replicate.
- Baking:Bread, pastry, and cracker formulations leveraging starch for crumb structure, moisture retention, and shelf-life extension. Large commercial bakeries in the U.S. Southeast and Texas corridor drive specification standards, with clean-label mandates from quick-service restaurant chains forcing native starch substitution for chemically modified alternatives.
- Sauces:Gravies, dressings, and prepared sauces requiring controlled viscosity and freeze-thaw stability. U.S. Midwest food processing corridors concentrate demand where corn-derived native starches dominate cost-sensitive institutional and retail channels.
- Confectionery:Gelling, molding, and anti-staling applications in candies and chocolate coatings.
- Dairy:Yogurt stabilization, ice cream texture modification, and processed cheese functionality.
Baking absorbs the largest production volumes. Dairy is climbing the fastest as plant-based alternatives proliferate.
Source:
Feedstock selection locks manufacturers into specific agricultural supply geographies and processing chemistries that resist rapid switching.
- Corn:Dominant cereal grain feedstock processed through wet milling into dextrose, gluten, and food-grade starch fractions. Iowa and Illinois processing infrastructure anchors North American supply security, with varietal selection optimized for high-amylose or waxy specifications depending on end-use viscosity requirements.
- Potato:Tuber-derived starch delivering superior clarity and neutral flavor for premium sauce and confectionery applications.
- Tapioca:Cassava root extraction serving allergen-free and non-GMO positioning in clean-label formulations.
- Wheat:Cereal grain source providing A-starch and B-starch fractions with distinct protein contamination profiles.
Corn commands the installed wet milling base. Tapioca is expanding most quickly on clean-label export demand.
End User:
Customer scale and technical sophistication create tiered service requirements that fragment supplier strategies across the value chain.
- Food Processing:Industrial manufacturers of packaged goods, bakery products, and prepared meals requiring specification-grade starches with batch-to-batch consistency. Large Midwest and Southeast processors negotiate direct supply agreements that bypass traditional ingredient distribution, compressing price discovery timelines and logistics coordination.
- Retail:Private-label and branded consumer product companies sourcing starch for home-use baking mixes and thickening agents.
- Hospitality:Foodservice operators, restaurant chains, and institutional kitchens using starch in prepared sauces and baking applications.
- Industrial:Non-food applications including paper sizing, adhesives, and textile processing.
Food processing channels the majority of volume. Retail is gaining share fastest on private-label expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial corn wet milling scaled first across the U.S. Midwest during the early twentieth century, establishing processing infrastructure that now defines North American food starch supply geography. Canadian prairie expansion and Mexican maize cultivation subsequently built out regional feedstock alternatives.
United States
Clean-label mandates from quick-service restaurant chains are restructuring procurement toward native and resistant starch alternatives. The FDA's updated dietary fiber classification guidance accelerates resistant starch incorporation into processed foods targeting digestive health claims. Iowa and Illinois wet milling clusters anchor regional supply security for food-grade derivatives.
Canada
Saskatchewan and Manitoba prairie expansion offers untapped non-GMO corn and pulse starch sourcing for clean-label export markets. Health Canada and PMRA coordinate cross-border standards for genetically modified organism disclosure and pesticide residue limits. Ontario processing infrastructure concentrates near the U.S. border to leverage integrated North American distribution networks.
Mexico
Domestic maize cultivation supports growing native starch extraction for regional sauces and baking applications. The Secretariat of Economy enforces labeling harmonization with U.S. trade partners under USMCA provisions. Jalisco and Bajío Region processing corridors develop specialty starch fractions for confectionery and dairy exports.
North America Food Starch Market Competitive Landscape
Capital-heavy wet millers compete with asset-light specialty starch formulators across divergent margin structures and capital intensity requirements. The vendor base concentrates around integrated agribusiness conglomerates with captive corn supply and dedicated modification infrastructure. Three archetypes dominate: vertically integrated grain processors with fermentation capabilities, regional wet milling specialists serving foodservice channels, and precision fermentation startups targeting resistant starch functionality. Competitive dynamics center on backward integration into seed genetics and forward partnerships with quick-service restaurant chains.
Among U.S.-based integrated processors, Archer Daniels Midland Company, Ingredion Incorporated, and Cargill Incorporated exemplify the capital-intensive archetype with Midwest wet milling networks. These entities occupy positions spanning native extraction through chemically modified and enzymatically tailored derivatives. European-headquartered specialists including AGRANA Beteiligungs-AG and Tate & Lyle represent the formulation-driven tier, emphasizing clean-label texturizers and resistant starch portfolios. Roquette Frères anchors the pulse-derived and non-GMO positioning vector with pea and potato starch alternatives.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Cargill Incorporated |
| AGRANA Beteiligungs-AG |
| Tate & Lyle |
| Roquette Frères |
| Grain Processing Corporation |
| Emsland Group |
| MGP Ingredients |
| Others |
Value Network & Pricing Analysis
Corn futures volatility transmits directly through native starch contract pricing, with Iowa and Illinois wet millers indexing quarterly adjustments to CBOT benchmarks while modified starch premiums absorb enzymatic biocatalyst cost swings through longer-term offtake agreements with U.S. Southeast baking conglomerates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates clean-label certified resistant starch from chemically modified industrial grades and commodity native extracts. Price differentiation rests on organic certification tier and volume scale, with quick-service restaurant chains commanding lowest unit costs through direct miller partnerships. Cost compression in standard modified grades is intensifying because enzymatic alternatives erode chemical cross-linking premiums. Institutional foodservice channels exhibit highest price sensitivity, while functional food manufacturers targeting gut-health claims accept premium positioning.
Supply Chain Analysis
USDA Organic and Non-GMO Project certification gating restricts supplier qualification to Iowa, Illinois, and Indiana wet milling facilities with verified traceability systems. Raw material flows draw from the U.S. corn belt, Canadian prairie non-GMO expansion, and Mexican Jalisco cultivation corridors. Single-source vulnerability concentrates in rail-dependent logistics from Midwest processing clusters to coastal export terminals. Distribution runs through direct miller-processor relationships that displace traditional ingredient broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America food starch market represents a late-cycle quality story as clean-label mandates from quick-service restaurant chains displace commodity modified starches with premium native and resistant alternatives.
For Market Incumbents: Acquire Saskatchewan and Manitoba organic corn cultivation assets to secure non-GMO feedstock positioning ahead of Canadian prairie infrastructure buildout. Anchor Midwest wet milling capacity with backward integration into high-amylose seed genetics that lock in proprietary resistant starch functionality. Defend against precision fermentation startups by accelerating enzymatic modification R&D to compress clean-label reformulation timelines below 18 months. For New Entrants and Emerging Players: Begin with resistant starch gut-health formulations targeting functional food white space beyond traditional thickening applications. Canadian organic starch cultivation offers the most penetrable geography given underdeveloped prairie processing infrastructure and export demand pull. Pursue direct supply agreements with regional quick-service chains in the U.S. Southwest that seek native starch alternatives to modified industrial grades. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale enzymatic modification specialists lack capital to scale clean-label capacity against integrated agribusiness conglomerates. Long-term viability favors processors with captive organic feedstock and FDA-resistant starch fiber claim substantiation capability. Watch for inflection where FDA finalizes resistant starch quantification guidance and triggers reformulation compliance spending spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Seed Genetics | Captive high-amylose corn supply locks in resistant starch functionality premiums for clean-label positioning. |
| Enzymatic Modification Capacity Expansion | Commercial-scale biocatalyst deployment bridges clean-label mandates with industrial shear resistance requirements. |
| Direct Quick-Service Restaurant Partnerships | Channel compression bypasses ingredient brokers and secures multi-year native starch offtake commitments. |
| Canadian Prairie Processing Infrastructure | Saskatchewan and Manitoba facilities capture non-GMO export demand with integrated North American distribution. |
| In-House Resistant Starch Testing Capability | FDA compliance readiness preempts fiber claim substantiation gaps before guidance finalization. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market through structured interviews with wet milling plant managers, quick-service restaurant procurement directors, food processing R&D leads, and regulatory affairs specialists at starch modification facilities. Secondary validation draws from USDA crop production reports, FDA guidance documents, Health Canada regulatory filings, and U.S. customs trade data. Bottom-up capacity modeling triangulates against top-down demand segmentation across product type, application, and end-user channels.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions include product type tier, source crop, application category, and end-user scale. CAGRs derive from installed capacity utilization curves, corn futures price trend assumptions, and clean-label substitution elasticity estimates. Industry-specific inputs incorporate wet milling energy cost structures and enzymatic biocatalyst commercialization timelines.
Caveats apply where FDA resistant starch fiber quantification guidance, drought-induced corn yield compression, or cross-border GMO labeling harmonization failures could materially shift the outlook. Forecasts embed assumptions about quick-service chain clean-label adoption velocity and prairie organic cultivation expansion rates. A model refresh is warranted upon material change in FDA guidance finalization or Midwest rail logistics capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
Instant Fat Powder Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Europe Food Micronized Salt Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Food Grade Carrageenan Market