
 Etidronic Acid Market | 2026-2036
Etidronic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Etidronic Acid Market Foresight
Phosphonate alternatives to traditional polyphosphate scale inhibitors is consolidating material economics across industrial water circuits. BASF SE leverages captive ethylene amine supply to anchor European etidronate production. Italmatch Chemicals S.p.A. specializes in phosphonate blends for cooling tower applications. Shandong IRO Chelating Chemical Co., Ltd. dominates bulk powder exports through integrated phosphorus processing in Shandong Province.
Etidronic acid (1-hydroxyethane-1,1-diphosphonic acid, HEDP) functions as a chelating agent and scale inhibitor with thermal stability exceeding 200°C in alkaline boiler water conditions, manufactured through phosphorous acid acetaldehyde condensation. The compound sequesters calcium and magnesium ions to prevent carbonate and sulfate precipitation in circulating water systems. Powder formulations occupy the largest volume share due to handling efficiency in bulk industrial dosing, while liquid concentrates gain traction in automated feed systems. Water treatment applications lead value generation given replacement cycles in power generation and oilfield injection facilities, whereas pharmaceutical-grade material commands premium positioning through USP and EP certification requirements.
EPA effluent limitation guidelines constrain phosphonate discharge concentrations in US industrial wastewater, compelling end-users toward higher-purity etidronic acid grades with reduced orthophosphate residuals. REACH registration under ECHA mandates full toxicological dossiers for phosphonate imports into the European Economic Area, raising compliance costs for non-EU suppliers. China's MEE enforces stricter total phosphorus limits in surface water discharge standards, accelerating domestic producer consolidation. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration investments with regional enforcement trajectories.
Market Dynamics
Phosphonate discharge thresholds are tightening across major industrial jurisdictions, forcing etidronic acid producers to reformulate for lower orthophosphate residuals while maintaining scale inhibition performance in high-temperature boiler circuits.
Growth Catalysts
- Desalination infrastructure:State-backed projects in China are expanding procurement of chelating agents for membrane protection in reverse osmosis facilities.
- REACH compliance investments:European water treatment operators are upgrading to higher-purity etidronic acid grades to meet ECHA-mandated toxicological dossier requirements.
- Scale-control automation:Power generation facilities are deploying liquid concentrate feed systems that favor etidronic acid over traditional polyphosphate dosing.
Market Restraints
- Phosphorus feedstock volatility:Yellow phosphorus price swings in Guizhou and Yunnan provinces compress margins for powder-grade manufacturers.
- Substitution pressure from polyaspartic acid:Biodegradable alternatives are capturing share in cooling tower applications where discharge permits restrict phosphonate loading.
- EPA effluent guidelines:US industrial wastewater discharge limits on phosphonate concentrations constrain end-use expansion in metal finishing and oilfield sectors.
Strategic Opportunities
- Pharmaceutical-grade certification:USP and EP certification requirements create premium positioning for producers capable of meeting injectable-grade purity standards.
- Integrated phosphorus processing:Captive phosphorous acid production in Shandong Province enables cost-advantaged bulk powder exports to Southeast Asian water treatment markets.
- MEE surface water standards:China's stricter total phosphorus limits are accelerating consolidation among domestic etidronic acid producers with compliant effluent treatment.
Industry Challenges
- REACH registration timelines:Full toxicological dossier preparation for ECHA extends product launch cycles by 18-24 months for non-EU suppliers.
- Legacy system integration:Automated dosing infrastructure in aging power plants requires retrofit compatibility testing for liquid concentrate formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Etidronic Acid Market |
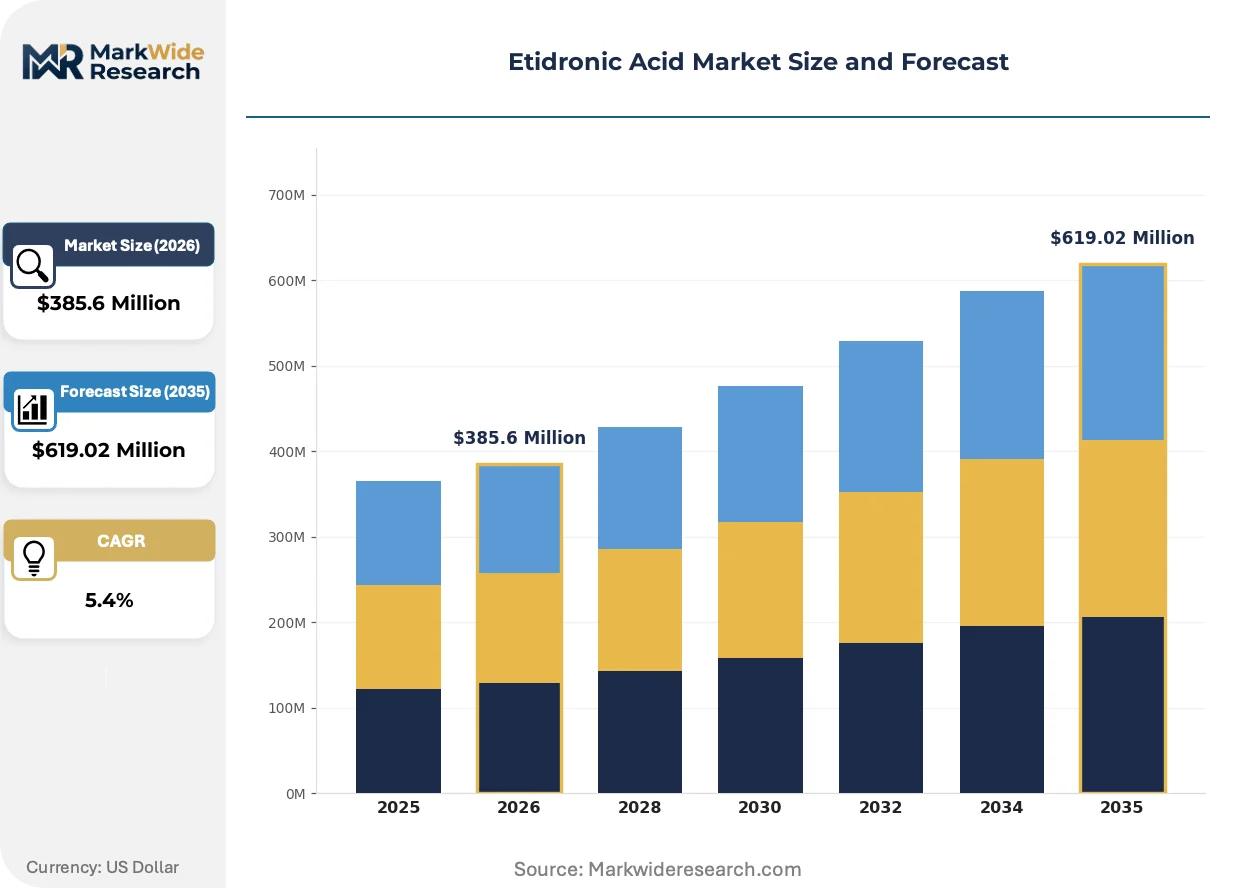
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Liquid, Tablets Application: Water Treatment, Agriculture, Pharmaceuticals, Industrial Use End User: Manufacturers, Hospitals, Research Institutions, Agricultural Sector Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | BASF SE, Akzo Nobel N.V., Italmatch Chemicals S.p.A., Shandong IRO Chelating Chemical Co., Ltd., Aquapharm, Zouping Dongfang Chemical Industry Co., Ltd., Uniphos Chemicals, Shandong Taihe Technologies Co., Ltd., Xi'An Rejee Industry Development, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Etidronic Acid Market Shifts & Advancements
Formulation chemistry and regulatory compliance frameworks are diverging across industrial water treatment markets, creating distinct technical specifications for etidronic acid grades by end-use vertical and geography.
High-purity liquid concentrates is overtaking powder formulations in automated feed systems at combined-cycle power plants and municipal desalination facilities. These installations prioritize continuous dosing precision over bulk handling efficiency. The shift is compressing demand for traditional powder grades in premium applications while expanding service-contract revenue for chemical management providers.
REACH registration under ECHA now mandates full substance evaluation for phosphonate imports into the European Economic Area. Industrial water treatment operators face reformulation costs or supplier switching to maintain compliance. German cooling tower applications are most affected, with facility managers prioritizing suppliers with established EU-based registration dossiers.
Long-term chemical management agreements are replacing spot procurement in oilfield water injection facilities. Major operators in the Permian Basin and North Sea are bundling etidronic acid supply with performance guarantees on scale inhibition metrics. This unbundles traditional distributor relationships and concentrates purchasing authority with integrated service providers capable of field-level technical support.
Etidronic Acid Market Segmentation
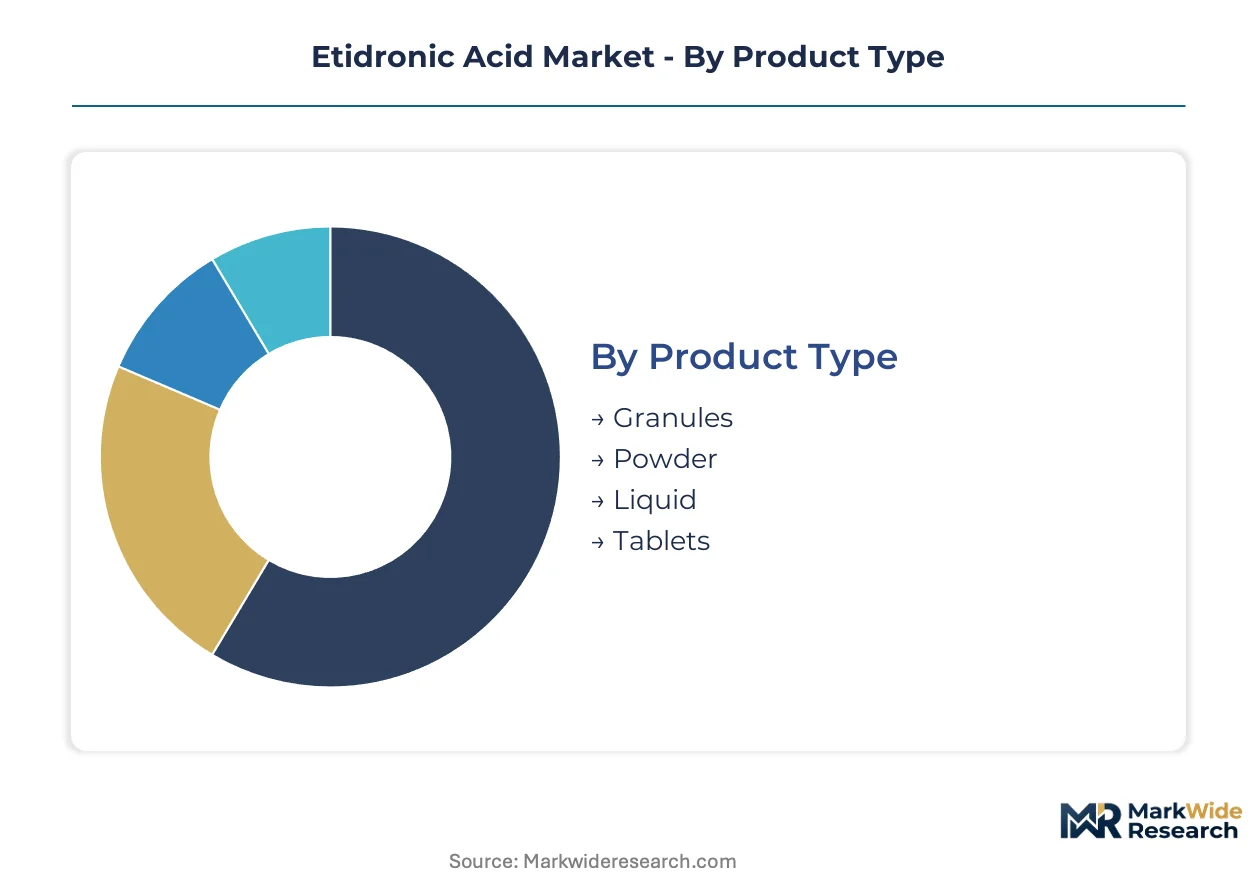
Segmentation in the etidronic acid market reflects divergent purity requirements, handling logistics, and regulatory compliance burdens across end-use verticals. Product form and application specifications determine margin structures and customer switching costs.
Product Type:
Standardization dominates bulk industrial procurement, while pharmaceutical and precision dosing applications demand customized formulation parameters.
- Powder:Dry crystalline form with 90% minimum active content serves bulk water treatment facilities through pneumatic conveying systems. Demand concentrates in Chinese desalination projects where Shandong Province producers supply membrane protection chemicals for reverse osmosis trains.
- Liquid:Aqueous concentrates at 50-60% concentration enable automated feed systems in power generation and oilfield injection facilities. Expansion concentrates in combined-cycle plants retrofitting legacy polyphosphate dosing infrastructure for continuous precision delivery.
- Granules:Free-flowing agglomerated particles reduce dust exposure during manual handling in agricultural fertilizer blending operations.
- Tablets:Compressed solid dosage forms target small-scale water treatment applications requiring pre-measured dosing without liquid handling equipment.
Most installed capacity flows through powder formulations. Expansion is steepest in liquid concentrates.
Application:
Volume scales inversely with purity requirements, creating distinct margin tiers across industrial, agricultural, and pharmaceutical end-uses.
- Water Treatment:Scale inhibition in cooling towers, boilers, and reverse osmosis systems consumes the largest volume share. Municipal procurement in China and industrial facility upgrades in Germany drive specification tightening for lower orthophosphate residuals.
- Pharmaceuticals:USP and EP certified grades for injectable formulations and diagnostic reagents command premium positioning through batch-level traceability documentation.
- Agriculture:Chelant applications in micronutrient fertilizers and irrigation system scale prevention serve plantation-scale operations in Southeast Asia.
- Industrial Use:Metal surface treatment, textile processing, and oilfield corrosion inhibition span diverse technical specifications with fragmented customer concentration.
Water treatment absorbs the majority of production volume. Pharmaceuticals generates the highest margin per kilogram.
End User:
Procurement sophistication varies from commodity tendering in agricultural cooperatives to validated supplier audits in hospital pharmacy departments.
- Manufacturers:Industrial formulators and chemical blenders purchase bulk grades for downstream product integration, with qualification cycles spanning 12-18 months for pharmaceutical customers.
- Agricultural Sector:Plantation operators and fertilizer compounders prioritize cost efficiency and bulk logistics over certification documentation.
- Hospitals:Pharmacy and clinical laboratory procurement departments enforce GMP-compliant supply chains with mandatory supplier quality agreements.
- Research Institutions:Academic and government laboratories purchase small volumes of high-purity grades through specialized chemical distributors.
Manufacturers represent the dominant demand channel. Hospitals impose the most stringent qualification requirements.
Distribution Channel:
Channel selection tracks order size, technical service requirements, and geographic proximity to production centers.
- Distributors:Regional chemical distributors hold inventory positions for mid-volume industrial customers requiring technical support and just-in-time delivery coordination.
- Direct Sales:Producer-customer relationships serve large water treatment operators and pharmaceutical manufacturers with dedicated account management and formulation customization.
- Online:E-procurement platforms capture small-laboratory and maintenance-repair-operations demand through catalog-based ordering with credit card settlement.
- Retail:Limited presence in agricultural supply cooperatives and specialty chemical storefronts serving small-scale water treatment installations.
Distributor networks handle the majority of transaction volume. Direct sales is expanding fastest among pharmaceutical and large industrial accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province anchors production concentration through integrated phosphorus processing clusters serving membrane protection chemical demand from state-backed desalination infrastructure. Municipal procurement cycles and discharge threshold tightening are reshaping specification requirements across four major demand centers.
China
State-backed reverse osmosis facility construction drives chelant procurement volume in coastal provinces. MEE surface water discharge standards enforce stricter total phosphorus limits, accelerating domestic producer consolidation. Shandong Province producers supply bulk powder exports through captive phosphorous acid production integrated with membrane protection chemical manufacturing.
Germany
Cooling tower operators in the Ruhr industrial corridor upgrade to higher-purity etidronic acid grades. ECHA REACH registration mandates full toxicological dossiers for phosphonate imports, extending qualification cycles for non-EU suppliers. BASF SE leverages captive ethylene amine supply from Ludwigshafen to anchor European etidronate production serving industrial water circuits.
United States
Permian Basin oilfield water injection facilities bundle etidronic acid supply with performance guarantees on scale inhibition metrics. EPA effluent limitation guidelines constrain phosphonate discharge concentrations in industrial wastewater, compelling end-users toward higher-purity grades. Texas and Louisiana chemical management providers consolidate purchasing authority through long-term service contracts.
India
Power generation facility upgrades in Gujarat and Maharashtra deploy automated feed systems favoring liquid concentrate formulations. Central Pollution Control Board enforcement of wastewater discharge standards tightens procurement specifications for cooling tower applications. Domestic formulators in the Mumbai-Pune industrial belt qualify suppliers through 12-18 month certification cycles for bulk industrial integration.
Saudi Arabia
Desalination capacity expansion in the Eastern Province drives chelating agent demand for thermal and membrane-based water production. The national water regulator enforces discharge quality standards that elevate procurement requirements for scale inhibition chemicals. Jubail Industrial City clusters integrate etidronic acid into process water treatment for petrochemical complexes.
Etidronic Acid Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and regulatory compliance capabilities. The vendor base separates into integrated phosphorus processors, specialty phosphonate blenders, and pharmaceutical-grade certification specialists. Three archetypes dominate: captive feedstock operators, regional distribution-anchored formulators, and purity-tier certification players. Capacity expansion and REACH registration dossier preparation represent the dominant competitive moves as qualification barriers rise.
Among European-based chemical conglomerates, BASF SE exemplifies the integrated archetype through captive ethylene amine supply chains. Italmatch Chemicals S.p.A. occupies a position within the specialty phosphonate blending tier, while Shandong IRO Chelating Chemical Co., Ltd. anchors the bulk powder export segment through Shandong Province production concentration. These three entities represent distinct strategic positioning vectors: backward integration, application-specific formulation, and scale-driven geographic export.
| Leading Market Players |
|---|
| BASF SE |
| Akzo Nobel N.V. |
| Italmatch Chemicals S.p.A. |
| Shandong IRO Chelating Chemical Co., Ltd. |
| Aquapharm |
| Zouping Dongfang Chemical Industry Co., Ltd. |
| Uniphos Chemicals |
| Shandong Taihe Technologies Co., Ltd. |
| Xi'An Rejee Industry Development |
| Others |
Supply & Pricing Matrix
Captive phosphorous acid production in Shandong Province anchors both supply security and pricing power for Chinese etidronic acid exporters, insulating integrated producers from yellow phosphorus volatility in Guizhou and Yunnan while compressing margins for non-integrated competitors dependent on spot feedstock markets.
Pricing Analysis
Yellow phosphorus cost pass-through dominates powder-grade pricing, with Shandong integrated producers absorbing volatility more effectively than non-captive competitors. Three-tier pricing structure across pharmaceutical-grade, industrial high-purity, and standard bulk tiers reflects certification burden and orthophosphate residual specifications. Pricing pressure stems from polyaspartic acid substitution in cooling tower applications where discharge permits restrict phosphonate loading. Agricultural fertilizer blenders exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize batch traceability over unit economics.
Supply Chain Analysis
Freight cost differentials favor liquid concentrate distribution within 500-kilometer radii of production hubs, while powder formulations tolerate longer-haul logistics to Southeast Asian water treatment markets. Supply concentrates in China, Germany, and the United States, with Shandong Province, Ludwigshafen, and Texas Gulf Coast serving as respective manufacturing anchors. Feedstock dependence spans phosphorous acid, acetaldehyde, and ethylene amine inputs. Single-source vulnerability runs through Chinese yellow phosphorus processing. Distribution runs through regional chemical distributors for mid-volume industrial accounts, with direct sales expanding among pharmaceutical and large water treatment operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Etidronic acid functions as a stable compounder, with municipal water infrastructure replacement cycles and tightening phosphorus discharge regulations providing durable demand tailwinds across industrial jurisdictions.
For Market Incumbents: Hedge against polyaspartic acid substitution by accelerating REACH registration dossiers for premium phosphonate blends in German cooling tower applications. Deepen backward integration into phosphorous acid production to defend margin position against Guizhou feedstock volatility. Prioritize liquid concentrate capacity additions in Texas and Louisiana to capture Permian Basin service contract bundling trends.
For New Entrants and Emerging Players: The mid-tier pricing gap between USP-certified pharmaceutical grades and standard industrial powder creates white-space opportunity for regional formulators in India and Saudi Arabia. Target power generation facility retrofits in Gujarat and Maharashtra where automated feed system deployment outpaces qualified local supply. Pursue toll manufacturing arrangements with Shandong producers to bypass 18-24 month ECHA qualification timelines for European market entry.
For Investors and Strategic Acquirers: Roll-up economics work for regional phosphonate blenders because REACH registration barriers prevent new competitor entry while customer switching costs extend contract durations. Five-to-ten year viability hinges on consolidation among domestic Chinese producers with MEE-compliant effluent treatment. Monitor EPA effluent guideline enforcement intensity as inflection indicator for US market premium-grade pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Dossier Completion | ECHA compliance unlocks German cooling tower procurement channels for non-EU suppliers. |
| Backward Integration into Phosphorous Acid | Captive feedstock production in Shandong insulates margin from Guizhou price swings. |
| Liquid Concentrate Capacity Expansion | Automated dosing system compatibility captures power generation retrofit demand. |
| Pharmaceutical-Grade Certification Investment | USP and EP batch traceability commands premium positioning in injectable formulations. |
| Long-Term Service Contract Bundling | Performance guarantees on scale inhibition metrics consolidate Permian Basin purchasing authority. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with water treatment procurement managers, phosphonate plant operations directors, pharmaceutical quality assurance leads, and ECHA regulatory consultants with secondary validation against customs trade data, SEC chemical company filings, MEE discharge standard publications, and ACC industrial water treatment reports. Bottom-up volume modeling from individual facility procurement cycles triangulated against top-down market sizing from production capacity assessments.
Comparable historical periods anchored the projection horizon, with segmentation dimensions spanning product form, application vertical, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from facility-level replacement cycle analysis and infrastructure investment pipeline tracking across desalination, power generation, and oilfield water injection end-uses. Forecast inputs incorporated phosphonate discharge threshold tightening trajectories and polyaspartic acid substitution elasticity estimates.
Caveats apply where EPA effluent guideline enforcement intensity, REACH registration timeline extensions, or yellow phosphorus supply disruptions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Methanol Market
Chemicals
Betaine Market
Chemicals
Global Diphenylmethane Diisocyanate Market
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
Valeryl Chloride Market
Chemicals
Global Lactate Salts Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Sodium Cyanide Market
Chemicals
Flooring Chemicals Market
Chemicals
Hydrogen Fluoride Pyridine Market
Chemicals
Antiozonant Market
Chemicals
Nonanoic Acid Market
Chemicals
Penoxsulam Market
Chemicals
US Methanol Market
Chemicals
Potassium Iodide Market
Chemicals
Chemical As a Service Market