
 North America Humic Acid Market | 2026-2036
North America Humic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Humic Acid Market Analysis
The USDA National Organic Program is pivoting humic acid demand toward certified input suppliers across North American agricultural supply chains. Black Earth Humic LP leverages its Canadian peat-derived extraction capacity to anchor wholesale supply into Midwest fertilizer distributors. The Andersons, Inc. competes through integrated agronomy services that bundle humic acid with precision nutrient programs. Wilbur-Ellis Company controls extensive retail channels that extend liquid formulation access to row-crop operators.
North America humic acid comprises decomposed organic matter rich in humic and fulvic acids, typically extracted from leonardite or peat through alkaline dissolution processes yielding carbon concentrations between 50-70%. Its primary commercial purpose centers on chelating soil nutrients and stimulating microbial activity to improve fertilizer use efficiency. Liquid formulations dominate volume flows through direct sales channels serving large-scale farming operations, while powder and granular types sustain higher per-unit margins in specialty horticulture and landscaping segments. The agriculture application anchors overall demand as corn and soybean producers integrate humic acid into nitrogen management protocols, whereas wastewater treatment represents an emerging structural growth pocket as municipal utilities adopt bio-stimulant approaches for sludge conditioning.
The EPA oversees manufacturing facility compliance under Clean Water Act discharge permits, while USDA Organic certification rules govern allowable humic acid sourcing for organic crop production. Health Canada and PMRA coordinate cross-border product registration standards that shape market access timelines for imported formulations. State-level soil health initiatives in Iowa, Illinois, and Indiana are creating localized procurement incentives that stakeholders must track against evolving carbon credit qualification criteria.
Market Dynamics
The USDA National Organic Program certification tightening is redirecting procurement toward verified humic acid suppliers, compressing informal sourcing channels while elevating input traceability requirements across Midwest corn and soybean operations.
Growth Catalysts
- Soil Carbon Programs:State-level initiatives in Iowa, Illinois, and Indiana are creating direct procurement incentives tied to carbon credit qualification, pulling humic acid into nitrogen management protocols.
- EPA Bio-Stimulant Pathways:The EPA's evolving framework for bio-stimulant registration is clarifying compliance routes, reducing regulatory uncertainty for wastewater treatment applications in municipal utilities.
- Leonardite Extraction Scale-Up:Alkaline dissolution process improvements at North American peat and leonardite deposits are expanding commercial-grade humic acid output for agricultural distributors.
Market Restraints
- Input Cost Volatility:Peat and leonardite extraction costs fluctuate with energy pricing and Canadian provincial extraction permit availability, squeezing processor margins.
- Substitution Pressure:Synthetic chelating agents and microbial inoculants compete for the same soil amendment budgets in conventional farming, particularly where organic certification is not required.
- Cross-Border Registration Friction:Health Canada and PMRA coordination delays extend product registration timelines for US formulations entering Canadian agricultural channels.
Strategic Opportunities
- Municipal Wastewater Expansion:Sludge conditioning applications in US municipal utilities represent underpenetrated demand as bio-stimulant approaches displace chemical flocculants.
- Specialty Horticulture Channels:Powder and granular formulations command premium positioning in greenhouse and landscaping segments where per-unit margin sensitivity is lower.
- USDA Organic Input Lists:Inclusion on the National Organic Program's approved input registry creates preferential access to certified organic row-crop acreage across the Corn Belt.
Industry Challenges
- Carbon Quantification Expertise Gap:Agronomists and distributors lack standardized training in soil carbon measurement protocols, slowing farmer adoption of carbon-credit-linked application programs.
- Liquid Formulation Stability:Shelf-life variability in liquid humic acid products creates quality assurance complexity for retail distributors managing inventory across multiple growing seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Humic Acid Market |
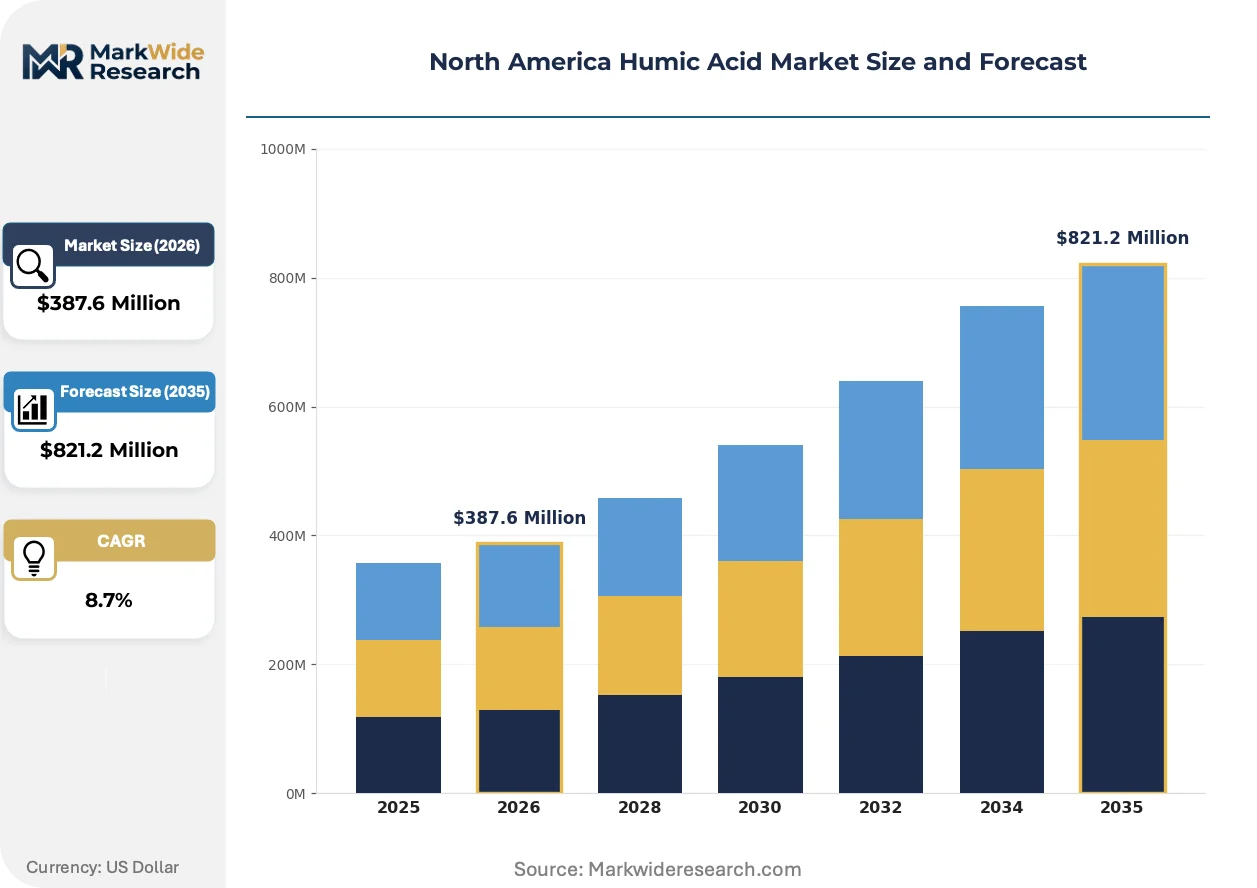
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Pellets Application: Agriculture, Horticulture, Soil Amendment, Wastewater Treatment Distribution Channel: Online, Retail, Direct Sales, Wholesale End User: Farmers, Agronomists, Landscaping Companies, Environmental Agencies |
| Companies Covered | The Andersons, Inc., Black Earth Humic LP, Wilbur-Ellis Company, Actagro, LLC, Humic Growth Solutions, Arctech, Inc., Humintech GmbH, Agbio, Inc., Faust Bio-Agricultural Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Humic Acid Market Emerging Trajectories
Extraction technology refinement and regulatory clarity are converging to reshape how humic acid moves from raw material deposits into differentiated agricultural and environmental applications.
Alkaline dissolution extraction from leonardite deposits is expanding into higher-purity humic acid fractions suitable for precision agriculture equipment. Large-scale corn and soybean operators in the Midwest are integrating these formulations into variable-rate nitrogen application systems. The technology is expanding into direct-injection equipment compatibility, compressing the addressable market for lower-grade bulk powders.
The USDA National Organic Program's tightened input sourcing standards are disqualifying non-certified humic acid suppliers from organic crop production supply chains. This regulatory compression is forcing distributors to validate extraction origin and processing methods through third-party audit trails. Midwest fertilizer distributors serving certified organic acreage are restructuring procurement relationships to maintain compliance eligibility.
Farmer buying committees and cooperative purchasing organizations are consolidating input procurement decisions across multi-county geographies. Traditional independent retail agronomists are losing share to volume-aggregated buying platforms that bundle humic acid with seed and crop protection products. This channel compression is most visible in Iowa and Illinois where cooperative membership density is highest and price transparency pressures are intensifying.
North America Humic Acid Market Segmentation
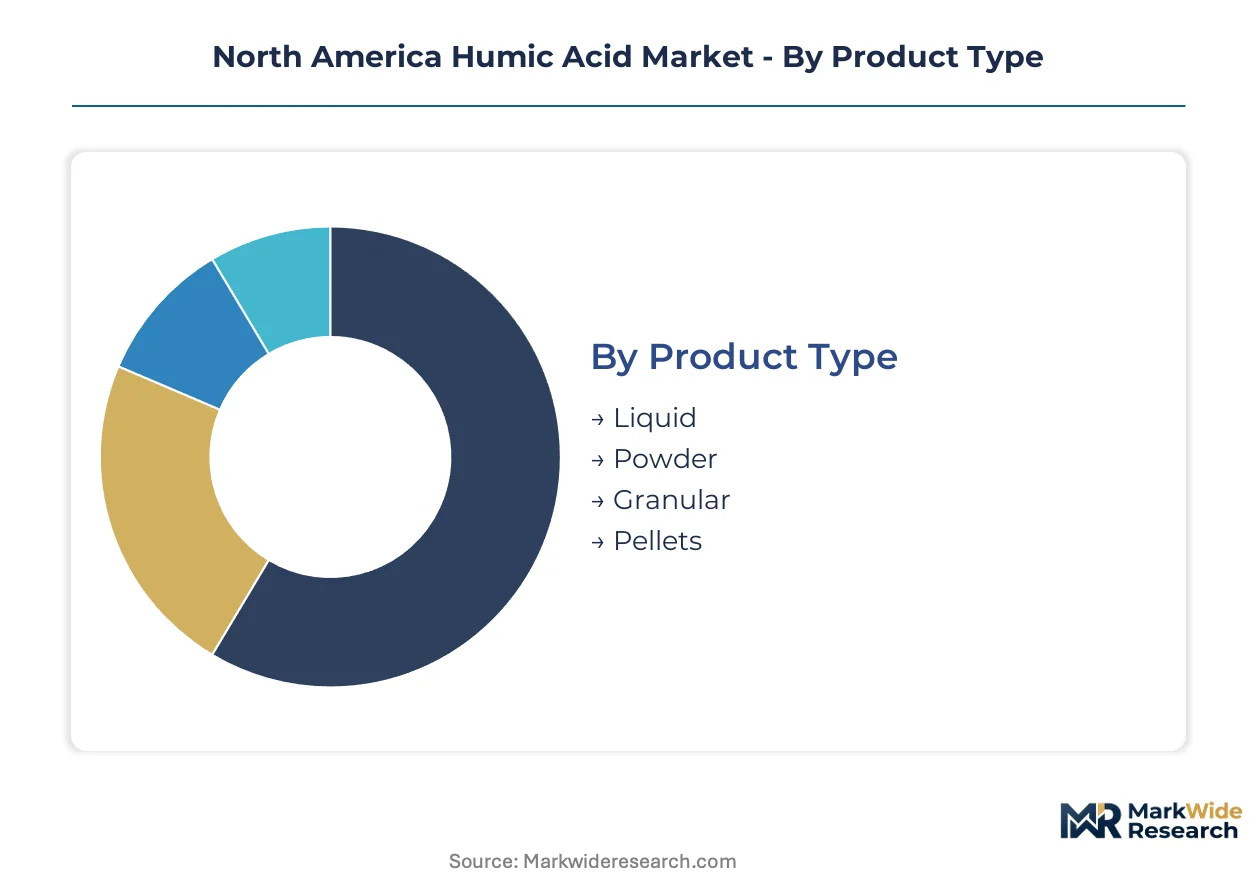
Humic acid segmentation in North America tracks distinct procurement patterns across input formulations, end-use intensity, and channel control points. Each dimension reveals where margin capture concentrates versus where volume flows commoditize.
Product Type:
Customization intensity varies sharply across physical states, with liquid formulations enabling precision application while solid forms demand less equipment integration.
- Liquid:Alkaline-extracted humic acid suspended in aqueous solution, typically 12-20% carbon concentration by weight. Demand concentrates in Midwest corn and soybean operations where direct-injection equipment compatibility drives procurement. State-level soil carbon programs in Iowa and Illinois are pulling liquid formulations into nitrogen management protocols.
- Powder:Spray-dried humic acid with 50-70% carbon content, requiring reconstitution before field application. Specialty horticulture channels in greenhouse clusters across California and Florida sustain premium positioning where per-unit margin sensitivity is lower.
- Granular:Agglomerated humic acid blended with carrier materials for broadcast spreading compatibility. Landscaping companies in Texas and Florida municipal contracts favor this form for ease of mechanical application.
- Pellets:Compressed humic acid with controlled-release characteristics, suited for turf management and golf course maintenance. Demand from landscaping companies in Arizona and Nevada golf resort corridors anchors this segment.
Most installed capacity flows through Liquid. Expansion is steepest in Powder.
Application:
End-use economics separate high-volume commodity agriculture from specialized environmental remediation where regulatory compliance costs reshape procurement.
- Agriculture:Soil amendment and nutrient chelation in row-crop production, integrated with variable-rate nitrogen systems. Corn and soybean producers across the Corn Belt states are incorporating humic acid into fertility programs as USDA Organic certification tightens input sourcing standards.
- Horticulture:Greenhouse and nursery applications requiring precise dosing control for container-grown crops. California Central Valley vegetable propagators and Florida ornamental growers drive formulation customization.
- Soil Amendment:Broad-acre carbon restoration and degraded soil rehabilitation, often tied to carbon credit qualification. State-level initiatives in Indiana and Ohio are creating localized procurement incentives.
- Wastewater Treatment:Sludge conditioning and bio-stimulant approaches displacing chemical flocculants in municipal utilities. EPA bio-stimulant pathway clarification is reducing registration uncertainty for this emerging application.
Volume concentration sits with Agriculture. Regulatory tailwinds are accelerating fastest in Wastewater Treatment.
Distribution Channel:
Channel control determines price realization, with direct sales capturing equipment-linked value while wholesale sacrifices margin for geographic reach.
- Direct Sales:Manufacturer-to-farmer relationships with integrated agronomy services and application equipment bundling. Large-scale operators in Illinois and Iowa cooperative buying committees are consolidating procurement through this channel.
- Wholesale:Bulk supply to regional fertilizer distributors serving retail agronomists. Canadian peat-derived extraction capacity flows through Midwest distributor networks anchored by leonardite processors.
- Retail:Independent farm supply stores and cooperative locations with localized inventory and seasonal credit terms. Share compression is visible as cooperative purchasing platforms aggregate volume.
- Online:E-commerce platforms serving specialty horticulture and small-acreage producers with standardized formulations. Greenhouse operators and landscaping companies access technical specifications directly.
Margin capture peaks in Direct Sales. Geographic expansion runs through Wholesale.
End User:
Technical sophistication and procurement scale separate professional agronomists from price-sensitive municipal buyers.
- Farmers:Row-crop and specialty crop producers integrating humic acid into fertility management. Certified organic acreage across the Corn Belt is redirecting procurement toward verified suppliers with USDA National Organic Program traceability.
- Agronomists:Independent and cooperative-employed crop consultants prescribing input programs. Carbon quantification expertise gaps are slowing adoption of carbon-credit-linked application protocols.
- Landscaping Companies:Commercial turf maintenance, golf course management, and municipal groundskeeping contractors. Arizona and Nevada desert golf operations favor pellet formulations for controlled-release characteristics.
- Environmental Agencies:Municipal utilities and state departments adopting bio-stimulant approaches for sludge conditioning. EPA discharge permit compliance under the Clean Water Act shapes procurement specifications.
Procurement volume concentrates with Farmers. Technical specification influence sits with Environmental Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomist talent clusters in the Midwest Corn Belt anchor North American humic acid demand, with soil carbon program expertise concentrating in Iowa and Illinois cooperative extension networks.
United States
Corn and soybean producers across Iowa, Illinois, and Indiana integrate humic acid into variable-rate nitrogen protocols. The USDA National Organic Program certification tightening redirects procurement toward verified suppliers with traceable extraction origins. Midwest fertilizer distributors in Des Moines and Springfield restructure supply relationships to maintain organic compliance eligibility.
Canada
Peat-derived extraction operations in Alberta and Saskatchewan supply wholesale feedstock to US agricultural channels. Health Canada and PMRA coordinate cross-border product registration standards that shape market access timelines. Edmonton-based processors leverage provincial extraction permits to anchor bulk supply into Midwest distributor networks.
Mexico
Specialty horticulture demand in Sinaloa and Baja California greenhouse clusters pulls powder formulations for vegetable propagation. The country's national agricultural regulator oversees input registration timelines for imported formulations. Guadalajara-area distributors serve protected agriculture operations with technical-grade humic acid for precision dosing systems.
North America Humic Acid Market Vendor Landscape
Capital-heavy extraction processors compete with asset-light formulation specialists across North American humic acid supply chains. The market structure fragments between leonardite deposit owners, alkaline dissolution operators, and precision agriculture integrators. Three archetypes dominate: vertically integrated peat extractors, wholesale distributors with agronomy service bundling, and liquid formulation specialists serving direct-injection equipment. Competitive moves concentrate on USDA Organic certification acquisition and cooperative buying committee penetration.
Within the integrated extraction tier, Black Earth Humic LP anchors Canadian peat-derived supply capacity. The Andersons, Inc. and Wilbur-Ellis Company occupy positions across Midwest wholesale distribution with bundled agronomy services. These three exemplify the channel compression reshaping procurement relationships as farmer buying committees consolidate input decisions across multi-county geographies.
| Leading Market Players |
|---|
| The Andersons, Inc. |
| Black Earth Humic LP |
| Wilbur-Ellis Company |
| Actagro, LLC |
| Humic Growth Solutions |
| Arctech, Inc. |
| Humintech GmbH |
| Agbio, Inc. |
| Faust Bio-Agricultural Services, Inc. |
| Others |
Supply Flow & Price Mechanics
Midwest cooperative buying committees concentrate procurement volume across Iowa and Illinois, anchoring contract-based offtake pricing that rewards scale commitments with preferential terms against spot-market powder premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic-certified liquid formulations from conventional agricultural grades and bulk powder commodities. Price differentiation rests on certification tier and volume scale, with organic-certified commands sustaining margin premiums. Cost compression in standard agricultural grades is intensifying because synthetic chelating agents compete for the same fertility budgets. Municipal utilities exhibit lowest price sensitivity due to regulatory compliance mandates, while independent retail agronomists face highest sensitivity as cooperative platforms aggregate volume and compress margins.
Supply Chain Analysis
Freight costs from Canadian peat extraction sites in Alberta and Saskatchewan to Midwest distributor hubs in Des Moines and Springfield represent a material cost stack, particularly for liquid formulations requiring temperature-controlled transport. Supply concentrates in Canada and the United States, with Mexican greenhouse clusters drawing from US wholesale channels. Raw material dependencies center on leonardite deposits, alkaline dissolution chemicals, and aqueous suspension carriers. Single-source vulnerability sits with Canadian provincial extraction permit availability, which can constrain feedstock flow. Distribution runs through wholesale fertilizer distributors with integrated agronomy service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as soil carbon program enrollment across Corn Belt states creates durable, regulation-anchored demand pull with multi-year contract visibility.
For Market Incumbents: Acquire carbon quantification expertise through specialist agronomist teams or technology platforms. Backward integration into leonardite extraction assets in Alberta or Saskatchewan secures feedstock control against permit volatility. Channel control through cooperative buying committee penetration defends position against synthetic chelating agent substitution in conventional acreage.
For New Entrants and Emerging Players: Launch via municipal wastewater treatment direct sales channels where EPA bio-stimulant pathway clarification reduces registration friction. Underpenetrated demand in sludge conditioning applications offers fastest path to revenue without competing against entrenched agricultural distributors. Target Arizona and Nevada golf resort corridors with pellet formulation specialization where controlled-release premiums sustain margin.
For Investors and Strategic Acquirers: Fertilizer distributors with bundled agronomy services are the most active acquirer in this space, seeking to deepen input integration and capture cooperative buying committee volume. Acquisition target archetype: liquid formulation specialists with direct-injection equipment compatibility and USDA Organic certification. Signal to watch: state-level soil carbon program expansion beyond Iowa, Illinois, and Indiana into Ohio and Nebraska as inflection indicator for addressable market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Investment | Certified input registry inclusion unlocks premium pricing in organic row-crop acreage across Corn Belt states. |
| Backward Integration into Leonardite Extraction | Captive supply of Canadian peat deposits insulates margins from provincial permit availability volatility. |
| Municipal Wastewater Channel Development | EPA discharge permit compliance requirements create sticky demand with multi-year contract structures. |
| Carbon Quantification Capability Buildout | Soil carbon measurement expertise accelerates farmer adoption of credit-linked application programs. |
| Cooperative Buying Committee Penetration | Volume aggregation platforms in Iowa and Illinois compress independent retail channels and consolidate procurement decisions. |
Methodological Framework
Direct dialogue with extraction plant managers, Midwest fertilizer distributor procurement leads, cooperative agronomists, municipal utility operations directors, and greenhouse propagation specialists grounded qualitative insights. Secondary validation drew from USDA National Organic Program input registries, EPA bio-stimulant registration filings, state-level soil health initiative documentation, and Canadian provincial extraction permit records. Bottom-up and top-down triangulation cross-checked volume estimates against trade flow data and end-use consumption patterns.
Bottom-up modeling anchored projections across the analysis window, with top-down macro validation against agricultural input expenditure trends. Segmentation dimensions included product formulation state, application end-use, distribution channel control point, and end-user technical sophistication. CAGRs derived from fitted growth curves calibrated to enrollment trajectories in state soil carbon programs and EPA regulatory pathway progression. Forecast inputs incorporated leonardite extraction capacity expansion timelines and cooperative membership density projections.
Several conditions sit outside the modeled scope, including abrupt shifts in Canadian provincial environmental policy, synthetic chelating agent price collapse, and federal preemption of state carbon credit frameworks. Forecasts reflect documented assumptions about regulatory continuity and farmer adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Cyclopentanone Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Aspartic Acid Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
Alanine Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
Humic Acid Market
Organic Chemicals
Mercaptopropionic Acid Market