
 E-Rickshaw Market | 2026-2036
E-Rickshaw Market Size, Share, and Industry Trends Forecast 2026-2036
E-Rickshaw Market Analysis
The E-Rickshaw market is decoupling into premium lithium-ion offerings and commodity lead-acid segments with diverging margin structures and replacement cycles. Mahindra Electric leverages its automotive heritage to sustain higher power ratings and standardized charging protocols across dealer networks. Saera Electric Auto competes on cost-optimized passenger configurations that dominate Tier-2 and Tier-3 city distribution. Bajaj Auto anchors its position through extensive service infrastructure and spare parts availability that reduces total cost of ownership for fleet operators.
An E-Rickshaw is a three-wheeled electric vehicle powered by a brushless DC motor typically rated between 500W and 2000W, designed for short-haul passenger transport and light cargo movement in congested urban corridors. The chassis employs tubular steel construction with a maximum payload capacity of 400-600 kg depending on configuration, while battery placement beneath the floor pan lowers the center of gravity for stability on uneven roads. Passenger-type vehicles lead volume due to established commuter dependence in South Asian cities, though cargo and delivery variants are gaining structural importance as e-commerce fulfillment networks electrify last-mile distribution. Lithium-ion battery configurations command premium positioning and longer cycle life, while lead-acid systems retain share in price-sensitive procurement where upfront capital constraints override lifetime operating cost considerations.
India's Ministry of Road Transport and Highways mandates AIS-156 safety standards for electric three-wheelers, while the Central Electricity Authority regulates battery-swapping station grid connections and tariff structures. Bangladesh's Road Transport Authority enforces vehicle fitness certification that increasingly incorporates electrical system inspection protocols for converted and factory-built units. Stakeholders must monitor how subsidy phase-out timelines and domestic battery manufacturing mandates reshape supplier economics and fleet financing models across the value chain.
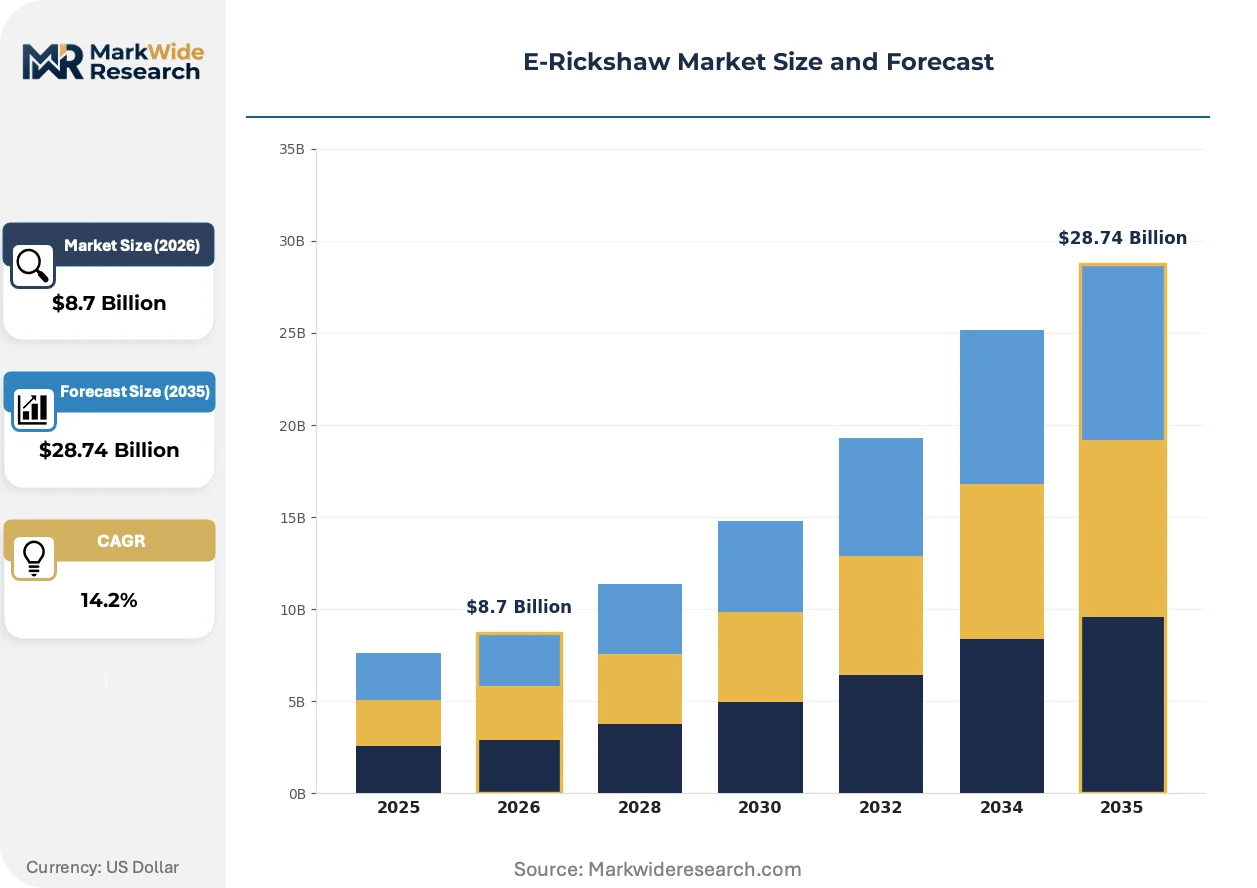
Market Dynamics
The E-Rickshaw market is bifurcating around battery chemistry economics, with lithium-ion configurations commanding fleet operator preference in formal procurement channels while lead-acid variants saturate informal rental and owner-operator segments across South Asian urban corridors.
Growth Catalysts
- FAME-II Subsidy Architecture:India's purchase incentives and battery-swapping infrastructure grants compress payback periods for commercial fleet operators transitioning from diesel three-wheelers.
- Last-Mile Electrification Mandates:E-commerce fulfillment networks in Bangladesh and Nepal now specify electric vehicle quotas in logistics vendor contracts, pulling informal operators into formal electrification pathways.
- Lead-Acid Replacement Cycles:The 12-18 month replacement interval for conventional batteries generates recurring aftermarket demand that sustains dealer network viability in Tier-2 and Tier-3 distribution.
Market Restraints
- Lithium Cell Import Concentration:Domestic battery assembly operations depend on Chinese cathode and cell imports, exposing margin structures to tariff volatility and supply rationing.
- AIS-156 Certification Timelines:India's safety standard compliance requirements extend product development cycles by 8-14 months for new vehicle platforms, delaying market entry for unproven chassis designs.
- Grid Connection Friction:Bangladesh's distribution utilities lack standardized tariff categories for battery-swapping stations, forcing operators into commercial-industrial rate schedules that erode charging economics.
Strategic Opportunities
- Nepal's Mountain Corridor Electrification:The Kathmandu-Pokhara freight route remains underserved by factory-built cargo variants, creating first-mover positioning for purpose-designed high-torque configurations.
- Solar-Integrated Charging Infrastructure:Hybrid solar-battery swapping stations address grid reliability gaps in eastern Uttar Pradesh and Bihar, enabling off-grid fleet operations.
- CEA Grid Integration Standards:India's Central Electricity Authority protocols for station interconnection create regulatory clarity that attracts utility-scale capital into charging network deployment.
Industry Challenges
- Brushless DC Motor Repair Scarcity:The specialized winding and controller diagnostics skillset concentrates in Tier-1 service centers, leaving peripheral markets dependent on component replacement rather than refurbishment.
- Battery Swapping Interoperability:Proprietary connector designs and battery form factors across OEMs fragment station utilization rates and strand fleet assets during network expansion phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Rickshaw Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger, Cargo, Delivery, Tour Battery Type: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Others Power Rating: 500W, 1000W, 1500W, 2000W Charging Mode: Standard Charging, Fast Charging, Solar Charging, Swappable Battery |
| Companies Covered | Atul Auto, Saera Electric Auto, Mahindra Electric, Kinetic, Yatri, Lohia Auto, Piaggio, Bajaj Auto, Terra Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Rickshaw Market Emerging Trajectories
Technology convergence and regulatory specification are compressing product lifecycles while elevating safety and performance baselines across the E-Rickshaw value chain. Manufacturers now face simultaneous pressure to reduce upfront cost and extend operational durability.
Lithium iron phosphate cell chemistry is overtaking nickel-manganese-cobalt alternatives in commercial fleet procurement due to superior thermal stability and cycle life metrics. Formal logistics operators in Delhi and Dhaka now specify LFP configurations in tender documents, compressing residual value risk and enabling longer lease terms. This chemistry shift is overtaking traditional lead-acid dominance in the 1000W+ motor segment where daily duty cycles exceed 80 kilometers.
India's AIS-156 Phase 2 amendments mandate fire-resistant battery enclosures and thermal runaway propagation testing for all new electric three-wheeler type approvals. The regulation forces chassis redesigns and supplier qualification programs that favor established automotive component manufacturers over legacy fabrication shops. Factory-built units with integrated battery management systems now capture preferential financing terms from fleet leasing providers, displacing retrofitted conversions in formal procurement channels.
Fleet operators are consolidating vendor relationships around integrated service contracts that bundle vehicle supply, battery maintenance, and charging infrastructure access. This procurement compression displaces the fragmented owner-operator model where drivers sourced vehicles, batteries, and repairs from separate suppliers. The bundled service model concentrates in India's National Capital Region and Maharashtra, where logistics companies electrify hundred-vehicle blocks under single-source agreements with performance guarantees.
E-Rickshaw Market Segmentation
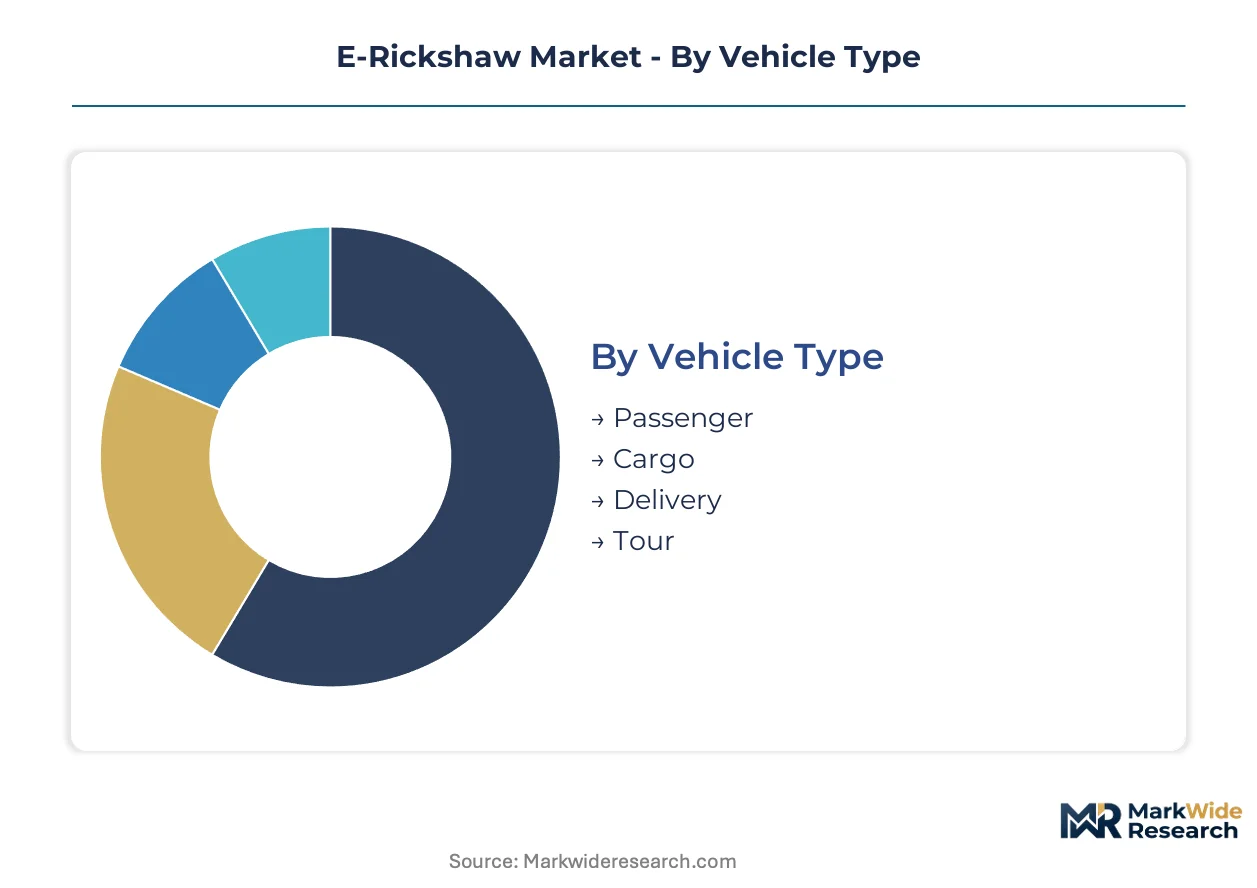
Segmentation in the E-Rickshaw market reveals divergent procurement patterns between informal owner-operators and formal fleet operators. Battery chemistry and power rating selections directly correlate with daily duty cycles, financing access, and charging infrastructure availability across South Asian urban corridors.
Vehicle Type:
Volume concentration favors utilitarian configurations, while premium positioning clusters around specialized service applications.
- Passenger:Tubular steel chassis with 4-6 seat configurations dominate urban commuter corridors. Demand concentrates in Delhi, Dhaka, and Kathmandu where established informal transit networks electrify existing routes. Lead-acid batteries retain share here due to lower upfront capital requirements for individual owner-operators.
- Cargo:Reinforced load beds with 400-600 kg payload ratings serve last-mile freight distribution. E-commerce fulfillment networks in India's National Capital Region and Maharashtra now mandate electric cargo quotas in vendor contracts, pulling informal operators into formal procurement channels with lithium-ion specifications.
- Delivery:Compact footprint variants with weather-protected storage compartments address parcel and grocery distribution. Quick-commerce platforms in Bangladesh specify these configurations for sub-5-kilometer delivery radii.
- Tour:Premium seating and enhanced suspension systems target heritage corridor operators. Deployment concentrates in Rajasthan and Nepal's Pokhara-Kathmandu route where tourism recovery drives fleet renewal.
Mature deployment sits with Passenger configurations. Newer deployment is concentrated in Cargo variants.
Battery Type:
Procurement splits sharply between price-sensitive upfront minimization and lifetime cost optimization strategies.
- Lead-Acid:Flooded and VRLA configurations with 12-18 month replacement cycles sustain informal rental markets. Tier-2 and Tier-3 Indian cities retain this chemistry where charging infrastructure gaps and capital constraints dominate purchase decisions.
- Lithium-Ion:LFP chemistry overtakes NMC in commercial fleet procurement due to thermal stability and 2000+ cycle life. Delhi and Dhaka logistics operators now specify LFP in tender documents, compressing residual value risk and enabling longer lease terms from financing providers.
- Nickel-Metal Hydride:Transitional chemistry with moderate energy density retains niche presence in early-generation retrofitted conversions. Replacement demand concentrates in Bangladesh's informal conversion workshops.
- Others:Emerging sodium-ion and solid-state prototypes remain pre-commercial, with pilot deployments limited to Indian OEM test fleets under PLI scheme validation protocols.
Lead-Acid retains volume leadership in owner-operator procurement. Lithium-Ion is climbing the fastest in formal fleet channels.
Power Rating:
Motor specification tracks terrain severity and payload requirements across operating environments.
- 500W:Entry-level brushless DC motors suit flat urban corridors with minimal gradients. Dhaka's dense old city neighborhoods favor these configurations for maneuverability in narrow lanes.
- 1000W:Mid-range rating balances acceleration and energy consumption for mixed-route operations. India's Tier-2 cities deploy this specification as the default for new fleet procurement.
- 1500W:Enhanced torque output addresses hill starts and moderate payloads. Nepal's Kathmandu Valley operators require this minimum rating for terrain compliance.
- 2000W:Maximum continuous duty rating supports heavy cargo and steep gradient corridors. Factory-built cargo variants for Nepal's mountain freight routes specify this threshold.
1000W ratings dominate current procurement volumes. 2000W configurations are expanding most quickly in high-torque applications.
Charging Mode:
Infrastructure availability and fleet utilization rates determine charging technology selection.
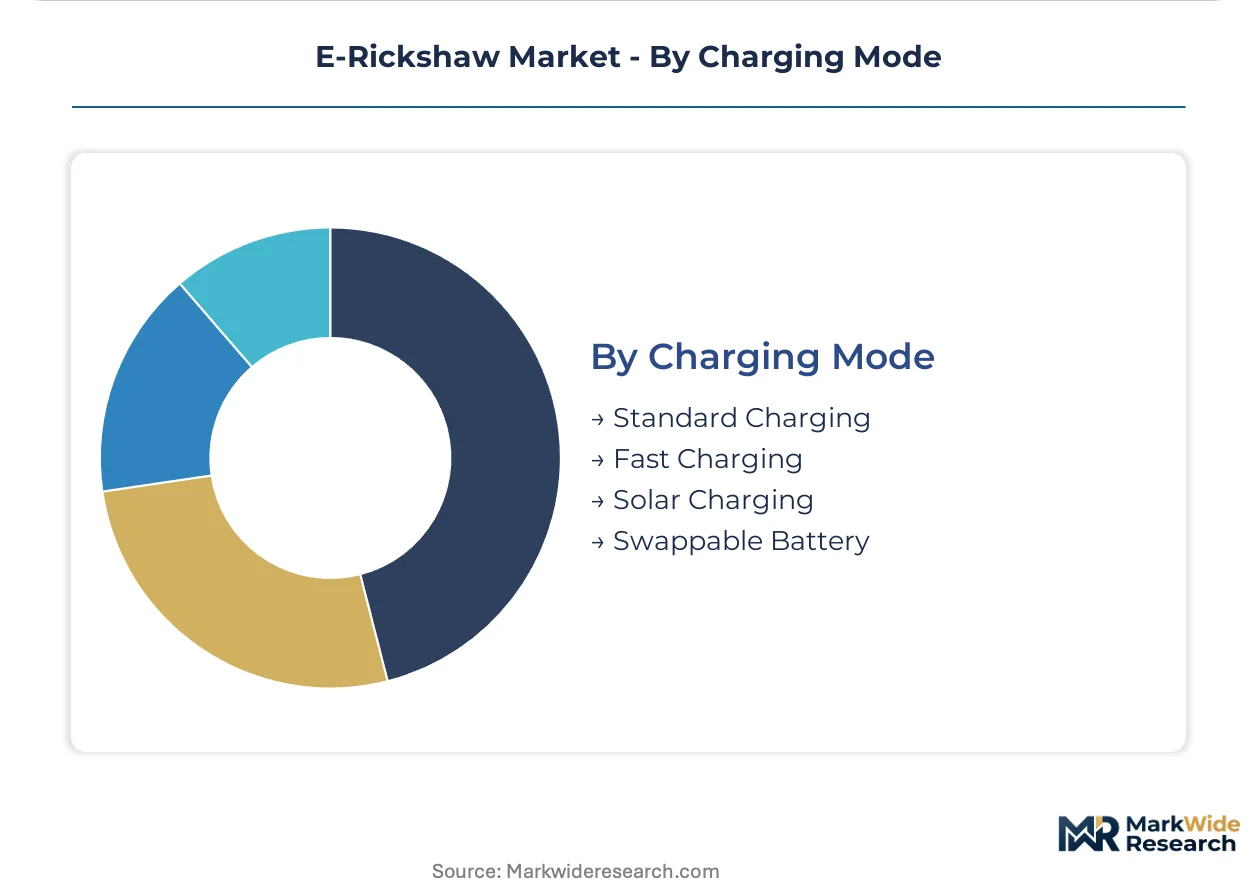
- Standard Charging:Overnight AC charging at 220V residential connections sustains owner-operator economics. India's residential tariff slabs favor this mode where grid reliability permits.
- Fast Charging:DC rapid stations compress downtime for high-utilization fleets. Delhi's logistics hubs deploy these for multi-shift operations exceeding 150 kilometers daily.
- Solar Charging:Hybrid PV-battery systems enable off-grid operation in eastern Uttar Pradesh and Bihar where grid supply remains intermittent. CEA grid integration standards now clarify interconnection protocols for solar-hybrid stations.
- Swappable Battery:Automated exchange systems eliminate charging downtime for continuous-duty fleets. Bangladesh lacks standardized tariff categories for swapping stations, forcing operators into commercial-industrial rate schedules.
Standard Charging retains the largest installed base. Swappable Battery systems are gaining share fastest in high-utilization fleet applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Delhi-NCR anchors South Asian E-Rickshaw deployment density, where informal transit networks and formal logistics fleets electrify in parallel. India's FAME-II subsidy architecture compresses payback periods for commercial operators transitioning from diesel three-wheelers. Bangladesh and Nepal now represent concentrated demand zones where informal electrification outpaces formal infrastructure buildout.
India
Delhi, Mumbai, and Bangalore drive fleet electrification through e-commerce logistics mandates and last-mile delivery quotas. India's Ministry of Road Transport and Highways enforces AIS-156 safety standards for electric three-wheelers, while the Central Electricity Authority regulates battery-swapping station grid connections. Uttar Pradesh and Bihar concentrate owner-operator procurement where lead-acid configurations retain price-sensitive market share.
Bangladesh
Dhaka's dense urban corridors generate demand for compact 500W configurations maneuvering through narrow lanes. The country's Road Transport Authority enforces vehicle fitness certification incorporating electrical system inspection protocols for converted and factory-built units. Chittagong's port logistics zone pulls informal operators into formal electrification pathways through vendor contract specifications.
Nepal
Kathmandu Valley operators require 1500W minimum motor ratings for terrain compliance on steep gradients. The Kathmandu-Pokhara freight route remains underserved by factory-built cargo variants, creating positioning opportunities for high-torque configurations. Pokhara's tourism recovery drives fleet renewal for premium tour configurations with enhanced suspension systems.
China
Zhengzhou and Shandong manufacturing clusters supply brushless DC motors and battery management systems to South Asian assemblers. China's MIIT governs electric vehicle component export standards and dual carbon goals shape supplier qualification programs. The Pearl River Delta concentrates lithium cell production that feeds domestic battery assembly operations across the region.
E-Rickshaw Market Vendor Landscape
Premium-margin players sit above commodity-margin players across battery chemistry and power rating tiers, with lithium-ion configurations commanding fleet operator preference while lead-acid variants saturate informal rental segments. The vendor base stratifies into three strategic archetypes: automotive heritage manufacturers leveraging dealer networks, cost-optimized specialists dominating Tier-2 and Tier-3 distribution, and integrated service providers bundling vehicle supply with battery maintenance. Competitive moves concentrate on vertical integration into battery assembly and geographic expansion through bundled fleet service contracts.
Among India-based manufacturers, Mahindra Electric occupies a position within the automotive heritage tier, while Saera Electric Auto exemplifies cost-optimized passenger configuration specialists. Bajaj Auto anchors the integrated service segment through extensive spare parts availability that reduces total cost of ownership for fleet operators.
| Leading Market Players |
|---|
| Atul Auto |
| Saera Electric Auto |
| Mahindra Electric |
| Kinetic |
| Yatri |
| Lohia Auto |
| Piaggio |
| Bajaj Auto |
| Terra Motors |
| Others |
Supply Flow & Price Mechanics
India's dual carbon goals and FAME-II subsidy phase-out timelines gate qualified supply access and premium-tier pricing power across the E-Rickshaw value chain. Battery chemistry certification under AIS-156 Phase 2 amendments separates factory-built lithium-ion configurations from informal lead-acid conversions, compressing margin structures for uncertified assemblers while elevating pricing floors for compliant OEMs.
Pricing Analysis
Throughput-based leasing contracts anchor value-based pricing for fleet operators, with monthly rates scaling to daily duty cycles and battery swap guarantees. Three-tier pricing structure across premium lithium-ion, standard LFP, and economy lead-acid tiers tracks certification grade and thermal stability metrics. Pricing pressure stems from Chinese cathode import tariffs and domestic cell assembly bottlenecks. Owner-operators in Uttar Pradesh and Bihar exhibit highest price sensitivity, while Delhi-NCR logistics fleets prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Single-source vulnerability sits with China's Zhengzhou and Shandong manufacturing clusters for brushless DC motors and battery management systems. Domestic assembly operations in India and Bangladesh draw from Chinese lithium cell imports, South Korean cathode precursors, and Japanese power electronics. Tariff exposure on finished cell imports threatens margin structures for non-integrated assemblers. Distribution runs through OEM-owned dealer networks in Tier-1 cities and fragmented spare parts markets in Tier-2 corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The E-Rickshaw market occupies a technology-transition phase where lithium iron phosphate chemistry displaces lead-acid dominance in commercial fleet procurement. This chemistry shift compresses replacement cycle economics and reshapes supplier qualification requirements across South Asian manufacturing clusters.
For Market Incumbents: Anticipate margin compression from subsidized domestic cell manufacturing under India's PLI scheme by securing backward integration into battery pack assembly. Reinforce channel control through captive financing partnerships that bundle vehicle supply with battery maintenance contracts, locking out informal conversion workshops from formal fleet procurement channels.
For New Entrants and Emerging Players: Battery-swapping interoperability protocols offer a technology-first wedge into Bangladesh's underserved logistics corridors where grid tariff ambiguity blocks incumbent expansion. Target Nepal's Kathmandu-Pokhara freight route with purpose-designed 2000W cargo configurations. Pursue utility-scale capital partnerships under CEA grid integration standards to finance solar-hybrid charging infrastructure.
For Investors and Strategic Acquirers: FAME-II subsidy extension announcements are the leading indicator that fleet electrification mandates will harden into vendor contract specifications. Position for a five-to-ten year consolidation window favoring integrated service providers with in-house battery assembly and swapping network control. Monitor AIS-156 certification backlog timelines as signal of regulatory capacity constraints that favor established automotive heritage manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Chemistry Standardization | LFP cell specifications under AIS-156 Phase 2 enable longer lease terms from SBI and HDFC fleet financing. |
| Swapping Infrastructure Partnership | CEA grid interconnection protocols attract Tata Power and Adani Green into charging network deployment. |
| Backward Integration into Cells | Domestic assembly under PLI scheme reduces exposure to Chinese cathode import tariff volatility. |
| High-Torque Cargo Platform Launch | 2000W configurations address Nepal's Kathmandu-Pokhara gradient requirements where factory-built supply is scarce. |
| Solar-Hybrid Station Deployment | PV-battery systems enable off-grid operations in eastern Uttar Pradesh where grid reliability remains intermittent. |
Methodological Framework
Trade customs records, vehicle registration databases, and FAME-II disbursement filings formed the secondary backbone, supplemented by regulatory documentation from India's Ministry of Road Transport and Highways and Bangladesh's Road Transport Authority. Primary fieldwork encompassed fleet operators in Delhi-NCR and Dhaka, battery assemblers in Uttar Pradesh, OEM platform engineers at Mahindra Electric and Bajaj Auto, and dealer network managers across Tier-2 Indian cities. Bottom-up triangulation across procurement volume estimates and top-down validation against subsidy disbursement aggregates anchored market sizing.
Historical trendline analysis of FAME-II uptake curves and lead-acid replacement cycle frequencies informed projection parameters across the analysis window. Segmentation modeling incorporated vehicle type, battery chemistry, power rating, and charging mode dimensions, with daily duty cycle assumptions calibrated against e-commerce logistics contract specifications. CAGRs derived from logistic diffusion curves of fleet electrification mandates and informal conversion workshop displacement rates.
Several conditions sit outside the modeled scope, including unannounced subsidy phase-out accelerations, lithium cell import quota restrictions, and grid tariff reclassifications in Bangladesh. Forecasts reflect documented assumptions regarding AIS-156 certification timeline stability and PLI scheme disbursement continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
South America Electric Bus Battery Pack Market
Electric Vehicles
Micro Electric Vehicle Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
UK Electric Vehicle Market
Electric Vehicles
Water Proof E-Scooter Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
ASEAN Electric Bicycle Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
India Electric Vehicle Financing Market
Electric Vehicles
North America Electric Vehicle Market