
 Alkaline Secondary Battery Market | 2026-2036
Alkaline Secondary Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Alkaline Secondary Battery Market Insights
The EU Battery Regulation is consolidating compliance requirements across the alkaline secondary battery value chain, forcing manufacturers to document carbon intensity and recycled content thresholds. Panasonic Corporation leverages its vertical integration into cathode active materials to sustain cost advantages in cylindrical cell production. Energizer Holdings Inc. anchors its competitive position through brand strength and channel control across North American retail networks. GP Batteries International Ltd. specializes in prismatic form factors for industrial power tool applications, differentiating through regional manufacturing scale in Southeast Asia.
Alkaline secondary batteries encompass rechargeable electrochemical cells utilizing nickel-metal hydride or nickel-cadmium chemistries, typically operating at nominal voltages of 1.2V with energy densities ranging from 60 to 120 Wh/kg depending on cathode composition and electrolyte formulation. These cells serve as critical power sources in devices requiring moderate cycle life and stable discharge characteristics without the thermal management complexity of lithium-ion alternatives. The cylindrical segment dominates unit volume due to established tooling and compatibility with legacy consumer electronics and power tool platforms, while the energy storage application category captures expanding margin pools as grid operators seek proven chemistries for frequency regulation services. NiMH cell types retain structural importance in hybrid automotive applications where safety tolerance and temperature stability outweigh energy density requirements.
The EPA enforces hazardous waste rules affecting NiCd battery disposal and recycling infrastructure in the United States, while China's MEE implements dual carbon goals that tighten emissions benchmarks for electrode manufacturing facilities. Japan's METI coordinates domestic battery supply chain resilience programs that subsidize local production of separator films and electrolyte salts. Stakeholders must monitor how divergent recycling mandates across these jurisdictions reshape cost structures and determine which production geographies maintain access to premium OEM supply contracts.
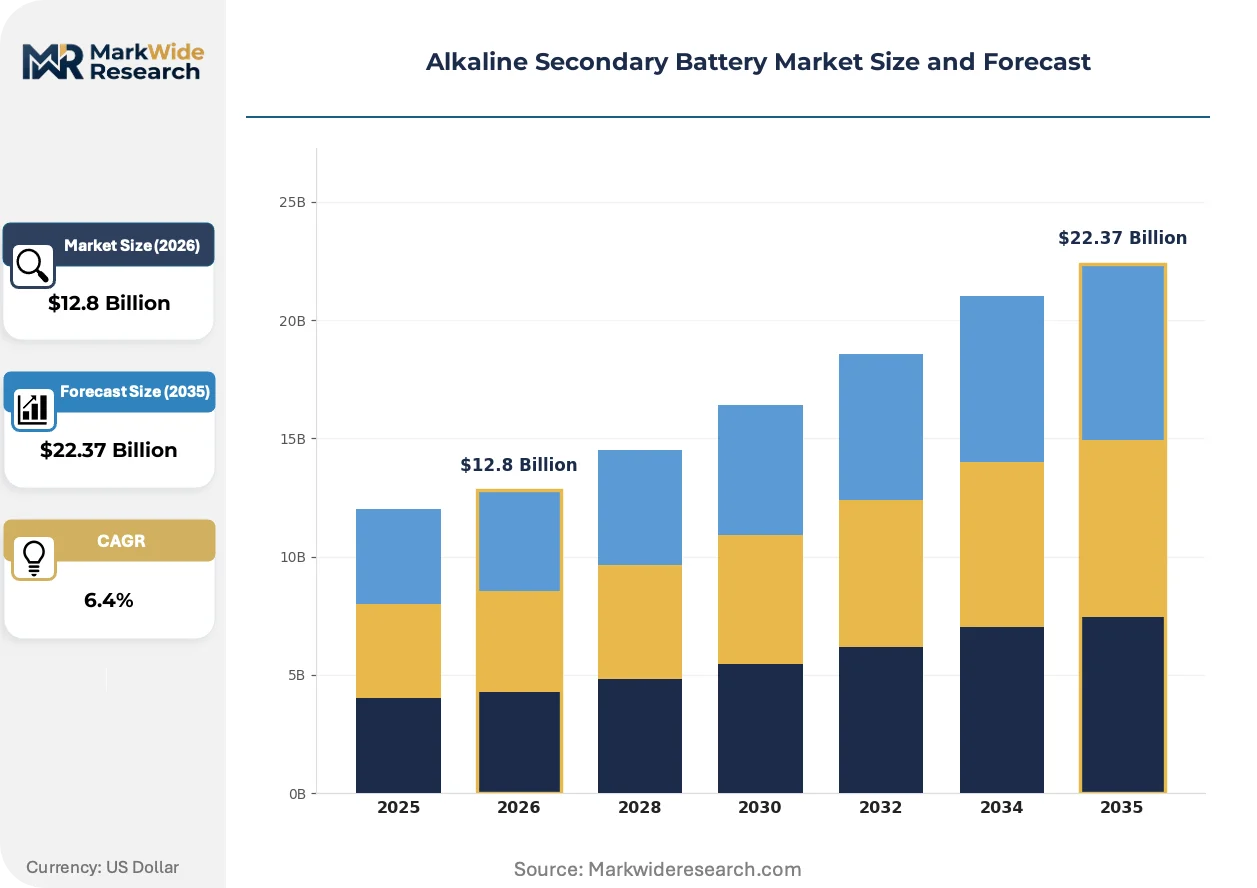
Market Dynamics
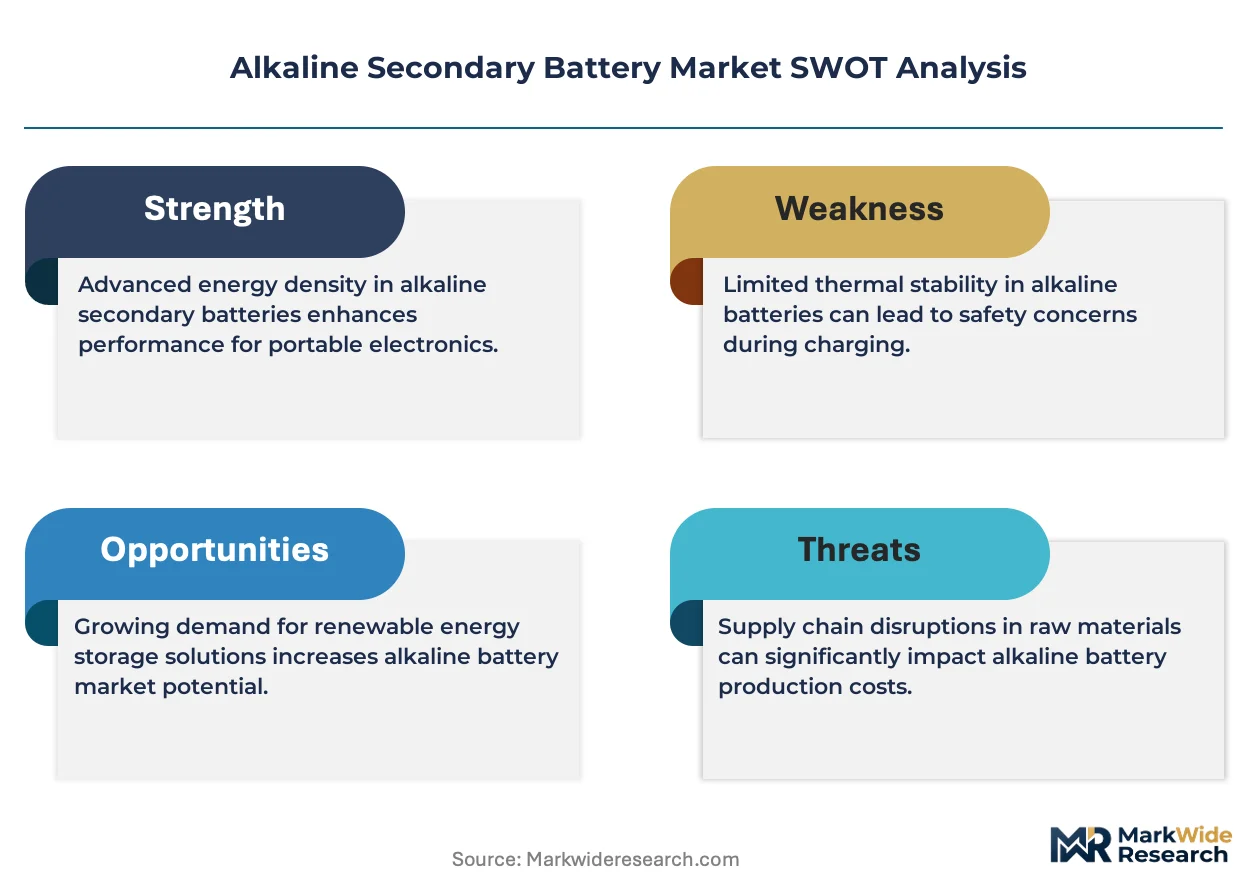
The alkaline secondary battery market is being reshaped by the EU Battery Regulation's carbon footprint disclosure mandates, which are forcing manufacturers to reconfigure material sourcing networks and document recycled content thresholds across their supply chains.
Growth Catalysts
- Hybrid automotive procurement:Japan's automotive sector is accelerating NiMH cell purchases for hybrid electric vehicles, driven by safety tolerance requirements that outweigh energy density considerations.
- Grid frequency regulation:Energy storage operators are deploying alkaline secondary batteries for proven frequency regulation services, capitalizing on stable discharge characteristics without thermal management complexity.
- China's dual carbon goals:The MEE is tightening emissions benchmarks for electrode manufacturing facilities, creating compliance-driven demand for cleaner production technologies and low-carbon material inputs.
Market Restraints
- Cadmium toxicity constraints:The EPA's hazardous waste rules for NiCd battery disposal have elevated recycling infrastructure costs and restricted landfill access across the United States.
- East Asian supply concentration:Cathode active material production clusters in Japan and South Korea's refining corridor create geographic vulnerability to regional disruptions and trade policy shifts.
- Lithium-ion substitution pressure:Declining lithium-ion costs and improving energy density are displacing alkaline secondary batteries from consumer electronics and emerging mobility applications.
Strategic Opportunities
- Industrial power tool expansion:Southeast Asian manufacturing zones present underpenetrated demand for prismatic NiMH cells in professional-grade power tool platforms.
- Separator film localization:Japan's METI supply chain resilience programs subsidize domestic separator film production, creating captive supply advantages for integrated manufacturers.
- Recycled content premiums:The EU Battery Regulation's recycled content thresholds are generating price premiums for batteries meeting verified circularity standards in European industrial procurement.
Industry Challenges
- Electrolyte salt qualification timelines:New electrolyte formulations require extended certification cycles under IEC safety standards, compressing product development windows.
- Legacy system integration friction:Grid operators face technical complexity when retrofitting alkaline secondary battery arrays into existing frequency regulation infrastructure designed for lead-acid chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkaline Secondary Battery Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cell Type: NiMH, NiCd, Li-ion, Li-poly End User: Consumer Electronics, Automotive, Industrial, Telecommunications Application: Energy Storage, Electric Vehicles, Power Tools, Renewable Energy Form Factor: Cylindrical, Prismatic, Pouch, Button |
| Companies Covered | Duracell Inc., Energizer Holdings Inc., Panasonic Corporation, Spectrum Brands Holdings Inc., GP Batteries International Ltd., Toshiba Corporation, FDK Corporation, Camelion Batterien GmbH, Gold Peak Industries (Holdings) Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkaline Secondary Battery Market Trends and Innovations
Electrode manufacturing processes are converging with digital quality control systems, while regulatory frameworks are hardening material provenance requirements. These forces are compressing margins for non-integrated producers and rewarding upstream control.
High-nickel cathode formulations are consolidating technical leadership in cylindrical cell production. Japanese cathode active material producers are adopting these chemistries for hybrid vehicle contracts. This transition is consolidating procurement power among buyers with volume commitments and backward integration into precursor refining.
REACH compliance documentation is expanding scope to cover full battery lifecycle carbon intensity. European industrial buyers are now requiring supplier disclosures on mining origin and refining energy sources. The cylindrical segment faces the steepest compliance cost escalation as legacy supply chains lack traceability infrastructure.
Aftermarket battery replacement cycles are compressing as power tool OEMs bundle cells with equipment leases rather than discrete sales. Professional contractor segments in North America are migrating to subscription-based power platforms. Japan's construction sector shows similar procurement model evolution, with equipment manufacturers capturing recurring revenue streams previously lost to third-party battery suppliers.
Alkaline Secondary Battery Market Segmentation
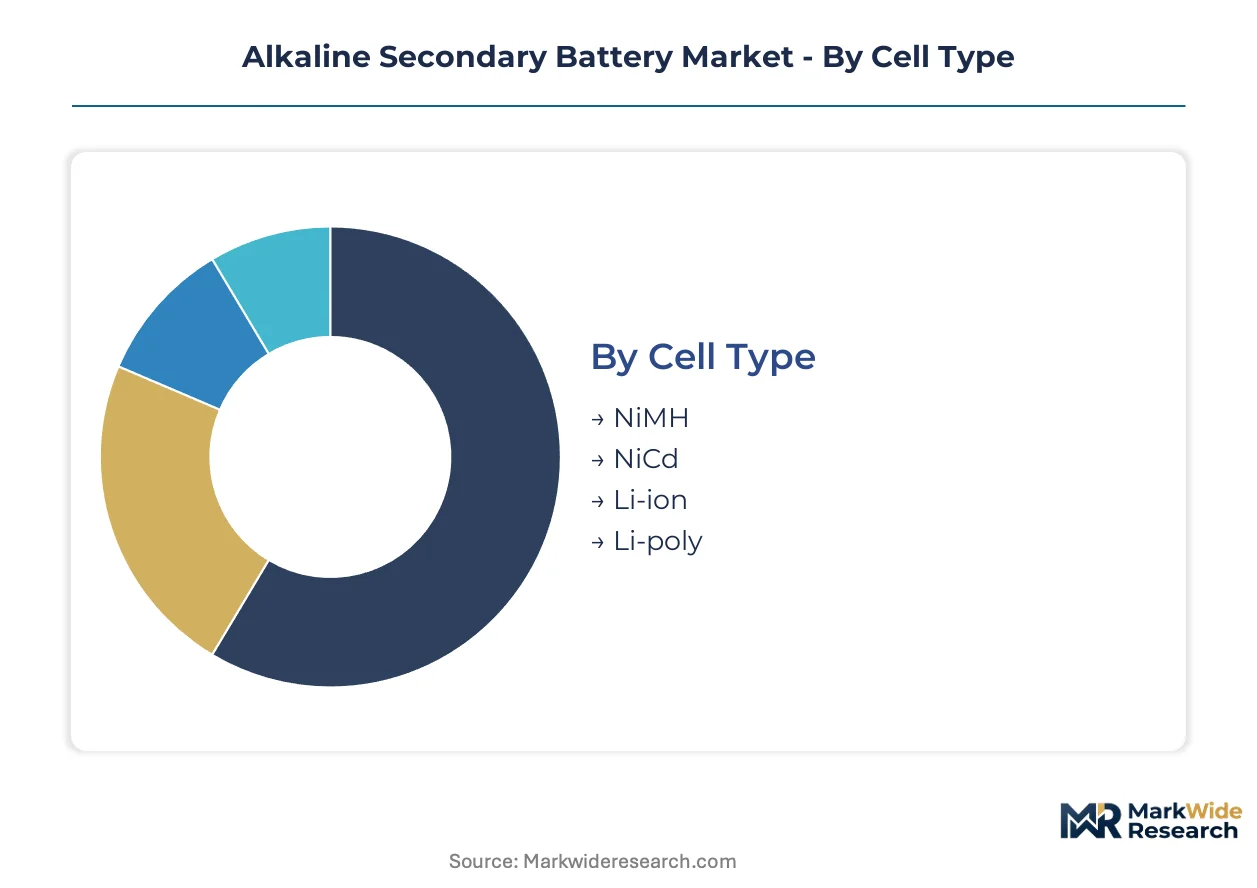
Alkaline secondary battery segmentation reveals how capital deployment, regulatory exposure, and end-use specifications fragment manufacturing strategies. Each dimension carries distinct tooling requirements and compliance burdens that reshape competitive positioning across cell producers.
Cell Type:
NiMH and NiCd chemistries demand the heaviest upfront investment in electrode coating lines and electrolyte formulation facilities, while lithium variants require distinct dry-room infrastructure.
- NiMH:Nickel-metal hydride cells utilize rare earth metal hydride anodes and nickel oxyhydroxide cathodes, delivering 60-120 Wh/kg with superior temperature stability. Procurement from Japan's hybrid automotive sector concentrates in cylindrical formats for Toyota and Honda powertrain integration, driven by safety tolerance requirements that outweigh energy density considerations.
- NiCd:Nickel-cadmium chemistry employs metallic cadmium anodes and nickel oxyhydroxide cathodes in potassium hydroxide electrolyte, offering exceptional cycle durability and low-temperature performance. The EPA's hazardous waste rules have elevated recycling infrastructure costs across the United States, restricting landfill access and compressing margins for non-compliant producers.
- Li-ion:Lithium-ion variants dominate energy density-sensitive applications through lithium cobalt oxide or lithium iron phosphate cathodes.
- Li-poly:Lithium-polymer cells enable flexible form factors for wearable electronics and slim-profile consumer devices.
NiMH absorbs the bulk of installed capacity for hybrid automotive contracts; Li-ion is expanding most quickly into grid frequency regulation services.
End User:
Automotive and industrial buyers command pricing power through volume commitments, while consumer electronics segments fragment procurement across numerous OEMs with shorter contract cycles.
- Consumer Electronics:Portable electronics manufacturers source cylindrical and button cells for digital cameras, wireless peripherals, and handheld gaming devices, with procurement shifting toward bundled battery-service subscriptions.
- Automotive:Hybrid electric vehicle programs in Japan anchor NiMH demand through multi-year supply agreements with cathode active material producers.
- Industrial:Professional power tool OEMs specify prismatic NiMH cells for contractor-grade equipment, with Southeast Asian manufacturing zones presenting underpenetrated demand for regional production scale.
- Telecommunications:Base station backup power systems specify valve-regulated lead-acid alternatives, limiting alkaline secondary penetration to remote tower installations requiring extreme temperature tolerance.
Industrial procurement absorbs the bulk of installed capacity for prismatic form factors; automotive contracts are climbing the fastest as hybrid production scales.
Application:
Energy storage and electric vehicle applications concentrate demand in high-volume formats, while power tools and renewable energy segments fragment across regional specifications.
- Energy Storage:Grid operators deploy alkaline secondary batteries for frequency regulation services, capitalizing on stable discharge characteristics without thermal management complexity. China's MEE emissions benchmarks for electrode manufacturing are tightening material sourcing rules for facilities supplying this segment.
- Electric Vehicles:Hybrid electric vehicles retain NiMH chemistry for safety-critical powertrains where thermal runaway tolerance outweighs energy density requirements.
- Power Tools:Cordless professional equipment specifies high-discharge-rate cylindrical cells for drilling, cutting, and fastening applications.
- Renewable Energy:Solar and wind integration projects specify alkaline secondary batteries for short-duration storage in off-grid installations.
Energy storage applications absorb the bulk of margin expansion; electric vehicle integration is gaining share fastest as hybrid platforms proliferate.
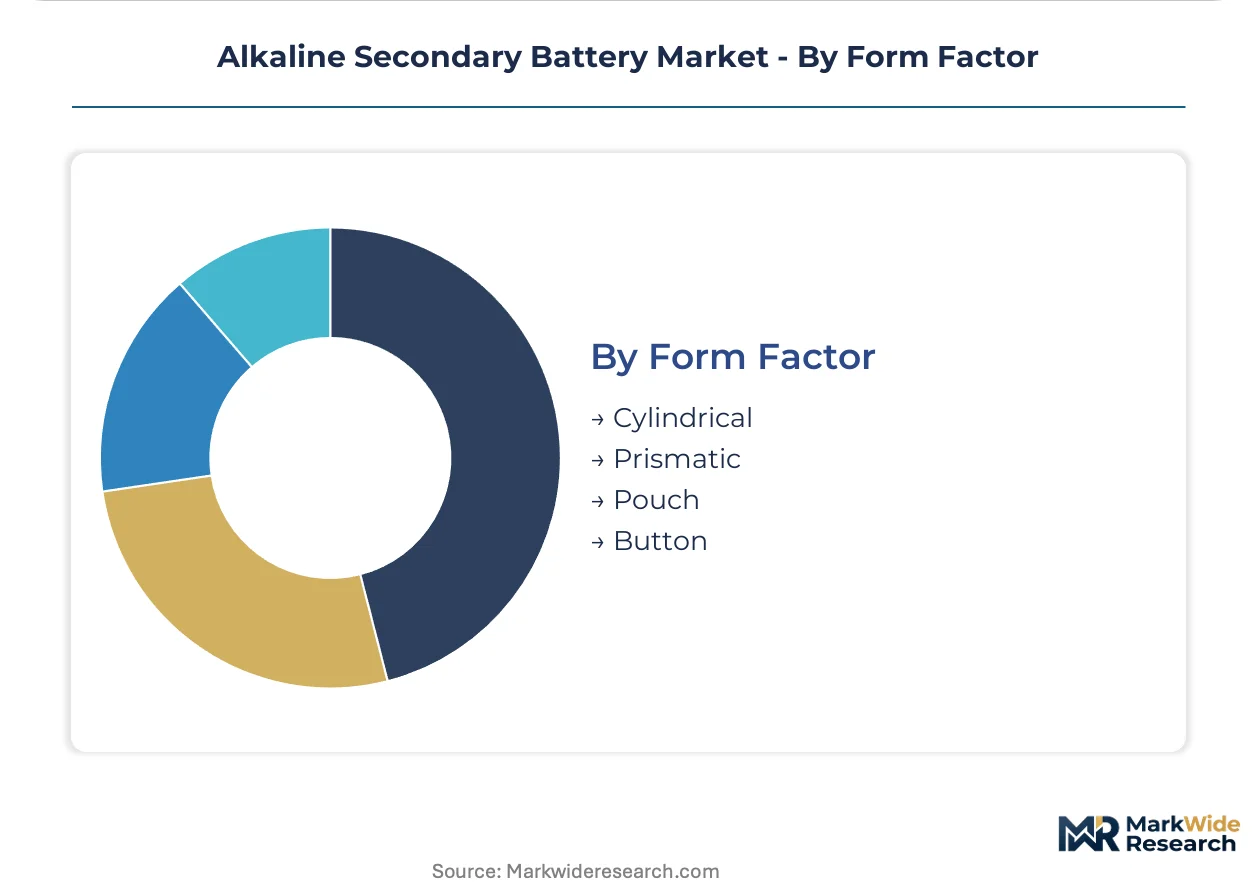
Form Factor:
Cylindrical tooling amortizes across the highest unit volumes, while prismatic and pouch formats require specialized winding and stacking equipment with longer changeover intervals.
- Cylindrical:Standardized diameters and lengths enable automated assembly lines with minimal retooling between cell capacities. The cylindrical segment faces steep compliance cost escalation under REACH carbon footprint disclosure mandates as legacy supply chains lack traceability infrastructure.
- Prismatic:Rectangular aluminum or steel can designs maximize volumetric efficiency for power tool and industrial applications. GP Batteries International Ltd. specializes in this format for regional manufacturing scale in Southeast Asia.
- Pouch:Flexible laminated film enclosures reduce casing weight for aerospace and premium consumer electronics applications.
- Button:Coin-shaped cells serve hearing aids, medical implants, and compact backup power functions with minimal self-discharge requirements.
Cylindrical formats absorb the bulk of unit volume; prismatic configurations are expanding most quickly in industrial power tool platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's battery materials refining corridor anchors global cathode active material production, with Japan's cathode zones and China's electrode manufacturing belt forming a triad of concentrated supply capacity.
Japan
Hybrid electric vehicle programs at Toyota and Honda drive NiMH procurement through multi-year cathode supply agreements. METI subsidizes domestic separator film and electrolyte salt production under supply chain resilience programs. The Kanto region around Tokyo hosts concentrated cathode active material production zones serving automotive tier-1 suppliers.
South Korea
Refining complexes in the Ulsan-Busan corridor process nickel and cobalt precursors for battery-grade cathode materials. The Ministry of Environment enforces emissions benchmarks that tighten electrode manufacturing compliance costs. Gyeonggi Province's material science clusters specialize in high-purity electrolyte formulations for cylindrical cell producers.
China
Dual carbon goals from MEE are accelerating cleaner production technology adoption across electrode coating facilities. The Yangtze River Delta manufacturing belt concentrates prismatic cell assembly for industrial power tool exports. Shenzhen and Dongguan house specialized winding equipment makers serving both domestic and Southeast Asian battery producers.
United States
Grid operators in Texas and California deploy alkaline secondary batteries for frequency regulation services requiring minimal thermal management. EPA hazardous waste rules elevate NiCd recycling infrastructure costs and restrict landfill access nationwide. The Midwest industrial corridor retains legacy cylindrical cell assembly for power tool OEM supply contracts.
Germany
Industrial procurement teams at power tool manufacturers specify REACH-compliant NiMH cells with documented carbon footprint disclosures. The EU Battery Regulation mandates recycled content thresholds that reshape material sourcing networks for European-market cells. Baden-Württemberg's precision manufacturing clusters host testing laboratories certifying electrolyte formulations to IEC safety standards.
Alkaline Secondary Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across cathode material integration and regulatory compliance capabilities. The vendor base separates into integrated chemical producers, branded cell assemblers, and regional contract manufacturers with limited upstream control. Three archetypes dominate: backward-integrated Japanese conglomerates with captive cathode supply, North American brand owners with retail channel dominance, and Southeast Asian scale producers serving industrial power tool OEMs. Competitive moves concentrate on separator film localization subsidies and electrolyte qualification acceleration.
Among Japan-based integrated producers, Panasonic Corporation and FDK Corporation occupy positions defined by upstream control over cathode active materials and hybrid automotive supply relationships. Energizer Holdings Inc. anchors the branded-assembler archetype through North American retail network penetration. GP Batteries International Ltd. exemplifies the regional-scale specialist model with Southeast Asian manufacturing presence.
| Leading Market Players |
|---|
| Duracell Inc. |
| Energizer Holdings Inc. |
| Panasonic Corporation |
| Spectrum Brands Holdings Inc. |
| GP Batteries International Ltd. |
| Toshiba Corporation |
| FDK Corporation |
| Camelion Batterien GmbH |
| Gold Peak Industries (Holdings) Limited |
| Others |
Pricing and Supply Chain Analysis
EU Battery Regulation recycled content mandates are compelling manufacturers to reconfigure cathode active material sourcing networks, elevating costs for non-integrated producers while rewarding backward-integrated Japanese conglomerates with captive precursor refining capacity.
Pricing Analysis
Cycle-life guarantees in grid frequency regulation contracts anchor value-based pricing for industrial NiMH deployments. Pricing stratifies across premium, standard, and economy tiers based on carbon footprint disclosure grade and cathode nickel purity. Cost compression in cylindrical consumer segments is intensifying because REACH documentation requirements have added compliance overhead. Industrial power tool OEMs exhibit lowest price sensitivity due to equipment-lease bundling, while retail consumer channels face acute margin pressure.
Supply Chain Analysis
Freight cost volatility between South Korea's Ulsan-Busan refining corridor and Japan's Kanto cathode zones is reshaping regional procurement patterns. Supply concentrates in Japan, South Korea, and China's Yangtze River Delta manufacturing belt. Electrode coating lines draw from nickel sulfate, rare earth metal hydrides, and potassium hydroxide electrolyte inputs. Single-source vulnerability in separator film production creates structural exposure. Distribution runs through automotive tier-1 suppliers and power tool OEM direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's carbon footprint disclosure mandates have erected a compliance moat that favors incumbent producers with documented supply chain traceability and penalizes new entrants lacking certification infrastructure.
For Market Incumbents: Anticipate lithium-ion substitution pressure in consumer electronics by accelerating high-nickel cathode qualification for hybrid automotive contracts. Defend margin position through separator film localization subsidies under Japan's METI programs and electrolyte salt backward integration. For New Entrants and Emerging Players: Begin with Southeast Asian industrial power tool manufacturing zones where prismatic NiMH demand outpaces regional supply capacity. Target contractor-grade equipment OEMs with localized assembly and REACH-compliant carbon disclosure as the go-to-market wedge. For Investors and Strategic Acquirers: The window for entry favors integrated chemical producers with captive cathode precursor capacity and existing IEC safety certification. Long-term viability hinges on supply chain resilience programs and dual carbon compliance positioning. Watch for inflection when Japan's METI expands separator film subsidy scope to foreign-owned facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Refining | Captures margin pools concentrated in South Korea's nickel processing corridor and reduces EU Battery Regulation compliance costs. |
| Separator Film Localization Investment | Accesses METI supply chain resilience subsidies while insulating against logistics disruption in Japan's Kanto production zones. |
| High-Nickel Cathode Formulation Qualification | Secures multi-year procurement contracts with Toyota and Honda hybrid powertrain programs requiring thermal stability. |
| Carbon Footprint Disclosure Infrastructure | Enables REACH-compliant market access for European industrial buyers mandating documented mining origin and refining energy sources. |
| Prismatic Cell Capacity Expansion in Southeast Asia | Serves underpenetrated demand from professional power tool OEMs seeking regional manufacturing scale and reduced freight exposure. |
Research Methodology
Independent corroboration across primary interviews with cathode material procurement directors, electrode manufacturing plant managers, and grid operator storage planners underwrites the qualitative findings. Secondary validation draws from customs trade data, SEC filings of listed battery producers, METI subsidy program disclosures, and EU Battery Regulation implementation guidance. Bottom-up cell production estimates and top-down end-use demand aggregation triangulate market sizing.
Rate-of-change decomposition across cell chemistry, form factor, and end-use application dimensions structures the analytical framework. CAGRs derive from segment-level volume trajectories and value-per-unit assumptions across the projection horizon. Hybrid automotive production schedules, grid storage deployment pipelines, and power tool OEM inventory cycles constitute industry-specific forecast inputs.
Underlying measurement precision varies by segment; cylindrical consumer electronics and automotive NiMH contracts carry tighter precision than emerging energy storage applications. Forecasts reflect assumptions about regulatory implementation timelines and cathode material cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Printed Batteries Market
Batteries
Li-Ion Pouch Battery Market
Batteries
Aluminum Based Battery Market
Batteries
North Europe Battery Market
Batteries
Battery Maintainer Market
Batteries
Lithium Marine Battery Market
Batteries
Global Cylindrical Lithium Battery Pack Market
Batteries
18650 And 21700 Battery Market
Batteries
India Rechargeable Battery Market
Batteries
North America NMC Battery Pack Market
Batteries
Primary Lithium Battery Market
Batteries
Submarine Batteries Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Hybrid Flow Battery Market
Batteries
Micro Battery Market
Batteries
Cobalt-Free Battery Market