
 Absorbent Mats Market | 2026-2036
Absorbent Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbent Mats Market Analysis
Southeast Asia is reshaping competitive dynamics in absorbent mat production as Vietnam and Thailand add meltblown polypropylene capacity. 3M Company leverages its materials science portfolio to sustain premium positioning in industrial spill control applications. Kimberly-Clark anchors North American supply through its established healthcare and hygiene distribution infrastructure. New Pig Corporation specializes in channel control, operating a direct-to-industry model that bypasses traditional distributor networks.
Absorbent mats are engineered porous structures, typically constructed from meltblown polypropylene or natural fiber composites with absorption capacities ranging from 0.5 to 25 gallons per pad, designed to capture and immobilize liquid spills in industrial environments. Oil Absorbent products dominate volume flows across petrochemical and automotive end users, while Universal Absorbent variants command margin premiums through multi-liquid compatibility that reduces SKU complexity for procurement teams. Polypropylene-based materials lead on cost efficiency and chemical resistance, though Recycled Materials segments are gaining structural traction as ESG procurement criteria harden across European and North American manufacturing buyers.
The EPA's Spill Prevention, Control, and Countermeasure (SPCC) rules and OSHA workplace safety standards shape product performance requirements and compliance documentation burdens for U.S. manufacturers. REACH chemical safety classifications in Europe are forcing absorbent mat suppliers to reformulate treated surfaces and validate degradation profiles. Stakeholders must monitor how evolving extended producer responsibility frameworks for industrial consumables will alter cost allocation between manufacturers and end users.
Market Dynamics
EU REACH chemical safety classifications are forcing absorbent mat suppliers to reformulate treated surfaces and validate degradation profiles, compressing product development cycles while expanding compliance documentation burdens.
Growth Catalysts
- REACH Regulation Expansion:The EU's tightening chemical handling safety mandates are mandating upgraded workplace absorbent material specifications across German and French manufacturing facilities, accelerating replacement cycles for legacy inventory.
- Petrochemical Corridor Investment:Gulf Coast petrochemical operators in the United States are expanding spill containment infrastructure, concentrating demand for high-capacity oil absorbent products in Texas and Louisiana processing clusters.
- Meltblown Polypropylene Scale-up:Vietnam and Thailand are adding specialized nonwoven production lines, lowering input costs for regional converters and enabling competitive export positioning into European and North American markets.
Market Restraints
- Propylene Feedstock Volatility:Polypropylene resin prices fluctuate with crude oil and naphtha benchmarks, compressing margins for converters lacking long-term supply contracts or backward integration into polymer production.
- Asian Supply Concentration:Meltblown media production clusters heavily in Southeast Asian export zones, exposing buyers to freight rate spikes and port congestion risks during peak shipping seasons.
- Biodegradation Performance Gap:Natural fiber alternatives to synthetic absorbents exhibit inconsistent liquid retention under hydrocarbon exposure, limiting substitution in critical petrochemical containment applications.
Strategic Opportunities
- Extended Producer Responsibility Frameworks:Emerging EU regulations on industrial consumables are creating service-based revenue models where manufacturers retain ownership and handle end-of-life mat recovery.
- Healthcare Contamination Control:Hospital and pharmaceutical manufacturing facilities are adopting universal absorbent protocols for cytotoxic and biological spill management, opening premium specification channels.
- Direct-to-Industry Distribution:E-procurement platforms and specialized industrial supply marketplaces are enabling manufacturers to bypass traditional distributor markups and capture margin from mid-size manufacturing accounts.
Industry Challenges
- Cross-Border Certification Complexity:Suppliers must navigate divergent testing protocols between EPA SPCC documentation, REACH substance registration, and ISO 9001 quality management, extending product launch timelines.
- Legacy Inventory Integration:Industrial buyers maintain mixed absorbent stockpiles across multiple generations of product specifications, complicating unified procurement and compliance auditing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbent Mats Market |
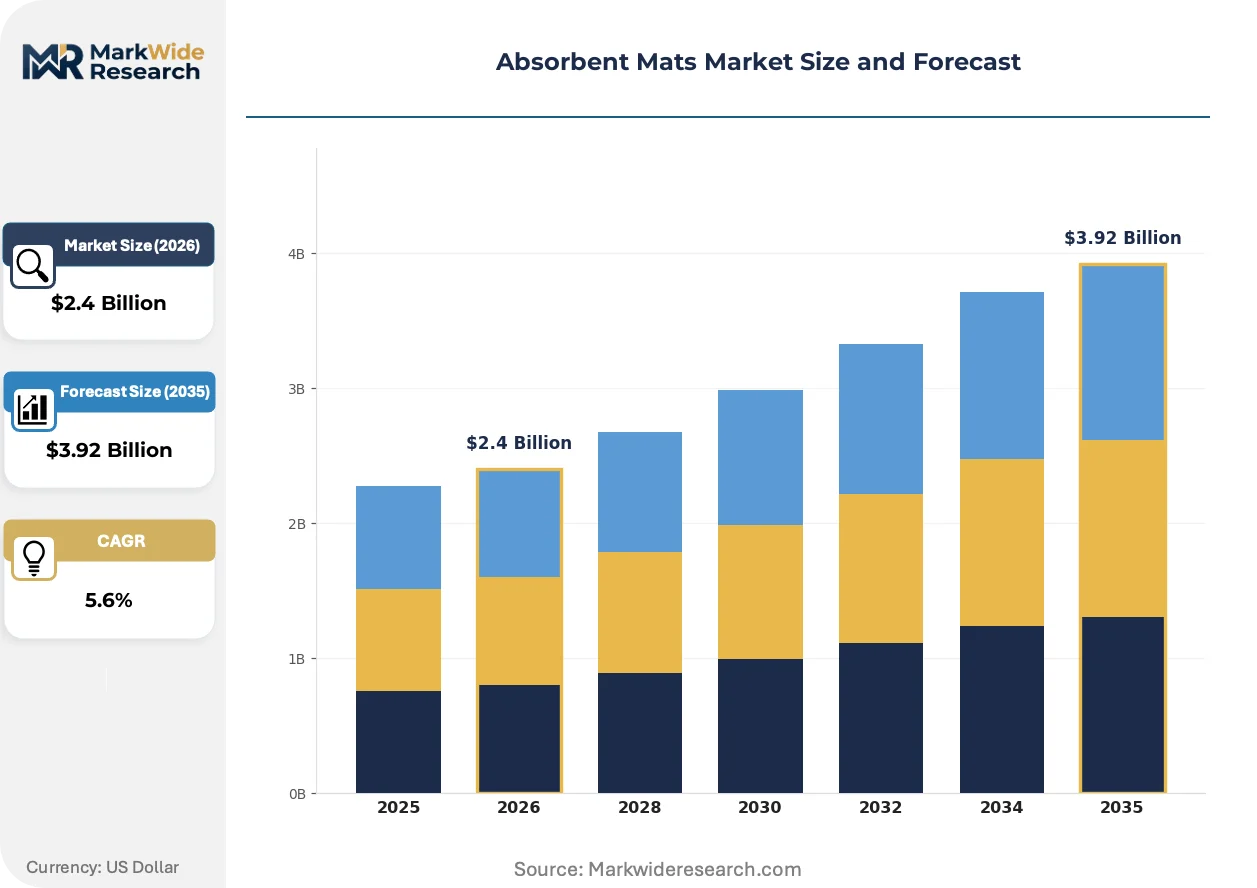
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil Absorbent, Universal Absorbent, Chemical Absorbent, Specialty Absorbent End User: Manufacturing, Automotive, Healthcare, Food Processing Material: Polypropylene, Natural Fibers, Composites, Recycled Materials Application: Spill Control, Maintenance, Cleaning, Safety Management |
| Companies Covered | SpillTech, Meltblown Technologies Inc., 3M Company, Avery Dennison Corporation, Kimberly-Clark, New Pig Corporation, Oil-Dri Corporation of America, Novipax LLC, Brady Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbent Mats Market Emerging Trajectories
Material science advances and regulatory stringency are converging to redefine performance benchmarks, with sustainability credentials and digital procurement integration emerging as decisive competitive differentiators.
Recycled polypropylene feedstock is migrating from niche sustainability positioning to mainstream industrial specifications. Automotive and aerospace manufacturing buyers in Germany and the United States are mandating post-consumer content thresholds in absorbent procurement tenders. This migration from virgin resin dependence is compressing price premiums for circular-economy-certified products and forcing conventional suppliers to secure recycled material supply chains.
REACH chemical safety classifications are forcing absorbent mat suppliers to reformulate treated surfaces and validate degradation profiles. Industrial users in European chemical processing and pharmaceutical manufacturing must now document absorbent material compatibility with specific substance categories. Oil absorbent segments face the steepest compliance burden, as hydrocarbon-specific treatments require re-registration under evolving hazard criteria.
Buyer consolidation among industrial distributors is compressing supplier negotiation leverage and accelerating private-label absorbent program expansion. Large maintenance, repair, and operations distributors in the United States are unbundling after-sales technical support to capture margin from mid-market manufacturing accounts. This channel restructuring is most visible across Midwest automotive supplier networks, where regional distributors are ceding share to national platforms with integrated e-procurement capabilities.
Absorbent Mats Market Segmentation
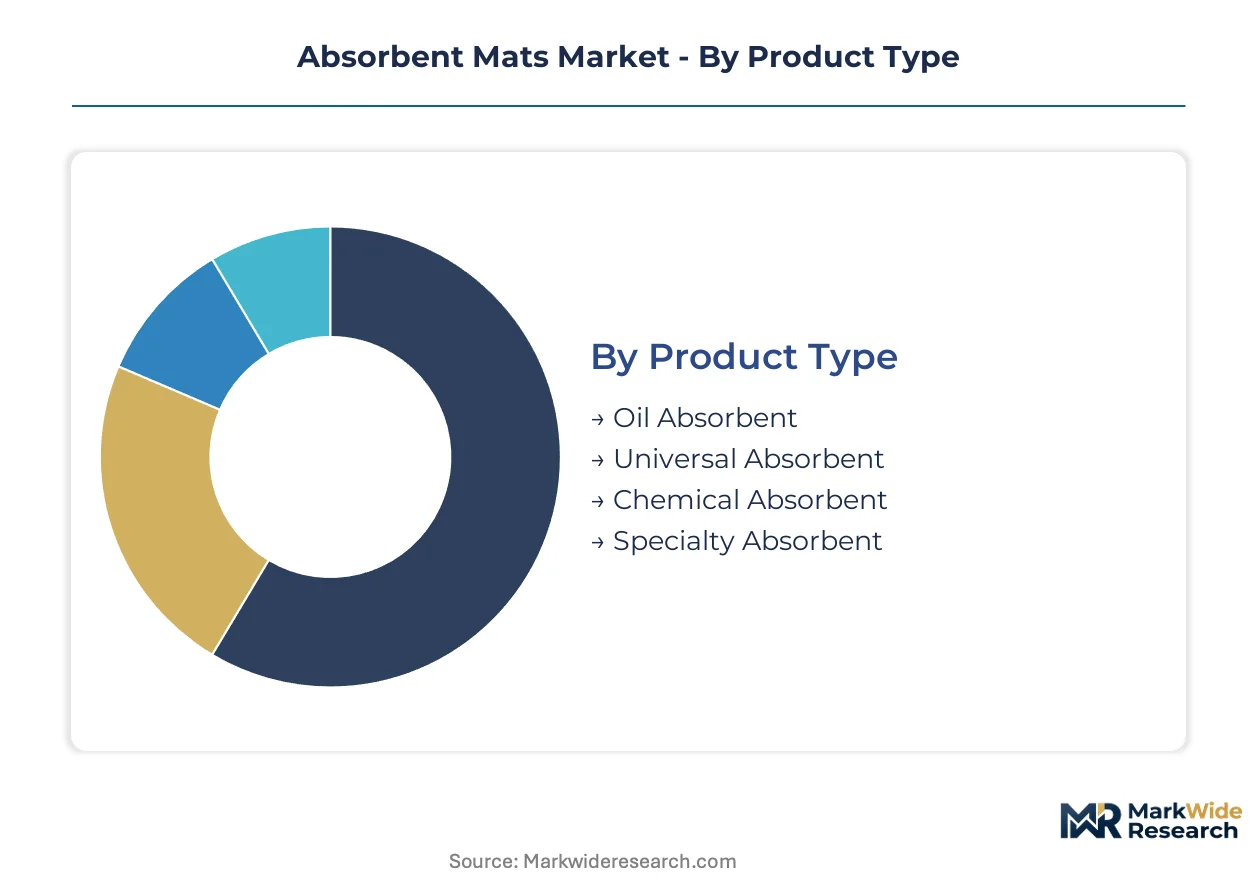
Segmentation in absorbent mats reveals divergent replacement rhythms across industrial environments. Product type and material composition determine procurement frequency, while end-user verticals impose distinct compliance documentation burdens that reshape vendor relationships.
Product Type:
Oil Absorbent pads turn over fastest in petrochemical corridors, while Specialty Absorbent variants persist longest due to customized specifications and lower incident frequency.
- Oil Absorbent:Engineered meltblown polypropylene structures with hydrophobic surface treatments selectively immobilize hydrocarbons while repelling aqueous solutions. Demand concentrates across Texas and Louisiana petrochemical processing clusters where EPA SPCC rules mandate continuous spill readiness. Gulf Coast operators absorb inventory volatility through blanket purchase agreements tied to crude throughput metrics.
- Universal Absorbent:Multi-liquid compatible constructions blend polypropylene with surfactant-treated layers for aqueous and solvent capture alike. German automotive manufacturers specify these variants to reduce SKU complexity across mixed-chemistry production floors. REACH substance registration requirements now force suppliers to document compatibility matrices for each treated surface formulation.
- Chemical Absorbent:Acid-resistant and caustic-specific formulations serve semiconductor and pharmaceutical manufacturing cleanrooms.
- Specialty Absorbent:Custom-dimensioned and color-coded variants address nuclear decommissioning and aerospace fuel cell containment protocols.
Oil Absorbent dominates installed base across heavy industry. Universal Absorbent is where expansion concentrates as procurement teams consolidate supplier rosters.
End User:
Cost tier stratification separates high-compliance healthcare procurement from price-sensitive food processing volumes, with automotive and manufacturing occupying intermediate positions.
- Manufacturing:General industrial facilities deploy high-volume standard pads across machining, assembly, and warehousing zones. Midwest metalworking clusters in the United States drive recurring demand through lean inventory practices that minimize on-hand safety stock.
- Automotive:OEM and tier-one suppliers mandate recycled content thresholds in absorbent procurement tenders. German passenger vehicle manufacturers now require post-consumer polypropylene certification for all non-critical spill containment materials.
- Healthcare:Hospital and pharmaceutical manufacturing facilities adopt universal absorbent protocols for cytotoxic and biological spill management.
- Food Processing:USDA-inspected facilities specify food-grade polypropylene with extractables testing to prevent contamination.
Manufacturing commands volume leadership across all geographies. Healthcare is climbing the fastest as contamination control protocols harden.
Material:
Supply concentration in Southeast Asian meltblown production creates divergent landed cost structures between virgin polypropylene and recycled alternatives.
- Polypropylene:Virgin resin-based meltblown media deliver superior chemical resistance and consistent absorption capacity across temperature extremes. Vietnamese and Thai production lines now supply European converters at cost advantages that compress margin structures for North American domestic producers lacking long-term feedstock contracts.
- Recycled Materials:Post-consumer polypropylene feedstock migrates from niche sustainability positioning to mainstream industrial specifications. Automotive and aerospace manufacturing buyers in Germany and the United States now mandate minimum recycled content thresholds in tender documents.
- Natural Fibers:Cellulosic and cotton-based alternatives serve applications demanding biodegradation certification.
- Composites:Layered constructions combining synthetic and natural elements balance performance with environmental claims.
Polypropylene dominates current procurement volumes. Recycled Materials is where specification momentum is concentrating fastest.
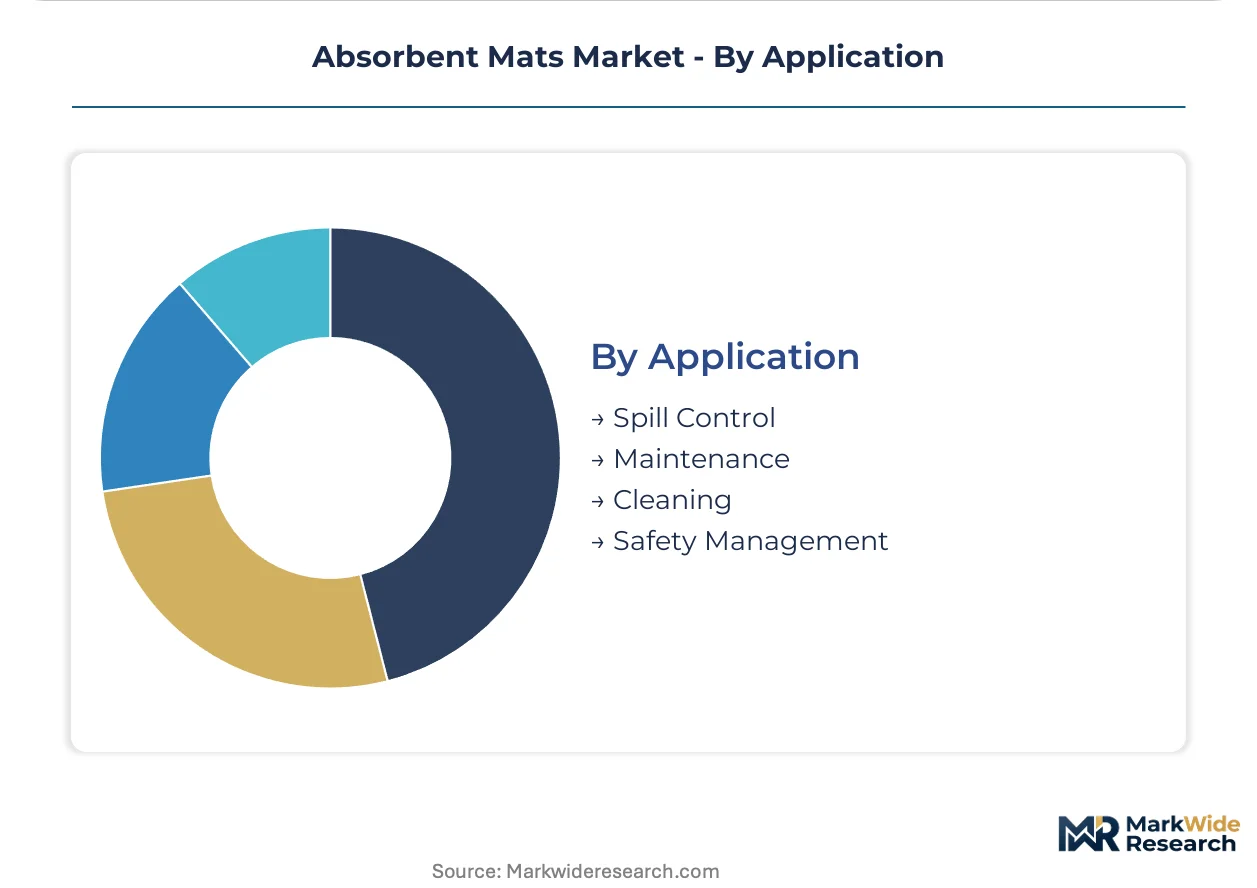
Application:
Customer type segmentation separates reactive incident response from preventive maintenance programs, with divergent margin structures across each.
- Spill Control:Emergency response deployments require rapid-deployment formats with high capacity-to-weight ratios. Petrochemical operators stockpile oil-specific variants in weatherproof caddies positioned throughout processing units.
- Maintenance:Scheduled equipment servicing drives predictable consumption patterns with long-term contract pricing. Automotive assembly plants in the United States negotiate annual volume commitments that lock in resin cost pass-through mechanisms.
- Cleaning:Routine facility hygiene applications favor economy-tier specifications with lower absorption capacity requirements.
- Safety Management:Regulatory compliance documentation drives premium positioning for certified and traceable product lines.
Spill Control anchors revenue through emergency procurement premiums. Maintenance is where contract duration and customer lifetime value are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian meltblown polypropylene capacity additions in Vietnam and Thailand are compressing input costs for regional converters and reshaping export competitiveness into European and North American markets. German manufacturing facilities are accelerating absorbent mat procurement to meet tightening EU REACH compliance deadlines. Gulf Coast petrochemical corridors in Texas and Louisiana concentrate emergency spill containment demand.
United States
EPA SPCC rules mandate continuous spill readiness across Texas and Louisiana petrochemical processing clusters. Gulf Coast operators negotiate blanket purchase agreements tied to crude throughput metrics. Midwest automotive supplier networks in Michigan and Ohio are consolidating procurement through integrated e-procurement platforms.
Germany
EU REACH chemical safety classifications are forcing absorbent mat suppliers to reformulate treated surfaces and validate degradation profiles. German automotive OEMs now require post-consumer polypropylene certification for non-critical spill containment materials. Industrial manufacturing facilities in Bavaria and North Rhine-Westphalia are expanding absorbent mat procurement for compliance.
Vietnam
Specialized nonwoven production lines are lowering input costs for regional converters and enabling competitive export positioning. Vietnamese meltblown media producers supply European converters at cost advantages that compress margin structures for North American domestic producers. Manufacturing zones near Ho Chi Minh City anchor expanding polypropylene processing capacity.
Thailand
Thai production lines are adding meltblown polypropylene capacity that serves regional demand and export markets alike. The country's central location within ASEAN trade corridors supports logistics efficiency for absorbent mat distribution. Industrial estates in the Eastern Economic Corridor concentrate expanding nonwoven manufacturing infrastructure.
China
Domestic absorbent mat production serves massive internal manufacturing demand while selective exporters target premium European specifications. Chinese chemical processing and electronics manufacturing facilities drive volume consumption of universal absorbent variants. Yangtze River Delta industrial clusters concentrate both production capacity and end-user demand.
Absorbent Mats Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower portfolios but deeper process expertise. The vendor base separates into three strategic tiers: diversified materials science conglomerates with cross-industrial portfolios, specialized industrial hygiene manufacturers with dedicated spill control divisions, and focused absorbent product specialists operating direct-to-industry models. Consolidation pressure is intensifying through distributor private-label expansion and backward integration by large chemical processors seeking captive supply security.
Within the diversified materials science tier, 3M Company and Kimberly-Clark exemplify platform breadth that spans healthcare, industrial, and consumer applications. New Pig Corporation occupies a distinct position as a specialized direct-to-industry operator bypassing traditional distributor networks. These three anchors illustrate divergent competitive strategies: portfolio leverage against channel control against vertical focus.
| Leading Market Players |
|---|
| SpillTech |
| Meltblown Technologies Inc. |
| 3M Company |
| Avery Dennison Corporation |
| Kimberly-Clark |
| New Pig Corporation |
| Oil-Dri Corporation of America |
| Novipax LLC |
| Brady Corporation |
| Others |
Supply Flow & Price Mechanics
Shanghai-Rotterdam container freight corridors transmit cost volatility from Southeast Asian meltblown polypropylene clusters to European converters, amplifying price spreads between virgin resin and recycled feedstock tiers while compressing margins for distributors lacking long-term supply contracts.
Pricing Analysis
EPA SPCC and EU REACH chemical safety classifications dictate the pricing tier structure across the absorbent mats market. Certification-grade differentiation separates premium REACH-compliant formulations from standard industrial specifications, with economy tiers serving non-regulated maintenance applications. Cost compression in standard-grade polypropylene absorbents is intensifying because Vietnamese and Thai production lines are flooding export markets with competitively priced meltblown media. Food processing and general manufacturing buyers exhibit highest price sensitivity, while pharmaceutical and semiconductor facilities prioritize compliance documentation over unit cost.
Supply Chain Analysis
Extended payment terms from Vietnamese and Thai producers to European converters are financing inventory positions through peak shipping seasons. Raw material sourcing draws from Saudi and Qatari propylene feedstock, Chinese naphtha crackers, and recycled polypropylene collectors in Germany and the United States. Single-source vulnerability concentrates in Ho Chi Minh City and Bangkok production zones, where port congestion during monsoon seasons disrupts delivery schedules. Distribution runs through integrated industrial supply marketplaces and traditional MRO distributors serving Midwest automotive and Gulf Coast petrochemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized nonwoven production expertise sits in short supply relative to accelerating demand for REACH-compliant formulations, constraining capacity expansion timelines for converters attempting to capture specification premiums.
For Market Incumbents: Harden technical documentation capabilities to defend against private-label expansion by large MRO distributors unbundling after-sales support. Secure backward integration into recycled polypropylene collection networks in Germany and the United States to meet automotive OEM content mandates. Channel control through direct-to-industry e-procurement platforms offers the strongest defensive lever against margin compression. For New Entrants and Emerging Players: Central and Eastern European manufacturing corridors present the most penetrable geography, where REACH compliance deadlines are tightening faster than local converter capacity can respond. Target mid-size chemical processors seeking captive supply security through toll manufacturing arrangements. A service-based revenue model retaining end-of-life mat ownership under emerging extended producer responsibility frameworks bypasses established distributor relationships entirely. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified materials science conglomerates where absorbent product lines represent non-core industrial hygiene exposure. Long-term viability hinges on securing recycled feedstock supply chains ahead of hardened ESG procurement criteria across European and North American manufacturing buyers. Monitor REACH substance re-registration timelines as the critical inflection signal for product line obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Secures post-consumer polypropylene supply for German automotive OEM certification mandates. |
| REACH Compliance Documentation Investment | Accelerates product launch timelines for hydrocarbon-specific absorbent formulations. |
| Direct-to-Industry E-Procurement Platform | Bypasses distributor markups to capture margin from mid-size manufacturing accounts. |
| Extended Producer Responsibility Service Model | Transforms transactional product sales into recurring revenue through end-of-life recovery. |
| Southeast Asian Production Partnership | Accesses Vietnamese and Thai meltblown capacity at cost advantages compressing North American domestic margins. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with plant managers, procurement leads at petrochemical operators, MRO distribution channel partners, and technical R&D directors at nonwoven converters; alongside secondary validation through customs and trade data, EPA SPCC enforcement records, ECHA REACH substance registrations, and SEC filings from disclosed market participants. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Forecast inputs span product type segmentation across oil, universal, chemical, and specialty absorbent variants; material composition tiers from virgin polypropylene through recycled and natural fiber alternatives; and end-user verticals spanning manufacturing, automotive, healthcare, and food processing. CAGRs were derived from replacement cycle analysis, regulatory compliance-driven upgrade timelines, and capacity expansion announcements across Southeast Asian production zones. Feedstock cost pass-through mechanisms and freight rate volatility shaped regional price trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by petrochemical operators or accelerated private-label expansion by national MRO platforms would shift outcomes. Macroeconomic deviation, regulatory reclassification of treated surface chemistries, or breakthrough biodegradation performance in natural fiber alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Antimicrobial Textiles Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Global Biomedical Textiles Market
Medical and Hygiene Textiles
Global Diabetic Socks Market
Medical and Hygiene Textiles
Global Antimicrobial Medical Textiles Market
Medical and Hygiene Textiles
United States Sanitary Napkin Market
Medical and Hygiene Textiles
Latin America Sanitary Napkin Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market
Medical and Hygiene Textiles
Feminine Wipes Market
Medical and Hygiene Textiles
North America Sanitary Napkin Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Europe Sanitary Napkin Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Intestinal Wash Bags Market
Medical and Hygiene Textiles
Tissue Towel Market