
 North America Vaccines Market | 2026-2036
North America Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vaccines Market Outlook
Adult and adolescent populations are reorganizing demand patterns as public health programs broaden age-based immunization coverage. Pfizer Inc. leverages its mRNA manufacturing infrastructure to sustain supply commitments across seasonal and pandemic formulations. Merck & Co., Inc. anchors its position through vertical control over viral vector production and long-standing pediatric franchise relationships. Moderna, Inc. competes by specializing in respiratory virus combinations and rapid platform adaptability.
North America vaccines comprise biologically active preparations containing antigens—proteins, polysaccharides, or nucleic acids—formulated to elicit protective immune responses, with stability profiles typically requiring cold-chain maintenance between two and eight degrees Celsius for conventional products. Their commercial purpose centers on preventing infectious morbidity and reducing healthcare system burden through population-level immunization. mRNA platforms represent the fastest-expanding product category, driven by shortened development cycles and adaptable manufacturing. Government programs channel the dominant distribution flow, capturing volume through CDC and Public Health Agency of Canada procurement mechanisms. Oncology vaccines occupy an emerging therapy area where therapeutic rather than prophylactic mechanisms create distinct margin dynamics.
The FDA and Health Canada enforce lot-release testing and facility inspection regimes that shape market access timelines and compliance costs for all manufacturers. CDC advisory committee recommendations and the National Advisory Committee on Immunization in Canada directly determine public formulary inclusion and reimbursement scope. Stakeholders must monitor platform diversification into combination respiratory vaccines and the evolving regulatory posture toward gene-based therapeutics.
Market Dynamics
FDA accelerated approval pathways for mRNA platforms compress development timelines from years to months, while CDC procurement mechanisms concentrate volume allocation among manufacturers with established cold-chain infrastructure.
Growth Catalysts
- Expanded Pediatric Schedules:United States and Canada immunization programs now cover adolescent and adult populations beyond traditional childhood frameworks, broadening addressable patient bases.
- Platform Adaptability:mRNA manufacturing infrastructure permits rapid antigen redesign for seasonal variants without facility retooling, shortening response cycles for respiratory pathogens.
- Federal Procurement Mechanisms:CDC bulk purchasing and Public Health Agency of Canada national contracts guarantee volume commitments that de-risk manufacturing scale-up investments.
Market Restraints
- Cold-Chain Dependency:Conventional vaccines require uninterrupted two-to-eight-degree Celsius logistics, limiting distribution reach to regions with validated infrastructure.
- Regulatory Lot-Release Testing:FDA and Health Canada mandatory batch verification creates six-to-twelve-week access delays that compress effective patent windows.
- Specialized Manufacturing Concentration:Viral vector production capacity clusters among three North American contract manufacturers, creating single-source vulnerability for novel platform entrants.
Strategic Opportunities
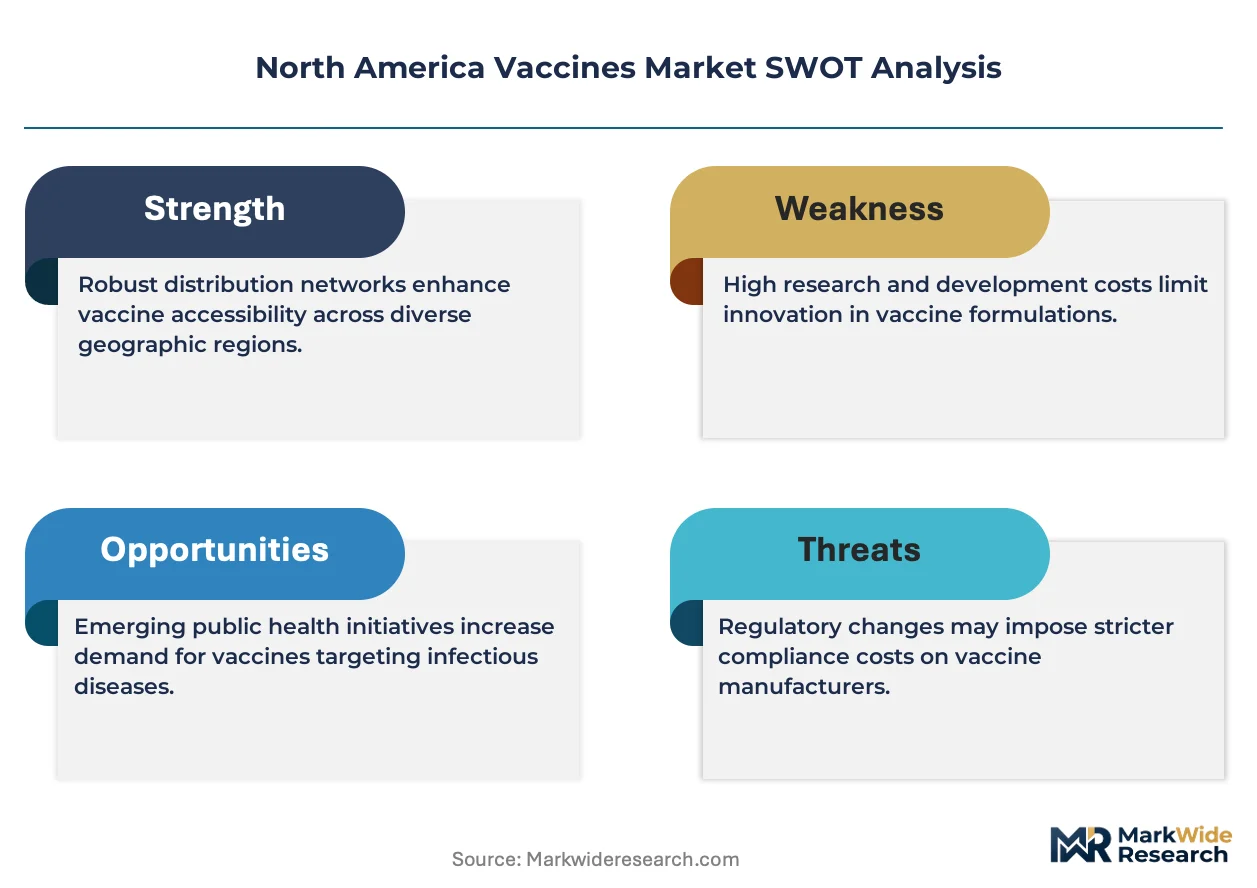
- Therapeutic Oncology Vaccines:Immuno-oncology applications shift margin dynamics from prevention to treatment, commanding reimbursement premiums in United States Medicare frameworks.
- Combination Respiratory Formulations:COVID-influenza-RSV trivalent candidates address polyvalent demand from United States pharmacy chains and Canadian provincial formularies.
- Gene-Based Therapeutic Pathways:FDA emerging guidance on nucleic acid therapeutics creates regulatory clarity that attracts platform diversification beyond infectious disease.
Industry Challenges
- Bioprocessing Talent Scarcity:Cell culture and aseptic fill-finish expertise concentrates among legacy vaccine manufacturers, constraining workforce mobility for new entrants.
- Legacy System Integration:Electronic batch record systems from 1990s-era facilities require costly validation upgrades to meet FDA data integrity expectations for continuous manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vaccines Market |
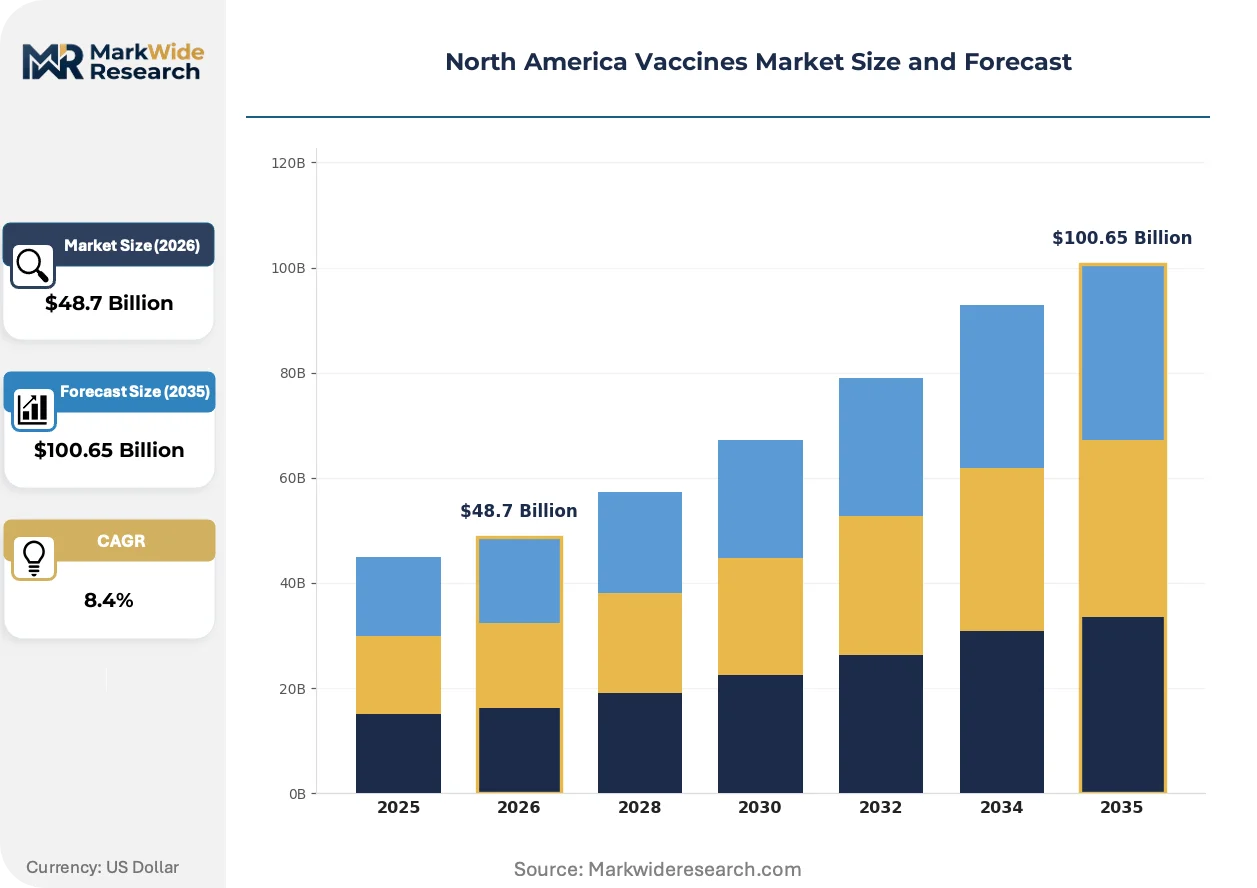
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Subunit, mRNA End User: Hospitals, Clinics, Pharmacies, Research Institutions Distribution Channel: Direct Sales, Wholesale, Retail, Government Programs Therapy Area: Pediatrics, Infectious Diseases, Travel Health, Oncology |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., GSK plc, Sanofi, CSL, Moderna, Inc., AstraZeneca, Johnson & Johnson Services, Inc., Emergent BioSolutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vaccines Market Strategic Shifts
mRNA platform standardization is fragmenting competitive moats as manufacturing know-how diffuses beyond pioneer firms, forcing differentiation through formulation stability and combination product design rather than process exclusivity.
Self-amplifying RNA constructs reduce antigen-encoding payload requirements by triggering intracellular replication machinery. United States biomanufacturers are adopting these architectures for pandemic preparedness stockpiles. The technology is decomposing traditional dose-volume constraints that previously limited multi-valent product feasibility.
Health Canada and FDA alignment on post-market pharmacovigilance data sharing accelerates safety signal detection across North American jurisdictions. Manufacturers must now integrate cross-border adverse event reporting systems. Pediatric combination products face heightened scrutiny under this harmonized framework.
United States hospital systems and Canadian provincial health authorities are consolidating vaccine procurement into multi-year sole-source agreements that exchange volume guarantees for price caps. Group purchasing organizations displace fragmented physician-office purchasing. This concentration is most pronounced in United States integrated delivery networks managing employee health populations.
North America Vaccines Market Segmentation
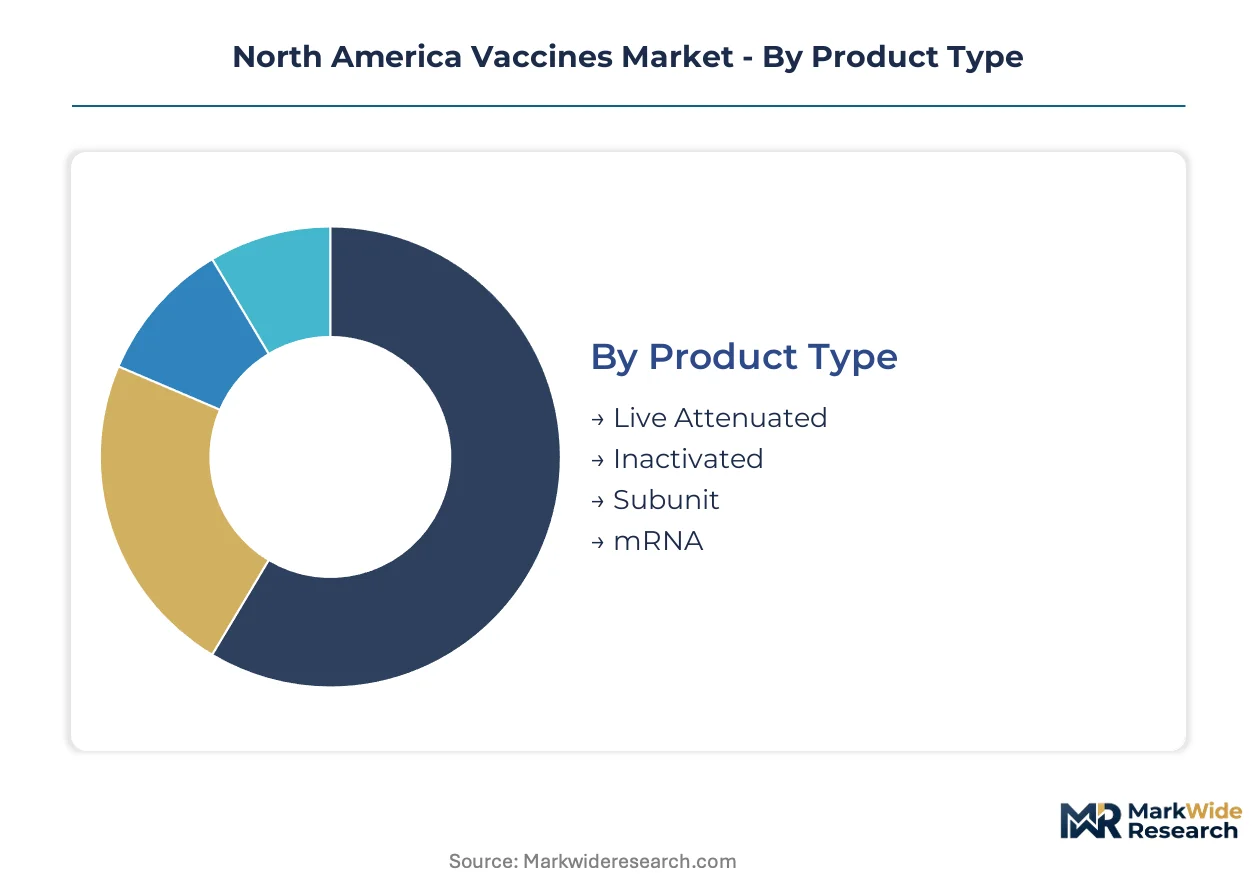
Segmentation in the North America vaccines market reveals how regulatory pathways, procurement mechanisms, and cold-chain infrastructure reshape commercial priorities across product categories and customer channels. Understanding these divides exposes where margin pools concentrate versus where volume guarantees stabilize manufacturing investments.
Product Type:
FDA lot-release protocols and Health Canada stability requirements create divergent compliance burdens that segment manufacturers by platform maturity and facility investment thresholds.
- mRNA:Nucleic acid constructs formulated in lipid nanoparticles enable rapid antigen redesign without cell culture infrastructure. United States federal stockpiling programs and Canadian pandemic preparedness contracts concentrate demand for respiratory applications, compressing development timelines from years to months through accelerated approval pathways.
- Live Attenuated:Weakened pathogen formulations elicit durable cellular immunity with reduced dosing schedules. Pediatric immunization schedules across United States CDC programs and Canadian provincial formularies anchor volume, though cold-chain sensitivity and contraindication screening limit pharmacy distribution reach.
- Inactivated:Killed pathogen preparations rely on alum or novel adjuvant systems to boost immunogenicity. Travel health clinics and occupational health programs in United States border states drive seasonal procurement.
- Subunit:Purified protein or polysaccharide antigens minimize reactogenicity for immunocompromised populations. Medicare reimbursement frameworks in the United States support adult indications including shingles and pneumococcal disease.
Established volume favors live attenuated platforms in pediatric channels; emerging adoption favors mRNA in respiratory and therapeutic applications.
End User:
Procurement scale and reimbursement complexity sort end users into distinct margin tiers, with integrated delivery networks commanding price concessions unavailable to fragmented physician practices.
- Hospitals:Inpatient and emergency department administration captures high-acuity indications including rabies post-exposure and tetanus prophylaxis. United States health systems leverage group purchasing organization contracts to consolidate volume across multi-hospital networks, exchanging price caps for sole-source commitments.
- Pharmacies:Community and retail clinic settings handle seasonal influenza and COVID-19 boosters through standing orders from state pharmacy boards. CVS Health, Walgreens Boots Alliance, and independent chains in the United States plus Shoppers Drug Mart and Rexall in Canada dominate walk-in immunization volume.
- Clinics:Federally qualified health centers and rural health clinics serve underinsured populations through CDC Vaccines for Children program allocations. Reimbursement rates lag hospital outpatient departments but volume guarantees offset margin compression.
- Research Institutions:Academic medical centers and contract research organizations manage Phase III trial supply and early-access programs for novel oncology vaccines. FDA investigational new drug oversight and institutional review board protocols govern procurement.
Price discipline concentrates in pharmacy chains with national footprints; margin protection persists in hospital systems with captive patient populations.
Distribution Channel:
Cold-chain validation requirements and lot-traceability mandates stratify channels by infrastructure investment intensity, favoring established distributors with validated temperature monitoring systems.
- Government Programs:CDC centralized purchasing and Public Health Agency of Canada national contracts allocate volume through Vaccines for Children and provincial immunization programs. These mechanisms de-risk manufacturing scale-up but impose price caps and sole-source bidding requirements that compress supplier margins.
- Wholesale:McKesson, AmerisourceBergen, and Cardinal Health in the United States plus McKesson Canada dominate third-party logistics for private-market vaccines. Their distribution centers maintain two-to-eight-degree Celsius validation required for conventional products.
- Direct Sales:Manufacturers with captive field forces bypass distributors for large hospital system accounts, preserving price control and service differentiation. This channel carries highest operational overhead but protects margin in oncology and travel health segments.
- Retail:Limited to over-the-counter travel vaccines in some Canadian provinces and select United States jurisdictions with pharmacist prescribing authority. Regulatory fragmentation constrains scalability.
Volume security concentrates in government procurement; margin expansion depends on direct sales penetration in specialty therapeutic categories.
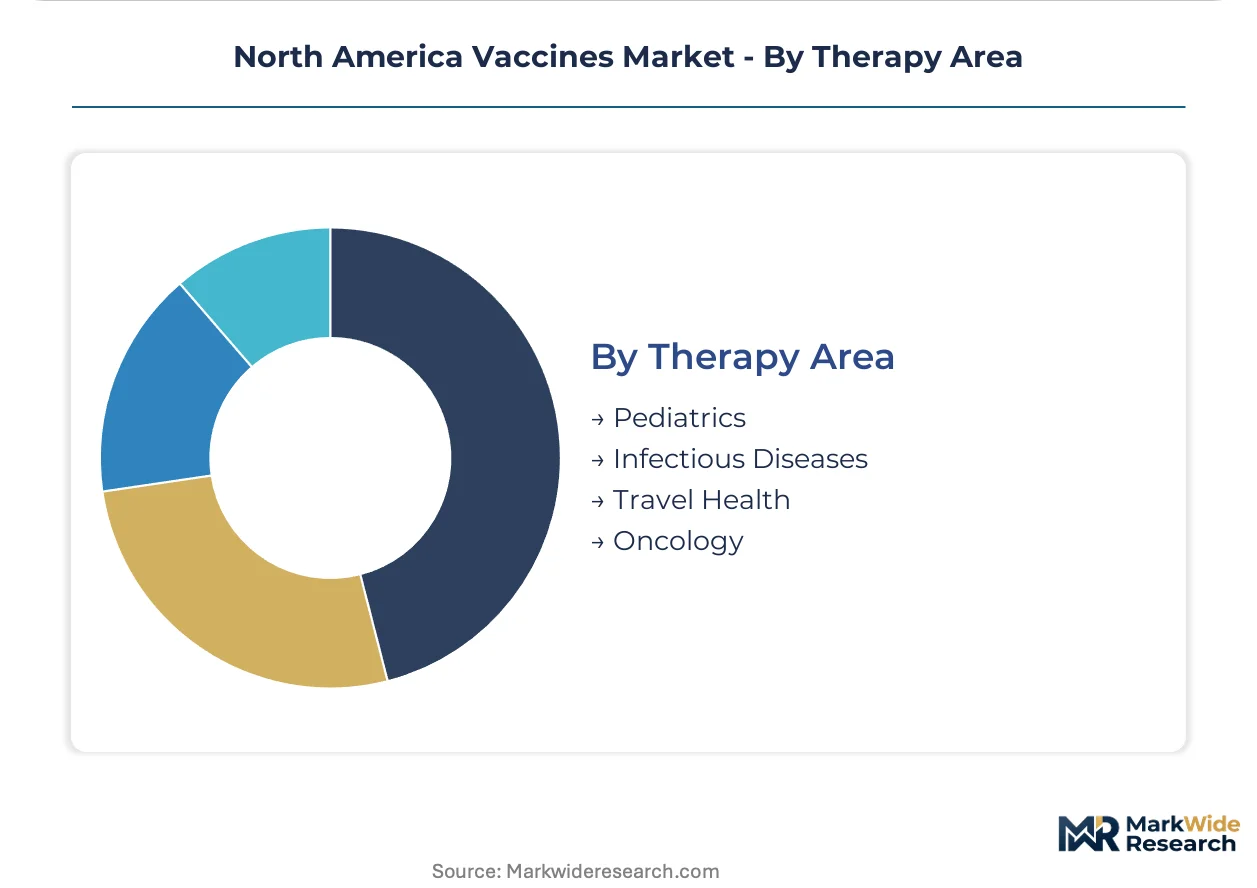
Therapy Area:
Reimbursement pathway differentiation—preventive versus therapeutic, pediatric versus adult—creates distinct margin dynamics that attract platform investment toward oncology and away from commodified infectious disease prophylaxis.
- Oncology:Therapeutic cancer vaccines including personalized neoantigen approaches command Medicare Part B reimbursement at administered-drug rates rather than preventive vaccine schedules. United States academic medical centers and Canadian cancer centers pilot these modalities through FDA breakthrough therapy and Health Canada priority review designations.
- Pediatrics:Routine immunization schedules against measles, pertussis, and varicella generate volume through CDC Advisory Committee on Immunization Practices recommendations. Combination products reduce injection burden but face manufacturing complexity penalties.
- Infectious Diseases:Adult pneumococcal, hepatitis B, and herpes zoster vaccines serve aging populations through Medicare Part D and provincial drug plans in Canada. Seasonal influenza demand fluctuates with variant prediction accuracy.
- Travel Health:Yellow fever, typhoid, and Japanese encephalitis vaccines serve pre-travel consultation markets concentrated in coastal United States cities and Toronto/Vancouver metropolitan areas. CDC travel health notices drive episodic demand spikes.
Prevention economics dominate pediatric and infectious disease segments; treatment premiums attract platform innovation toward oncology applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The CDC's Vaccines for Children distribution hub in Atlanta anchors North American supply chain architecture, with cold-chain validated air corridors linking manufacturing clusters to federal stockpile facilities.
United States
Pediatric immunization schedules and Medicare Part D adult coverage drive procurement volume. FDA accelerated approval pathways for mRNA platforms compress development timelines from years to months. The Research Triangle Park in North Carolina hosts contract manufacturing organizations scaling viral vector production for platform diversification.
Canada
Provincial immunization programs and federal pandemic preparedness contracts stabilize demand forecasting. Health Canada lot-release testing and facility inspection regimes shape market access timelines for all manufacturers. Toronto and Vancouver metropolitan areas concentrate travel health clinic networks serving pre-departure consultation markets.
Mexico
Cross-border cold-chain logistics and maquiladora zone biomanufacturing investments expand regional supply capacity. COFEPRIS regulatory alignment with FDA standards accelerates product registration for North American market access. Baja California and Mexico City host emerging fill-finish operations serving United States distribution networks.
North America Vaccines Market Competitive Environment
Concentration sits with legacy pharmaceutical conglomerates possessing integrated manufacturing infrastructure and long-standing government procurement relationships. The vendor base stratifies across three tiers: vertically integrated innovators controlling platform technology, mid-scale specialists with regional distribution networks, and contract manufacturers serving platform-agnostic production demand. Dominant competitive moves include strategic partnerships for mRNA lipid nanoparticle supply and capacity expansion into combination respiratory vaccine formulations.
Among United States-based innovators, Pfizer Inc., Moderna, Inc., and Merck & Co., Inc. exemplify distinct strategic archetypes. Pfizer Inc. represents platform diversification through lipid nanoparticle manufacturing scale. Moderna, Inc. occupies a position emphasizing respiratory virus specialization and rapid antigen redesign capabilities. Merck & Co., Inc. anchors the traditional pediatric franchise segment through viral vector production control.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| GSK plc |
| Sanofi |
| CSL |
| Moderna, Inc. |
| AstraZeneca |
| Johnson & Johnson Services, Inc. |
| Emergent BioSolutions |
| Others |
Value Chain & Pricing Dynamics
Multi-dose vial scale economies in United States bulk procurement anchor price floors across pediatric and adult immunization tiers, concentrating manufacturing investment toward CDC-allied contract manufacturers and compressing margin structures for second-source entrants lacking comparable volume guarantees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels sorts manufacturers by FDA lot-release certification status and cold-chain validation investment. Premium tiers capture mRNA platform products with lipid nanoparticle formulation complexity; economy tiers serve inactivated vaccines for government stockpiles. Price differentiation stems from adjuvant technology licensing fees and pediatric combination product manufacturing complexity. Cost compression in standard-tier pneumococcal and influenza vaccines intensifies as pharmacy chain consolidation concentrates buyer power. Federally qualified health centers exhibit highest price sensitivity; integrated delivery networks with captive populations show lowest sensitivity due to Medicare reimbursement rate protection.
Supply Chain Analysis
The United States anchors lipid nanoparticle formulation and fill-finish capacity; Canada concentrates viral vector production through Toronto-area contract manufacturers; Mexico supplies glass vial and syringe components through Baja California maquiladora operations. Raw material dependencies center on cholesterol derivatives for mRNA delivery systems, specialized cell culture media for viral propagation, and borosilicate glass for thermal stability. Single-source vulnerability concentrates in lipid nanoparticle lipid supply, where three specialty chemical producers serve North American demand. Distribution runs through CDC centralized allocation for public programs and McKesson-validated cold-chain networks for private-market pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vaccine service-attach opportunities concentrate in cold-chain monitoring subscriptions and lot-release testing acceleration services, with recurring revenue layers in logistics validation expanding faster than antigen manufacturing hardware across the analysis window.
For Market Incumbents: Secure sole-source CDC contract renewals through pandemic preparedness stockpile commitments and pediatric combination product exclusivity. Threat from self-amplifying RNA platform entrants with reduced dose-volume requirements demands backward integration into lipid nanoparticle lipid supply to preserve margin structures against commodification pressure. For New Entrants and Emerging Players: Differentiate on thermostable formulation platforms that bypass two-to-eight-degree Celsius infrastructure requirements for pharmacy direct distribution. White-space targets include therapeutic oncology vaccines in Medicare Part B reimbursement pathways and travel health clinic networks in Toronto and Vancouver metropolitan areas. Go-to-market angle should emphasize rapid Health Canada lot-release timelines through prior FDA approval reciprocity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-agnostic contract manufacturers with viral vector and mRNA dual capability over single-platform pure-plays. Long-term viability rests on therapeutic vaccine pipeline optionality beyond infectious disease prophylaxis. Acquisition target archetype: mid-scale specialists with Health Canada inspection history and provincial formulary relationships. Signal to watch is FDA guidance clarity on gene-based therapeutic pathways as inflection indicator for platform diversification capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | CDC bulk purchasing commitments de-risk capital deployment for mRNA facility expansion in Research Triangle Park. |
| Regulatory Approval Pathway | FDA accelerated approval for combination respiratory vaccines compresses development timelines versus sequential indication pursuit. |
| Licensing Agreement | Lipid nanoparticle formulation partnerships with specialty chemical producers secure supply continuity for pandemic response manufacturing. |
| Pipeline Diversification | Therapeutic oncology vaccine candidates access Medicare Part B reimbursement premiums unavailable to preventive indications. |
| Hospital System Partnership | Sole-source agreements with United States integrated delivery networks exchange volume guarantees for price protection in high-acuity segments. |
Study Parameters
Cross-validation between regulatory filing analysis and procurement database review anchors the qualitative findings on CDC and Public Health Agency of Canada contract structures. Primary interviews with vaccine development executives, regulatory affairs leads, hospital procurement managers, and GPO contracts managers inform platform investment prioritization and pricing tier dynamics. Secondary validation draws from FDA 483 inspection observations, Health Canada facility establishment licenses, CDC Vaccines for Children program allocation data, and CMS Medicare reimbursement schedules. Bottom-up manufacturer capacity assessments triangulate against top-down public health program budget appropriations.
Sensitivity analysis across pediatric schedule expansion rates, mRNA platform adoption curves, and therapeutic oncology reimbursement pathway timing shapes the analytical framework. Segmentation dimensions modeled include product platform technology, therapy area classification, end-user procurement scale, and distribution channel regulatory intensity. CAGRs derive from patent expiry impact modeling and biosimilar entry probability assessments. Forecast inputs incorporate CDC Advisory Committee on Immunization Practices recommendation timelines and provincial formulary inclusion patterns in Canada.
The analysis sits within stated boundaries; outcomes outside sustained federal procurement commitment levels or accelerated FDA pathway maintenance would require recalibration. Forecasts reflect assumptions on cold-chain infrastructure investment continuity and Health Canada-FDA regulatory alignment persistence. Recalibration cycles align with material shifts in CDC pediatric schedule recommendations and breakthrough therapy designation grant rates for therapeutic candidates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Peptide Drug Conjugates Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
Rivaroxaban Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Paediatric Oncology Therapeutics Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market
Biopharmaceuticals
Plasmid DNA Manufacturing Market
Biopharmaceuticals
Compounded Bioidentical Hormone Therapy Market