
 Telecom Millimeter Wave (MMW) Technology Market | 2026-2036
Telecom Millimeter Wave (MMW) Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Millimeter Wave (MMW) Technology Market Analytics
Modular antenna-amplifier bundling is restructuring procurement patterns across telecom infrastructure buyers. Qualcomm leverages its integrated modem-RF platform to dominate chipset supply for MMW endpoints. Ericsson anchors European deployment roadmaps through its street macro and mini-macro portfolio optimized for 28 GHz and 39 GHz bands. Huawei competes aggressively on total cost of ownership for massive MIMO antenna arrays in Asian metro markets.
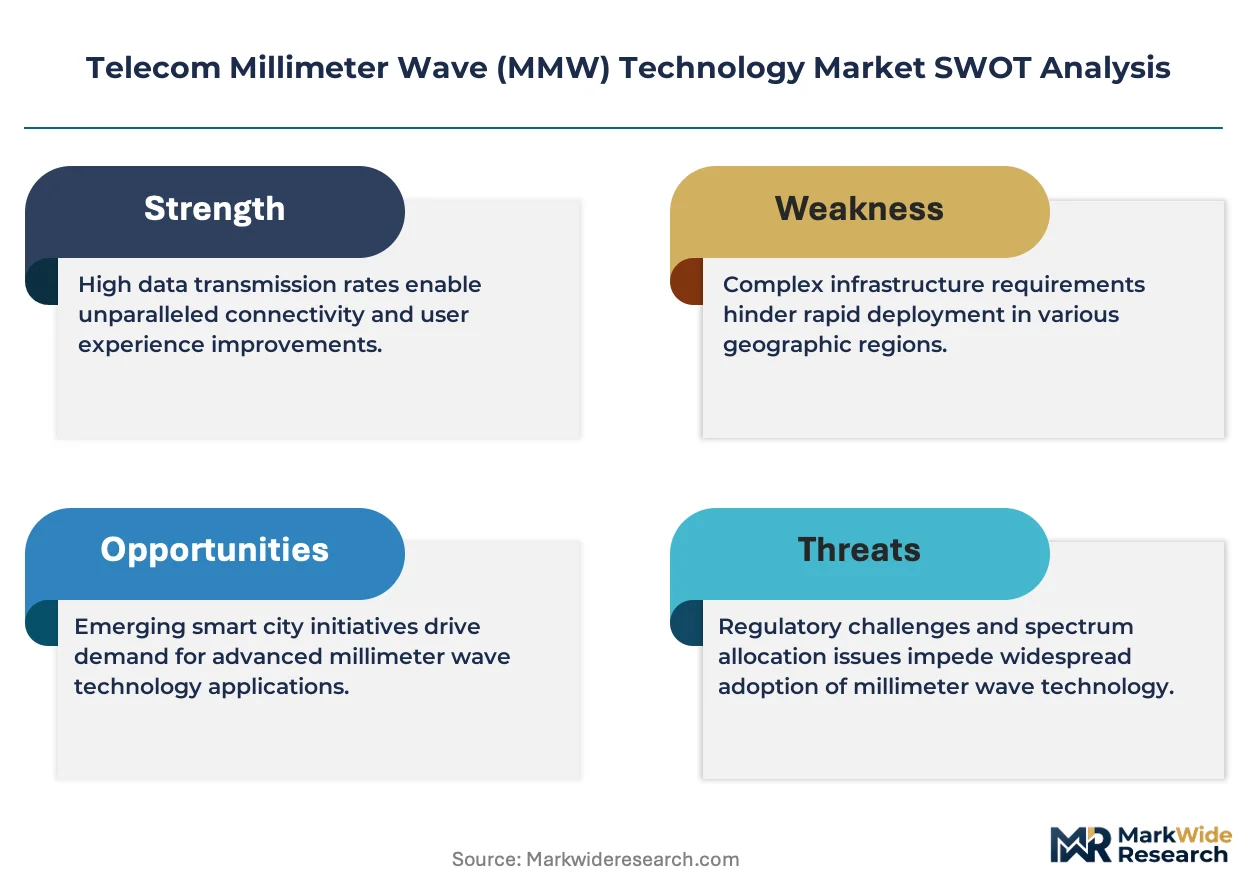
Telecom Millimeter Wave Technology encompasses electromagnetic transmission in the 30-300 GHz spectrum with wavelengths of 1-10 millimeters, enabling multi-gigabit throughput over short line-of-sight links. Active MMW components—particularly gallium nitride power amplifiers and phased-array beamformers—constitute the highest-margin segment due to materials scarcity and precision packaging requirements. Backhaul applications lead current volume deployment, while small cell infrastructure represents the fastest-expanding application category as operators densify networks below 500-meter inter-site distances. Hybrid active-passive architectures are gaining share where power consumption constraints limit fully active array adoption.
The FCC governs spectrum allocation and equipment authorization for MMW devices in the United States, while ETSI harmonizes standards across European member states and China's MIIT directs domestic 5G millimeter wave trials and commercial licensing timelines. These regulators shape demand through auction design, power density limits, and cross-border interference coordination protocols. Stakeholders must track spectrum refarming decisions and local zoning preemptions for small cell siting to anticipate deployment velocity shifts.
Market Dynamics
Spectrum scarcity in sub-6 GHz bands is compressing deployment timelines and forcing operators toward 28 GHz and 39 GHz allocations, restructuring capital allocation across baseband, RF front-end, and antenna subsystems.
Growth Catalysts
- Small cell densification mandates:Urban capacity constraints in New York, Seoul, and Shanghai are accelerating 500-meter inter-site deployments where fiber backhaul costs prove prohibitive.
- FCC spectrum releases:Auctions of contiguous 24-100 GHz blocks reduce fragmentation and lower equipment complexity for multi-band base stations.
- Gallium nitride maturation:GaN-on-SiC power amplifiers achieve 60% efficiency at E-band frequencies, shrinking thermal management footprints for street-level installations.
Market Restraints
- Line-of-sight propagation limits:Rain fade and building penetration losses restrict reliable coverage to 200-400 meters, demanding dense infrastructure investment.
- Sub-6 GHz substitution:Massive MIMO deployments at 3.5 GHz and C-band delay MMW urgency where spectrum permits.
- Phased-array packaging costs:Precision laminate substrates and hermetic sealing for beamformer ICs concentrate supply among Japanese and Taiwanese substrate fabricators.
Strategic Opportunities
- Private 5G industrial networks:Manufacturing campuses in Germany and automotive test tracks in Michigan present captive deployment scenarios with controlled propagation environments.
- Fixed wireless access expansion:Residential broadband gaps in suburban Texas and Australian exurbs favor 28 GHz point-to-multipoint architectures over trenching fiber.
- AI-native beam management:Machine learning-driven predictive beamforming converges with edge compute to reduce handover latency in high-mobility corridors.
Industry Challenges
- RF systems integration talent scarcity:Packaging engineers with millimeter-wave electromagnetic simulation expertise command premium compensation, constraining OEM scaling.
- Multi-vendor interoperability certification:ETSI and 3GPP compliance testing cycles extend 14-18 months, delaying revenue recognition for new antenna-amplifier platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Millimeter Wave (MMW) Technology Market |
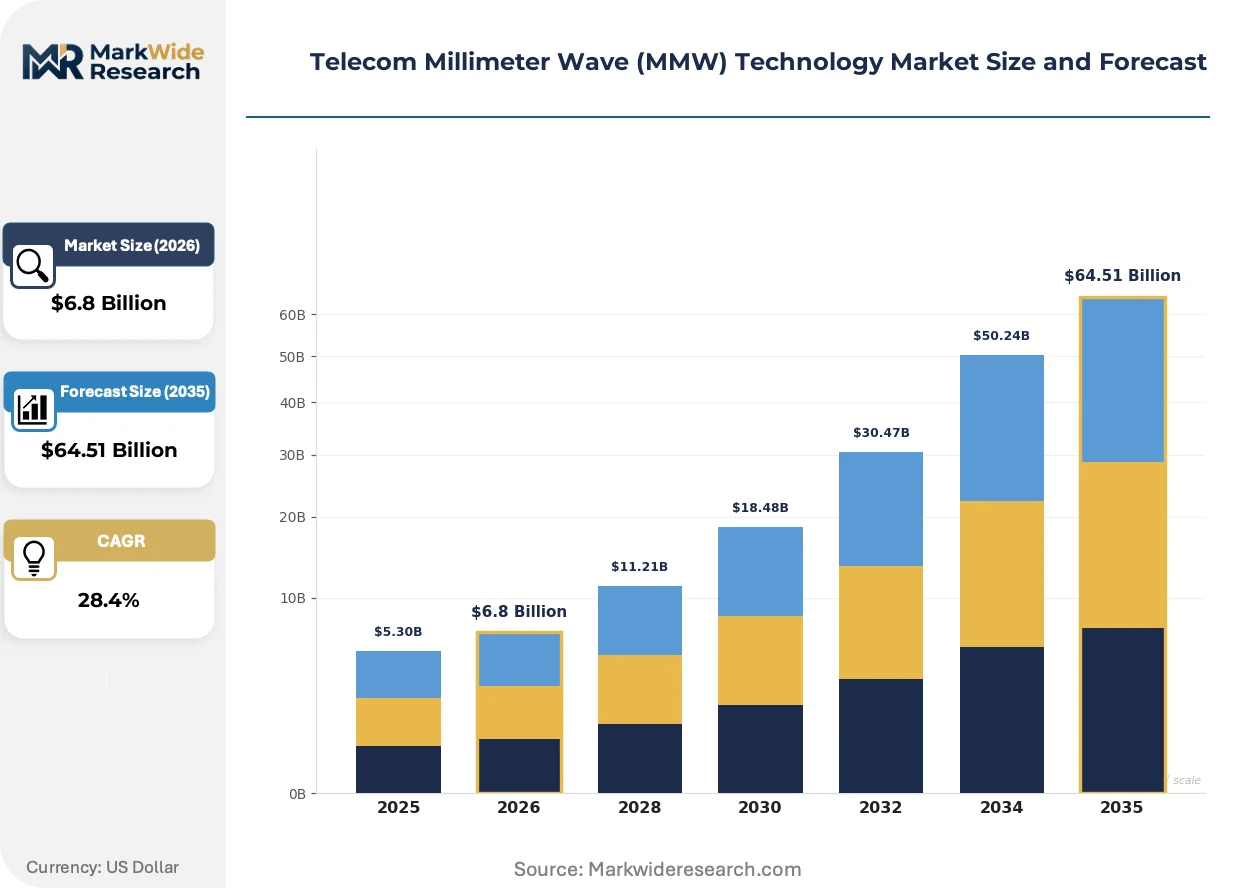
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $64.51 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmitters, Receivers, Amplifiers, Antennas Application: Backhaul, Small Cells, Satellite Communication, High-Speed Data Transfer End User: Telecom Operators, Government, Enterprises, Research Institutions Technology: Active, Passive, Hybrid, Digital |
| Companies Covered | Analog Devices, Inc., Bridgewave Communications, Qualcomm, NEC Corporation, Aviat Networks, Huawei, Keysight Technologies Inc., Siklu Communication Ltd., Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Millimeter Wave (MMW) Technology Market Evolving Landscape
Silicon photonics integration and AI-driven network automation are collapsing traditional boundaries between optical transport and radio access, compressing equipment form factors while expanding addressable deployment scenarios.
Silicon-based beamformer ICs with embedded calibration logic are electrifying active antenna unit designs by replacing discrete phase shifters and attenuators with monolithic 64-element arrays. Tier-1 infrastructure OEMs in Sweden and Finland are qualifying these devices for 28 GHz street macro applications. The shift is compressing bill-of-materials costs and enabling software-defined radiation patterns without hardware swaps.
ETSI's harmonized 5G-Advanced spectrum frameworks are mandating improved power density limits and cross-border interference coordination across European member states. Equipment vendors must now certify simultaneous compliance with national implementations in France, Germany, and Italy. The regulatory convergence is accelerating modular platform strategies that span multiple national markets without hardware variants.
Network equipment procurement is consolidating toward integrated modem-RF-antenna bundles rather than discrete component sourcing. Mobile operators in South Korea and Japan now specify end-to-end performance guarantees from single vendors, displacing multi-supplier integration models. The bundling trend is most pronounced in dense urban corridors where deployment velocity outweighs unit cost optimization.
Telecom Millimeter Wave (MMW) Technology Market Segmentation
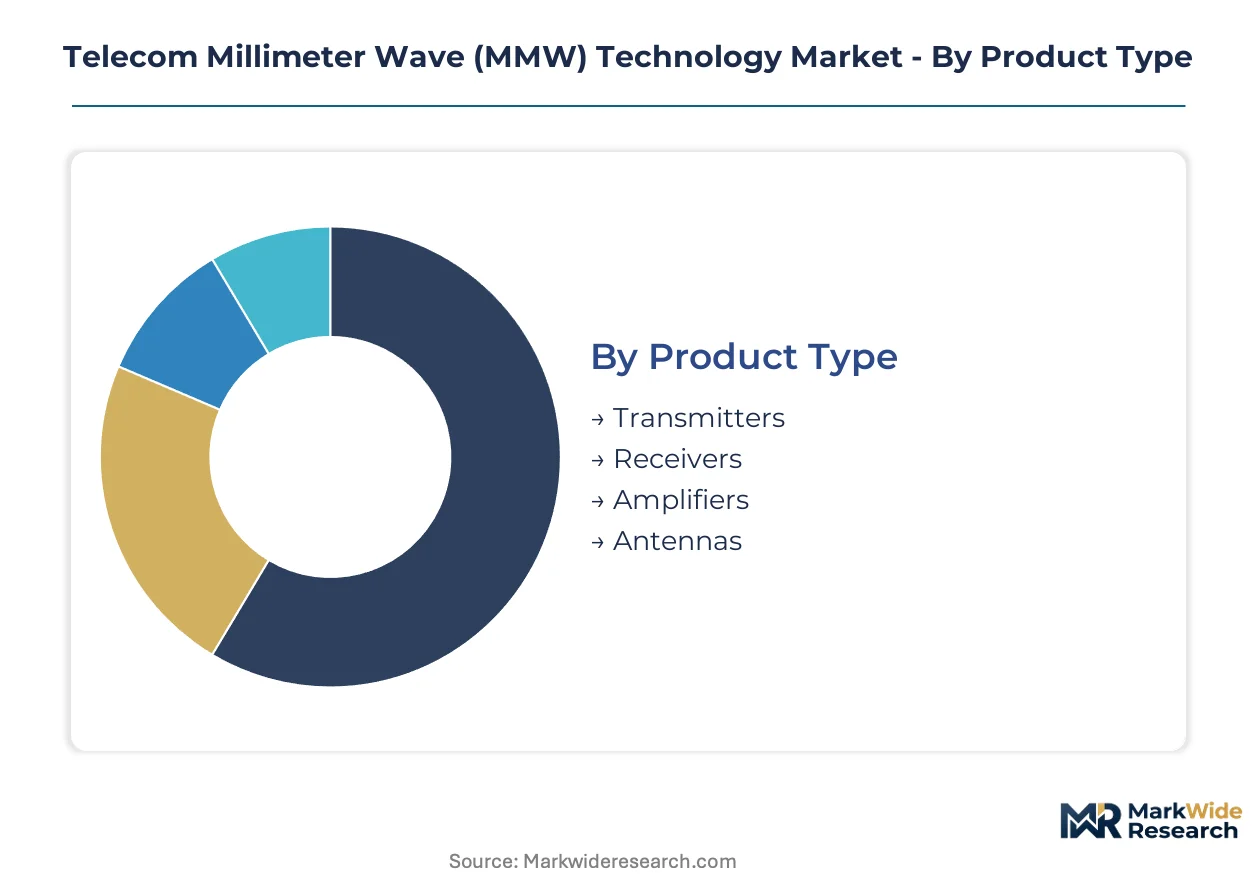
Segmentation in the Telecom Millimeter Wave Technology Market reveals how component specialization, deployment architecture, and procurement authority reshape vendor strategies. Distinct technical requirements across transmitters versus antennas, or backhaul versus small cells, fragment addressable opportunities and concentrate margins in narrow subsystems.
Product Type:
Supply concentration in GaN-on-SiC substrates and precision beamformer packaging elevates certain product categories above commodity RF components.
- Transmitters:Gallium nitride power amplifiers dominate transmitter architectures for 28 GHz and 39 GHz bands, achieving 60% efficiency in street-level base stations. Demand clusters in South Korean and German urban corridors where fiber backhaul costs exceed wireless deployment economics.
- Amplifiers:E-band power amplifiers constitute the highest-margin segment due to materials scarcity and hermetic sealing requirements. Japanese and Taiwanese substrate fabricators control precision laminate supply, constraining OEM scaling and amplifying pricing power for qualified suppliers.
- Receivers:Low-noise amplifiers with embedded calibration logic reduce bill-of-materials complexity in integrated modem-RF platforms.
- Antennas:Phased-array beamformers enable software-defined radiation patterns without hardware swaps in active antenna units.
Amplifiers absorb the bulk of installed capacity; antennas are expanding most quickly as operators densify networks below 500-meter inter-site distances.
Application:
Deployment velocity and capital intensity diverge sharply between long-haul connectivity and hyperlocal capacity augmentation.
- Backhaul:Point-to-point links in the 24-100 GHz range transport aggregated traffic from cell sites to core networks where trenching fiber proves uneconomical. Dense urban corridors across New York, Seoul, and Shanghai drive volume procurement as operators bypass last-mile fiber constraints.
- Small Cells:Street macro and mini-macro installations below 500-meter spacing address capacity hotspots in stadiums, transit hubs, and central business districts. Rain fade and line-of-sight limitations restrict reliable coverage to 200-400 meters, demanding infrastructure density that elevates unit volume potential.
- Satellite Communication:Ground segment terminals leverage MMW for feeder links in low-earth orbit constellations.
- High-Speed Data Transfer:Fixed wireless access architectures bridge suburban and exurban broadband gaps in Texas and Australian markets.
Backhaul commands the dominant share of current deployment spend; small cells are climbing the fastest as 5G-Advanced roadmaps accelerate urban densification mandates.
End User:
Procurement authority and technical specification complexity fragment addressable demand across institutional buyer types.
- Telecom Operators:Mobile network operators in South Korea and Japan specify end-to-end performance guarantees from single vendors, displacing multi-supplier integration models. Bundled modem-RF-antenna procurement prioritizes deployment velocity over unit cost optimization in dense urban corridors.
- Enterprises:Manufacturing campuses in Germany and automotive test tracks in Michigan deploy private 5G networks with controlled propagation environments. Captive spectrum allocations and deterministic latency requirements favor turnkey MMW infrastructure over public network reliance.
- Government:Defense and public safety agencies procure hardened equipment for secure communications infrastructure.
- Research Institutions:Universities and national laboratories validate beamforming algorithms and propagation models for standards bodies.
Telecom operators absorb the bulk of installed capacity; enterprises are gaining share fastest as industrial digitization expands private network deployments.
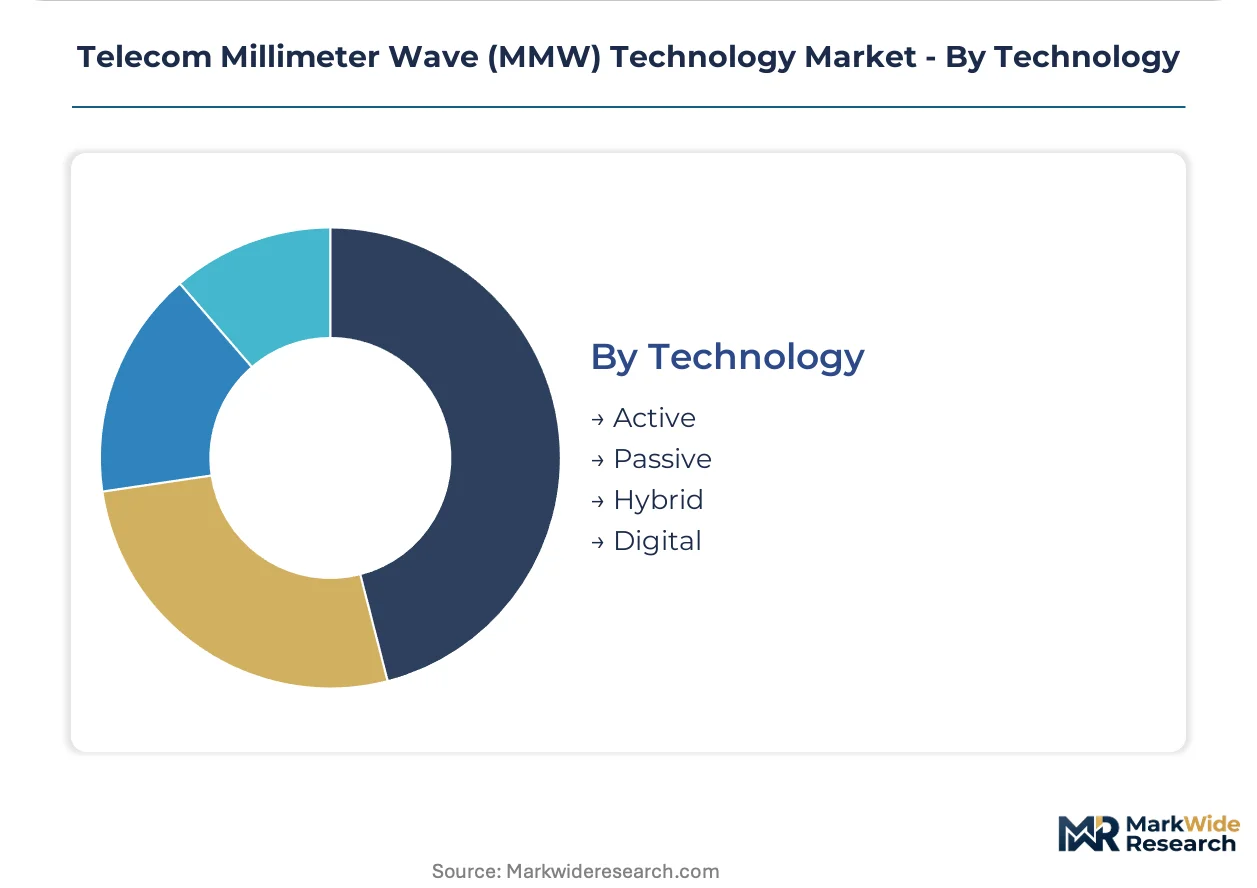
Technology:
Power consumption constraints and cost-performance tradeoffs stratify adoption across architectural approaches.
- Active:Fully active phased arrays with monolithic 64-element beamformer ICs enable software-defined radiation patterns and real-time beam steering. Tier-1 infrastructure OEMs in Sweden and Finland qualify these devices for 28 GHz street macro applications where thermal management permits continuous operation.
- Hybrid:Active-passive architectures partition beamforming between analog RF chains and digital baseband processing. Power-constrained installations favor this intermediate approach where fully active arrays exceed thermal or cost envelopes.
- Passive:Discrete phase shifters and attenuators persist in cost-sensitive applications with relaxed performance requirements.
- Digital:All-digital beamforming architectures converge with AI-native beam management for predictive handover optimization.
Active technology absorbs the bulk of installed capacity; hybrid architectures are expanding most quickly where power constraints limit fully active adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of GaN power amplifiers and beamformer substrates concentrates among Japanese and Taiwanese fabricators, while deployment demand clusters in urban corridors across the United States, South Korea, and Germany where fiber backhaul economics favor wireless alternatives.
United States
Verizon and AT&T accelerate 28 GHz small cell densification across Manhattan and downtown Chicago to relieve sub-6 GHz congestion. The FCC's Auction 103 released contiguous 37 GHz and 39 GHz blocks that reduce equipment complexity for multi-band base stations. Deployment velocity concentrates in New York Metro and Los Angeles basin where zoning preemptions streamline street-level siting approvals.
South Korea
SK Telecom and KT Corporation drive 28 GHz street macro installations below 500-meter spacing in Seoul's Gangnam and Jongno districts. The Korea Communications Commission harmonized power density limits with 3GPP Release 17 specifications to accelerate 5G-Advanced roadmaps. Samsung Electronics anchors domestic supply chains while government-backed trials validate E-band backhaul for Incheon International Airport expansion.
Germany
Deutsche Telekom and Vodafone deploy private 5G networks for BMW's Leipzig assembly plant and Bosch's Stuttgart manufacturing campus using 26 GHz and 28 GHz allocations. ETSI's harmonized spectrum frameworks mandate cross-border interference coordination with France and Poland. Industrial digitization concentrates demand in Bavaria and Baden-Württemberg where automotive OEMs specify deterministic latency for robotic coordination.
China
China Mobile and China Unicom conduct MIIT-directed millimeter wave trials in Beijing's Zhongguancun tech corridor and Shanghai's Pudong financial district ahead of commercial licensing timelines. The Ministry of Industry and Information Technology reserves 24.75-27.5 GHz and 37-42.5 GHz bands for coordinated 5G-Advanced deployment. Huawei and ZTE dominate domestic infrastructure procurement while state-backed subsidies compress total cost of ownership for massive MIMO arrays.
Japan
NTT Docomo and SoftBank prioritize 28 GHz indoor coverage solutions for Tokyo Station and Osaka's Kansai International Airport passenger terminals. METI's spectrum allocation framework released 27 GHz and 28 GHz bands with streamlined equipment authorization procedures. Deployment concentrates in Kanto and Kansai metropolitan areas where population density justifies infrastructure investment despite building penetration constraints.
Telecom Millimeter Wave (MMW) Technology Market Competitive Landscape
The competitive structure tilts toward integrated platform providers over discrete component specialists. Vendor concentration remains moderate with three to five firms capturing dominant share in RF front-end subsystems while beamformer packaging retains specialist fragmentation. Two archetypes define positioning: integrated modem-RF-antenna bundlers serving tier-1 operators, and precision substrate fabricators controlling GaN-on-SiC supply. Competitive moves center on strategic partnerships for multi-vendor interoperability certification and capacity expansion in Japanese and Taiwanese laminate facilities.
Within the integrated platform tier, Qualcomm anchors North American supply through modem-RF system-on-chip architectures, while Ericsson exemplifies European infrastructure bundling with street macro portfolios optimized for 28 GHz deployment. Huawei occupies a position as cost-optimized massive MIMO supplier for Asian metro markets. These three firms represent divergent geographic and procurement-model strategies rather than direct product rivalry.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| Bridgewave Communications |
| Qualcomm |
| NEC Corporation |
| Aviat Networks |
| Huawei |
| Keysight Technologies Inc. |
| Siklu Communication Ltd. |
| Ericsson |
| Others |
Value Network & Pricing Analysis
Japanese and Taiwanese family-owned substrate fabricators anchor GaN-on-SiC supply for millimeter-wave power amplifiers, translating materials scarcity into disciplined pricing power across RF front-end tiers. Their concentrated ownership structures resist capacity expansion despite demand surges from 28 GHz small cell deployments, compressing buyer leverage and amplifying margin capture for qualified suppliers.
Pricing Analysis
Margin tightening in E-band power amplifiers reflects hermetic sealing complexity and precision laminate substrate scarcity. Three-tier pricing structure across military-grade, carrier-certified, and commercial-industrial levels separates defense procurement from telecom operator bundles. Cost-down pressure on hybrid active-passive architectures accelerates as South Korean operators consolidate vendor lists. Enterprise private 5G buyers exhibit lowest price sensitivity due to captive spectrum value, while suburban fixed wireless access providers face acute budget constraints.
Supply Chain Analysis
ETSI and FCC equipment authorization timelines gate supplier qualification, extending 14-18 month certification cycles that freeze out unproven entrants. Production concentrates in Japan, Taiwan, and the United States for GaN substrates, beamformer ICs, and precision packaging. Raw material flows draw from silicon carbide wafers, gallium nitride epitaxy, and hermetic ceramic housings. Single-source vulnerability concentrates in Japanese laminate fabricators. Distribution runs through direct OEM partnerships rather than distributor networks, reflecting technical integration requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN-on-SiC supply scarcity and 3GPP certification burdens are forcing subscale beamformer specialists toward distressed exits, creating consolidation windows for integrated platform vendors.
For Market Incumbents: Lock in multi-year substrate offtake agreements with Japanese and Taiwanese fabricators before capacity constraints harden. Deepen backward integration into GaN epitaxy to defend margin position against emerging silicon-based beamformer substitutes. Prioritize ETSI-FCC dual certification investment to capture cross-Atlantic procurement consolidation.
For New Entrants and Emerging Players: The 40-60% price spread between Qualcomm-anchored premium bundles and unbranded Chinese antenna arrays opens white space in mid-tier hybrid architectures for European industrial private 5G. Target German automotive campuses and Michigan test tracks where deterministic latency requirements favor turnkey over public network reliance. Lead with AI-native beam management software to bypass hardware qualification barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor GaN-on-SiC substrate specialists with existing FCC equipment authorization in the United States and ETSI harmonization in Europe. Long-term viability hinges on 5G-Advanced roadmap execution and 6G research positioning. Watch for MIIT commercial licensing timeline acceleration in China as the demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Capacity Expansion | Secures substrate supply for Ericsson's 28 GHz street macro portfolio amid Japanese fabricator constraints. |
| AI-Native Beam Management Development | Enables predictive handover optimization for SK Telecom's Seoul corridor densification mandates. |
| ETSI-FCC Dual Certification Investment | Accelerates revenue recognition for multi-band base stations across Deutsche Telekom and Verizon deployments. |
| Private 5G Turnkey Partnership | Captures BMW Leipzig and Bosch Stuttgart manufacturing campus demand with controlled propagation environments. |
| Silicon Photonics Integration | Collapses optical-radio boundaries for NTT Docomo's Tokyo Station indoor coverage solutions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with RF systems engineers, telecom procurement directors, semiconductor packaging specialists, and baseband platform architects combined with FCC equipment authorization databases, ETSI harmonization frameworks, and MIIT trial disclosures. Bottom-up component demand modeling and top-down operator capex triangulation validated segmentation outputs across product type, application, and technology dimensions.
Reconciliation of installation data from South Korean and German operators with substrate shipment records from Japanese and Taiwanese suppliers shaped the forecast framework. Segmentation by transmitter versus antenna, backhaul versus small cell, and active versus hybrid architectures structured volume projections across the analysis window. CAGRs derived from operator roadmap commitments, spectrum auction timelines, and GaN device learning curve trajectories. 5G-Advanced standardization velocity and millimeter wave licensing decisions in China provided cross-check inputs.
Underlying measurement precision varies by segment; backhaul deployment tracking carries tighter precision than emerging small cell densification given reporting opacity. Forecasts reflect documented assumptions regarding operator capital allocation priorities and regulatory timeline adherence. Model refresh is warranted upon material change in FCC spectrum refarming decisions or MIIT commercial licensing acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Mobile Signal Booster Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market
Wireless Technologies
Wireless Communication Equipment Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Light Fidelity Market
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
North America in-Building Wireless Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Femtocell Market
Wireless Technologies
France Fixed Wireless Access (FWA) Market
Wireless Technologies
Fixed LTE Wireless Broadband Market
Wireless Technologies
Wireless Access Point Market
Wireless Technologies
Optical Wireless Communication and Li-Fi Market
Wireless Technologies
Wireless Intercoms Market