
 Rental Outdoor LED Display Market | 2026-2036
Rental Outdoor LED Display Market Size, Share, and Industry Trends Forecast 2026-2036
Rental Outdoor LED Display Market Analytics
Asset-light leasing models are reshaping competitive dynamics in the rental outdoor LED display sector. INFiLED leverages captive manufacturing in Shenzhen to control module supply for European festival operators. LianTronics sustains R&D intensity around fine-pitch outdoor sealing technology. ROE Visual anchors premium positioning through its Black Marble series for broadcast-integrated stage designs.
Rental outdoor LED displays comprise modular, weather-sealed diode arrays typically rated IP65 or higher, assembled from cabinets with pixel pitches between 2.9mm and 10mm for variable viewing distances in uncontrolled ambient light. Their primary commercial purpose is temporary visual communication for live audiences at events, sports venues, and public activations where ownership economics prove impractical. Mobile LED configurations lead volume deployment due to rapid rigging requirements for touring productions, while transparent LED represents the fastest-expanding sub-category as architects integrate digital facades into temporary structures. SMD technology dominates current fleet composition, though COB is gaining share in high-impact advertising applications where surface durability reduces field failure rates.
FCC Part 15 emissions standards in the United States constrain wireless control system design for networked display arrays, while the EU's CE marking and RoHS directives govern material composition and electromagnetic compatibility for European deployments. China's GB standards on electronic display energy consumption are tightening test protocols for export-bound manufacturers. Stakeholders must monitor how emerging carbon accounting rules under the EU Green Deal reshape logistics and fleet amortization decisions for cross-border rental operations.
Market Dynamics
Festival operators are compressing rigging windows to sub-four-hour turnarounds, forcing rental fleet operators to prioritize rapid-assembly cabinet designs over pure pixel density specifications.
Growth Catalysts
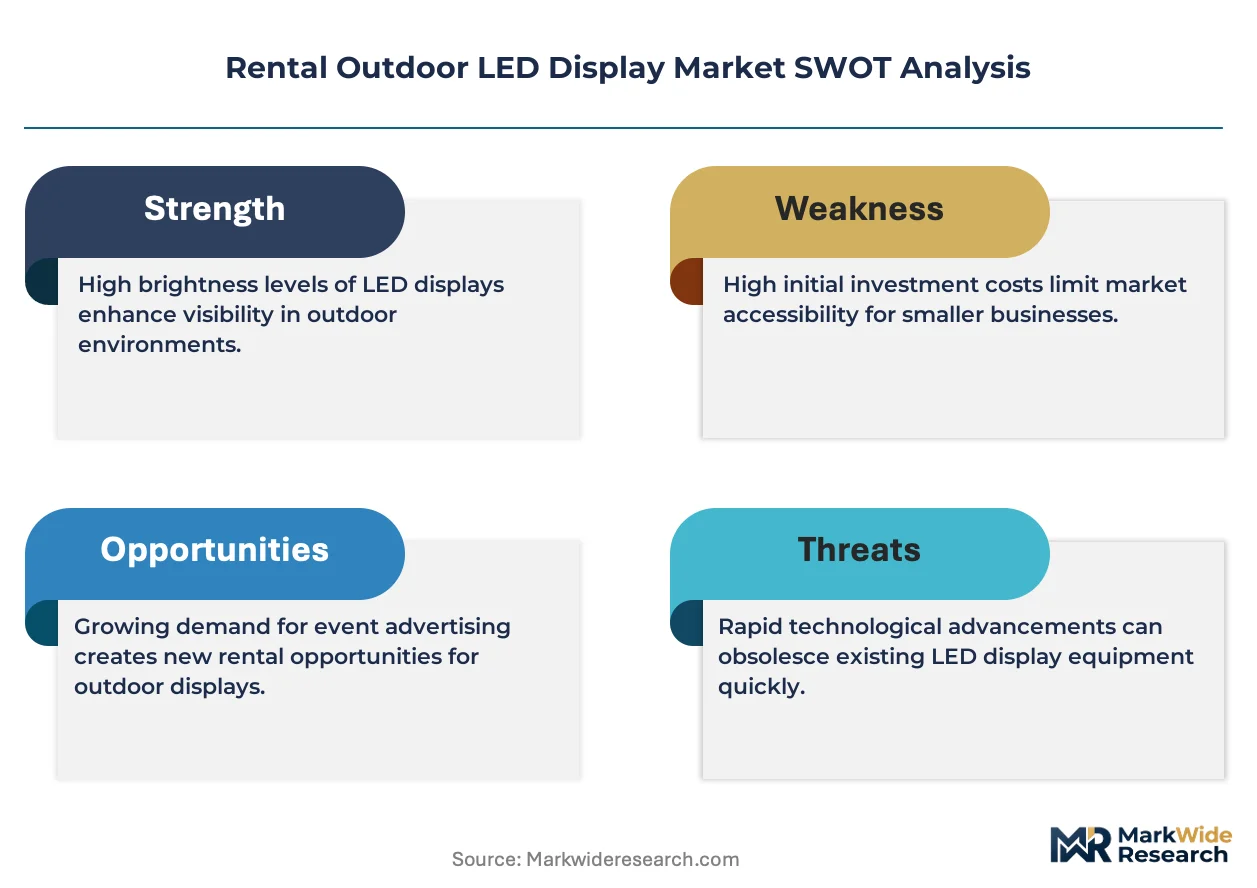
- EU F-Gas Regulation:Tightening energy-efficiency mandates for large-format cooling systems are accelerating fleet refresh cycles toward heat-dissipating COB architectures.
- Live concert touring:Production companies are expanding multi-year rental commitments to secure priority access during peak summer festival seasons.
- Germany's live events corridor:Concentrated demand from Berlin to Munich is pulling modular inventory toward Central European logistics hubs.
Market Restraints
- LED driver IC concentration:Taiwan and South Korea foundries control critical semiconductor supply, exposing rental operators to allocation volatility during capacity crunches.
- Aluminum extrusion input costs:Cabinet frame fabrication depends on primary aluminum pricing that fluctuates with energy-intensive smelter economics.
- IP65 sealing trade-offs:Weatherproofing requirements limit thermal dissipation pathways, constraining peak brightness output in direct sunlight deployments.
Strategic Opportunities
- Transparent LED sub-category:Architectural integration into temporary facades and stage backdrops is opening premium rental tiers for see-through diode arrays.
- EU Green Deal carbon accounting:Emerging logistics amortization rules will reward regional fleet positioning over cross-border equipment shuttling.
- Broadcast-integrated stage designs:Convergence of LED backdrops with real-time camera tracking systems is creating specification pull from television production units.
Industry Challenges
- Field calibration expertise:Color uniformity maintenance across modular arrays requires technicians trained in gamma curve matching and degradation compensation.
- CE marking timeline compression:European deployments face electromagnetic compatibility certification bottlenecks that delay festival season availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rental Outdoor LED Display Market |
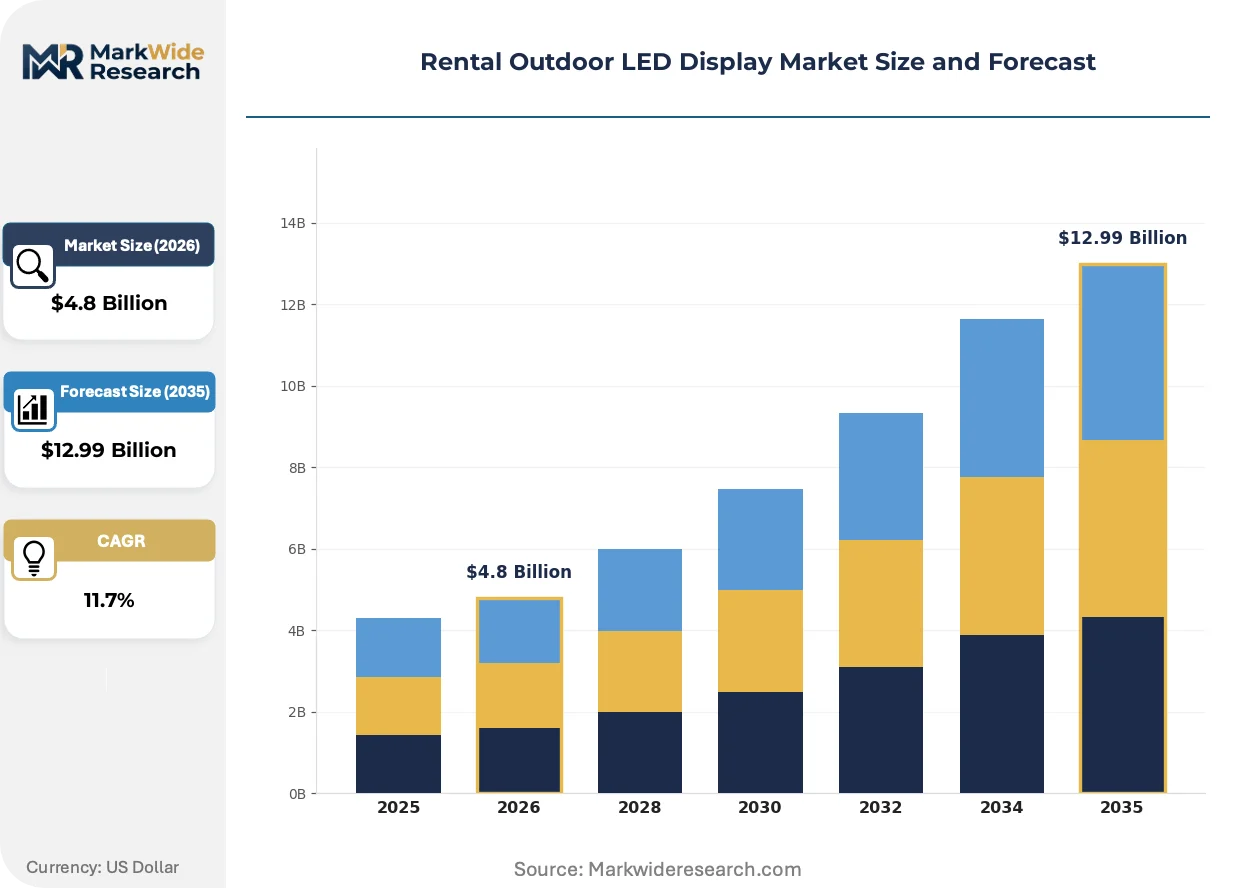
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile LED, Fixed LED, Transparent LED, Mini LED End User: Event Organizers, Advertising Agencies, Corporate, Sports Arenas Technology: SMD, COB, Backlit, Edge-Lit Integration Level: Standalone, Networked, Integrated, Modular |
| Companies Covered | INFiLED, LianTronics, Unilumin Group, ROE Visual, Barco, Absen, Daktronics, PixelFLEX LED, Leyard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rental Outdoor LED Display Market Evolving Landscape
Control system architectures are migrating toward mesh-networked wireless protocols, eliminating cable infrastructure while introducing new electromagnetic compliance complexity for temporary installations.
COB (Chip-on-Board) packaging is consolidating multiple diodes beneath a single phosphor layer, improving surface durability against touring abrasion and moisture ingress. Festival operators in the Netherlands and Belgium are specifying COB modules for multi-week outdoor deployments where field failure rates must approach zero. This consolidation is digitizing maintenance scheduling by embedding predictive thermal monitoring directly into driver electronics.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in cooling systems above specific capacity thresholds, compelling manufacturers to redesign thermal management for high-brightness outdoor cabinets. Compressor-based cooling architectures face obsolescence risk, accelerating adoption of passive liquid-cooling loops and thermally conductive housing materials. German rental operators are front-loading fleet investment ahead of 2027 enforcement milestones.
Asset-light leasing models are fragmenting procurement authority, with production companies unbundling display rental from full-service staging contracts to negotiate directly with specialized LED providers. This disintermediation compresses margin capture for integrated audiovisual contractors while rewarding fleet operators with captive manufacturing control. The shift is most pronounced in touring productions originating from London and Manchester, where production managers maintain direct supplier relationships.
Rental Outdoor LED Display Market Segmentation
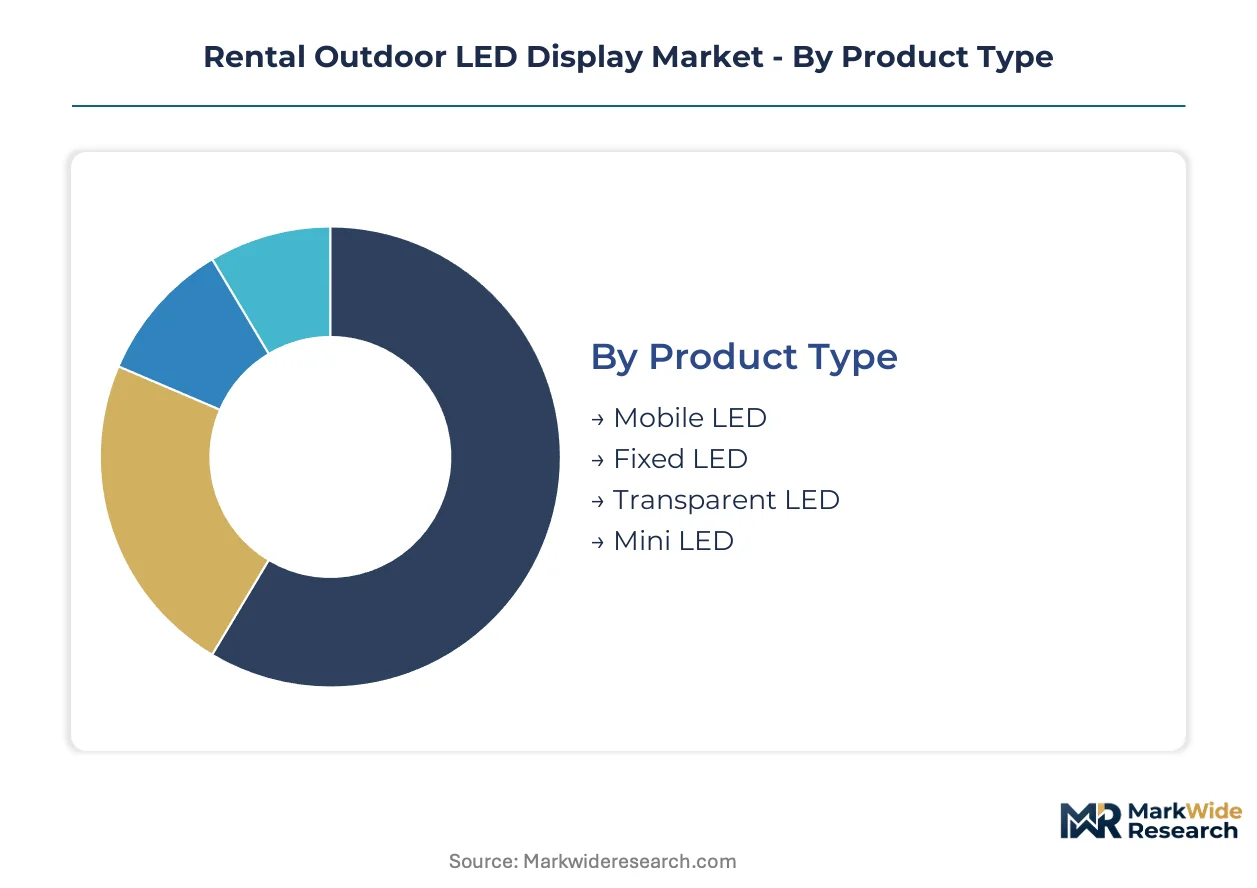
Rental fleet operators configure procurement around deployment velocity, weather exposure, and rigging constraints. Segmentation reveals how technical specifications map to distinct commercial use cases across touring productions and temporary installations.
Product Type:
Mobile configurations dominate touring workflows where four-hour turnaround windows compress rigging schedules.
- Mobile LED:Rapid-assembly cabinets with integrated transport dollies and tool-free locking mechanisms. Festival operators in Germany's Berlin-Munich corridor prioritize these units for multi-stage setups where crews reposition hardware overnight.
- Transparent LED:See-through diode arrays with 60-85% light transmission enabling architectural integration. Dutch and Belgian festival designers specify transparent modules for temporary facades and stage backdrops where sightlines must remain unobstructed.
- Fixed LED:Semi-permanent installations for seasonal venues and recurring event series.
- Mini LED:Fine-pitch arrays for premium close-viewing applications in broadcast-integrated productions.
The dominant share belongs to Mobile LED, while Transparent LED is closing the gap fastest.
End User:
Procurement authority fragments as production companies bypass integrated contractors to negotiate directly with specialized fleet operators.
- Event Organizers:Multi-year rental commitments secure priority inventory access during peak summer festival seasons. These stakeholders specify IP65 sealing and rapid-assembly designs to meet compressed load-in schedules.
- Advertising Agencies:Brand activations and pop-up campaigns drive demand for modular configurations with short-term lease terms. Agency clients prioritize wireless control architectures to eliminate cable infrastructure in temporary urban installations.
- Corporate:Product launches and shareholder events favor premium pixel density for close-viewing audiences.
- Sports Arenas:Seasonal installations for outdoor tournaments and temporary viewing zones.
Event Organizers command the largest fleet allocation, though Advertising Agencies are expanding their share through unbundled procurement.
Technology:
Packaging architectures trade off surface durability against thermal dissipation pathways.
- SMD:Surface-mount diode arrays with discrete LED packages. Current fleet composition favors SMD for cost efficiency in high-volume touring deployments where module replacement economics matter.
- COB:Chip-on-Board consolidation embeds multiple diodes beneath single phosphor layers. Netherlands operators specify COB for multi-week outdoor deployments where moisture ingress and surface abrasion threaten field reliability.
- Backlit:Direct illumination configurations for high-brightness daylight visibility.
- Edge-Lit:Slim-profile designs prioritizing transport density over peak luminance.
SMD retains installed base leadership, though COB is climbing the fastest as F-Gas Regulation deadlines approach.
Integration Level:
Control system architectures determine electromagnetic compliance complexity for temporary installations.
- Modular:Interchangeable cabinets with standardized power and data interfaces. Rental operators in London and Manchester specify modular systems to mix pixel pitches across single stage designs.
- Networked:Mesh wireless protocols eliminating cable runs. FCC Part 15 emissions standards constrain transmitter power and frequency selection for US deployments.
- Standalone:Self-contained units with onboard media players for simple playback.
- Integrated:Tight coupling with camera tracking and real-time rendering engines for broadcast productions.
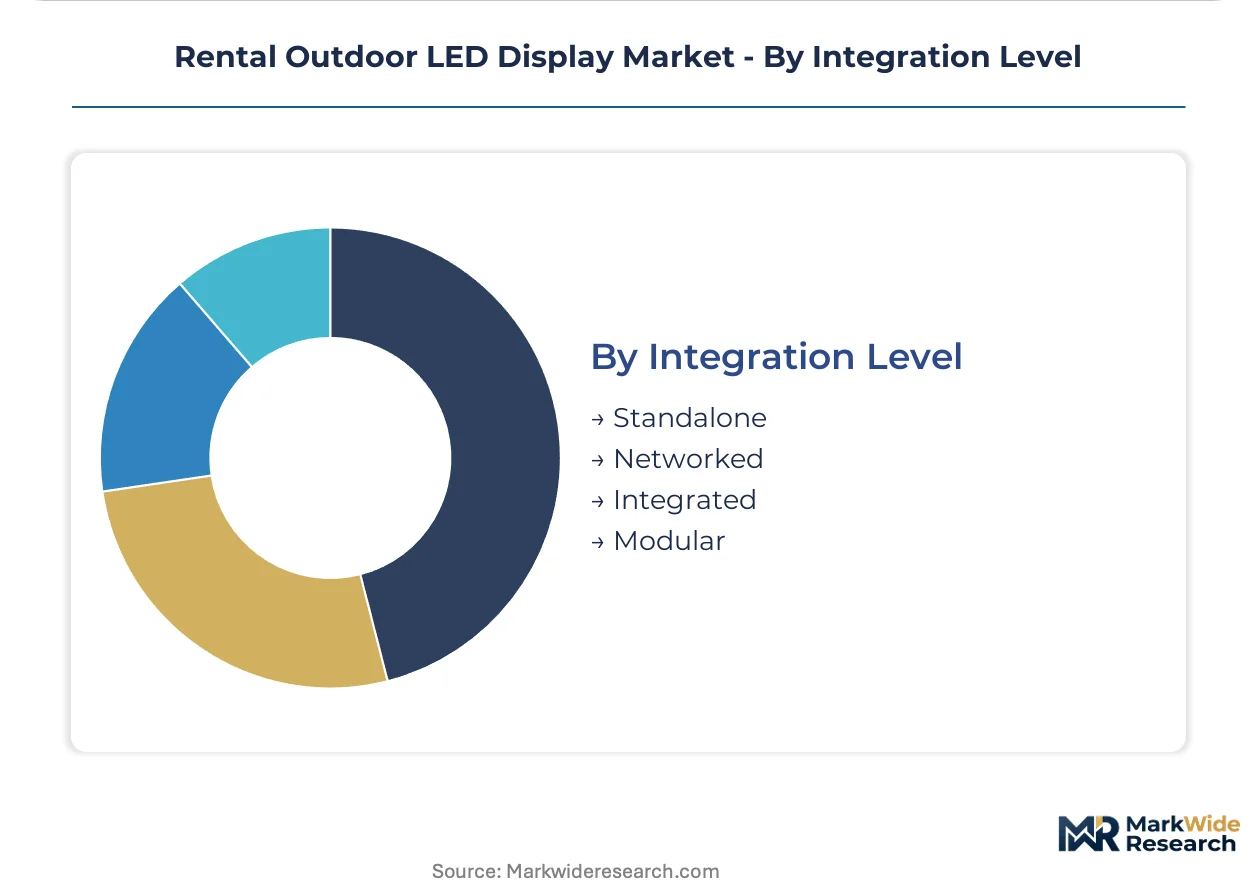
Modular configurations hold the largest inventory position, while Networked systems are gaining share fastest among touring productions originating from UK logistics hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's F-Gas Regulation is accelerating fleet refresh cycles toward heat-dissipating architectures across European rental operators. Production companies in touring hubs are securing multi-year commitments to lock inventory access. Demand clusters concentrate where festival density intersects with logistics infrastructure.
Germany
Festival operators along the Berlin-Munich corridor are compressing rigging windows to sub-four-hour turnarounds. The F-Gas Regulation mandates tighter energy-efficiency standards for large-format cooling systems above specified capacity thresholds. Rental fleet operators in Munich and Berlin are front-loading capital expenditure ahead of 2027 enforcement milestones.
United States
Touring productions originating from Los Angeles and Nashville are expanding rental fleet commitments for summer amphitheater circuits. FCC Part 15 emissions standards constrain wireless control system design for networked display arrays. Production managers in these hubs maintain direct supplier relationships, bypassing integrated audiovisual contractors.
Netherlands
Festival designers are specifying transparent LED modules for temporary facades where sightlines must remain unobstructed. CE marking and RoHS directives govern material composition and electromagnetic compatibility for European deployments. Amsterdam and Rotterdam rental operators are prioritizing COB architectures for multi-week outdoor deployments.
United Kingdom
Production companies in London and Manchester are unbundling display rental from full-service staging contracts. The country's national electronic equipment regulations align with EU electromagnetic compatibility frameworks during post-transition alignment periods. These logistics hubs are pulling modular inventory for touring productions across domestic and continental circuits.
Belgium
Festival operators are embedding predictive thermal monitoring into driver electronics for zero-failure deployments. National regulations transpose EU directives on electronic display energy consumption and fluorinated gas phase-down schedules. Rental providers in Brussels and Antwerp are consolidating procurement authority with specialized LED fleet operators.
Rental Outdoor LED Display Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: Shenzhen-based manufacturers with captive module supply, European premium-positioned designers for broadcast-integrated stages, and North American systems integrators with regional service density. Competitive moves concentrate on backward integration into driver IC sourcing and geographic footprint expansion through hub-and-spoke logistics models.
Among Shenzhen-based manufacturers, INFiLED, LianTronics, and Absen occupy positions defined by module supply control and export-scale production capacity. These entities exemplify the manufacturing-anchored archetype competing on fleet refresh velocity and captive supply chain coordination. European-market positioning is represented by ROE Visual, which sits within the premium-tier vector for broadcast-integrated stage designs. The competitive dynamic between these groupings centers on procurement authority fragmentation as production companies negotiate directly with specialized providers.
| Leading Market Players |
|---|
| INFiLED |
| LianTronics |
| Unilumin Group |
| ROE Visual |
| Barco |
| Absen |
| Daktronics |
| PixelFLEX LED |
| Leyard |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Antwerp logistics corridor shapes cost dynamics across rental fleet procurement, concentrating supply chain leverage with Shenzhen-based manufacturers while forcing European operators into tiered pricing stratification based on certification grade and thermal management specifications.
Pricing Analysis
Certification level creates the primary spread between premium CE-marked modules and standard-grade alternatives. The market runs on a hybrid pricing structure combining per-unit cabinet leasing with project-based service bundling. Price differentiation hinges on IP65 sealing grade and F-Gas Regulation compliance tier. Cost compression in standard-tier mobile LED is intensifying because aluminum extrusion input volatility feeds through to frame fabrication economics. Event organizers exhibit the highest price sensitivity due to compressed festival margins, while broadcast-integrated production units prioritize performance over unit economics.
Supply Chain Analysis
Export-control regimes on semiconductor manufacturing equipment constrain LED driver IC flows from Taiwan and South Korea foundries. Module assembly concentrates in China, with driver electronics sourcing anchored in Taiwan and South Korea. Raw material dependencies span aluminum extrusions for cabinet frames, phosphor compounds for COB packaging, and copper for thermal management loops. Single-source vulnerability in driver IC allocation exposes rental operators to capacity crunch disruptions. Distribution runs through hub-and-spoke logistics models centered on Berlin, London, and Amsterdam for European festival circuits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mesh-networked control architectures are transforming rental outdoor LED displays into interoperable platform ecosystems, where fleet operators compete on software-defined service layers rather than hardware specifications alone.
For Market Incumbents: Harden defensive positioning through backward integration into driver IC sourcing partnerships with Taiwan foundries, insulating against allocation volatility that threatens summer festival season availability. Consolidate regional service density around Central European logistics hubs before carbon accounting rules under the EU Green Deal penalize cross-border equipment shuttling. Prioritize captive manufacturing control over module supply chains as production companies disintermediate integrated audiovisual contractors.
For New Entrants and Emerging Players: Belgium's festival production cluster offers underpenetrated white-space for specialized COB fleet operators targeting multi-week outdoor deployments with zero-failure specifications. Transparent LED architectural integration presents a second entry vector, as Dutch and Belgian designers seek see-through diode arrays for temporary facades where sightlines must remain unobstructed. Pursue direct procurement relationships with London and Manchester production managers who have already unbundled display rental from full-service staging contracts.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with underutilized LED module production capacity and dormant CE marking pathways. Long-term viability centers on fleet operators with captive Shenzhen manufacturing and established hub-and-spoke logistics footprints across the EU festival corridor. Watch for inflection signals in F-Gas Regulation enforcement milestones, which will accelerate obsolescence risk for compressor-based cooling architectures and reward early movers in passive liquid-cooling designs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Sourcing | Taiwan foundry partnerships reduce allocation volatility exposure during semiconductor capacity crunches. |
| COB Architecture Fleet Refresh | F-Gas Regulation deadlines accelerate adoption of heat-dissipating packaging for outdoor durability. |
| Hub-and-Spoke Logistics Expansion | Regional fleet positioning captures advantage under emerging EU Green Deal carbon accounting rules. |
| Mesh-Networked Control Platform Launch | Wireless protocol integration eliminates cable infrastructure while introducing FCC Part 15 compliance complexity. |
| Transparent LED Premium Tier Development | Architectural integration into temporary facades opens premium rental tiers for see-through diode arrays. |
Research Methodology
A standing panel of festival production managers, rental fleet operators, LED module procurement leads, and broadcast technical directors provided ongoing calibration across primary fieldwork. Secondary validation drew from EU F-Gas Regulation filings, CE marking certification databases, customs records on aluminum extrusion trade flows, and SEC disclosures from publicly listed display manufacturers. Bottom-up triangulation across cabinet-level cost structures converged with top-down market sizing across Germany's live events corridor.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation modeling spanning mobile versus transparent versus fixed product configurations, SMD versus COB technology architectures, and modular versus networked versus integrated integration levels. CAGRs derived from unit deployment velocity assumptions tied to festival season density and rigging window compression trends. Forecast inputs incorporated aluminum pricing volatility indices and Taiwan foundry capacity utilization proxies.
Practitioners should monitor LED driver IC allocation volatility, F-Gas Regulation enforcement milestone timing, and carbon accounting rule finalization for early signals of forecast revision triggers. Forecasts reflect assumptions around sustained festival season demand concentration and continued Shenzhen manufacturing dominance. Material shifts in semiconductor export-control regimes or EU cooling system energy-efficiency standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Backlit Displays Market
Display Technologies
Thin Display Technology Market
Display Technologies
Commercial Display Market
Display Technologies
Field Emission Display Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Display Control and Management System Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
Gaming Monitors Market
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Light Field Display Market
Display Technologies
Display Glass Substrate Market
Display Technologies
LCD Panel Market
Display Technologies
Portable Projector Market
Display Technologies
Phosphor Screen Market
Display Technologies
Interferometric Modulator Display Market