
 Train Battery Market | 2026-2036
Train Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Train Battery Market Intelligence
Advanced lithium-ion cell chemistry with higher energy density and extended cycle life is reshaping how train battery systems are engineered for rail applications. Saft leverages its vertical integration in cell manufacturing to sustain long-term supply contracts with European rail OEMs. EnerSys anchors its position through deep specialization in nickel-cadmium backup systems for legacy rolling stock retrofits. GS Yuasa Corporation competes by controlling critical portions of the Asian supply chain for commuter and metro train deployments.
Train batteries are electrochemical energy storage systems engineered to deliver auxiliary power, starter functions, and emergency backup for locomotives and multiple-unit trains, typically specified for operating temperatures between minus 20 and plus 50 degrees Celsius with cycle life exceeding 2,000 charge-discharge events. Their primary purpose is ensuring reliable power delivery for lighting, braking, control systems, and propulsion support independent of overhead catenary or third-rail supply. Lithium-ion and solid-state chemistries are capturing margin pools as rail operators prioritize weight reduction and fast-charging compatibility. Lead acid retains volume in freight locomotive starter applications where capital constraints dominate procurement criteria. Metro systems and commuter trains represent the fastest-expanding application cluster as urban transit authorities electrify corridor services.
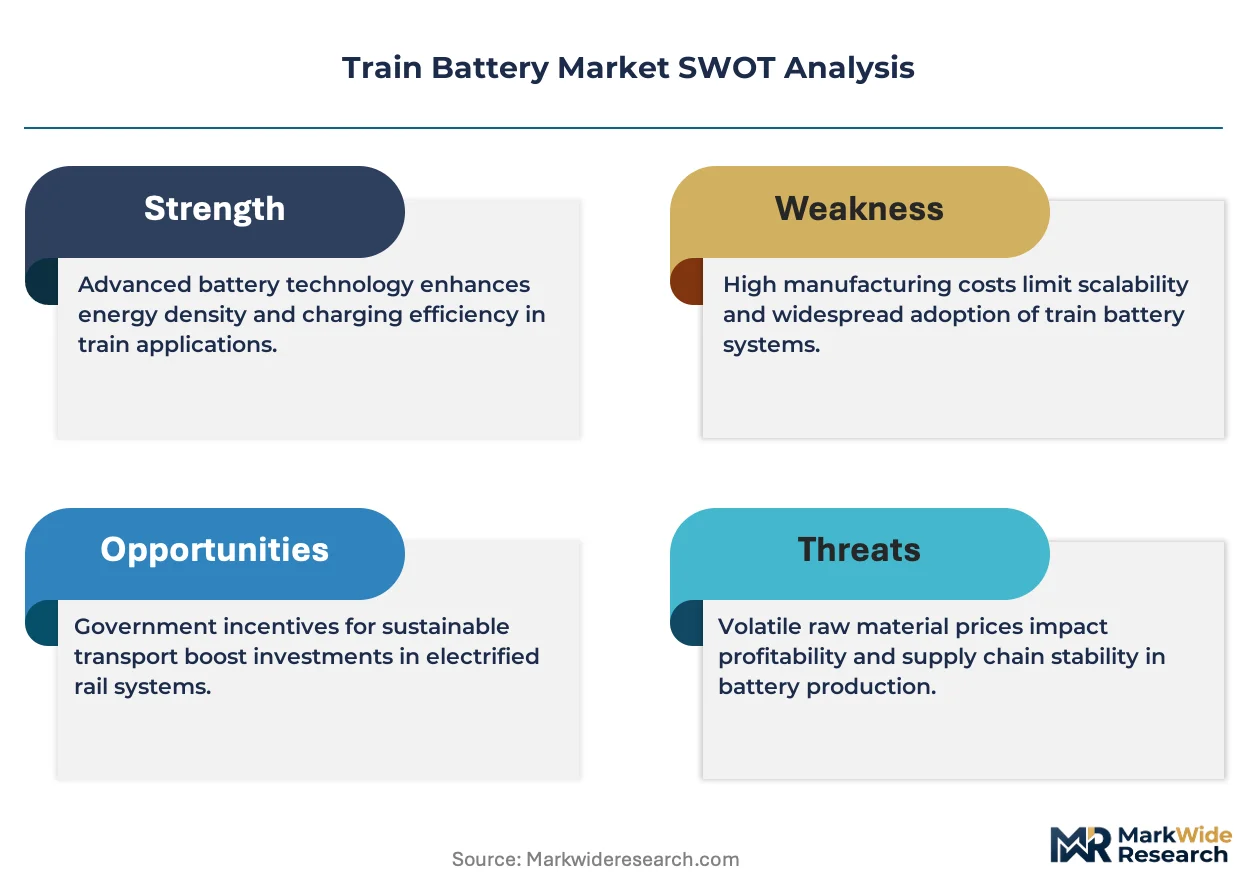
The EPA enforces emissions benchmarks that indirectly pressure North American freight operators toward battery-assisted idle reduction, while the EU Green Deal and F-Gas Regulation restrict fluorinated greenhouse gases in cooling systems, altering thermal management design requirements for battery packs deployed across European networks. India's BIS certification mandates and PLI scheme incentives are accelerating domestic battery assembly for railway applications. Stakeholders must monitor how evolving carbon-border mechanisms and chemistry-specific recycling mandates reshape supplier qualification criteria and long-term contract structures.
Market Dynamics
The EU F-Gas Regulation phase-down is forcing thermal management redesigns across European rolling stock, compressing supplier qualification timelines and redirecting procurement toward solid-state battery architectures that eliminate fluorinated cooling systems entirely.
Growth Catalysts
- EU Green Deal decarbonization mandates:National rail operators in Germany, France, and the Netherlands face binding fleet electrification targets that accelerate battery procurement for diesel-to-electric conversions.
- Lithium iron phosphate chemistry maturation:Cell-level energy density improvements above 180 Wh/kg enable single-battery solutions for auxiliary loads previously requiring dual-system redundancy.
- India PLI scheme incentives:Domestic assembly subsidies reduce landed cost gaps for Mumbai Metro and Delhi-Meerut RRTS projects, accelerating localized supply chain formation.
Market Restraints
- Lithium carbonate price volatility:Cathode material input costs swing 40-60% annually, compressing OEM margins on fixed-price rolling stock contracts.
- Nickel-cadmium supplier concentration:Two European foundries control 70% of aerospace-grade cadmium anode supply, creating single-source risk for legacy train retrofits.
- REACH substance restrictions:Cobalt and nickel compound classification shifts threaten existing cell formulations with mandatory substitution timelines.
Strategic Opportunities
- Second-life stationary storage:Retired metro train batteries retain 70-80% capacity, opening circular economy revenue streams for utilities and grid operators.
- Battery-swapping infrastructure:Automated exchange systems at terminal stations enable smaller onboard packs, reducing axle load and tunnel clearance constraints.
- Japan METI hydrogen-battery hybrid standards:Regulatory frameworks for fuel cell-battery dual propulsion create new system integration service markets.
Industry Challenges
- Functional safety certification backlog:EN 50126/8/9 railway safety case documentation creates 14-18 month approval delays for new cell suppliers.
- Thermal runaway containment engineering:Cell-to-cell propagation testing under UN 38.3 requires specialized fire suppression integration that few rail OEMs maintain in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Battery Market |
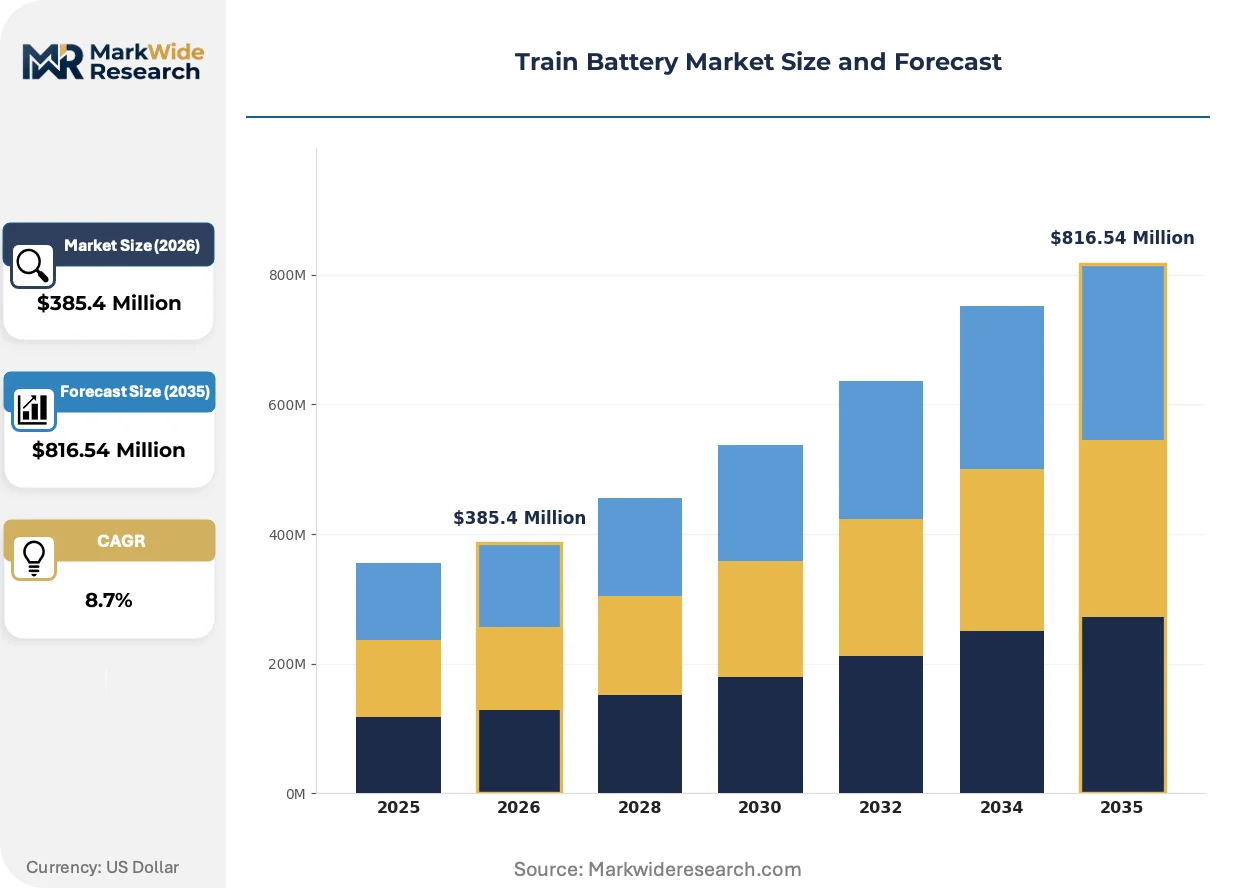
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Lead Acid, Nickel-Cadmium, Sodium-Sulfur, Solid-State, Flow Batteries Application: High-Speed Rail, Commuter Trains, Freight Trains, Light Rail, Metro Systems, Monorails Technology: Advanced Battery Management, Thermal Management, Fast Charging, Energy Recovery, Modular Design, Smart Monitoring End User: Urban Transit Authorities, Freight Operators, Passenger Service Providers, Railway Maintenance Companies, Vehicle Equipment Suppliers |
| Companies Covered | Saft, EnerSys, GS Yuasa Corporation, Exide Industries, Amara Raja Group, HOPPECKE Batteries GmbH & Co. KG, East Penn Manufacturing Company, AEG Power Solutions, First National Battery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Battery Market Strategic Shifts & Innovations
Solid-state electrolyte architectures are migrating from laboratory validation to commercial tender requirements, compressing the competitive window for incumbent liquid-electrolyte suppliers. Three distinct vectors are reshaping how train battery systems are specified, procured, and deployed.
Solid-state lithium-metal cells are migrating from aerospace qualification programs into commuter rail specifications. Japanese and Korean rail OEMs now require solid-state pilot installations for 2027-2028 metro deliveries, forcing European suppliers to accelerate their own electrolyte ceramic processing capabilities or risk exclusion from Asian tender processes.
The EU F-Gas Regulation bans refrigerants with GWP above 150 in new rolling stock from 2025, eliminating conventional HVAC-cooled battery packs. Manufacturers respond with phase-change material thermal mass systems and direct liquid cooling loops that use water-glycol mixtures, adding 8-12% to pack mass but ensuring compliance without fluorinated gases.
Indian Railways now mandates 75% domestic value addition under its revised rolling stock procurement rules. Foreign cell suppliers must form joint ventures with BIS-certified assemblers, transferring module integration know-how to Indian partners. This localization push fragments what had been centralized supply relationships with European and Japanese battery makers.
Train Battery Market Segmentation
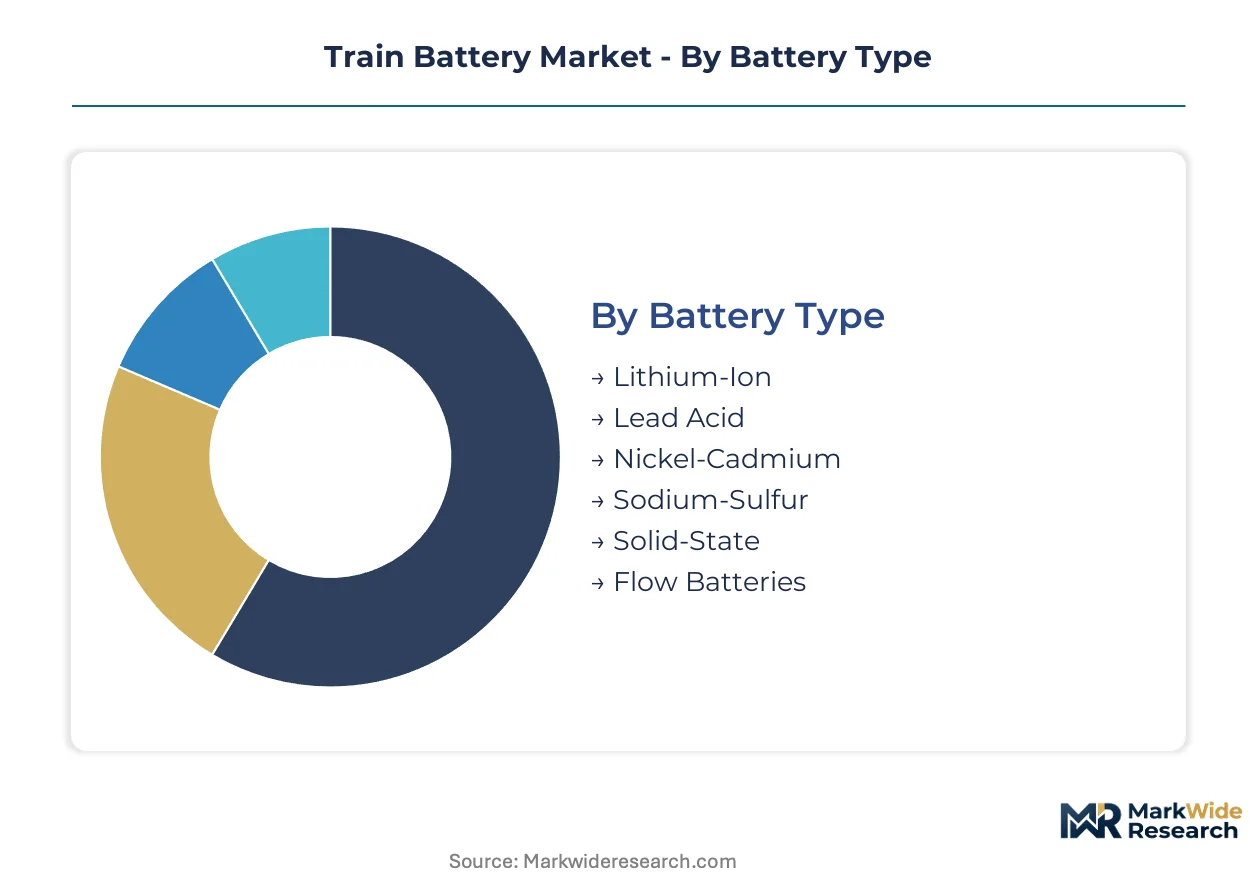
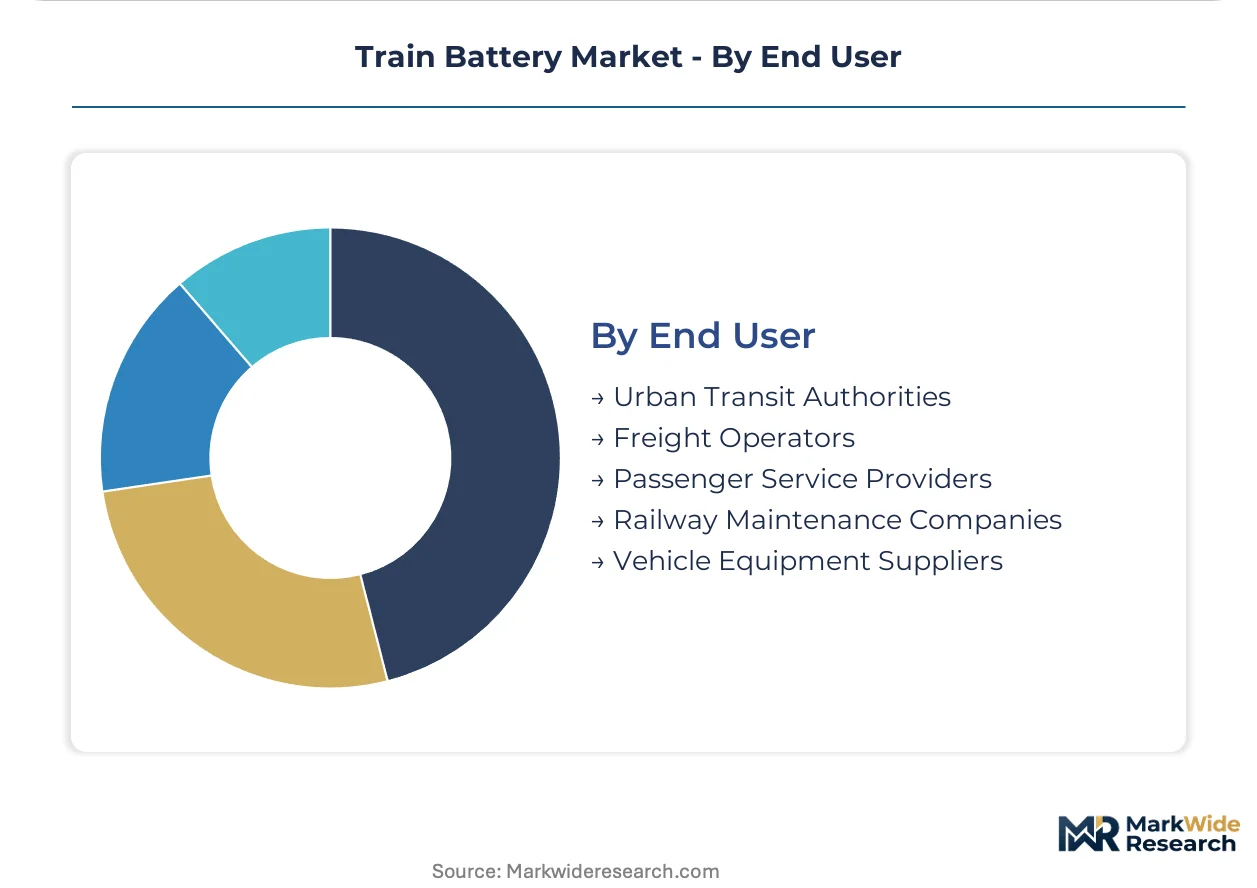
Rail operators specify battery systems against divergent duty cycles, thermal environments, and regulatory constraints. Segmentation reveals how chemistry selection, application context, and technology integration determine procurement priorities and supplier qualification pathways across electrification programs.
Battery Type:
The chemistry spectrum spans mature electrochemical systems and emerging solid-state architectures, each commanding distinct margin structures and qualification timelines.
- Lithium-Ion:Lithium iron phosphate and nickel-manganese-cobalt cells deliver 180+ Wh/kg energy density with 2,000+ cycle life. Metro operators in Germany and Japan specify these for auxiliary power and regenerative braking storage, driven by weight reduction mandates and fast-charging infrastructure compatibility.
- Solid-State:Ceramic electrolyte architectures eliminate liquid thermal runaway risks while enabling lithium-metal anodes. Korean and Japanese rail OEMs now require pilot installations for metro deliveries, pressured by F-Gas Regulation compliance and Asian tender specifications.
- Lead Acid:Flooded and valve-regulated designs persist in freight locomotive starter applications where capital constraints dominate over energy density.
- Nickel-Cadmium:Aerospace-grade sintered plate cells serve legacy rolling stock retrofits requiring extreme temperature resilience.
- Sodium-Sulfur:High-temperature ceramic electrolyte systems find niche deployment in stationary grid buffering at rail depots.
- Flow Batteries:Vanadium redox systems enable multi-hour discharge duration for off-grid maintenance facilities.
The dominant share belongs to Lithium-Ion, while Solid-State is closing the gap fastest.
Application:
Service patterns and infrastructure access dictate pack sizing, cycle depth, and charging protocol specifications.
- Metro Systems:Frequent stop-start cycles with 30-60 second station dwell times demand high C-rate capability and regenerative braking integration. Delhi-Meerut RRTS and Mumbai Metro procurements specify 15-year service life with 90% availability guarantees.
- High-Speed Rail:Traction power for catenary gaps and emergency backup requires 400+ kWh packs with aerospace-grade reliability certification.
- Commuter Trains:Diesel-to-electric conversion programs in the Netherlands and France drive hybrid battery-diesel tender specifications.
- Freight Trains:Yard switching and road locomotive starter functions prioritize cold-cranking amps over energy density.
- Light Rail:Catenary-free street running in historic districts necessitates onboard storage with rapid opportunity charging.
- Monorails:Straddle-beam configurations impose severe axle load limits, favoring lithium-ion over legacy chemistries.
Metro Systems command the largest procurement volume, though High-Speed Rail exhibits the steepest expansion trajectory.
Technology:
System-level integration capabilities separate qualified suppliers from commodity cell providers in rail tender evaluations.
- Thermal Management:Phase-change materials and water-glycol direct liquid cooling replace fluorinated refrigerants to satisfy EU F-Gas Regulation mandates, adding 8-12% to pack mass.
- Fast Charging:Pantograph-down opportunity charging at 3C+ rates requires specialized anode formulations and predictive thermal algorithms.
- Advanced Battery Management:Cell-level voltage and temperature monitoring with SIL-2 safety integrity enables predictive maintenance and warranty risk reduction.
- Energy Recovery:Regenerative braking capture and catenary re-injection circuits improve system-level efficiency metrics.
- Modular Design:Hot-swappable rack configurations reduce mean time to repair for revenue-service availability guarantees.
- Smart Monitoring:Cloud-connected state-of-health telemetry supports condition-based maintenance and second-life residual valuation.
Thermal Management attracts the most engineering investment, while Fast Charging is gaining specification priority fastest.
End User:
Procurement authority fragmentation across public and private entities shapes contract structures and financing mechanisms.
- Urban Transit Authorities:Municipal and regional operators in Germany, France, and India bundle battery procurement with rolling stock tenders, favoring long-term service contracts over capital purchase.
- Freight Operators:North American Class I railroads evaluate battery-assisted idle reduction under EPA emissions benchmarking, with payback periods driving adoption timing.
- Passenger Service Providers:Open-access operators in competitive markets prioritize interoperability and multi-vendor sourcing flexibility.
- Railway Maintenance Companies:Infrastructure contractors procure portable battery systems for track work vehicles and signaling backup.
- Vehicle Equipment Suppliers:Tier-1 integrators source cells and modules for OEM platform integration, controlling supplier qualification pathways.
Urban Transit Authorities dominate procurement volume, though Freight Operators are expanding specifications most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports advanced lithium-ion cell technology to European rail OEMs, while South Korean solid-state developers supply pilot systems to Asian metro operators. Germany anchors procurement volume through Deutsche Bahn electrification mandates.
Germany
Deutsche Bahn's fleet electrification targets drive battery procurement for diesel-to-electric conversions on regional corridors. The EU F-Gas Regulation bans refrigerants above 150 GWP from 2025, forcing thermal management redesigns for battery packs. Siemens Mobility and Alstom Deutschland source cells from domestic integrators in Bavaria and Baden-Württemberg.
India
Mumbai Metro and Delhi-Meerut RRTS projects accelerate localized battery assembly under PLI scheme subsidies. BIS certification mandates require 75% domestic value addition for rolling stock procurement. Foreign suppliers form joint ventures with certified assemblers in Maharashtra and Gujarat, transferring module integration capabilities.
Japan
East Japan Railway and Tokyo Metro specify solid-state pilot installations for 2027-2028 commuter deliveries. METI hydrogen-battery hybrid standards create new system integration service markets. Kawasaki Heavy Industries and Hitachi Rail anchor demand in the Kanto and Kansai industrial corridors.
South Korea
Seoul Metro and Korail expand regenerative braking storage specifications for high-frequency urban lines. Domestic cell manufacturers supply ceramic electrolyte systems for pilot deployments. Busan-Ulsan manufacturing clusters host module integration facilities serving Asian tender processes.
United States
Class I freight railroads evaluate battery-assisted idle reduction under EPA emissions benchmarking. California Air Resources Board rules pressure Union Pacific and BNSF toward electrified yard operations. Chicago and Los Angeles rail hubs concentrate procurement authority for corridor electrification pilots.
Train Battery Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered qualification pathways. European and Asian OEMs dominate rolling stock integration contracts, while dedicated battery manufacturers supply cells and modules through long-term service agreements. Three archetypes define competitive positioning: vertically integrated cell producers, system integrators with thermal management specialization, and regional assemblers leveraging localization incentives. Capacity expansion and strategic partnerships constitute the dominant competitive moves, particularly around solid-state electrolyte processing and F-Gas-compliant thermal architectures.
Within the European specialist tier, Saft and EnerSys exemplify divergent positioning strategies. Saft represents vertically integrated cell manufacturing with captive supply relationships to rail OEMs. EnerSys occupies a position emphasizing legacy system maintenance and retrofit service contracts. GS Yuasa Corporation anchors the Asian supply chain archetype, with geographic naming indicating Japanese origin and corporate structure suggesting public company status. These three entities illustrate how chemistry specialization and regional market access determine competitive boundaries.
| Leading Market Players |
|---|
| Saft |
| EnerSys |
| GS Yuasa Corporation |
| Exide Industries |
| Amara Raja Group |
| HOPPECKE Batteries GmbH & Co. KG |
| East Penn Manufacturing Company |
| AEG Power Solutions |
| First National Battery |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese lithium carbonate refining is compressing cathode material margins and forcing European cell integrators toward long-term offtake contracts to lock in feedstock costs. This utilization dynamic concentrates pricing power with raw material processors while rail OEMs absorb volatility through fixed-price rolling stock tenders.
Pricing Analysis
The technology-generation pricing gap separates solid-state pilot installations at premium tiers from mature lithium iron phosphate systems at standard levels and legacy lead-acid starter batteries at economy tiers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in standard-tier LFP systems is intensifying because Indian PLI subsidies are accelerating localized assembly. Freight operators in North America exhibit the highest price sensitivity due to capital constraints and EPA-driven payback period calculations, while Japanese metro authorities show the lowest sensitivity given solid-state pilot mandates.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for European rail OEMs sourcing processed cathode materials. Cell manufacturing concentrates in China, South Korea, and Japan, with module integration increasingly shifting to India and Germany to satisfy localization mandates. The supply chain draws from lithium carbonate, nickel sulfate, and cobalt hydroxide feedstocks, with single-source vulnerability concentrated in aerospace-grade cadmium anode supply for legacy nickel-cadmium retrofits. Distribution runs through Tier-1 rolling stock integrators who control supplier qualification pathways and long-term service contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as diesel-to-electric conversion programs across multiple geographies create specialized demand niches for hybrid battery-diesel system integrators.
For Market Incumbents: Insulate core supply relationships by securing captive lithium carbonate offtake from Chinese refiners and accelerating EN 50126/8/9 certification investments to extend approval timelines for new cell suppliers. Solid-state electrolyte processing capabilities represent the critical defensive lever against Asian OEM pilot mandates. For New Entrants and Emerging Players: India's underpenetrated domestic assembly market offers the most penetrable entry point through joint ventures with BIS-certified module integrators in Maharashtra and Gujarat. Target second-life stationary storage applications for retired metro batteries as a service-based go-to-market angle that bypasses rolling stock OEM qualification barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among thermal management specialists with F-Gas-compliant phase-change material systems. Long-term viability over the projection horizon favors acquiring system integrators with SIL-2 safety integrity certification and established rail OEM service contracts. The signal to watch is solid-state pilot installation win rates in Japanese and Korean metro tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Electrolyte Processing Investment | Captures premium positioning as Japanese OEMs mandate ceramic electrolyte pilots for metro deliveries. |
| F-Gas-Compliant Thermal Management Development | Ensures European market access as EU regulations ban refrigerants above 150 GWP from 2025. |
| Indian Joint Venture Formation | Unlocks PLI scheme subsidies and satisfies BIS certification mandates for domestic value addition. |
| Second-Life Storage Service Launch | Monetizes residual 70-80% capacity in retired metro batteries through utility grid contracts. |
| Long-Term Cathode Material Offtake | Hedges lithium carbonate volatility through fixed-price contracts with Chinese refiners. |
Research Approach
Initial hypotheses were tested against primary input from rolling stock procurement managers, battery system engineers at Tier-1 integrators, thermal management specialists, and rail operator maintenance directors, and refined through secondary validation against SEC filings from listed battery manufacturers, ECHA REACH substance restriction updates, EU F-Gas Regulation implementation guidance, and Indian Railways procurement notices. Bottom-up cell demand modeling triangulated against top-down rolling stock delivery forecasts.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled across battery chemistry type, rail application category, thermal management technology, and end-user procurement authority. CAGRs were derived from fitted growth curves calibrated to named electrification program timelines and regulatory mandate enforcement schedules. Forecast inputs incorporated lithium carbonate price elasticity coefficients and EN 50126 safety case approval duration assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese solid-state developers or accelerated EU F-Gas phase-down schedules would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Railway Lithium Battery Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
E-Axle Market
Electric Vehicles
Europe Electric Vehicle Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
Electric Vehicle (EV) Fluids Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
Asia-Pacific Electric Bus Market
Electric Vehicles
E-Bike Accessories Market