
 North America Electric Vehicle (EV) Fluids Market | 2026-2036
North America Electric Vehicle (EV) Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle (EV) Fluids Market Outlook
Fleet operators is reorganizing procurement priorities as electrified commercial transport scales across North America, pulling volume away from traditional automaker-direct contracts. Shell plc leverages its integrated lubricant supply chain to anchor long-term service agreements with logistics providers. Valvoline Global Operations competes through its quick-lube network footprint, converting existing bays for EV fluid servicing. FUCHS specializes in high-performance thermal management formulations, positioning its R&D labs to meet OEM validation cycles.
North America Electric Vehicle Fluids comprise engineered dielectric coolants, low-conductivity greases, and thermally stable transmission lubricants formulated for electrified powertrains, typically operating within temperature ranges of minus forty to one hundred fifty degrees Celsius to manage battery thermal runaway and motor efficiency. Their primary commercial purpose centers on extending component life, maintaining dielectric integrity, and optimizing energy density in high-voltage systems. Cooling Fluids and Thermal Management Fluids together command the dominant margin pool, as battery pack energy densities rise and fast-charging protocols intensify heat rejection requirements. Passenger Vehicles remains the volume anchor, though Fleet Vehicles represents the fastest-growing application segment as electrified delivery and transit contracts multiply.
The EPA tailpipe emissions framework and California Air Resources Board zero-emission vehicle mandates jointly compel fluid suppliers to certify formulations against evolving dielectric strength and biodegradability thresholds. NHTSA safety standards for battery thermal propagation further shape product development roadmaps, requiring coolants that suppress cell-to-cell fire spread. Stakeholders must monitor how state-level procurement preferences and utility fleet electrification timelines reshape channel structures between direct OEM supply and aftermarket distribution.
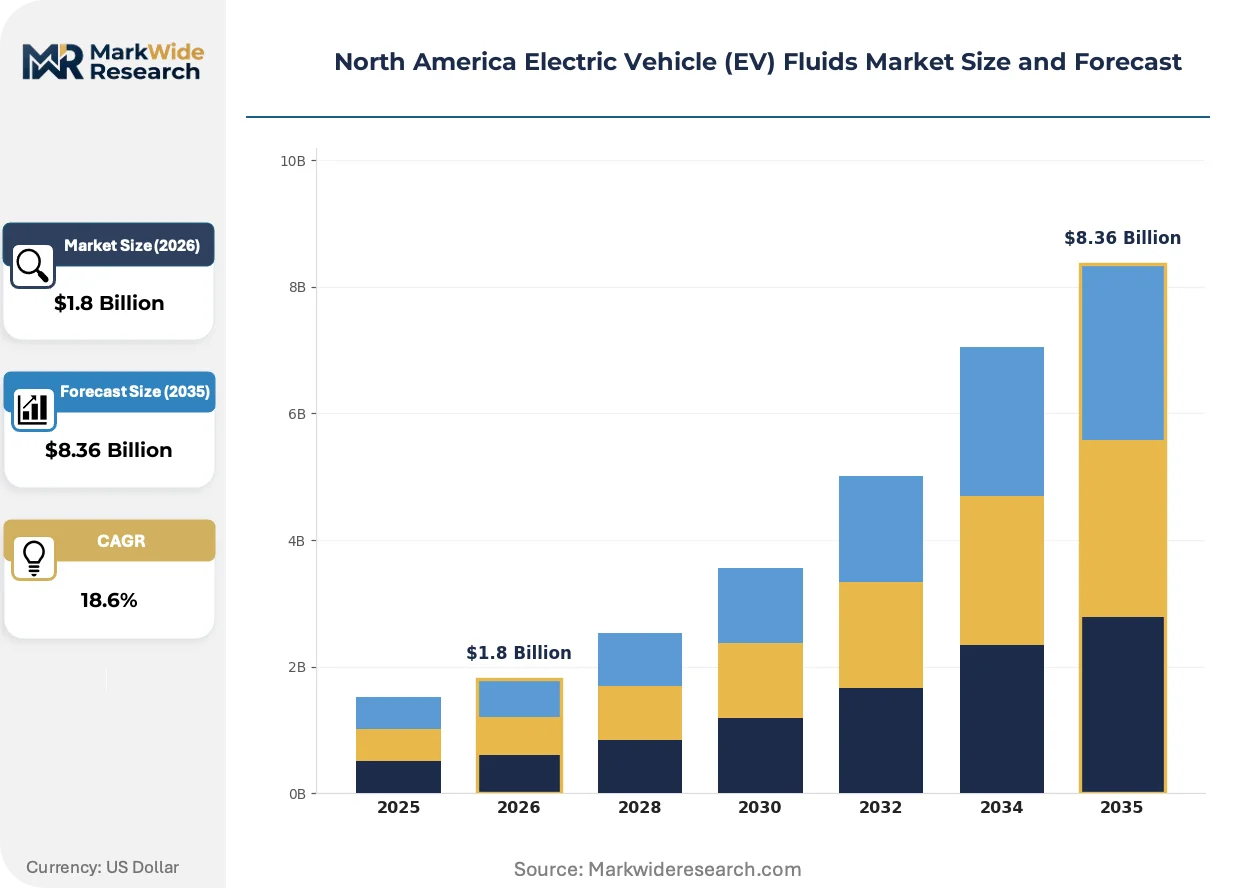
Market Dynamics
Fleet electrification timelines are compressing procurement cycles across North America, forcing fluid suppliers to revalidate formulations against OEM thermal management specifications at unprecedented speed. The shift from automaker-direct contracts to logistics-fleet bulk purchasing is restructuring channel economics and margin capture.
Growth Catalysts
- EPA Tailpipe Emissions Framework:The tightening standards compel commercial vehicle operators to electrify, generating sustained demand for dielectric coolants and thermal management fluids in heavy-duty battery systems.
- Battery Gigafactory Clustering:Tennessee, Georgia, and South Carolina production hubs concentrate regional demand, creating localized economies of scale for fluid distribution and technical service infrastructure.
- Fast-Charging Protocol Intensification:Higher amperage charging stations generate elevated heat rejection requirements, pulling advanced coolant formulations into mainstream commercial deployment faster than baseline projections anticipated.
Market Restraints
- Base Oil Supply Concentration:North American production of Group III+ and polyalphaolefin base stocks concentrates among a limited refiner set, exposing formulators to input cost volatility and allocation constraints.
- Dielectric Strength Validation Bottlenecks:OEM thermal propagation testing cycles extend eighteen to thirty-six months, delaying commercialization of next-generation coolant chemistries regardless of laboratory performance.
- Legacy ICE Service Infrastructure:Existing quick-lube bays require capital conversion for high-voltage system handling, slowing aftermarket penetration in rural and secondary metropolitan markets.
Strategic Opportunities
- Canadian Commercial Transit Electrification:Provincial zero-emission bus mandates and federal transit infrastructure funding create underpenetrated demand corridors for thermal fluid suppliers with cold-climate formulation expertise.
- Second-Life Battery Thermal Management:Stationary energy storage repurposing of automotive battery packs requires adapted coolant chemistries, opening adjacent revenue streams outside original equipment supply chains.
- California Advanced Clean Trucks Regulation:The phased mandate for medium- and heavy-duty zero-emission vehicles generates regulatory tailwind for fluid formulators with CARB-certified low-conductivity product portfolios.
Industry Challenges
- High-Voltage Safety Technician Scarcity:Fleet maintenance operations face acute shortages of technicians certified for high-voltage system fluid servicing, constraining aftermarket service network expansion regardless of product availability.
- Multi-OEM Validation Fragmentation:Each battery manufacturer maintains proprietary thermal management specifications, forcing suppliers to maintain parallel formulation tracks and diluting R&D efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle (EV) Fluids Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Fluids, Thermal Management Fluids, Brake Fluids, Transmission Fluids Application: Passenger Vehicles, Commercial Vehicles, Fleet Vehicles, E-Bikes Technology: Battery Electric Vehicles, Plug-In Hybrid Vehicles, Fuel Cell Electric Vehicles, Range-Extended Electric Vehicles End User: Automakers, Aftermarket Providers, Fleet Operators, Distributors |
| Companies Covered | Exxon Mobil Corporation, Shell plc, TotalEnergies, Valvoline Global Operations, FUCHS, BP Plc, Petroliam Nasional Berhad (PETRONAS), Lubrizol Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle (EV) Fluids Market Strategic Shifts
Thermal management architectures are undergoing fundamental redesign as battery energy densities climb and charging speeds accelerate, compressing development timelines for fluid formulators. Three interconnected developments are reshaping competitive positioning.
Single-phase dielectric coolants are displacing traditional glycol-water mixtures in premium battery pack designs, offering superior electrical insulation and reduced corrosion risk. European luxury EV manufacturers have adopted these formulations for flagship platforms, and North American OEMs are accelerating validation programs to match. The technology is miniaturizing thermal management hardware footprints, enabling packaging efficiency gains that translate directly to vehicle range extension.
California Air Resources Board zero-emission vehicle mandates are cascading into fluid formulation requirements through dielectric strength and biodegradability certification thresholds. Formulators must now submit to CARB-validated testing protocols before commercial deployment in vehicles sold within the state. Heavy-duty truck and transit bus segments face the most compressed compliance timelines, driving concentrated investment in biodegradable ester-based chemistries.
Fleet procurement departments are consolidating fluid purchasing under long-term service agreements that bundle predictive maintenance analytics with volume supply commitments. Direct OEM supply relationships are losing share to logistics-provider contracts that specify performance-based fluid monitoring and replacement scheduling. This restructuring is most visible in the US Southeast, where Amazon, UPS, and FedEx electrification hubs are negotiating regional master service agreements with integrated lubricant suppliers.
North America Electric Vehicle (EV) Fluids Market Segmentation
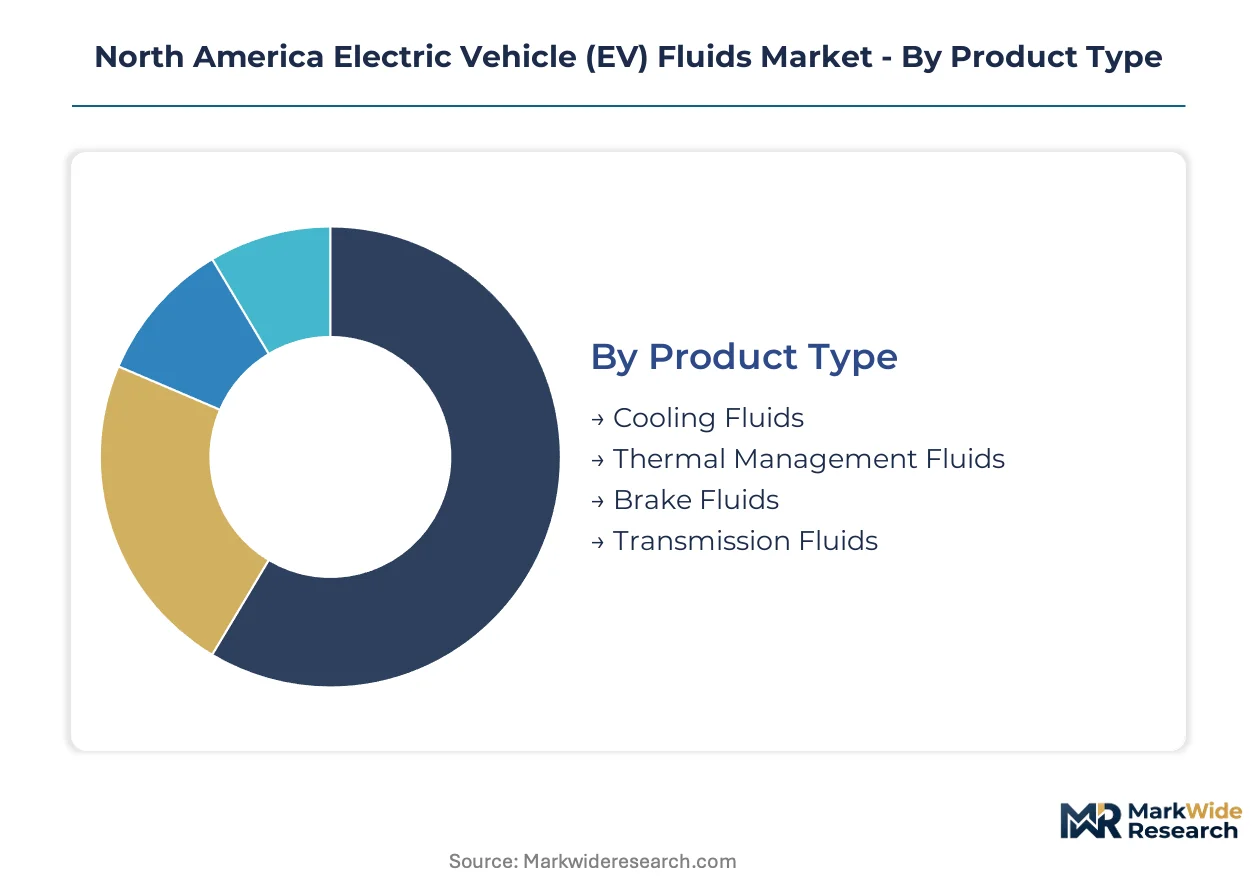
North America Electric Vehicle (EV) Fluids Market segmentation reveals how regulatory pressure and electrification speed reshape demand across product categories. Each dimension exposes distinct margin structures and validation requirements that suppliers must navigate.
Product Type:
EPA emissions standards and California Air Resources Board mandates differentiate fluid specifications by thermal performance and biodegradability thresholds, forcing formulators to align chemistries with compliance tiers.
- Cooling Fluids:Engineered dielectric formulations manage battery pack temperatures across minus forty to one hundred fifty degrees Celsius operating ranges. Tennessee, Georgia, and South Carolina battery gigafactories concentrate procurement for these fluids as regional production capacity scales.
- Thermal Management Fluids:Single-phase dielectric chemistries displace glycol-water mixtures in premium platforms, offering superior electrical insulation and corrosion resistance. Fast-charging protocol intensification across the US Southeast pulls advanced formulations into commercial deployment faster than baseline projections.
- Brake Fluids:Low-conductivity synthetic formulations address regenerative braking system thermal loads in electrified powertrains.
- Transmission Fluids:Thermally stable lubricants optimized for single-speed and multi-speed e-axle configurations in heavy-duty applications.
Cooling Fluids handles the majority of throughput; Thermal Management Fluids is the fastest mover on share.
Application:
Cost tier differentiation separates high-volume passenger specifications from premium fleet-grade formulations with integrated predictive maintenance analytics.
- Passenger Vehicles:Standardized fluid specifications dominate volume, with automaker-direct contracts still anchoring supply relationships. California zero-emission vehicle mandates compress validation cycles for dielectric coolant formulations in this segment.
- Fleet Vehicles:Electrified delivery and transit contracts multiply across Amazon, UPS, and FedEx electrification hubs, consolidating procurement under long-term service agreements. Bulk purchasing restructuring pulls volume away from traditional automaker-direct channels.
- Commercial Vehicles:Medium- and heavy-duty applications face EPA tailpipe emissions framework compliance deadlines.
- E-Bikes:Compact thermal management requirements for two-wheel electrification in urban mobility corridors.
Passenger Vehicles captures the dominant volume position; Fleet Vehicles expands most quickly as logistics electrification accelerates.
Technology:
Application maturity varies by electrification architecture, with pure battery platforms commanding formulation investment priority over transitional hybrid systems.
- Battery Electric Vehicles:Full electrification architectures require comprehensive thermal management suites spanning battery packs, motors, and power electronics. NHTSA battery thermal propagation standards shape coolant development roadmaps for suppressing cell-to-cell fire spread.
- Plug-In Hybrid Vehicles:Dual powertrain fluid requirements create complex formulation portfolios balancing ICE legacy specifications with emerging EV thermal management needs.
- Fuel Cell Electric Vehicles:Specialized coolant chemistries manage fuel cell stack thermal stability and membrane hydration.
- Range-Extended Electric Vehicles:Series-hybrid architectures with auxiliary power units demand segmented fluid strategies for electric and combustion subsystems.
Battery Electric Vehicles anchors current formulation development; Plug-In Hybrid Vehicles retains transitional relevance as fleet operators phase toward full electrification.
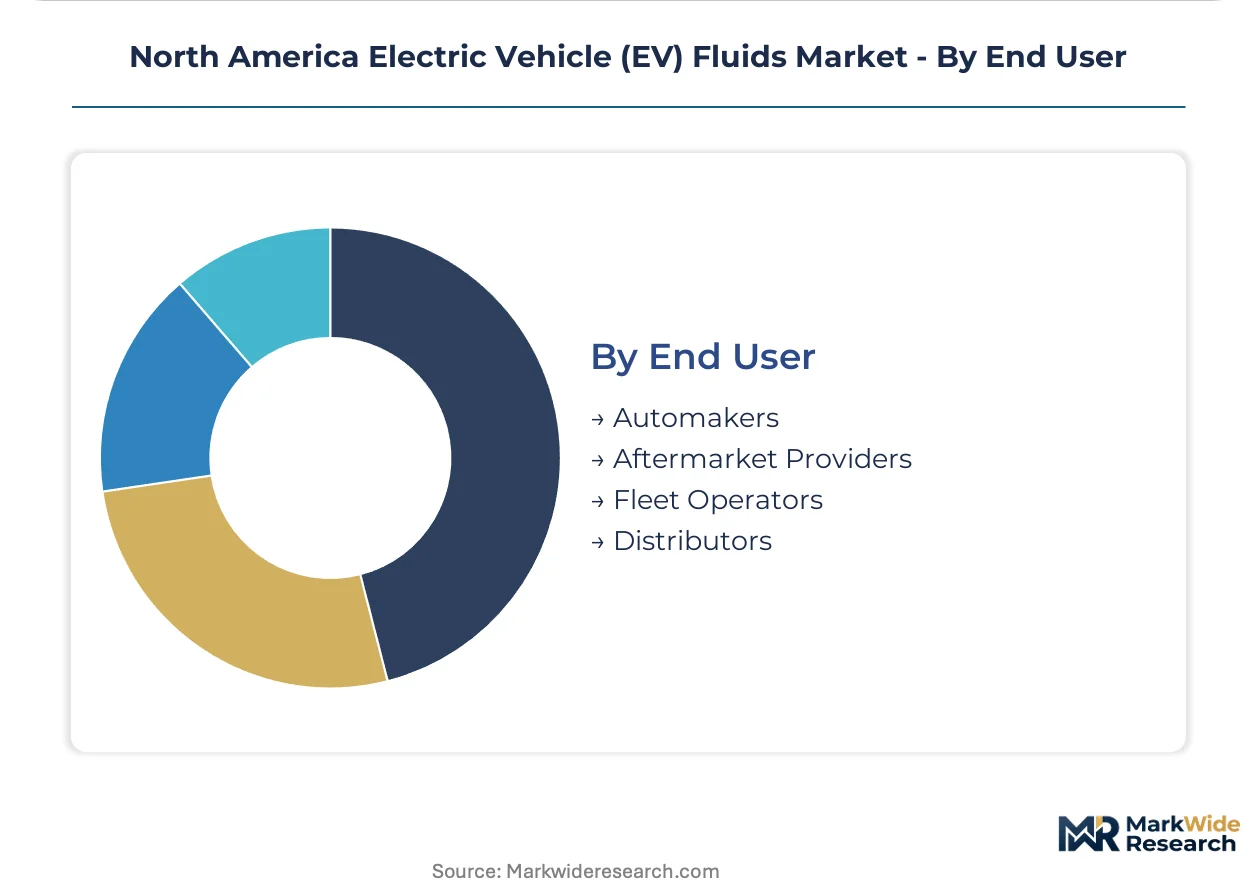
End User:
Customer type restructuring reconfigures channel economics, with direct OEM supply losing ground to consolidated fleet procurement and aftermarket conversion.
- Automakers:Original equipment specifications drive validation-intensive development cycles, with each battery manufacturer maintaining proprietary thermal management requirements. Multi-OEM validation fragmentation forces suppliers to maintain parallel formulation tracks.
- Fleet Operators:Logistics providers negotiate regional master service agreements bundling predictive maintenance analytics with volume supply commitments. The shift from automaker-direct contracts to logistics-fleet bulk purchasing restructures margin capture across the US Southeast.
- Aftermarket Providers:Quick-lube bay conversion for high-voltage system handling constrains network expansion in rural and secondary metropolitan markets.
- Distributors:Intermediate channel positioning between formulators and service networks.
Automakers retains specification authority; Fleet Operators gains procurement leverage fastest as electrified logistics networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base oil refining capacity and battery manufacturing investments concentrate fluid demand across three national markets. EPA tailpipe standards and provincial zero-emission mandates reshape procurement geography. Industrial clustering around automotive electrification corridors determines regional competitive intensity.
United States
Tennessee, Georgia, and South Carolina battery gigafactories anchor continental production scale. EPA tailpipe emissions framework and California's Advanced Clean Trucks regulation compel dielectric coolant certification cycles. The US Southeast concentrates Amazon, UPS, and FedEx electrification hubs negotiating regional master service agreements.
Canada
Provincial zero-emission bus mandates and federal transit infrastructure funding accelerate commercial fleet conversion. Health Canada's environmental assessment protocols align with EPA biodegradability thresholds for cross-border formulation approval. Ontario and Quebec manufacturing corridors develop cold-climate thermal management expertise for Arctic logistics applications.
Mexico
Nearshoring of EV component assembly pulls fluid demand southward as US-Mexico-Canada Agreement trade rules reshape supply chains. The country's national environmental regulator enforces emerging dielectric fluid discharge standards for maquiladora operations. Nuevo León and Bajío Region industrial parks attract thermal management supplier co-location.
North America Electric Vehicle (EV) Fluids Market Competitive Environment
Concentration sits with integrated petroleum majors and specialized lubricant formulators competing across validation-intensive OEM channels. The market structures around three archetypes: multinational energy corporations with captive base oil supply, independent lubricant specialists with quick-lube distribution networks, and chemical companies with additive technology portfolios. Competitive moves center on long-term fleet service agreements and dielectric formulation patent filings.
Among integrated energy majors, Exxon Mobil Corporation and Shell plc exemplify scale-driven archetypes with backward integration into Group III+ base stock production. Valvoline Global Operations occupies the independent service network position, converting quick-lube infrastructure for high-voltage system handling. FUCHS represents the specialized formulator archetype, anchoring technical validation relationships with battery OEMs.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Shell plc |
| TotalEnergies |
| Valvoline Global Operations |
| FUCHS |
| BP Plc |
| Petroliam Nasional Berhad (PETRONAS) |
| Lubrizol Corporation |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-thirty-six month OEM validation cycles compress inventory turns and concentrate pricing power with validated suppliers holding CARB-certified formulations. Base oil allocation constraints and dielectric strength certification bottlenecks tether margin capture to upstream refining capacity and downstream technical service infrastructure.
Pricing Analysis
California's Advanced Clean Trucks regulation dictates the pricing tier structure across the North America EV fluids market, stratifying formulations by CARB dielectric strength and biodegradability certification levels. Three-tier pricing separates OEM-validated premium dielectric coolants from standard fleet-grade thermal management fluids and economy glycol-water alternatives. Cost compression in standard tiers intensifies because Group III+ base oil supply concentrates among limited North American refiners. Fleet procurement departments exhibit highest price sensitivity through consolidated volume bidding, while premium passenger vehicle OEMs prioritize thermal propagation performance over unit cost.
Supply Chain Analysis
Inventory cycles stretching eighteen-to-thirty-six months for OEM validation create working capital intensity that favors backward-integrated petroleum majors with captive base oil production. Group III+ and polyalphaolefin base stocks draw from concentrated United States, South Korean, and Japanese refinery capacity. Formulation depends on specialized additive packages from German and Japanese chemical suppliers. Single-source vulnerability sits with limited North American producers of high-purity dielectric base fluids. Distribution runs through direct OEM supply contracts, regional fleet master service agreements, and converted quick-lube aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures as a regulatory entrenchment story. CARB and EPA certification requirements create switching costs that lock validated suppliers into long-term OEM thermal management programs.
For Market Incumbents: Consolidate validation relationships by embedding technical service teams at Tennessee, Georgia, and South Carolina battery gigafactories. Deepen backward integration into Group III+ base oil production to defend margin position against allocation volatility. Secure CARB pre-certification for next-generation biodegradable ester chemistries before compliance deadlines compress.
For New Entrants and Emerging Players: Differentiate on cold-climate thermal management expertise targeting Canadian provincial zero-emission bus mandates and Arctic logistics applications. Penetrate the second-life battery stationary storage segment where adapted coolant specifications remain undefined. Pursue technical partnership routes with emerging battery OEMs seeking alternative validation pathways outside incumbent supply relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure play because EPA tailpipe standards and CARB mandates embed sustained demand regardless of EV adoption speed differentials. Target specialized formulators with dielectric patent portfolios and active OEM validation programs. Monitor fleet electrification contract announcements from Amazon, UPS, and FedEx as volume inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive Group III+ supply insulates formulators from refiner allocation constraints and price volatility. |
| CARB Pre-Certification Investment | Early dielectric strength validation accelerates commercial deployment before Advanced Clean Trucks phase-in deadlines. |
| Fleet Master Service Agreement Expansion | Regional logistics-provider contracts bundle predictive maintenance analytics with volume supply commitments. |
| Quick-Lube Bay High-Voltage Conversion | Aftermarket network adaptation captures service revenue as electrified passenger vehicle parc scales. |
| Second-Life Battery Coolant Development | Stationary energy storage thermal management opens adjacent revenue outside original equipment supply chains. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors, OEM thermal management engineers, lubricant formulator R&D leads, and quick-lube network operations managers. Secondary validation drew from EPA emissions filings, CARB certification databases, NHTSA safety standards documentation, and SEC 10-K disclosures from integrated petroleum majors. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and end-user segments.
Across the analysis window, projections model battery electric vehicle production ramp rates, fast-charging infrastructure deployment curves, and fleet electrification procurement timelines. Segmentation dimensions include propulsion architecture, vehicle class, thermal management system configuration, and regional regulatory cluster. CAGRs derive from regression analysis of historical adoption patterns and elasticity estimates against policy mandate schedules. Industry-specific inputs incorporate battery energy density trajectories and OEM thermal propagation testing cycle durations.
Forecasts assume regulatory continuity in EPA tailpipe emissions frameworks and California Air Resources Board zero-emission vehicle mandates; material policy shifts would require re-modeling demand trajectories. Base oil supply disruptions, dielectric additive shortages, or accelerated NHTSA thermal propagation standards revision could compress commercialization timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
ASEAN Electric Vehicle Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
North America Electric Truck Market
Electric Vehicles
E-Rickshaw Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
Vietnam Electric Vehicle Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Electric Vehicle (EV) Fluids Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market