
 3D Laser Scanner Market | 2026-2036
3D Laser Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
3D Laser Scanner Market Intelligence
The market for 3D laser scanners is pivoting on the divergence between high-precision, metrology-grade systems and more accessible, lower-cost handheld units. Hexagon leverages its extensive metrology software and hardware portfolio to serve industrial clients. Creaform specializes in portable, user-friendly handheld scanners for reverse engineering and quality control. Meanwhile, Trimble dominates the geospatial and construction surveying applications with ruggedized terrestrial scanners.
A 3D laser scanner is an instrument that captures the precise shape of physical objects using a line of laser light. The technology, often based on time-of-flight or phase-shift principles, measures millions of data points to create a digital 'point cloud' representation. Handheld scanners represent the fastest-growing product category, driven by their flexibility in quality control and reverse engineering applications. Within end-user segments, engineering consultancies and manufacturing plants constitute the largest share of procurement, valuing accuracy and data reliability.
Product safety and electromagnetic compatibility are governed by standards like CE marking in Europe and FCC regulations in the United States. International standards, such as those from ISO, provide guidelines for data accuracy and calibration, influencing buyer confidence in metrology-grade equipment. Vendor differentiation will increasingly depend on the integration of scanner hardware with proprietary software ecosystems for data processing and analysis.
Market Dynamics
The fundamental dynamic shaping the 3D laser scanner market is the bifurcation between high-precision, high-cost metrology systems and accessible, lower-cost handheld units. This divergence is driven by an expanding application base with varied accuracy and budget requirements.
Growth Catalysts
- Automated Processing:Integration of artificial intelligence for automated point cloud registration and feature extraction is lowering the skill threshold for adoption, particularly among engineering consultancies and construction firms.
- Heritage Preservation:Demand from government agencies and cultural institutions for the digital documentation of historical sites and artifacts provides a stable, value-driven application segment, especially in countries like Italy and Greece.
- Metrology Standards:Adherence to international standards like ISO 10360 for acceptance and reverification of coordinate measuring systems builds buyer confidence in high-accuracy scanners for quality control in German and Japanese automotive manufacturing.
Market Restraints
- High Capital Cost:The significant initial investment required for survey-grade terrestrial laser scanners remains a primary barrier to adoption for small and medium-sized enterprises in the construction and civil engineering sectors.
- Data Processing Complexity:Large, unstructured point cloud datasets require specialized, often proprietary, software and powerful computing hardware for processing, which presents a workflow bottleneck and hidden cost for end-users.
- Photogrammetry Substitution:For applications not requiring metrological accuracy, such as basic visualization or real estate marketing, lower-cost photogrammetry techniques using standard cameras present a viable substitute, capping growth at the market's low end.
Strategic Opportunities
- Autonomous Systems Integration:Incorporating compact 3D laser scanners into the sensor fusion suites of autonomous vehicles, drones, and industrial robots for real-time navigation and obstacle avoidance represents a major new application frontier.
- Infrastructure Development:Large-scale infrastructure projects in fast-growing economies across Southeast Asia and the Middle East create significant demand for terrestrial scanners for surveying, progress monitoring, and as-built verification.
- Digital Twin Expansion:The convergence of 3D scanning with Building Information Modeling (BIM) software enables the creation of high-fidelity digital twins for facility management, predictive maintenance, and operational simulation in smart factories.
Industry Challenges
- Skilled Technician Scarcity:A persistent talent gap exists for professionals who possess the dual expertise of operating scanning hardware in the field and managing complex data processing workflows in the office.
- Interoperability Hurdles:The lack of a universal file format standard across hardware and software vendors creates data silos and complicates workflows for users who operate multi-brand environments, particularly in large enterprises.
- Legacy System Integration:Connecting the data output from 3D scanning systems with established enterprise resource planning (ERP) and computer-aided design (CAD) platforms in manufacturing environments often requires custom development and significant IT resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Laser Scanner Market |
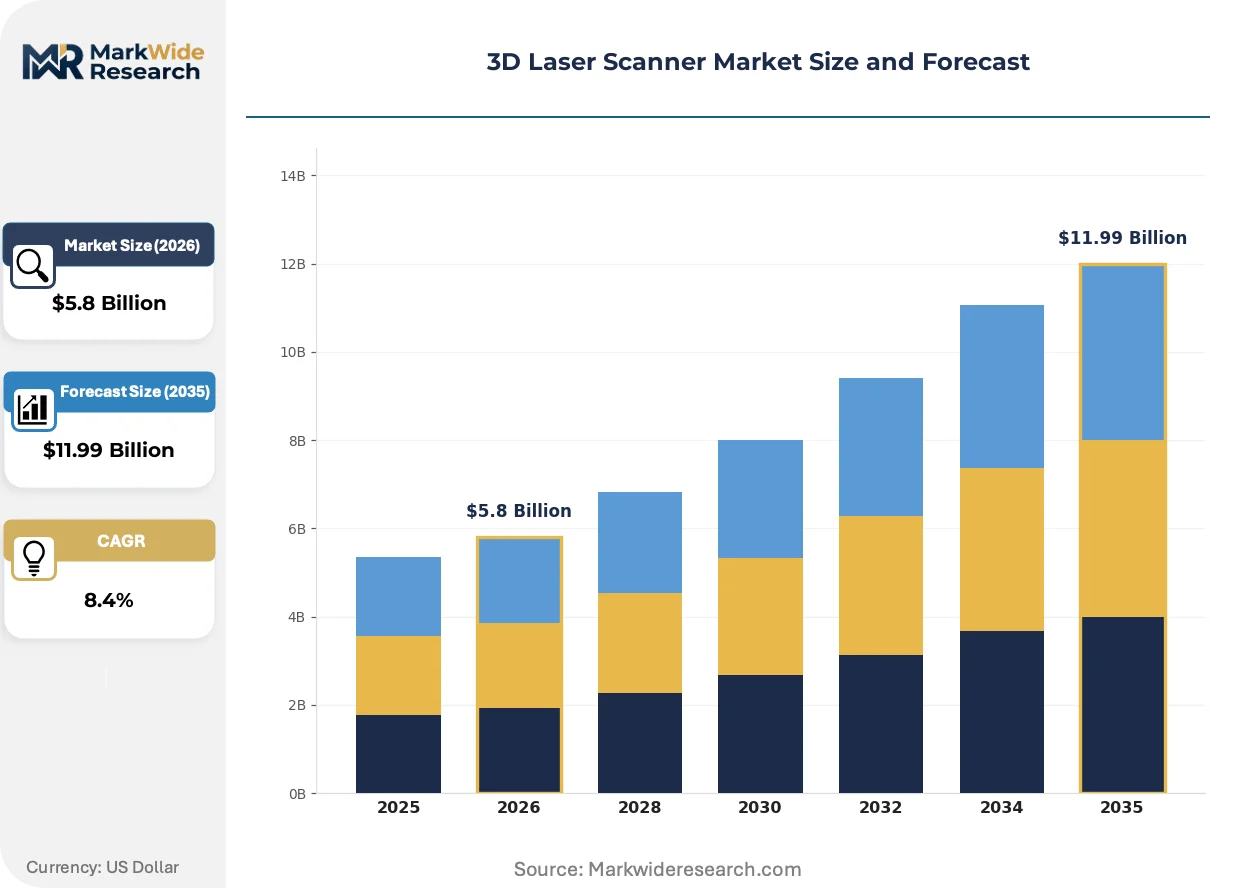
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terrestrial Scanner, Handheld Scanner, Overhead Scanner, Industrial Scanner, Mobile Scanner Technology: Time of Flight, Triangulation, Phase Shift, Structured Light, Photogrammetry Application: Construction Surveying, Heritage Documentation, Reverse Engineering, Quality Control, Virtual Reality End User: Engineering Consultancies, Manufacturing Plants, Research Institutes, Energy Sectors, Entertainment Studios |
| Companies Covered | Trimble Inc., Creaform, FARO Technologies, Inc, Riegl, Zoller + Fröhlich GmbH, Z+F USA, Inc, Nikon Metrology, Topcon, Hexagon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Laser Scanner Market Strategic Shifts & Innovations
The evolution of 3D laser scanners is defined by a push towards greater autonomy and data usability. Software ecosystems and on-device intelligence are becoming as critical as hardware specifications, making advanced scanning capabilities accessible to a wider user base beyond metrology specialists.
Edge computing integrated directly within scanner hardware is enabling on-site processing of point cloud data. This capability is being adopted in the construction and surveying sectors to provide immediate feedback and reduce data transfer volumes from the field to the office. This on-device processing is decentralizing data analysis away from a single, powerful workstation and toward a more distributed, real-time workflow.
European Union CE marking requirements for electromagnetic compatibility and electrical safety are becoming more rigorous for all electronic equipment. This is forcing manufacturers to invest more heavily in component shielding, emissions testing, and formal certification, particularly for portable and handheld scanners used in diverse industrial and public settings. Vendors targeting critical aerospace and medical device manufacturing applications face the most intense scrutiny.
A clear shift toward subscription-based software licensing and Hardware-as-a-Service (HaaS) models is underway. This business model lowers the initial barrier of high capital expenditure, allowing smaller architecture firms and project-based contractors to access state-of-the-art scanning technology. This trend is most pronounced in the North American and European architecture, engineering, and construction (AEC) sectors.
3D Laser Scanner Market Segmentation
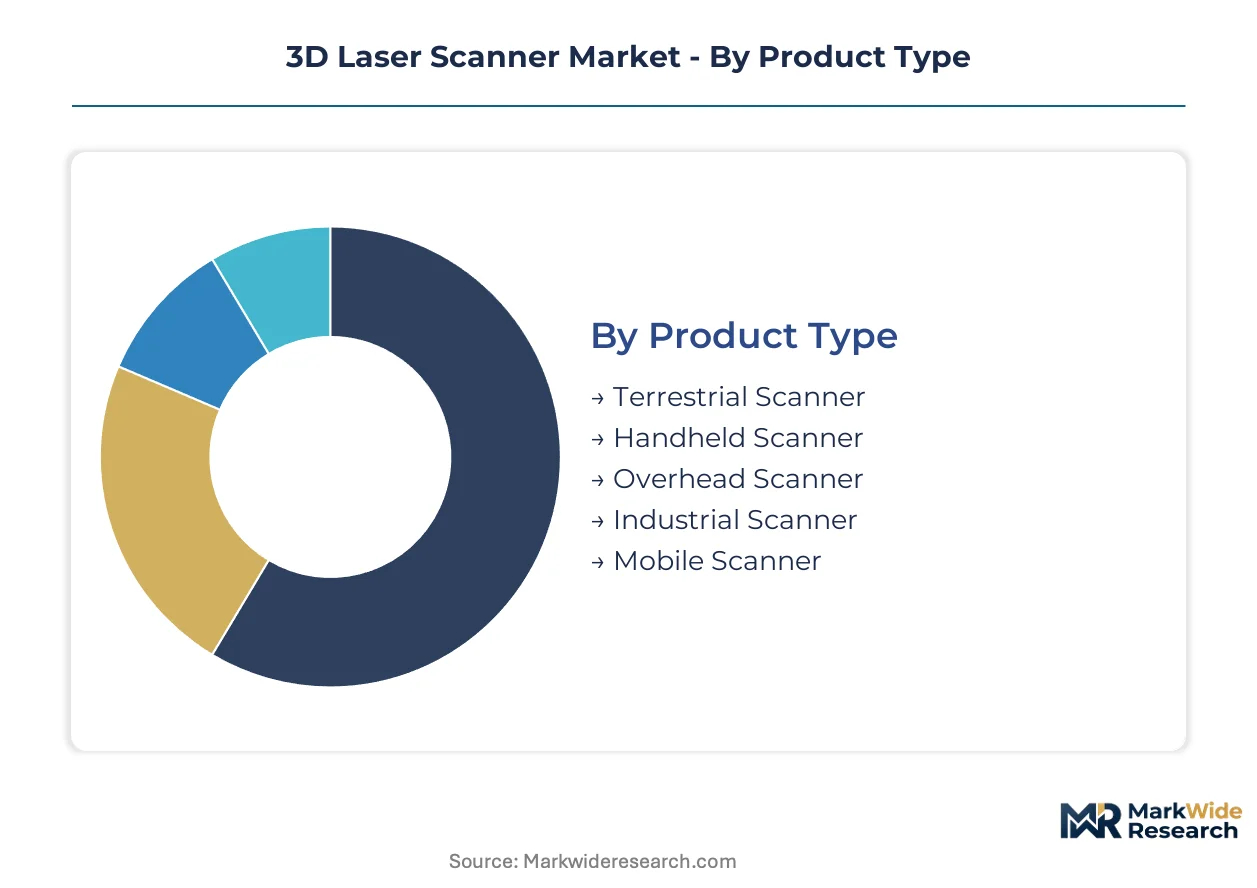
The 3D laser scanner market's segmentation reveals the diverse needs of its end-users, from high-precision industrial metrology to large-scale geospatial mapping. Understanding these distinct segments allows manufacturers to tailor product development and market strategies, addressing specific technical requirements and regulatory considerations.
Product Type:
Regulatory compliance, particularly CE marking in Europe and FCC regulations in the United States, significantly influences the design and market entry for various 3D laser scanner product types.
- Terrestrial Scanner:These stationary devices offer long-range capabilities and high accuracy, primarily deployed for large-scale outdoor surveying and construction site documentation where stability is paramount. Demand for these systems concentrates in infrastructure development projects across Southeast Asia.
- Handheld Scanner:Characterized by their portability and user-friendliness, handheld scanners excel in rapid data acquisition for reverse engineering and quality control in manufacturing environments. Their flexibility drives adoption in automotive clusters in Germany and Japan.
- Overhead Scanner:Mounted on gantries or robotic arms, these scanners provide automated, high-throughput inspection in fixed industrial settings.
- Industrial Scanner:Designed for harsh factory environments, industrial scanners perform continuous monitoring and quality assurance tasks on production lines.
- Mobile Scanner:Integrated into vehicles or drones, mobile scanners capture vast datasets rapidly for urban mapping and asset management.
Leading the category by volume: Terrestrial Scanner. Growing fastest: Handheld Scanner.
Technology:
The choice of 3D laser scanning technology directly dictates the achievable precision and operational range across different application requirements.
- Time of Flight:This technology measures the time a laser pulse takes to travel to an object and return, making it suitable for long-range scanning in large outdoor environments and construction surveying. Its application is critical for large-scale infrastructure projects.
- Phase Shift:Utilizing continuous wave lasers, phase shift scanners offer high accuracy and speed over shorter ranges, making them ideal for detailed industrial inspection and quality control applications. Demand is strong in precision manufacturing.
- Triangulation:This method uses a camera to detect the deformation of a laser line projected onto an object, providing high resolution for small to medium-sized objects.
- Structured Light:Projecting known light patterns, structured light scanners create dense point clouds for intricate geometries, often used in reverse engineering.
- Photogrammetry:While not strictly a laser technology, photogrammetry reconstructs 3D models from multiple 2D images, offering a lower-cost alternative for visualization.
Time of Flight technology captures substantial market share due to its long-range capabilities, while Structured Light methods are gaining traction for detailed, short-range inspections.
Application:
End-user procurement decisions for 3D laser scanner applications are heavily influenced by the specific industry's accuracy demands and workflow integration needs.
- Quality Control:This application involves verifying product dimensions against design specifications, crucial for ensuring compliance in automotive and aerospace manufacturing. German and Japanese automotive clusters drive significant demand.
- Construction Surveying:Scanners provide precise measurements for site mapping, progress monitoring, and as-built documentation on large infrastructure projects, particularly in fast-growing economies. This application supports urban development.
- Heritage Documentation:Digital preservation of historical sites and artifacts benefits from 3D scanning, creating detailed digital twins for research and conservation.
- Reverse Engineering:Creating CAD models from physical objects for design modification or reproduction is a core use case in product development.
- Virtual Reality:3D scans contribute to realistic virtual environments for training, simulation, and entertainment content creation.
Quality control applications drive significant demand in manufacturing, while infrastructure development projects increasingly rely on construction surveying.
End User:
The maturity of digital adoption within different end-user segments determines the rate and scale of 3D laser scanner integration into existing operational workflows.
- Engineering Consultancies:These firms leverage 3D scanners for diverse projects, including architectural design, civil engineering, and plant layout, valuing data accuracy and reliability for client deliverables. They often serve as early adopters of advanced scanning solutions.
- Manufacturing Plants:Implementing 3D scanners for quality assurance, tool inspection, and production line optimization, manufacturing plants require robust, high-precision systems. Automotive and aerospace industries represent major procurement hubs.
- Research Institutes:Academic and scientific institutions utilize scanners for metrology research, archaeological studies, and advanced material analysis.
- Energy Sectors:Oil and gas, and power generation industries deploy scanners for asset management, facility maintenance, and safety inspections of complex infrastructure.
- Entertainment Studios:Film, gaming, and special effects studios use 3D scans for creating realistic digital assets and environments.
Manufacturing plants represent a major procurement hub for metrology-grade systems, with engineering consultancies expanding their scanner fleets for diverse project requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive manufacturing cluster around Stuttgart, Germany, drives significant demand for 3D laser scanners for precision quality control. This region leverages metrology-grade systems to ensure product compliance and accelerate development cycles.
Germany
German automotive manufacturers demand high-precision 3D laser scanners for quality control and production line optimization. Adherence to ISO 10360 standards builds buyer confidence in metrology-grade equipment for critical applications. The automotive clusters in Bavaria and Baden-Württemberg continually integrate advanced scanning solutions.
Japan
Japanese automotive and electronics manufacturers require 3D laser scanners for stringent quality assurance and rapid prototyping. METI initiatives support advanced manufacturing technologies, including precision metrology equipment. The industrial zones around Nagoya and Tokyo concentrate procurement for advanced inspection systems.
United States
US construction firms and engineering consultancies adopt terrestrial scanners for large-scale infrastructure projects and building information modeling. FCC regulations govern the electromagnetic compatibility of electronic devices, influencing scanner design and deployment. Major urban development hubs in California and Texas utilize mobile scanning for rapid data acquisition.
Italy
Italian cultural institutions and government agencies extensively use 3D laser scanners for heritage documentation and digital preservation of historical sites. National policies support the digital archiving of cultural assets, driving demand for high-resolution scanning. Cities like Rome and Florence host numerous projects for artifact digitization and architectural restoration.
Singapore
Singapore's rapid urban development and smart city initiatives generate demand for mobile and terrestrial scanners for infrastructure monitoring. The Building and Construction Authority (BCA) promotes digital construction methods, including 3D scanning for project verification. Major government-led projects, such as those by the URA, integrate scanning for comprehensive asset management.
3D Laser Scanner Market Key Industry Players
Premium-margin players sit above commodity-margin players across the 3D laser scanner market, reflecting different technological capabilities and target applications. The market exhibits a tiered structure, with established incumbents focusing on high-precision metrology systems and agile specialists innovating in portable, user-friendly devices. Strategic archetypes include integrated solution providers, niche hardware developers, and software-centric platforms. Geographic expansion and portfolio diversification represent dominant competitive moves among these diverse entities.
Specialists in integrated solutions and portable devices define distinct market segments. Hexagon, for instance, exemplifies a comprehensive provider, leveraging an extensive metrology software and hardware portfolio to serve industrial clients globally. Creaform represents a company focused on portable, user-friendly handheld scanners, occupying a position in rapid reverse engineering and quality control applications. Trimble Inc. anchors the geospatial and construction surveying segment, providing ruggedized terrestrial scanners essential for large-scale infrastructure projects and precise site documentation.
| Leading Market Players |
|---|
| Trimble Inc. |
| Creaform |
| FARO Technologies, Inc |
| Riegl |
| Zoller + Fröhlich GmbH |
| Z+F USA, Inc |
| Nikon Metrology |
| Topcon |
| Hexagon |
| Others |
Cost & Logistics Intelligence
Captive component manufacturing by established metrology hardware firms anchors their supply position, enabling premium pricing strategies for high-precision 3D laser scanners. This integration ensures control over critical optical and sensor elements, influencing market entry points and cost structures.
Pricing Analysis
Outcome-based pricing anchors high-end metrology systems, reflecting the accuracy and reliability delivered for critical manufacturing processes. The dominant pricing structure for advanced 3D laser scanners involves tiered licensing for proprietary software ecosystems and per-unit transactional sales for hardware. Price differentiation stems from certification levels, such as ISO 10360 compliance, and the depth of after-sales support. Pricing pressure stems from the increasing viability of lower-cost photogrammetry solutions, particularly for visualization applications. Small and medium-sized enterprises exhibit the highest price sensitivity, unlike automotive and aerospace manufacturers who prioritize precision.
Supply Chain Analysis
Logistics costs for precision optical components and sensor arrays influence the final assembly location for 3D laser scanners. Supply concentration for advanced optical systems resides in Germany, Japan, and parts of East Asia. Key dependencies include high-performance laser diodes, sophisticated sensor modules, and specialized processing units. Single-source vulnerability for certain proprietary components represents a structural supply chain risk. Distribution typically runs through direct sales channels for large industrial clients and specialized value-added resellers for engineering consultancies and smaller firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D laser scanner market navigates a technology-transition phase, with advanced digital capture methods displacing traditional manual measurement techniques. This shift enables new applications and operational efficiencies across industries.
For Market Incumbents: Acquire specialized software firms to deepen proprietary data processing capabilities and enhance user experience. Incumbents must consolidate their software ecosystems to counter the threat from agile, software-centric startups offering simpler workflows. Investing in advanced AI integration for automated point cloud processing represents a critical R&D lever, securing long-term client retention in industrial sectors.
For New Entrants and Emerging Players: Specialized engineering consultancies represent a key channel partner type for new entrants seeking market penetration. Target the architecture, engineering, and construction (AEC) sector with accessible, lower-cost handheld units, particularly for smaller project-based contractors. A subscription-based Hardware-as-a-Service (HaaS) go-to-market angle lowers initial capital expenditure barriers, fostering broader adoption.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by larger industrial technology conglomerates seeking to expand their digital twin and autonomous systems portfolios. Long-term viability rests on the convergence of 3D scanning with Building Information Modeling (BIM) and real-time sensor fusion. A signal to watch for inflection is the widespread adoption of compact scanners in industrial robotics for predictive maintenance applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI for Automated Point Cloud Processing | This initiative lowers the skill threshold for adoption, broadening the user base among engineering consultancies. |
| Expand Subscription-Based Software Licensing | This model reduces initial capital expenditure, making advanced scanning technology accessible to smaller AEC firms. |
| Develop Compact Scanners for Autonomous Systems | Incorporating 3D scanners into drones and robots enables real-time navigation and obstacle avoidance for industrial applications. |
| Strengthen Proprietary Software Ecosystems | Vendor differentiation increasingly depends on seamless integration of scanner hardware with advanced data analysis platforms. |
| Target Infrastructure Development Projects | Large-scale projects in Southeast Asia demand terrestrial scanners for surveying and as-built verification. |
Research Approach
Multi-period observation of technology adoption rates and regulatory compliance trends anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with manufacturing plant managers, engineering consultancy principals, and cultural heritage site managers. Secondary data sources included ISO standards documentation, FCC regulations, CE marking guidelines, and industry association reports on metrology. This approach facilitated bottom-up market sizing and top-down validation of market dynamics.
An input-output matrix framing guided the quantitative market forecast across the analysis window. Segmentation dimensions modeled included product type, underlying technology, application, and end-user vertical, alongside geographic region. Compound annual growth rates were derived through a regression analysis of historical market performance and projected adoption curves. Key industry-specific forecast inputs included global infrastructure spending and automotive production volumes.
Several conditions sit outside the modeled scope, including rapid, unforeseen technological breakthroughs or significant geopolitical trade disruptions. Forecasts reflect assumptions concerning stable regulatory environments and sustained capital expenditure in key end-user industries. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Air Velocity Meter Market
Measuring Instruments
Global Reference Thermometer Market
Measuring Instruments
Monitoring Tools Market
Measuring Instruments
Temperature Calibrator Market
Measuring Instruments
Global Instrument Calibrator Market
Measuring Instruments
Global Laser Measuring Instrument Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
Americas 3D Metrology Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Data Acquisition Market
Measuring Instruments
Communication Test Equipment (CTE) Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
Network Diagnostic Tools Market
Measuring Instruments
Data Loggers Market
Measuring Instruments
Digital Refrigeration Gauge Market
Measuring Instruments
Ultraviolet Data Logger Market