
 Product Optimization Software Market | 2026-2036
Product Optimization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Product Optimization Software Market Analytics
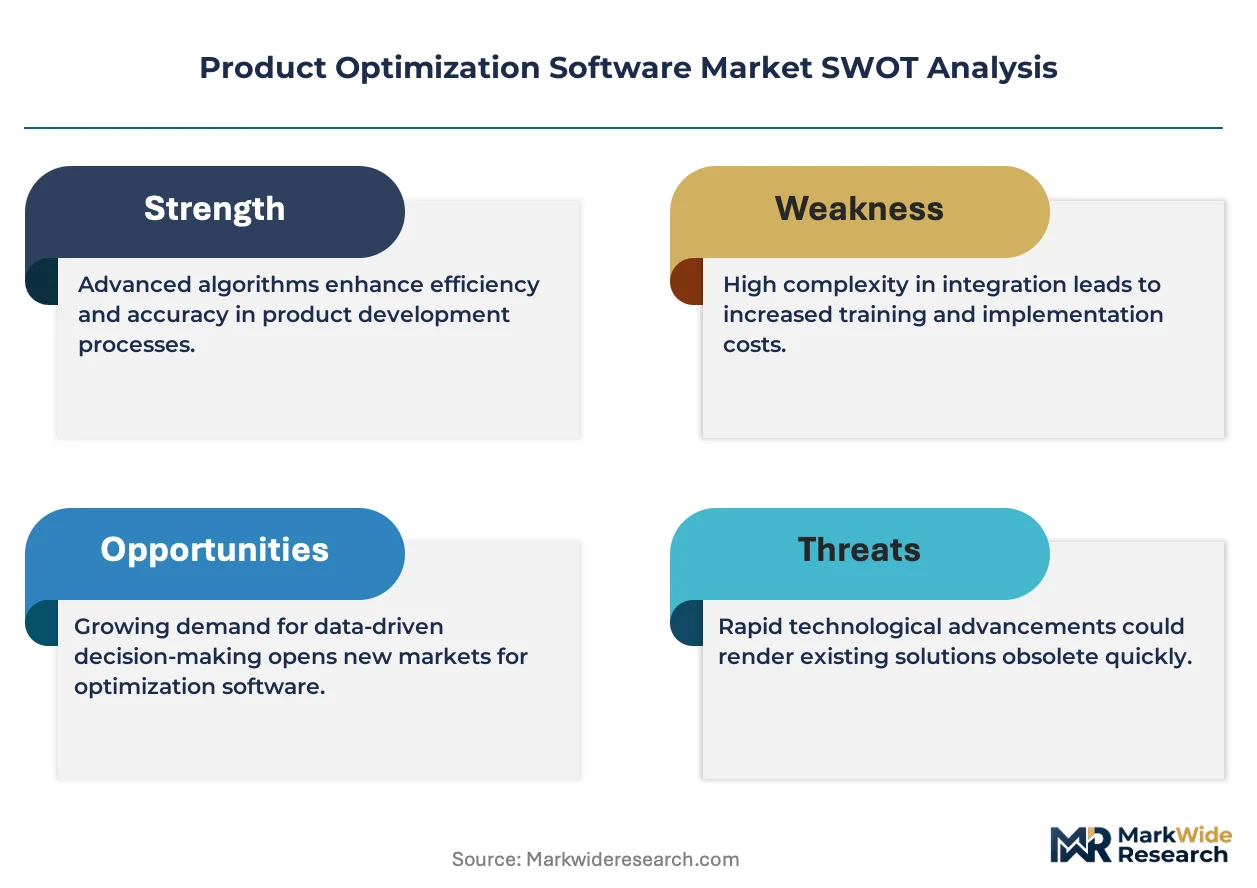
Subscription-based financing and asset-light SaaS procurement is reconfiguring competitive entry barriers for mid-sized manufacturers seeking enterprise-grade optimization capabilities without capital-intensive licensing. Schneider Electric leverages its energy management software heritage to anchor industrial optimization suites for process manufacturing clients. SAP SE sustains competitive positioning through deep ERP integration that controls data flow across procurement, production, and distribution modules. Dassault Systèmes differentiates via 3D simulation-driven product optimization that extends digital twin capabilities into live manufacturing environments.
Product optimization software encompasses algorithmic platforms that apply mathematical modeling, machine learning, and constraint-based analysis to refine product design parameters, material selection, production sequences, and performance outcomes against defined cost, quality, and time objectives. These systems typically process real-time sensor feeds, historical batch records, and simulation outputs to generate actionable recommendations for engineers and operations managers. Cloud-based deployment now leads among delivery models as manufacturers prioritize elastic compute access and reduced infrastructure overhead, while on-premises installations retain stronghold status in pharmaceutical verticals where FDA 21 CFR Part 11 validation requirements govern electronic records. Quality assurance applications represent the fastest-expanding segment as regulatory scrutiny intensifies across medical device and food processing supply chains.
FDA validation protocols for electronic quality systems shape software architecture requirements for pharmaceutical and medical device end users, compelling vendors to embed audit trails and electronic signature capabilities. EMA's Medical Device Regulation and EU AI Act converge to demand algorithmic transparency in optimization engines deployed across European healthcare manufacturing. BIS certification requirements in India and GB standards enforcement through SAMR in China add compliance layers for vendors seeking multi-jurisdictional market access. Stakeholders must monitor evolving cross-border data localization mandates and determine whether federated deployment architectures or region-specific instances better balance compliance cost against operational coherence.
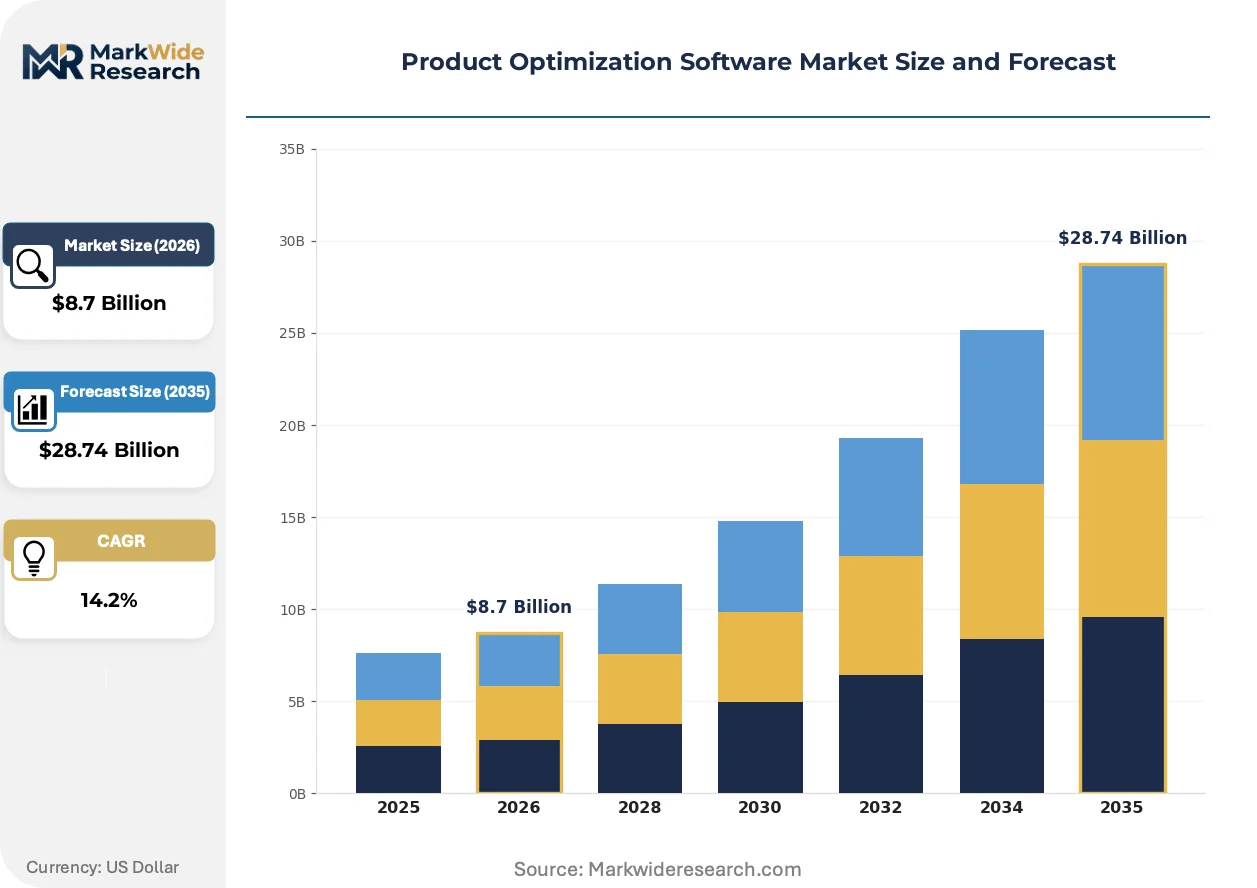
Market Dynamics
Cloud migration mandates and data sovereignty requirements are compelling vendors to rearchitect deployment architectures while pharmaceutical manufacturers accelerate platform adoption to compress quality assurance timelines. This structural tension between elastic compute access and jurisdictional compliance is reshaping vendor roadmaps and customer procurement criteria simultaneously.
Growth Catalysts
- EMA Medical Device Regulation:Algorithmic transparency requirements for optimization engines deployed across European healthcare manufacturing are expanding addressable market for compliant software suites.
- Automotive supply chains:Industrial software clusters in Munich and Stuttgart anchor adoption across precision engineering tiers seeking formulation cycle acceleration.
- Constraint-based analysis:Machine learning platforms processing real-time sensor feeds are displacing manual parameter refinement in batch manufacturing environments.
Market Restraints
- FDA 21 CFR Part 11 validation:Electronic records requirements in pharmaceutical verticals preserve on-premises installation preferences, constraining cloud revenue conversion.
- Input cost volatility:Elastic compute pricing fluctuations compress margins for SaaS vendors serving mid-sized manufacturers on fixed subscription terms.
- Technical limitation:Federated deployment architectures struggle to maintain operational coherence across region-specific instances with divergent update cycles.
Strategic Opportunities
- EU AI Act convergence:Algorithmic transparency mandates create regulatory tailwind for vendors embedding explainable optimization engines ahead of enforcement timelines.
- Food processing supply chains:Quality assurance applications represent underpenetrated vertical where regulatory scrutiny is intensifying beyond pharmaceutical incumbents.
- Digital twin convergence:3D simulation platforms merging with live manufacturing sensor networks are opening new deployment categories for process optimization.
Industry Challenges
- Skill scarcity in constraint-based modeling:Operations managers lack training to interpret machine learning recommendations against historical batch records.
- Legacy ERP integration complexity:Data flow synchronization across procurement, production, and distribution modules requires extensive customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Product Optimization Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-Based, On-Premises, Cloud-Based, Hybrid Application: Supply Chain Management, Quality Assurance, Data Analytics, Product Development Industry Vertical: Manufacturing, Retail, Consumer Electronics, Pharmaceuticals End User: SMEs, Large Enterprises, Startups, Consultants |
| Companies Covered | ABB, Schneider Electric, Infosys Limited, Weatherford, Baker Hughes, Plataine Ltd, Ambyint, Dassault Systèmes, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Product Optimization Software Market Evolving Landscape
Algorithmic platforms are actively merging mathematical modeling with live sensor infrastructure, compressing the gap between simulation and production environments. This convergence is redefining how manufacturers balance design parameter refinement against real-time operational constraints.
Digital twin technology is hybridizing static 3D simulation with continuous manufacturing data streams. Automotive and precision engineering clients in German industrial clusters are deploying these integrated platforms at accelerating pace. The technology is hybridizing product development cycles with quality assurance workflows, collapsing sequential handoffs between engineering and operations teams.
REACH chemical compliance and EU AI Act algorithmic governance are converging to demand auditable optimization logic. Industrial software vendors must now embed traceable decision pathways within machine learning engines. Medical device manufacturers face the steepest compliance burden, responding by procuring platforms with pre-validated electronic signature architectures.
Subscription financing is displacing perpetual licensing across mid-sized manufacturing procurement. Asset-light SaaS procurement is gaining share among precision engineering supply chains seeking enterprise capabilities without capital-intensive upfront commitments. Germany's automotive tier suppliers demonstrate this shift most visibly, consolidating vendor relationships around usage-based pricing models.
Product Optimization Software Market Segmentation
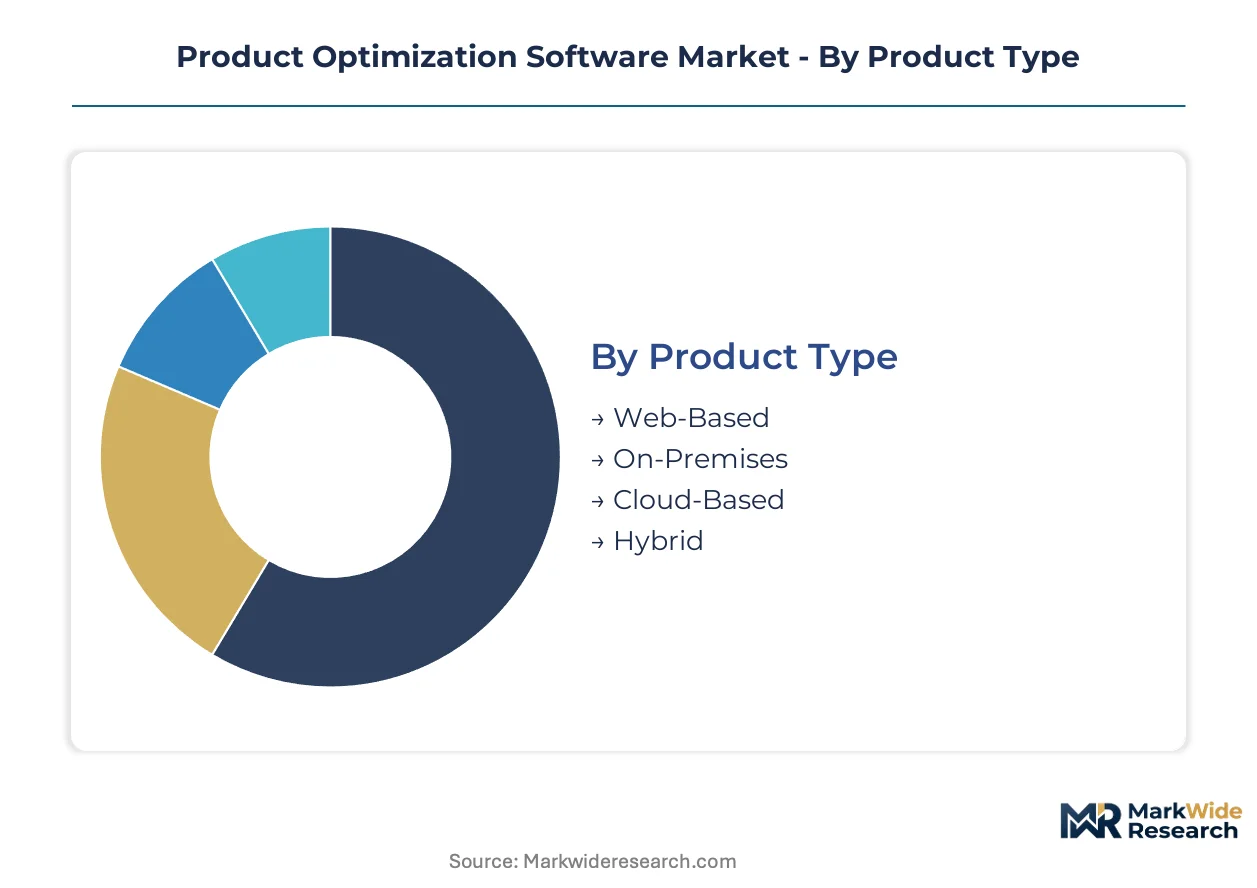
Product optimization software vendors architect modular platforms around distinct deployment models, functional applications, and customer scale tiers. Segmentation clarity enables buyers to match validation requirements, integration complexity, and pricing structures against operational constraints.
Product Type:
Mature on-premises installations coexist with emerging cloud-native architectures as manufacturers balance compliance legacy against elastic compute needs.
- Cloud-Based:Elastic infrastructure scales compute resources for real-time sensor processing and machine learning model training. Pharmaceutical manufacturers in Germany and automotive precision engineering clusters in Stuttgart prioritize cloud deployments for formulation cycle acceleration despite EMA data sovereignty requirements.
- On-Premises:Validated installations host electronic records systems subject to FDA 21 CFR Part 11 audit trail mandates. Medical device manufacturers retain strong preference for captive infrastructure where algorithmic transparency documentation must satisfy pre-market submission requirements.
- Web-Based:Browser-accessible platforms reduce client-side maintenance overhead for mid-sized manufacturers with limited IT staffing.
- Hybrid:Federated architectures partition sensitive quality data on-premises while pushing compute-intensive optimization workloads to cloud instances.
Cloud-Based handles the majority of new procurement volume; Hybrid is expanding most quickly as compliance-conscious manufacturers seek architectural flexibility.
Application:
Functional modules align with discrete operational pain points across manufacturing value chains, from procurement coordination through post-market surveillance.
- Quality Assurance:Algorithmic platforms automate batch record review, deviation detection, and corrective action tracking against regulatory submission standards. Medical device and food processing supply chains in Germany and France drive procurement as EMA MDR and EU AI Act transparency requirements intensify.
- Supply Chain Management:Constraint-based optimization synchronizes procurement, inventory positioning, and distribution sequencing across multi-tier supplier networks.
- Data Analytics:Descriptive and predictive modules process historical production records to identify parameter correlations affecting yield and defect rates.
- Product Development:Digital twin integration merges 3D simulation with live manufacturing feedback to compress design iteration cycles.
Quality Assurance commands the largest addressable market expansion; Data Analytics is gaining share fastest among precision engineering adopters seeking predictive maintenance capabilities.
Industry Vertical:
Vertical specialization determines regulatory validation depth, integration architecture, and pricing tolerance across buyer organizations.
- Pharmaceuticals:FDA and EMA submission pathways mandate pre-validated software configurations with embedded electronic signatures and immutable audit trails. German pharmaceutical manufacturers anchor European demand as they consolidate vendor relationships around compliant optimization suites.
- Manufacturing:Process industries deploy sensor-integrated platforms for real-time parameter refinement in batch and continuous production environments.
- Consumer Electronics:Rapid product lifecycle turnover drives demand for accelerated formulation and material selection optimization.
- Retail:Private-label manufacturers leverage platforms to coordinate supplier quality standards across geographically dispersed production networks.
Pharmaceuticals absorbs the highest per-seat pricing; Manufacturing represents the broadest installed base across deployment models.
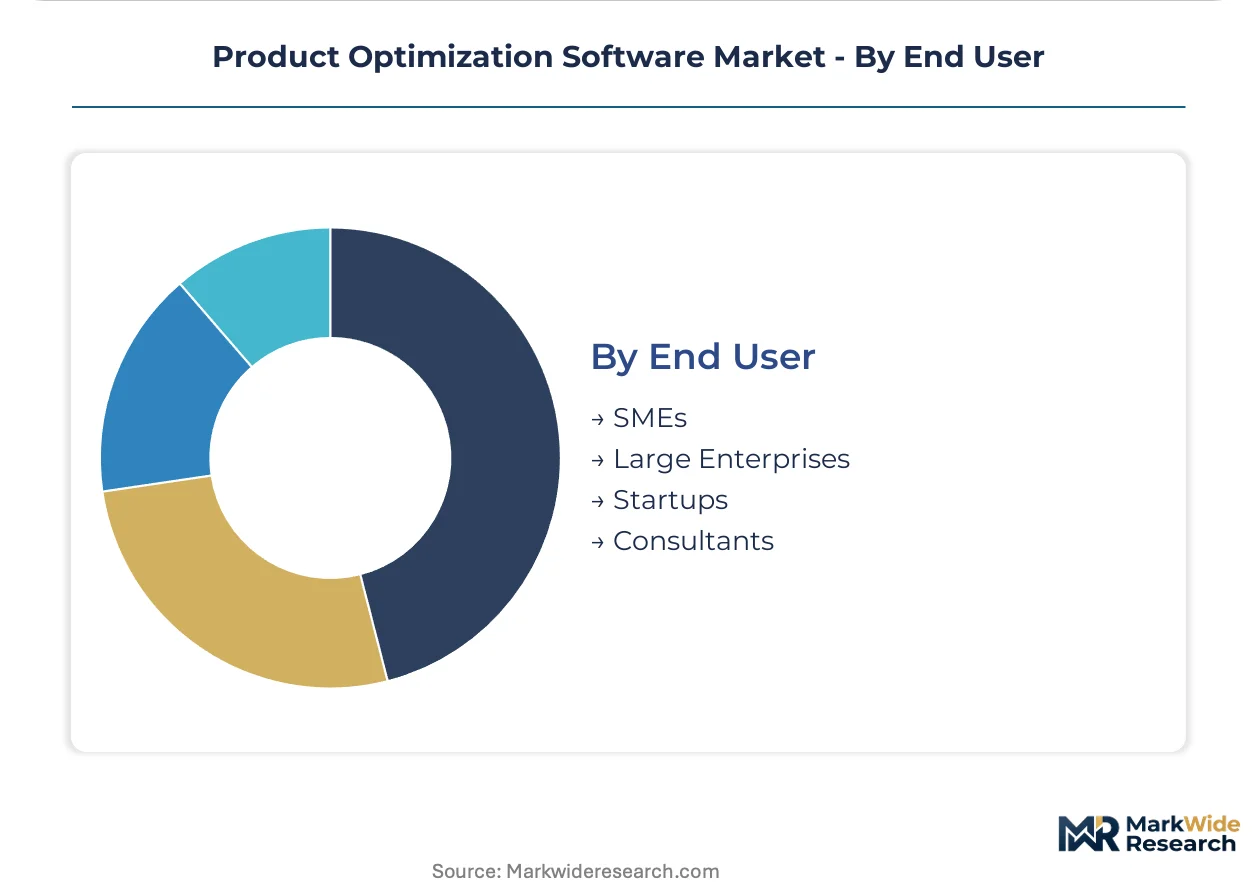
End User:
Customer scale tiers segment procurement authority, implementation complexity tolerance, and financing preference across the buyer universe.
- Large Enterprises:Multi-site deployments integrate optimization platforms with existing ERP infrastructure from SAP and similar vendors. German automotive OEMs and tier-one suppliers anchor this segment with centralized procurement of enterprise-wide licenses.
- SMEs:Subscription financing and asset-light SaaS procurement models reduce capital barriers for mid-sized manufacturers seeking algorithmic capabilities without perpetual license commitments.
- Consultants:Implementation partners and system integrators procure platform access to deliver optimization services across client portfolios.
- Startups:Venture-backed manufacturing technology firms pilot cloud-native optimization tools for rapid scale-up without infrastructure investment.
Large Enterprises dominate current revenue concentration; SMEs are climbing the fastest on subscription conversion rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large enterprises with centralized procurement authority dominate platform adoption, while mid-sized manufacturers accelerate subscription conversions. German automotive clusters and US pharmaceutical hubs anchor initial deployment waves. Regulatory validation requirements fragment vendor architectures across jurisdictional boundaries.
Germany
Automotive OEMs and tier-one precision engineering suppliers drive enterprise-wide license procurement for formulation cycle acceleration. EMA Medical Device Regulation algorithmic transparency requirements expand addressable market for compliant optimization suites. Munich and Stuttgart industrial software clusters anchor adoption across multi-tier supplier networks seeking digital twin integration.
United States
Pharmaceutical manufacturers deploy platforms to compress FDA 21 CFR Part 11 validation timelines for electronic quality systems. FDA pre-market submission pathways mandate pre-validated software configurations with embedded audit trails and electronic signatures. Boston and San Francisco biotech corridors concentrate demand for cloud-native architectures with elastic compute access.
China
Process manufacturers in chemical and materials verticals prioritize sensor-integrated platforms for real-time parameter refinement. SAMR GB standards enforcement and dual carbon goals add compliance layers for algorithmic transparency in manufacturing optimization. Yangtze River Delta industrial zones concentrate deployment of constraint-based analysis platforms for batch manufacturing environments.
India
Mid-sized precision engineering suppliers adopt asset-light SaaS procurement models to access enterprise-grade capabilities without capital-intensive licensing. BIS certification requirements for multi-jurisdictional market access compel vendors to embed traceable decision pathways. Bangalore and Pune software corridors anchor subscription conversion rates among automotive component manufacturers.
United Kingdom
Medical device manufacturers procure platforms with pre-validated electronic signature architectures to satisfy MHRA post-Brexit regulatory alignment. EU AI Act convergence demands explainable optimization engines ahead of enforcement timelines. London and Cambridge medtech clusters drive quality assurance application expansion beyond pharmaceutical incumbents.
Product Optimization Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment architecture, integration depth, and compliance validation tiers. The vendor base organizes around three strategic archetypes: ERP-integrated suite providers, simulation-native platform vendors, and energy-management heritage players extending into process optimization. Dominant competitive moves include M&A for regulatory validation capabilities and strategic partnerships for federated deployment architectures.
Within the ERP-integrated tier, SAP SE exemplifies channel control through data flow synchronization across procurement and production modules. Dassault Systèmes occupies a position among simulation-native specialists merging 3D modeling with live manufacturing sensor networks. Schneider Electric represents energy-management heritage players extending optimization capabilities into process manufacturing verticals.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Infosys Limited |
| Weatherford |
| Baker Hughes |
| Plataine Ltd |
| Ambyint |
| Dassault Systèmes |
| SAP SE |
| Others |
Value Network & Pricing Analysis
Elastic compute infrastructure concentration among hyperscalers in the United States and Western Europe anchors SaaS vendor cost structures, compressing margin pools for mid-tier optimization platforms serving fixed-subscription buyers in Germany and India.
Pricing Analysis
Certification level creates the primary spread between FDA 21 CFR Part 11-validated deployments and standard cloud-native tiers. Three-tier pricing structure across premium, standard, and economy levels segments pharmaceutical manufacturers from precision engineering SMEs. Cost compression in the mid-tier is intensifying because hyperscaler compute pricing volatility erodes fixed-subscription margins. Automotive tier suppliers in Stuttgart demonstrate highest price sensitivity, while German pharmaceutical OEMs absorb premium validation costs without procurement friction.
Supply Chain Analysis
Export-control restrictions on GPU clusters and advanced optimization algorithms limit technology flows from United States and European Union vendors into Chinese process manufacturing markets. Software supply draws from cloud infrastructure providers in the United States, Ireland, and Singapore, with algorithmic IP development concentrated in Germany and India. Single-source vulnerability sits with hyperscaler compute provisioning for real-time sensor processing. Distribution runs through direct enterprise sales teams and systems integrators serving automotive and pharmaceutical verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in product optimization software hinge on ERP ecosystem interoperability, where SAP and Dassault Systèmes anchor data flow integration that determines vendor switching costs and customer lifetime value.
For Market Incumbents: Insulate validated installation revenue streams by embedding electronic signature architectures ahead of EMA MDR enforcement timelines. Deepen backward integration into cloud infrastructure provisioning to offset hyperscaler pricing volatility eroding SaaS margins. Prioritize certification maintenance as emerging cloud-native entrants lack FDA submission pathway experience.
For New Entrants and Emerging Players: India's mid-sized precision engineering suppliers present the most penetrable white-space for asset-light SaaS procurement without legacy ERP integration burdens. Food processing quality assurance applications in France and the United Kingdom offer underpenetrated vertical expansion beyond pharmaceutical incumbents. Lead with browser-accessible deployment models that reduce client-side IT staffing requirements for SME buyers.
For Investors and Strategic Acquirers: Capital is best deployed toward simulation-native platform vendors merging 3D modeling with live sensor networks, as digital twin convergence accelerates across German automotive clusters. Long-term viability rests on regulatory validation depth rather than raw algorithmic performance. Monitor EMA algorithmic transparency enforcement timelines as inflection indicator for compliant suite demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP synchronization with SAP procurement modules anchors enterprise switching costs. |
| Regulatory Validation Pathway | FDA 21 CFR Part 11 pre-validation accelerates pharmaceutical manufacturer procurement cycles. |
| Acquisition of Specialist Firm | Digital twin capabilities from 3D simulation vendors compress design-to-production handoffs. |
| Strategic Partnership | Hyperscaler alliances secure elastic compute access for real-time optimization workloads. |
| Geographic Expansion | India's BIS certification requirements demand localized algorithmic transparency documentation. |
Research Methodology
Desk research of vendor financial disclosures, regulatory filing databases, and hyperscaler infrastructure expansion records preceded structured interviews with pharmaceutical quality assurance directors, automotive platform engineers, and cloud procurement officers. Primary fieldwork with SAP integration specialists and Dassault Systèmes deployment teams cross-validated secondary estimates of enterprise license concentration. Bottom-up segmentation modeling triangulated against top-down market sizing from disclosed customer counts and average contract values.
Assumptions held fixed include EMA MDR and EU AI Act enforcement timelines, FDA validation protocol stability, and hyperscaler regional availability zone expansion plans across the analysis window. Modeled segmentation spans deployment architecture, organization scale tier, vertical regulatory cluster, and geographic adoption pattern. CAGRs derived from logistic diffusion curves fitted to historical SaaS conversion rates in manufacturing software categories, with inputs from automotive production volume forecasts and pharmaceutical batch record digitization indices.
Practitioners should monitor export-control expansion on optimization algorithms and hyperscaler pricing regime shifts for early signals of vendor margin compression. Forecasts reflect assumptions of stable regulatory validation burden and continued cloud infrastructure cost pass-through elasticity. Material shifts in FDA electronic records enforcement or EU data sovereignty mandate expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Voip Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Paraphrasing Tools Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Engineering Software Market
Software & Services
Classified Platform Market
Software & Services
Know Your Customer Software Market
Software & Services
Android Emulator Market
Software & Services
Global AR Game Engine Software Market
Software & Services
Global Manufacturing Operations Management (MOM) Software Market
Software & Services
Europe Integration Platform As a Service Market
Software & Services
Indonesia IT Services Market
Software & Services
Account-Based Advertising Software Market
Software & Services
User Interface Software Market
Software & Services
Global Data Governance Software Market