
 Laser Distance Meter Market | 2026-2036
Laser Distance Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Distance Meter Market Outlook
Commercial contractors is redrawing procurement priorities across the laser distance meter industry as build-to-rent residential towers and data center campuses multiply. Bosch leverages in-house sensor production to control cost structures across European distribution channels. Hilti anchors its position through direct-to-contractor service models that bundle calibration and fleet management. Leica Geosystems differentiates by dominating geodetic-grade phase shift architectures for surveying workflows.
A laser distance meter is an electro-optical instrument that emits a modulated laser beam and calculates distance through time-of-flight or phase comparison methods, typically achieving accuracy within one millimeter per meter measured. These devices serve construction layout verification, as-built documentation, and spatial planning where tape measures introduce cumulative error. Handheld meters occupy the largest volume tier, though multi-functional tools that integrate inclinometers and Bluetooth data logging capture expanding margin pools among professional users. Phase shift technology leads in surveying applications demanding sub-centimeter precision, while time-of-flight architectures sustain cost competitiveness across contractor-grade handheld units.
FCC equipment authorization governs laser emission levels and electromagnetic compatibility for devices sold in the United States, while CE marking under EU directives mandates conformity with RoHS substance restrictions and electromagnetic compatibility standards for European market access. OSHA construction safety guidelines indirectly shape demand by encouraging documented measurement protocols that reduce rework exposure. Stakeholders must monitor how evolving ISO 16331-1 standards for outdoor laser performance testing reshape product differentiation claims and procurement specifications.
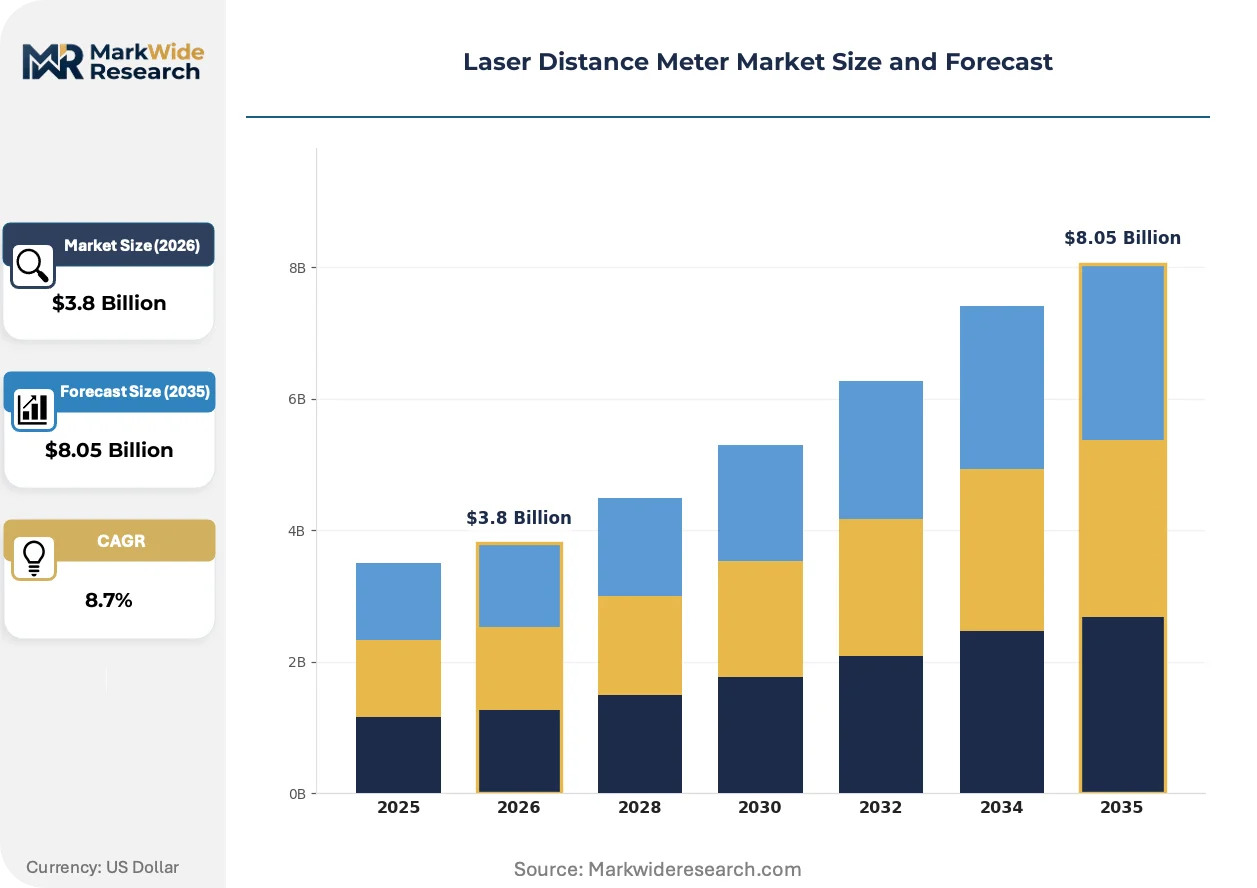
Market Dynamics
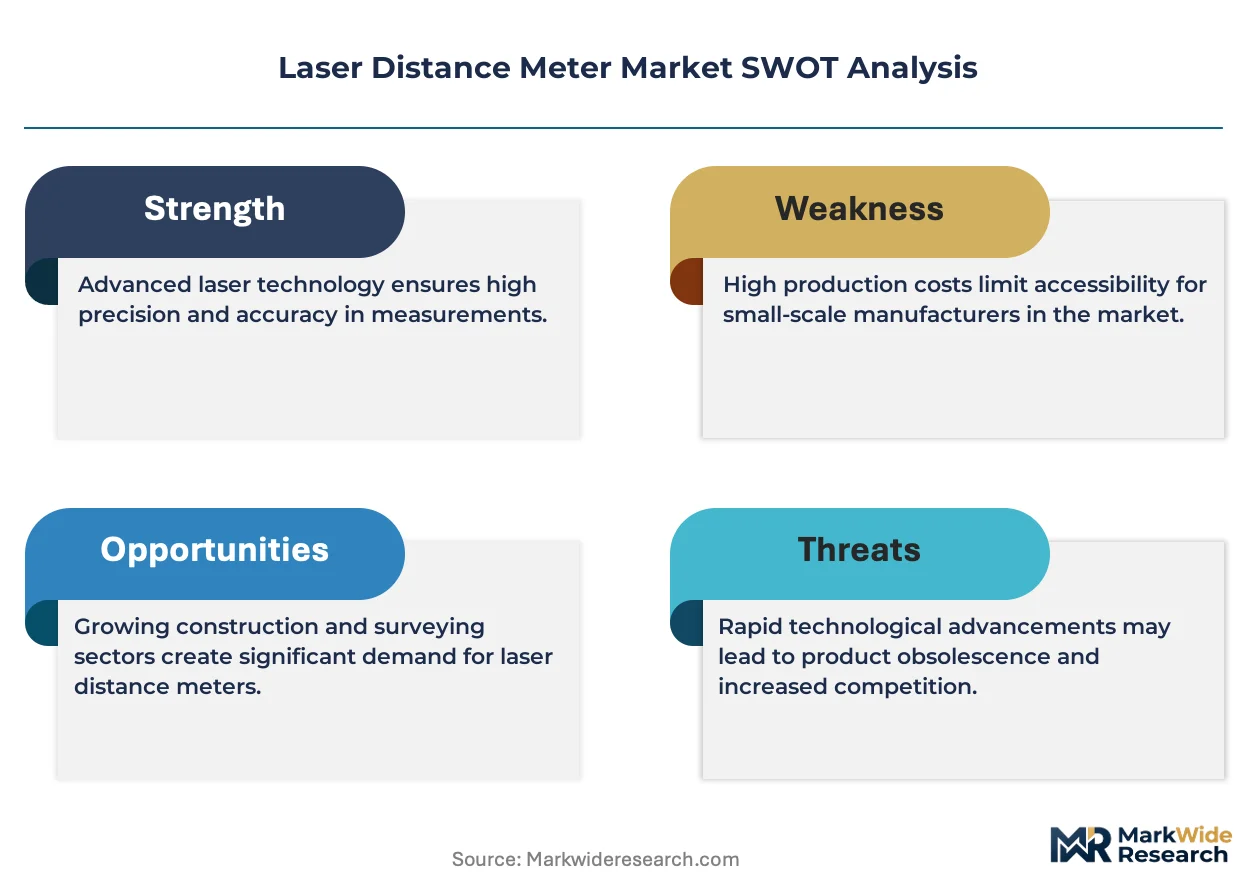
Phase shift technology is compressing the performance gap between contractor-grade handheld units and geodetic surveying instruments, forcing incumbents to reposition across precision tiers or surrender margin to modular competitors.
Growth Catalysts
- CE marking electromagnetic compatibility updates:Germany's tightened certification requirements are accelerating replacement cycles among commercial contractors who must demonstrate compliance to win public infrastructure tenders.
- Metro rail construction clusters:China's tier-one cities are mandating millimeter-grade layout verification for tunnel boring and station fit-out, creating concentrated demand for phase shift architectures.
- Build-to-rent residential towers:This asset class requires rapid as-built documentation for investor handover, displacing tape measure workflows with Bluetooth-enabled distance meters that feed directly into BIM platforms.
Market Restraints
- Indium gallium arsenide detector supply:Phase shift meters depend on this semiconductor material, and supply concentrates among a handful of Japanese and German specialty chemical producers.
- OSHA documented measurement protocols:While encouraging device adoption, compliance documentation creates administrative friction that slows procurement decisions among smaller contractors.
- Smartphone LiDAR substitution:Apple and Android flagship devices now embed time-of-flight sensors adequate for rough interior measurements, eroding the low-end handheld segment.
Strategic Opportunities
- Data center campus construction:Hyperscale operators in Northern Virginia and Frankfurt require sub-centimeter floor flatness and rack alignment, opening premium service contracts for calibrated fleet management.
- ISO 16331-1 outdoor performance testing:This emerging standard creates first-mover advantage for manufacturers who can validate claims under standardized sunlight and dust conditions.
- Integration with robotic total stations:Convergence between handheld distance meters and automated layout robotics enables single-operator workflows that reduce labor hours on large commercial sites.
Industry Challenges
- Field calibration technician shortage:Phase shift meters require periodic recertification to maintain accuracy warranties, and qualified service personnel concentrate in major metropolitan areas.
- FCC equipment authorization timelines:Laser emission level certification for new product variants routinely extends launch schedules by six to nine months.
- Legacy tape measure workflow inertia:Skilled trades in residential framing and finish carpentry resist device adoption where tactile measurement remains culturally embedded.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Distance Meter Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Meters, Multi-functional Tools, Fixed Installation Units, Digital Levels Application: Construction, Surveying, Real Estate, Interior Design End User: Contractors, Architects, Engineers, Homeowners Technology: Time of Flight, Phase Shift, Laser Triangulation, Ultrasonic |
| Companies Covered | Fluke Corporation, DEWALT, Leica Geosystems, Stanley Black & Decker, Makita, Bosch, Stabila, Trimble, Hilti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Distance Meter Market Strategic Shifts
Measurement instrumentation is fragmenting into specialized tiers as precision requirements diverge between commodity construction and geodetic surveying, while connectivity standards and calibration protocols reshape competitive moats.
Time-of-flight sensor architecture is bifurcating the contractor handheld segment into two distinct performance classes. Basic units now achieve two-millimeter accuracy sufficient for interior drywall layout and MEP rough-in. Professional-grade variants integrate inclinometers and Bluetooth data logging to feed directly into Autodesk and Trimble field software. This technical split is compressing pricing power at the middle tier while expanding margin pools at both entry and premium levels.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing manufacturers to redesign thermal management in phase shift electronics. The industrial consequence is accelerated migration to solid-state peltier cooling systems that eliminate refrigerant dependency. German and Austrian surveying equipment distributors report that CE-compliant thermal designs now feature prominently in municipal procurement specifications.
Commercial contractor buying patterns are consolidating around bundled calibration and fleet management services. Direct-to-contractor service models that guarantee measurement traceability are displacing traditional distributor relationships in North American metropolitan construction markets. This service unbundling is most visible in Texas and Florida, where large general contractors now specify calibration certificates as mandatory bid qualifications for subcontractor tiers.
Laser Distance Meter Market Segmentation
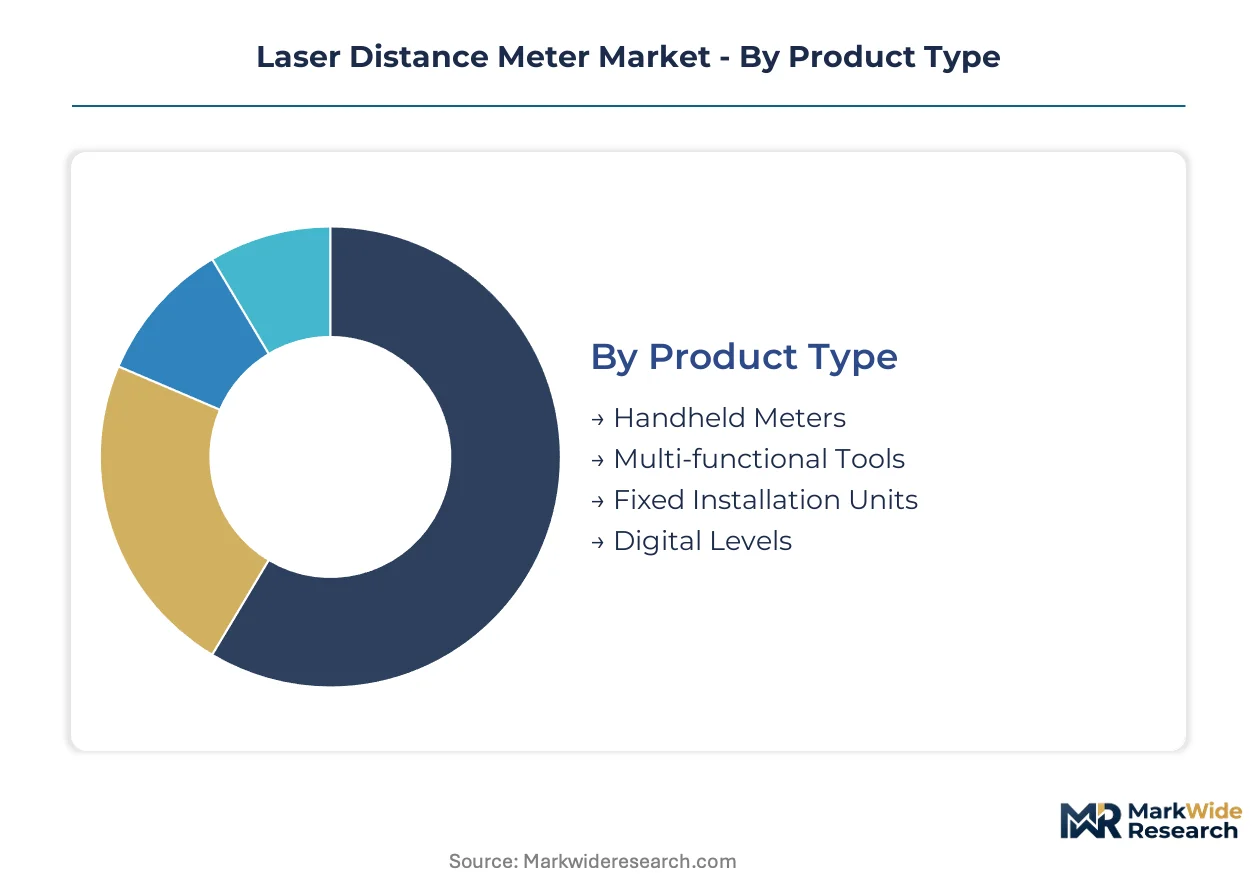
Segmentation in the laser distance meter market reveals where smartphone LiDAR substitution threatens commoditization and where precision requirements defend premium positioning. Understanding these fault lines guides resource allocation across product development and channel strategy.
Product Type:
Smartphone LiDAR encroachment varies sharply across form factors, with basic handheld units facing the most severe displacement risk while professional-grade instruments maintain defensive moats.
- Handheld Meters:Portable single-function devices dominate unit shipments through construction and real estate channels. Demand concentrates in China's tier-one cities where metro rail contractors require rapid layout verification for tunnel boring and station fit-out workflows.
- Multi-functional Tools:Integrated instruments combine distance measurement with inclinometers, Bluetooth data logging, and BIM platform connectivity. These capture expanding margin pools among commercial contractors in Texas and Florida who specify calibration certificates as mandatory bid qualifications.
- Fixed Installation Units:Permanently mounted systems serve automated manufacturing lines and warehouse dimensioning stations.
- Digital Levels:Hybrid instruments merge traditional spirit-level functionality with laser distance measurement for finish carpentry and cabinetry installation.
Handheld meters retain volume leadership; multi-functional tools hold the steepest expansion curve.
Application:
Cost tier stratification separates precision-dependent surveying workflows from tolerance-loose interior measurement tasks.
- Construction:Layout verification, as-built documentation, and MEP rough-in dominate commercial contractor procurement. Build-to-rent residential towers in Northern Virginia and Frankfurt require sub-centimeter floor flatness validation, opening premium service contracts for calibrated fleet management.
- Surveying:Geodetic-grade phase shift architectures demand millimeter precision for boundary determination and infrastructure staking. Germany's tightened CE marking electromagnetic compatibility requirements accelerate replacement cycles among contractors bidding public infrastructure tenders.
- Real Estate:Rapid spatial documentation for property marketing and investor handover.
- Interior Design:Aesthetic planning and furniture placement with lower accuracy thresholds.
Construction commands the largest revenue pool; surveying maintains the highest average selling prices.
End User:
Customer type determines whether procurement flows through distributor networks or direct service relationships.
- Contractors:Commercial general contractors and subcontractor tiers drive volume through bundled calibration and fleet management services. Direct-to-contractor models that guarantee measurement traceability displace traditional distribution in North American metropolitan construction markets.
- Architects:Design-phase spatial planning and code compliance documentation.
- Engineers:Infrastructure and industrial facility measurement protocols.
- Homeowners:DIY renovation and interior layout tasks most vulnerable to smartphone LiDAR substitution.
Contractors generate the dominant revenue share; homeowners represent the most contested segment.
Technology:
Supply concentration in indium gallium arsenide detectors constrains phase shift expansion while time-of-flight architectures compete on cost.
- Time of Flight:Pulse-based distance calculation achieves two-millimeter accuracy sufficient for interior drywall layout and MEP rough-in. Professional-grade variants integrate inclinometers and Bluetooth to feed directly into Autodesk and Trimble field software, compressing pricing power at the middle tier.
- Phase Shift:Modulated continuous-wave measurement delivers sub-centimeter precision for geodetic surveying. Japanese and German specialty chemical producers concentrate indium gallium arsenide detector supply, creating procurement risk for instrument manufacturers.
- Laser Triangulation:Short-range high-precision measurement for manufacturing quality control.
- Ultrasonic:Acoustic distance calculation with limited accuracy for consumer-grade applications.
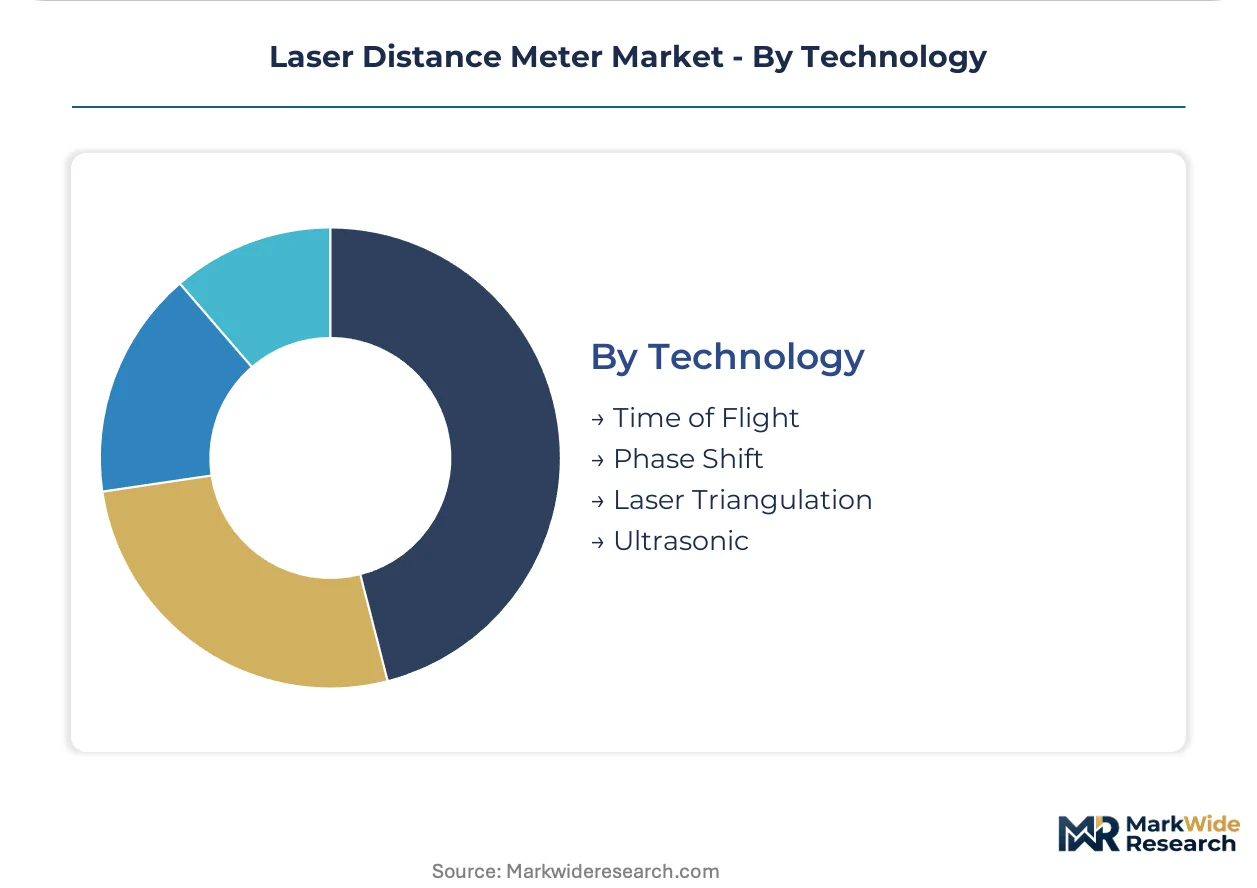
Time of flight retains volume leadership; phase shift holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium gallium arsenide detector supply concentrates among Japanese and German specialty chemical producers, creating procurement bottlenecks that shape regional manufacturing strategies. Phase shift instrument assembly clusters in southern Germany and Tokyo-Osaka corridors where component access and metrology expertise overlap.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives sub-centimeter floor flatness validation demand. FCC equipment authorization timelines routinely extend product launch schedules by six to nine months for new laser emission variants. Texas and Florida metropolitan markets now mandate calibration certificates as bid qualifications for subcontractor tiers.
Germany
Updated CE marking electromagnetic compatibility requirements accelerate replacement cycles among commercial contractors bidding public infrastructure tenders. EU F-Gas Regulation restrictions force migration to solid-state peltier cooling in phase shift electronics. Bavarian and Baden-Württemberg surveying equipment distributors report thermal design compliance now features in municipal procurement specifications.
China
Metro rail and high-speed residential construction in Beijing, Shanghai, and Shenzhen mandate millimeter-grade layout verification for tunnel boring and station fit-out. GB standards for electromagnetic compatibility shape domestic product certification pathways. Yangtze River Delta manufacturing clusters supply time-of-flight architectures for contractor-grade handheld units serving Asian export markets.
Japan
Specialty chemical producers in Osaka and Nagoya corridors concentrate indium gallium arsenide detector supply for phase shift meter manufacturers. METI industrial standards influence precision instrument export specifications across Asia-Pacific. Kanto region construction technology integrators bundle Japanese-made distance meters with robotic total station workflows.
United Kingdom
Build-to-rent residential tower development in London and Manchester requires rapid as-built documentation for investor handover. CE marking alignment post-Brexit creates dual certification requirements for instruments serving both UK and continental European contractors. Southeast England distribution channels increasingly emphasize Bluetooth-enabled units feeding directly into Autodesk and Trimble platforms.
Laser Distance Meter Market Competitive Environment
Concentration sits with diversified industrial conglomerates that leverage in-house sensor production and direct service networks. Three to four vertically integrated groups control premium-tier phase shift architectures while modular assemblers compete on time-of-flight cost structures. Strategic archetypes include: captive component manufacturers defending margin through upstream control; direct-to-contractor service specialists bundling calibration and fleet management; and geodetic-grade precision houses dominating surveying workflows. Competitive moves center on backward integration into semiconductor detector supply and geographic expansion of certified service technician networks.
Within the diversified industrial tier, Bosch and Hilti anchor contrasting service models. Bosch exemplifies captive manufacturing advantage through European distribution channel cost control. Hilti occupies a position as direct-to-contractor service archetype with bundled calibration offerings. Leica Geosystems represents geodetic-grade precision specialization for surveying workflows. Stanley Black & Decker and Makita sit within scale-driven contractor tool portfolios where distance meters complement broader power equipment ranges.
| Leading Market Players |
|---|
| Fluke Corporation |
| DEWALT |
| Leica Geosystems |
| Stanley Black & Decker |
| Makita |
| Bosch |
| Stabila |
| Trimble |
| Hilti |
| Others |
Value Chain & Pricing Dynamics
Long-term calibration service contracts lock in both indium gallium arsenide detector access and price visibility for phase shift meter manufacturers bidding German municipal infrastructure tenders. These bundled arrangements insulate premium-tier suppliers from spot-market volatility in Japanese semiconductor materials while compressing margins for modular assemblers dependent on distributor channels.
Pricing Analysis
CE marking electromagnetic compatibility dictates the pricing tier structure across European distribution channels. Three-tier pricing structure across premium, standard, and economy levels separates geodetic-grade phase shift architectures from Bluetooth-enabled professional units and basic time-of-flight handhelds. Cost compression in the economy tier intensifies because smartphone LiDAR substitution erodes the low-end segment. Commercial contractors in Texas and Florida demonstrate the least price sensitivity where calibration certificates function as mandatory bid qualifications.
Supply Chain Analysis
Japan and Germany anchor indium gallium arsenide detector production for phase shift meter manufacturers. Assembly draws from Yangtze River Delta clusters for time-of-flight architectures and Bavarian precision optics hubs for surveying-grade instruments. Single-source vulnerability concentrates in Osaka and Nagoya corridor specialty chemical producers. Distribution runs through direct-to-contractor service models in North American metropolitan markets and traditional industrial distributors across European construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around bundled calibration and fleet management services as large general contractors in Texas and Florida mandate measurement traceability from subcontractor tiers.
For Market Incumbents: Shield premium positioning through captive control over indium gallium arsenide detector supply chains against modular competitors. Accelerate certified service technician network expansion into secondary metropolitan areas to capture replacement cycle demand from Germany's tightened CE marking requirements. Backward integration into solid-state peltier cooling systems eliminates F-Gas regulatory exposure. For New Entrants and Emerging Players: Fast-track ISO 16331-1 outdoor performance certification creates entry pathway against established phase shift incumbents. Target data center campus construction in Northern Virginia and Frankfurt where hyperscale operators require sub-centimeter validation without entrenched supplier relationships. Lead with robotic total station integration to enable single-operator workflow value propositions. For Investors and Strategic Acquirers: Capital is best deployed toward direct-to-contractor service specialists with embedded calibration infrastructure across North American metropolitan construction markets. Five-to-ten year viability hinges on consolidation of fragmented aftermarket service networks. Watch for inflection when municipal procurement specifications in Germany and China mandate standardized outdoor performance testing protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Supply | Captive access to Japanese indium gallium arsenide production secures phase shift meter cost structures. |
| Calibration Service Network Expansion | Certified technician density in Texas and Florida metropolitan areas satisfies mandatory bid qualifications. |
| ISO 16331-1 Certification Investment | Validated outdoor performance claims differentiate products under standardized sunlight and dust conditions. |
| Robotic Total Station Integration | Convergence with automated layout robotics enables single-operator workflows on large commercial sites. |
| F-Gas Compliant Thermal Redesign | Solid-state peltier cooling systems meet EU regulatory requirements for phase shift electronics. |
Study Parameters
Cross-validation between primary interviews with commercial contractors, calibration service technicians, and municipal procurement officers anchors the qualitative findings. Secondary validation draws from FCC equipment authorization databases, CE marking compliance registries, and ISO standard development committee documentation. Bottom-up demand modeling triangulates against top-down construction expenditure forecasts across tier-one Chinese cities and German infrastructure budgets.
Sensitivity analysis tests forecast robustness across technology substitution scenarios and regulatory implementation timelines. Segmentation dimensions span product architecture, precision tier, end-user procurement channel, and regional certification requirements. CAGRs derive from unit shipment trajectories and average selling price evolution across handheld, multi-functional, and fixed installation form factors. Construction technology integration intensity and indium gallium arsenide detector supply availability shape projection boundaries.
Underlying assumptions cover CE marking electromagnetic compatibility implementation schedules and metro rail construction commitment levels in Beijing, Shanghai, and Shenzhen, with deviation risk concentrated in smartphone LiDAR performance advancement and indium gallium arsenide supply disruptions. Recalibration cycles align with material shifts in municipal procurement specification adoption and F-Gas regulatory enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Digital Refrigeration Gauge Market
Measuring Instruments
Global Container Weighing Systems Market
Measuring Instruments
Network Diagnostic Tools Market
Measuring Instruments
Moisture Meter Market
Measuring Instruments
Global Dimensional Metrology Software Market
Measuring Instruments
India Hydrological and Meteorological Equipment Market
Measuring Instruments
Monitoring Tools Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
Handheld Wind Anemometer Market
Measuring Instruments
Communication Test and Measurement (Ctandm) Market
Measuring Instruments
Global Instrument Calibrator Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Americas 3D Metrology Market
Measuring Instruments
Global Dissolved Oxygen Meters and Controllers Market
Measuring Instruments
Communication Test Equipment (CTE) Market
Measuring Instruments
Global Laser Measuring Instrument Market