
 Data Loggers Market | 2026-2036
Data Loggers Market Size, Share, and Industry Trends Forecast 2026-2036
Data Loggers Market Analysis
Wireless sensor miniaturization is narrowing the performance gap between compact loggers and traditional benchtop systems. Onset Computer Corporation leverages its HOBO product lineage to dominate environmental monitoring deployments across North American research institutions. Yokogawa Electric Corporation sustains premium positioning in industrial automation through high-channel-count architectures. Campbell Scientific, Inc. anchors its competitive stance in precision agriculture and extreme-climate field stations.
Data loggers are electronic instruments that autonomously record physical or electrical parameters—temperature, humidity, pressure, voltage—over time using onboard memory and calibrated analog-to-digital converters, with sampling intervals ranging from milliseconds to hours depending on application criticality. These devices serve industries requiring verifiable environmental or operational records for quality assurance, regulatory compliance, and process optimization. Temperature loggers command the largest revenue share due to pervasive cold chain mandates across pharmaceuticals and perishables, while wireless technology represents the fastest-expanding architecture as Bluetooth and low-power wide-area protocols eliminate cabling costs in distributed sensor networks. USB-based systems retain relevance in laboratory and desktop calibration workflows where physical tethering ensures data integrity.
FDA 21 CFR Part 11 and EU GDP guidelines compel pharmaceutical distributors to deploy validated temperature logging systems with audit-trail capabilities, directly shaping hardware specifications and software feature requirements. EPA emissions monitoring rules and ISO 17025 calibration standards further constrain product design for industrial and laboratory applications. Stakeholders must monitor evolving cybersecurity requirements for connected devices, as wireless data loggers face escalating scrutiny over encryption protocols and network vulnerability management.
Market Dynamics
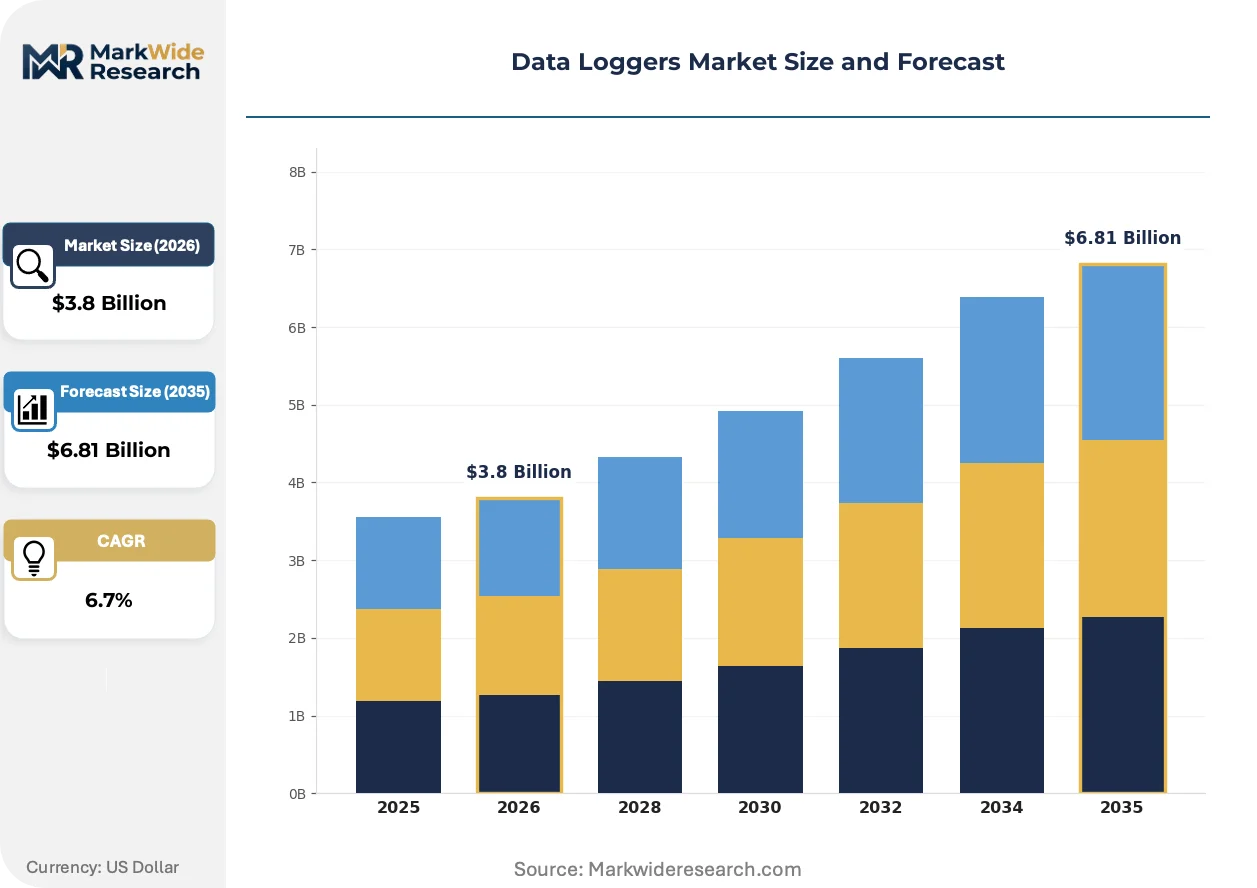
Wireless sensor miniaturization is compressing hardware footprints while expanding deployment density across cold chain networks, forcing incumbent vendors to retool product architectures around battery autonomy and mesh networking protocols.
Growth Catalysts
- FDA 21 CFR Part 11:Pharmaceutical distributors must deploy validated temperature logging systems with immutable audit trails, mandating hardware upgrades across US distribution networks.
- Bluetooth Low Energy:This protocol eliminates cabling costs in distributed sensor networks, accelerating replacement cycles for wired legacy installations in food processing facilities.
- German industrial automation clusters:Concentrated procurement from precision engineering hubs anchors European demand for high-channel-count data acquisition systems.
Market Restraints
- Lithium battery supply concentration:Dependence on East Asian cell manufacturers creates input cost volatility and geopolitical exposure for portable logger producers.
- Calibration infrastructure scarcity:ISO 17025-accredited laboratories remain concentrated in Western Europe and North America, limiting service accessibility elsewhere.
- Smartphone-based substitutes:Consumer-grade temperature probes with app connectivity threaten low-end professional logger segments in price-sensitive markets.
Strategic Opportunities
- India cold chain expansion:FSSAI traceability mandates and PLI scheme incentives for food processing infrastructure create untapped demand for validated logging systems.
- EU Green Deal alignment:Energy efficiency monitoring requirements in commercial buildings generate new application verticals for multi-parameter environmental loggers.
- LPWAN convergence:Integration of LoRa and NB-IoT protocols enables decade-long battery life in agricultural soil monitoring, opening remote deployment scenarios.
Industry Challenges
- Firmware cybersecurity certification:Connected wireless loggers face escalating scrutiny over encryption protocols, forcing vendors to navigate fragmented national cybersecurity frameworks.
- Legacy system integration:Pharmaceutical manufacturers require seamless data handoffs between new wireless loggers and existing SCADA infrastructure, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Loggers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Loggers, Humidity Loggers, Pressure Loggers, Voltage Loggers Technology: Wireless, Ethernet, USB, Bluetooth End User: Aerospace, Healthcare, Food & Beverage, Environmental Monitoring Application: Transportation, Energy Management, Industrial Automation, Research |
| Companies Covered | Testo SE & Co. KGaA, Onset Computer Corporation, Hioki E.E. Corporation, Yokogawa Electric Corporation, Omega Engineering, Inc., Campbell Scientific, Inc., ABB Ltd., National Instruments Corp., Dickson Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Loggers Market Emerging Trajectories
Sensor fusion architectures and edge computing capabilities are redefining what constitutes a standalone logger versus a distributed node in larger telemetry networks.
Multi-sensor fusion chipsets are digitizing environmental monitoring by consolidating temperature, humidity, pressure, and accelerometer inputs into single-package modules. Pharmaceutical contract manufacturers are adopting these integrated platforms at accelerated rates to reduce BOM complexity. This consolidation is digitizing quality assurance workflows by enabling real-time anomaly detection without cloud dependency.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants, compelling cold chain operators to retrofit monitoring systems for alternative cooling chemistries. Industrial refrigeration OEMs must now validate logger compatibility with CO2 and ammonia circuits. German food logistics providers are responding by specifying corrosion-resistant sensor housings in procurement tenders.
Subscription-based calibration and firmware update services are displacing perpetual ownership models among mid-sized pharmaceutical distributors. Equipment lessors and third-party logistics providers are capturing this shift through bundled hardware-service contracts. This transformation is most visible in the Netherlands, where GDP compliance outsourcing has concentrated buyer power among specialized cold chain service firms.
Data Loggers Market Segmentation
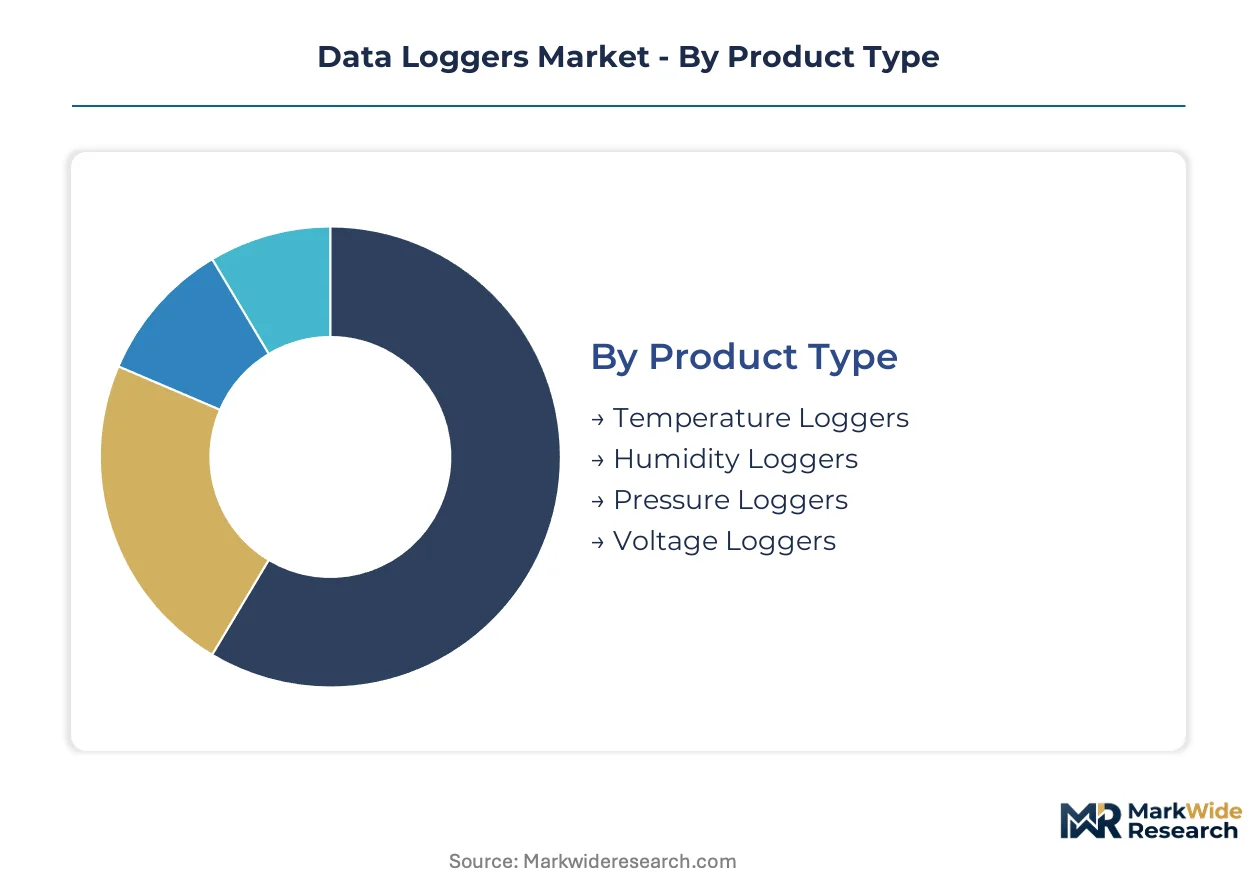
Data logger architectures diverge sharply across deployment environments, with cold chain mandates driving hardware specifications in pharmaceuticals while industrial automation demands multi-channel precision. Understanding these segment boundaries clarifies why vendors maintain parallel product families rather than unified platforms.
Product Type:
Cost tier differentiation separates commodity single-parameter devices from premium multi-sensor platforms requiring calibration certificates.
- Temperature Loggers:Calibrated thermistor or thermocouple-based units with FDA 21 CFR Part 11 audit trails dominate pharmaceutical distribution. Cold chain operators in Germany and the Netherlands specify these for GDP compliance across vaccine and biologics shipments.
- Humidity Loggers:Capacitive polymer sensors measure relative humidity with ±2% accuracy for semiconductor cleanrooms and museum conservation. Demand concentrates in Swiss pharmaceutical manufacturing where moisture control protects lyophilized drug stability.
- Pressure Loggers:Piezoresistive transducers monitor pipeline integrity and HVAC system performance in commercial buildings.
- Voltage Loggers:Multi-channel acquisition systems capture electrical signatures for predictive maintenance in industrial motor fleets.
Temperature loggers command the established base. The steepest expansion runs through humidity loggers as moisture-sensitive biologics proliferate.
Technology:
Application context determines connectivity architecture, with mobility requirements favoring untethered protocols and laboratory settings retaining physical connections.
- Wireless:Battery-powered nodes using proprietary RF or mesh protocols eliminate cabling in refrigerated transport containers. Food logistics operators in India deploy these for FSSAI-mandated traceability across fragmented cold chain infrastructure.
- Bluetooth:Low-energy beacons enable smartphone-based data retrieval for last-mile vaccine delivery in rural clinics. This protocol is gaining share fastest in price-sensitive emerging markets where dedicated reader hardware is uneconomical.
- Ethernet:Powered devices with Power-over-Ethernet supply continuous monitoring for server room and manufacturing line applications.
- USB:Tethered loggers with direct PC connectivity persist in calibration laboratories and quality assurance workflows requiring absolute data integrity.
Ethernet anchors the established base in fixed industrial installations. The steepest expansion runs through Bluetooth as smartphone penetration democratizes data access.
End User:
Customer type shapes procurement authority, with regulated industries demanding validated systems and commercial sectors prioritizing total cost of ownership.
- Healthcare:Hospitals and blood banks require 21 CFR Part 11-compliant systems with tamper-evident seals for controlled substance storage. US hospital networks drive specification standards through group purchasing organization contracts.
- Food & Beverage:Processors and distributors deploy HACCP-validated loggers across cooking, cooling, and distribution critical control points. German dairy cooperatives specify corrosion-resistant housings for ammonia-based refrigeration retrofits under EU F-Gas Regulation.
- Environmental Monitoring:Research institutions and regulatory agencies deploy weatherproof stations for climate and pollution tracking.
- Aerospace:Flight test programs and ground support equipment utilize shock-resistant units with extended temperature ranges.
Healthcare commands the established base through regulatory stickiness. The steepest expansion runs through Food & Beverage as traceability mandates globalize.
Application:
Volume scale separates high-unit-count transportation deployments from low-volume precision research instrumentation.
- Transportation:Single-use and returnable loggers track temperature excursions across ocean, air, and road freight. Pharmaceutical 3PLs in the Netherlands bundle these into GDP compliance service contracts with subscription calibration.
- Industrial Automation:Programmable logic controller-integrated systems capture process parameters for Six Sigma quality programs. German automotive suppliers anchor demand for high-channel-count architectures with millisecond sampling.
- Energy Management:Building automation systems leverage environmental loggers for HVAC optimization and carbon reporting under EU Green Deal requirements.
- Research:Precision-grade instruments with NIST-traceable calibration support academic and government laboratory protocols.
Industrial automation commands the established base. The steepest expansion runs through transportation as pharmaceutical cold chain complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German instrument manufacturers export precision data acquisition systems to pharmaceutical distributors across the Netherlands and Switzerland, anchoring intra-European trade flows in validated cold chain hardware.
United States
Hospital networks and blood banks drive procurement of 21 CFR Part 11-compliant temperature loggers through group purchasing organization contracts. FDA traceability mandates for controlled substance storage force hardware upgrades across distribution networks. Boston-area research institutions anchor demand for precision-grade environmental monitoring stations.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg specify high-channel-count data acquisition systems for automotive supplier quality programs. EU F-Gas Regulation compels food logistics providers to retrofit ammonia-compatible monitoring hardware. Testo SE & Co. KGaA anchors domestic supply capacity for corrosion-resistant sensor housings.
Netherlands
Third-party pharmaceutical logistics providers bundle GDP compliance services with subscription-calibrated logger deployments. GDP guidelines mandate validated temperature logging with immutable audit trails across vaccine distribution networks. Rotterdam-Antwerp corridor cold storage operators concentrate procurement authority for wireless transport monitoring.
India
FSSAI traceability mandates and PLI scheme incentives for food processing infrastructure accelerate cold chain instrument adoption. Fragmented rural distribution networks favor Bluetooth-enabled loggers with smartphone data retrieval. Maharashtra and Gujarat dairy cooperatives deploy HACCP-validated systems across ammonia refrigeration retrofits.
Japan
Semiconductor cleanroom operators demand humidity loggers with ±2% accuracy for moisture-sensitive wafer processing. METI industrial standards shape specifications for multi-parameter environmental monitoring in precision manufacturing. Osaka-Kyoto pharmaceutical manufacturing corridor anchors regional procurement for lyophilized drug stability systems.
Data Loggers Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Incumbent vendors with established calibration service networks defend relationships with regulated pharmaceutical distributors. Three archetypes dominate: precision instrumentation conglomerates with broad environmental sensing portfolios, wireless connectivity specialists leveraging mesh protocol expertise, and regional calibration-service integrators bundling hardware with compliance outsourcing. Competitive moves concentrate on strategic partnerships with cold chain logistics providers and portfolio diversification into subscription-based firmware update services.
Among precision instrumentation specialists, Testo SE & Co. KGaA and Yokogawa Electric Corporation occupy positions exemplifying the premium-tier archetype for industrial automation and validated monitoring applications. Onset Computer Corporation represents the wireless-focused specialist tier, anchoring environmental monitoring deployments through protocol-level expertise. Hioki E.E. Corporation sits within the electrical measurement specialist segment, serving industrial predictive maintenance applications with voltage acquisition systems.
| Leading Market Players |
|---|
| Testo SE & Co. KGaA |
| Onset Computer Corporation |
| Hioki E.E. Corporation |
| Yokogawa Electric Corporation |
| Omega Engineering, Inc. |
| Campbell Scientific, Inc. |
| ABB Ltd. |
| National Instruments Corp. |
| Dickson Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in precision sensor foundries across Taiwan and South Korea is tightening component availability for multi-channel data acquisition systems, forcing logger manufacturers to absorb input cost volatility while defending margin positions through certification-tier pricing.
Pricing Analysis
The technology-generation pricing gap between legacy wired architectures and next-generation Bluetooth Low Energy mesh systems is compressing as semiconductor integration reduces BOM differentials. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 11-validated pharmaceutical systems from HACCP-compliant food service units and uncalibrated consumer-grade devices. Cost compression in the economy tier is intensifying because smartphone-based temperature probes with app connectivity threaten entry-level professional segments. Food & Beverage distributors in price-sensitive emerging markets exhibit highest price sensitivity, while pharmaceutical 3PLs in the Netherlands and Germany demonstrate lowest sensitivity due to GDP compliance requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for data logger OEMs sourcing precision analog-to-digital converters and lithium primary cells. Manufacturing concentrates in China, Germany, and Japan, with final assembly drawing from Malaysian and Mexican contract electronics facilities. Raw material dependencies include rare-earth magnets for sensor packaging, lithium thionyl chloride cells for decade-long battery autonomy, and corrosion-resistant stainless steels for ammonia-compatible refrigeration retrofits. Single-source vulnerability in East Asian battery cell supply creates geopolitical exposure. Distribution runs through specialized industrial instrumentation distributors in Europe and direct OEM relationships in North American pharmaceutical networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data logger incumbents face substitution defense against smartphone-connected consumer probes and platform-based environmental monitoring services that threaten to commoditize low-end professional segments.
For Market Incumbents: Build calibration-service moats by acquiring ISO 17025-accredited laboratories in underserved geographies and bundling subscription firmware update contracts with hardware deployments. Pharmaceutical distributors in India and Southeast Asia require local calibration infrastructure to satisfy FSSAI and emerging traceability mandates. Backward integration into sensor fusion chipsets reduces BOM exposure to semiconductor foundry pricing volatility. Channel control through exclusive partnerships with cold chain logistics providers in the Rotterdam-Antwerp corridor defends against wireless connectivity specialists. For New Entrants and Emerging Players: Rural Indian dairy cooperatives represent the most penetrable white-space target, where fragmented cold chain infrastructure and FSSAI compliance deadlines outpace incumbent service capacity. Bluetooth-enabled loggers with smartphone data retrieval bypass dedicated reader hardware investments that price out smallholder aggregators. Target ammonia refrigeration retrofit specifications under EU F-Gas Regulation by partnering with German industrial automation clusters for corrosion-resistant housing design. Subscription-based calibration outsourcing contracts with third-party logistics providers capture recurring revenue without upfront capital intensity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across wireless sensor platforms as semiconductor integration consolidates multi-parameter acquisition into single-package modules. The 5-10 year viability window favors precision instrumentation conglomerates with established regulatory compliance workflows over pure-play connectivity vendors. Acquisition target archetype: regional calibration-service integrators bundling hardware with GDP compliance outsourcing in the Netherlands and Switzerland. The signal to watch is FDA cybersecurity guidance publication for connected medical devices, which would force firmware architecture redesigns and consolidate vendor bases around certified platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | ISO 17025 laboratory acquisitions in India satisfy FSSAI traceability mandates for dairy cooperatives. |
| Sensor Fusion Chipset Integration | Multi-parameter modules reduce BOM complexity for pharmaceutical contract manufacturers adopting edge computing. |
| Subscription Service Transition | Bundled hardware-calibration contracts capture recurring revenue from GDP compliance outsourcing in the Netherlands. |
| LPWAN Protocol Convergence | LoRa and NB-IoT integration enables decade-long battery life for remote agricultural soil monitoring deployments. |
| Cybersecurity Certification Investment | FDA encryption protocol compliance defends against platform commoditization in hospital network procurement. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cold chain logistics directors, pharmaceutical quality assurance managers, food processing plant engineers, and industrial automation procurement leads. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EU GDP regulatory texts, FSSAI circulars on traceability mandates, SEC filings of precision instrumentation conglomerates, and customs data on environmental sensor trade flows. Bottom-up unit economics across temperature, humidity, and pressure logger segments were triangulated against top-down market sizing from industrial automation capital expenditure patterns.
Calibration against historical adoption curves for wireless sensor networks anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, connectivity architecture, end-user industry, application environment, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating cold chain infrastructure investment schedules and pharmaceutical distribution network expansion. Industry-specific forecast inputs included lithium battery cost trajectories and ISO 17025 laboratory accreditation growth rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by smartphone-platform entrants or hyperscaler environmental monitoring services would shift outcomes beyond modeled bounds. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Global Dissolved Oxygen Meters and Controllers Market
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Monitoring Tools Market
Measuring Instruments
Global Laser Measuring Instrument Market
Measuring Instruments
3D Metrology Market
Measuring Instruments
Borescope Inspection Camera Market
Measuring Instruments
Temperature Calibrator Market
Measuring Instruments
Data Acquisition Market
Measuring Instruments
India Hydrological and Meteorological Equipment Market
Measuring Instruments
Global Reference Thermometer Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
North America Scientific Instruments Market
Measuring Instruments
Moisture Meter Market
Measuring Instruments
Global Instrument Calibrator Market
Measuring Instruments
Ultraviolet Data Logger Market