
 Temperature Calibrator Market | 2026-2036
Temperature Calibrator Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Calibrator Market Analytics
Digital sensor fusion and IoT-enabled traceability is reshaping how temperature calibrators integrate into plant-wide asset management systems. Fluke Corporation leverages its distributed service network to sustain aftermarket revenue streams across process industries. AMETEK Inc. anchors its position through deep vertical integration into precision sensor manufacturing. WIKA Alexander Wiegand SE & Co. KG differentiates by dominating high-pressure and high-temperature niche applications where certification requirements are most stringent.
A temperature calibrator is a precision instrument that generates or measures known thermal reference points—typically spanning -196°C to 1200°C depending on type—to verify and adjust the accuracy of thermocouples, RTDs, infrared pyrometers, and bimetallic thermometers against traceable standards such as ITS-90. Dry block calibrators lead unit volume due to their portability and suitability for field service applications, though infrared calibrators command premium pricing in non-contact measurement environments where emissivity compensation adds technical complexity. Digital technology represents the fastest-expanding segment as facilities replace legacy analog units to meet data integrity requirements under 21 CFR Part 11 and comparable pharmaceutical regulations.
FDA validation protocols and EMA GMP Annex 15 guidelines mandate documented calibration traceability for temperature-critical processes, directly expanding replacement demand in pharmaceutical and biotechnology manufacturing. The EPA's Good Automated Manufacturing Practice framework and ISO/IEC 17025 accreditation standards further tighten compliance windows for third-party calibration service providers. Stakeholders must monitor how emerging wireless and smart calibration architectures alter audit trail requirements and capital deployment priorities across regulated industries.
Market Dynamics
Pharmaceutical manufacturers are compressing calibration replacement cycles as FDA and EMA validation protocols harden documentation requirements for temperature-critical processes. This regulatory tightening is forcing facilities to retire analog architectures faster than historical depreciation schedules anticipated.
Growth Catalysts
- EMA GMP Annex 15:The guideline's expanded traceability mandates are compelling European biotechnology facilities to upgrade calibration infrastructure ahead of scheduled audits.
- Automotive battery testing:EV cell formation protocols require tighter thermal control, driving German and South Korean OEMs to expand in-house metrology capacity.
- Dry block portability:Field service applications favor lightweight calibrators, accelerating replacement of benchtop-only units in upstream oil and gas operations.
Market Restraints
- Platinum price volatility:RTD reference sensors depend on platinum wire, exposing manufacturers to commodity swings that compress margin predictability.
- Accredited laboratory concentration:Germany hosts disproportionate third-party calibration capacity, creating geographic dependency for traceability chains.
- Infrared emissivity uncertainty:Non-contact calibration remains technically constrained by surface property variability, limiting adoption in high-precision pharmaceutical applications.
Strategic Opportunities
- India's pharmaceutical expansion:CDSCO's tightening GMP enforcement creates replacement demand among domestic generic manufacturers upgrading for export certification.
- Wireless audit trails:Smart calibration architectures that auto-log to cloud databases address 21 CFR Part 11 data integrity requirements without manual transcription.
- Japan's hydrogen economy:METI-funded hydrogen liquefaction projects require cryogenic calibration capabilities below -196°C that few incumbent suppliers currently serve.
Industry Challenges
- ITS-90 implementation expertise:Facilities struggle to source technicians capable of maintaining primary standard traceability chains across distributed manufacturing sites.
- Legacy system integration:Digital calibrators must interface with decades-old distributed control systems through proprietary protocols, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Calibrator Market |
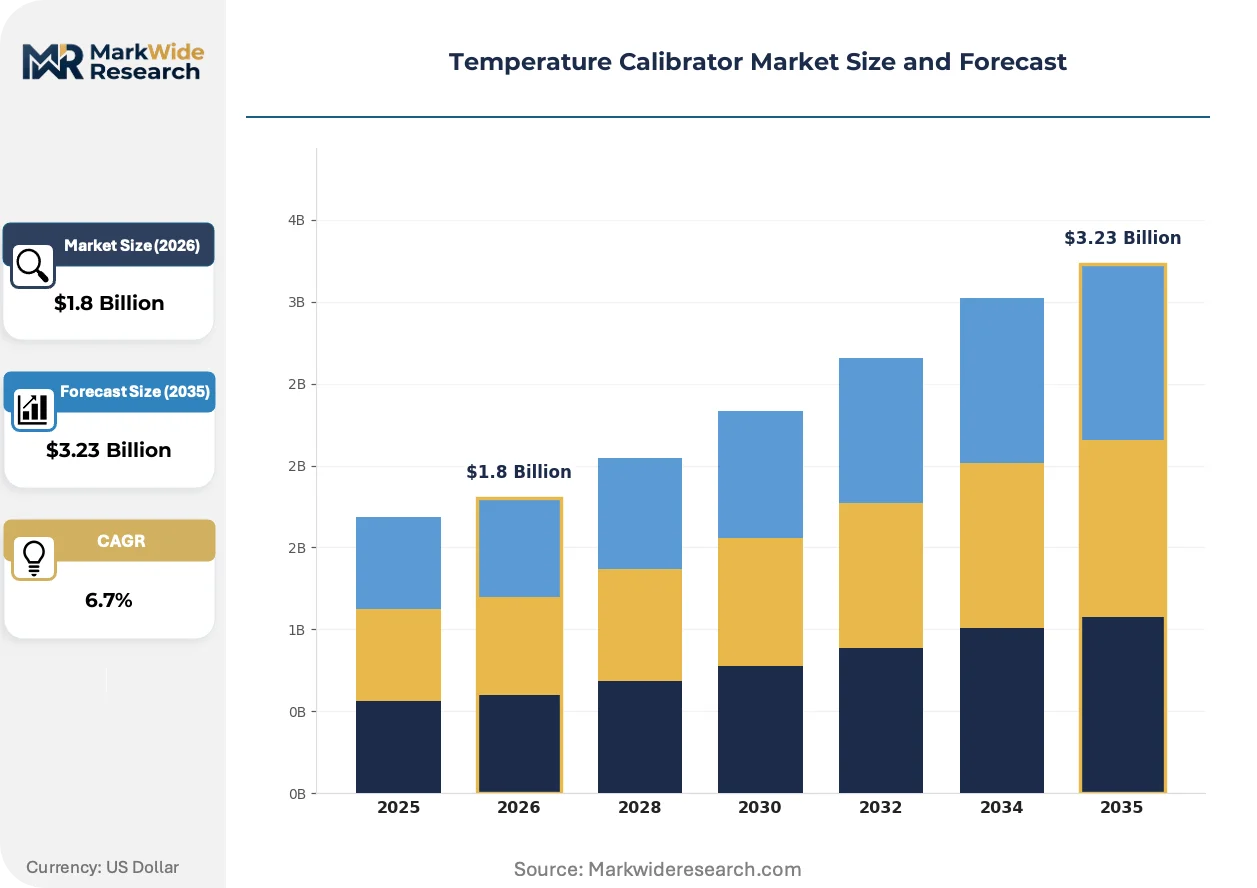
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Calibrators, Infrared Calibrators, Thermocouple Calibrators, Dry Block Calibrators Technology: Analog, Digital, Wireless, Smart End User: Manufacturing, Laboratory, Automotive, Aerospace Application: Research & Development, Quality Assurance, Process Control, Environmental Monitoring |
| Companies Covered | Fluke Corporation, AMETEK Inc., WIKA Alexander Wiegand SE & Co. KG, Additel Corporation, Yokogawa Electric Corporation, Beamex Oy AB, Omega Engineering Inc., Anritsu Meter Co., Ltd., Testo SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Calibrator Market Evolving Landscape
Digital architectures are virtualizing calibration workflows that once demanded physical presence, compressing both labor intensity and documentation latency. This shift is redrawing competitive advantage around software capabilities rather than hardware precision alone.
Multifunction calibrator platforms are virtualizing discrete single-purpose instruments by embedding thermocouple, RTD, and infrared simulation within unified firmware. Pharmaceutical quality departments in Switzerland and the United States are adopting these units to reduce bench clutter and simplify technician training. The technology is virtualizing capital allocation decisions, allowing facilities to defer dedicated infrared calibrator purchases until non-contact measurement volumes justify standalone equipment.
EPA's Good Automated Manufacturing Practice framework is tightening audit trail requirements for environmental monitoring systems in sterile manufacturing. Facilities must now demonstrate continuous calibration status rather than point-in-time certificates, forcing investment in automated documentation infrastructure. Biologics manufacturers in the United States are responding fastest, driven by warning letter precedents that elevated calibration documentation to inspection priority status.
Asset-as-a-service contracting is displacing outright purchase for high-end calibration systems, particularly among mid-sized contract manufacturers. Third-party metrology providers in Germany now bundle equipment, maintenance, and traceability documentation into per-calibration fees. This model is penetrating fastest among European chemical producers seeking to convert fixed calibration infrastructure costs into variable operating expenses aligned with batch campaign volumes.
Temperature Calibrator Market Segmentation
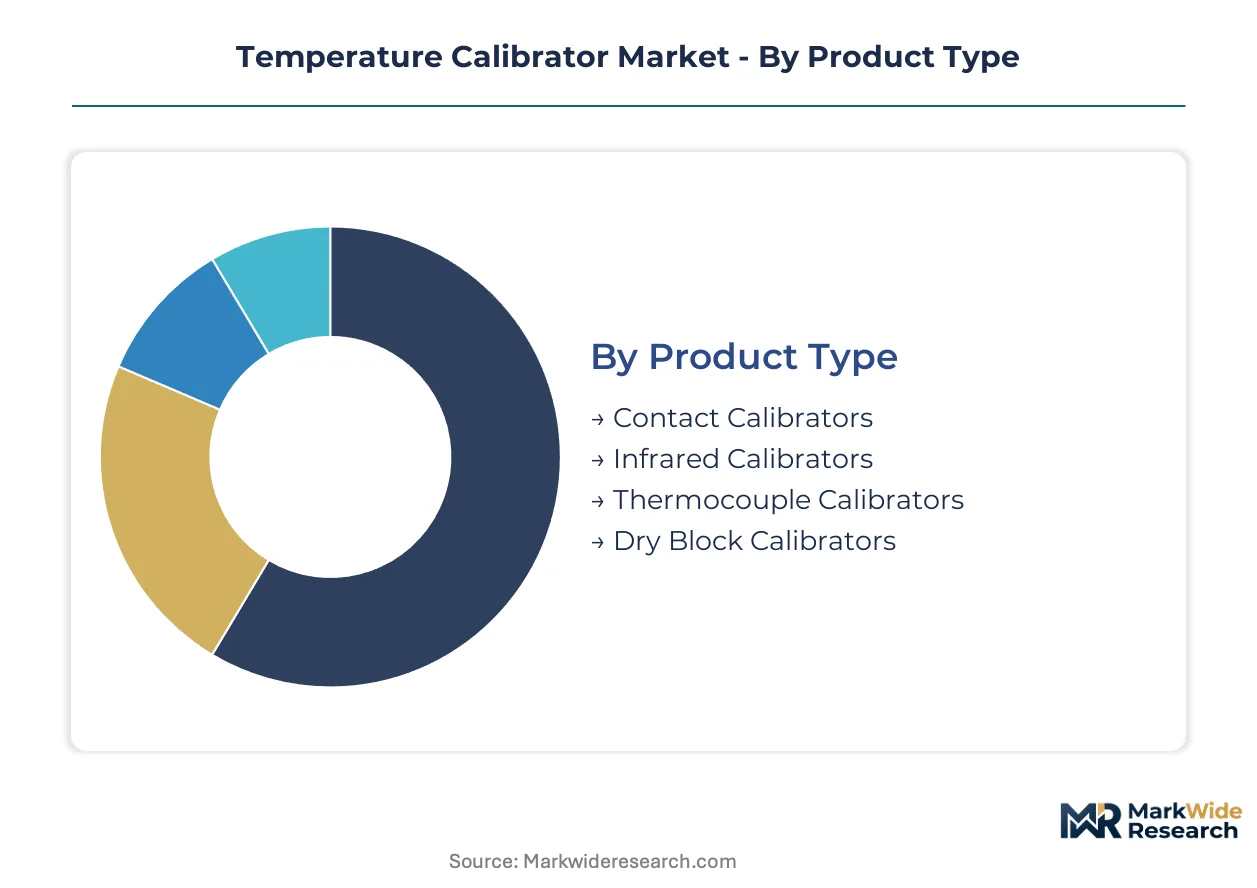
Temperature calibrator segmentation reveals how technical specifications map to compliance requirements across regulated industries. Product architecture, connectivity protocols, and end-use precision demands create distinct purchasing patterns that suppliers must address through specialized positioning.
Product Type:
Dry block units dominate field service mobility requirements, while infrared systems command specialized non-contact premiums in pharmaceutical and semiconductor environments.
- Dry Block Calibrators:Portable heating blocks with interchangeable inserts achieve thermal stability across -25°C to 650°C for thermocouple and RTD verification. Upstream oil and gas operators in the Permian Basin and North Sea deploy these units for pipeline sensor validation without laboratory transport delays.
- Infrared Calibrators:Blackbody radiation sources with emissivity-controlled surfaces generate traceable temperature references for pyrometer verification. German automotive paint curing lines and Japanese steel mills absorb volume for non-contact measurement chains where surface contact risks contamination or damage.
- Contact Calibrators:Benchtop instruments with precision probe interfaces serve laboratory primary standard maintenance.
- Thermocouple Calibrators:Dedicated millivolt simulators with cold-junction compensation target type-specific verification workflows.
Established volume favors dry block portability; emerging adoption favors infrared sophistication for automated production lines.
Technology:
Connectivity architecture determines audit trail automation potential and integration depth with plant asset management systems.
- Digital:Microprocessor-controlled units with stored calibration coefficients and linearization algorithms eliminate manual interpolation errors. FDA-regulated biologics facilities in Massachusetts and North Carolina are retiring analog architectures to satisfy 21 CFR Part 11 data integrity mandates ahead of inspection cycles.
- Smart:Embedded firmware with predictive drift algorithms and automated interval adjustment reduces unplanned downtime in continuous manufacturing. Swiss pharmaceutical contract manufacturers deploy these systems for real-time calibration status dashboards that satisfy EMA GMP Annex 15 documentation intensity.
- Analog:Potentiometer-based reference generation persists in cost-constrained maintenance shops with minimal compliance exposure.
- Wireless:Bluetooth and Wi-Fi-enabled units transmit results directly to cloud databases, eliminating transcription risk in multi-site operations.
Smart systems gain share fastest in regulated batch manufacturing; digital conversion accelerates across all compliance-exposed segments.
End User:
Precision requirements and procurement authority concentration vary sharply across facility types and operational scales.
- Manufacturing:Process industries with distributed sensor networks require high-volume, rapid-cycle verification equipment. Chemical producers along the US Gulf Coast maintain dedicated metrology teams with dry block fleets for monthly thermocouple verification across reactor trains.
- Laboratory:Accredited calibration facilities demand primary standard traceability with expanded uncertainty budgets below 0.05°C. Germany's dense cluster of DAkkS-accredited laboratories anchors European traceability chains for export certification.
- Automotive:EV battery formation protocols are tightening thermal control tolerances, expanding in-house capacity at South Korean and German OEMs.
- Aerospace:NIST-traceable requirements for flight hardware testing sustain premium pricing for specialized cryogenic and high-temperature ranges.
Laboratory accreditation sustains premium positioning; automotive electrification drives steepest capacity expansion.
Application:
Documentation intensity and measurement frequency dictate equipment specification and replacement cycle compression.
- Quality Assurance:Incoming inspection and final release testing demand documented calibration chains with audit-ready certificates. Generic pharmaceutical manufacturers in India upgrade infrastructure to meet CDSCO enforcement tightening for export market access.
- Process Control:Continuous manufacturing requires embedded calibration verification without production interruption. Biologics facilities deploy smart architectures with automated drift detection to maintain validated states across campaign durations.
- Research & Development:Experimental flexibility favors multifunction platforms with broad temperature range coverage.
- Environmental Monitoring:EPA Good Automated Manufacturing Practice requirements for sterile manufacturing elevate continuous calibration status demonstration above point-in-time certificates.
Quality assurance absorbs replacement volume; process control integration climbs fastest as continuous manufacturing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German calibration equipment flows primarily to pharmaceutical and automotive buyers across Switzerland, Austria, and the Netherlands, establishing a central European trade corridor for precision metrology instruments.
United States
Biologics manufacturers in Massachusetts and North Carolina are retiring analog calibration architectures to satisfy FDA 21 CFR Part 11 mandates. EPA Good Automated Manufacturing Practice frameworks tighten environmental monitoring documentation for sterile manufacturing. The Gulf Coast chemical corridor maintains dedicated metrology teams with dry block fleets for monthly thermocouple verification across reactor trains.
Germany
Automotive OEMs and chemical producers sustain dense clusters of DAkkS-accredited calibration laboratories. EMA GMP Annex 15 traceability mandates compel biotechnology facilities to upgrade infrastructure ahead of scheduled audits. The Rhine-Ruhr industrial region anchors European traceability chains for export certification to pharmaceutical markets.
Japan
Steel mills and automotive paint curing lines absorb volume for non-contact measurement chains where surface contact risks contamination. METI-funded hydrogen liquefaction projects require cryogenic calibration capabilities below -196°C. The Nagoya-Tokyo industrial corridor drives adoption of smart calibration architectures with automated drift detection.
India
Domestic generic manufacturers upgrade calibration infrastructure for export market access as CDSCO tightens GMP enforcement. Pharmaceutical quality departments compress replacement cycles to meet FDA and EMA validation protocols for active pharmaceutical ingredient facilities. The Maharashtra-Gujarat pharmaceutical belt concentrates demand for digital calibrators with cloud-based audit trails.
South Korea
EV battery formation protocols require tighter thermal control, expanding in-house metrology capacity at automotive OEMs. MFDS pharmaceutical manufacturing guidelines drive documentation intensity for temperature-critical processes. The Busan-Ulsan industrial complex anchors battery cell production calibration requirements for export to European and North American markets.
Temperature Calibrator Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational instrumentation conglomerates with distributed service networks, precision sensor manufacturers with backward integration into calibration equipment, and specialized metrology firms focused on niche temperature ranges. Two dominant competitive moves define current positioning: geographic expansion through localized accreditation partnerships and portfolio diversification into multifunction platforms that virtualize discrete single-purpose instruments.
Within the multinational instrumentation tier, Fluke Corporation and AMETEK Inc. exemplify scale-driven positioning through captive supply chains and aftermarket service density. Beamex Oy AB and Yokogawa Electric Corporation occupy positions among automation-integrated specialists serving process industries with embedded calibration verification. WIKA Alexander Wiegand SE & Co. KG anchors the precision sensor tier through in-house production of reference-grade measurement elements.
| Leading Market Players |
|---|
| Fluke Corporation |
| AMETEK Inc. |
| WIKA Alexander Wiegand SE & Co. KG |
| Additel Corporation |
| Yokogawa Electric Corporation |
| Beamex Oy AB |
| Omega Engineering Inc. |
| Anritsu Meter Co., Ltd. |
| Testo SE & Co. KGaA |
| Others |
Value Network & Pricing Analysis
German precision sensor manufacturers concentrate upstream reference-grade platinum wire supply, anchoring margin capture in downstream calibration equipment assembly while compressing pricing flexibility for mid-tier competitors sourcing from spot markets.
Pricing Analysis
Digital-to-analog pricing gaps span three technology generations: legacy analog units trade at commodity levels, current-generation digital platforms command certification premiums, and emerging smart architectures with predictive drift algorithms capture subscription-style recurring revenue. Three-tier pricing structure across premium, standard, and economy levels separates DAkkS-accredited laboratory systems from field-portable dry blocks and maintenance-shop analog units. Cost compression in economy tiers intensifies because Chinese manufacturers are flooding Asian markets with unaccredited digital calibrators. Contract manufacturers with thin compliance exposure exhibit highest price sensitivity; pharmaceutical quality departments with FDA audit risk show lowest.
Supply Chain Analysis
Electronics manufacturing services in Germany, Switzerland, and the Czech Republic hold contract assembly capacity for precision instrumentation. Supply chains draw from Japanese platinum wire refiners, Taiwanese microprocessor foundries, and German precision machining clusters. Single-source vulnerability concentrates in ITS-90 primary standard reference materials, where only three national metrology institutes maintain certified production. Distribution runs through authorized calibration service networks that bundle equipment sales with traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical quality departments as facility consolidation concentrates procurement authority among fewer metrology managers with expanded geographic scope.
For Market Incumbents: Insulate aftermarket revenue streams by embedding predictive maintenance algorithms that lock in multi-year service contracts. Deepen backward integration into platinum sensor manufacturing to offset commodity volatility threatening margin stability. Certification investment in CDSCO-accredited facilities positions defensively against Indian generic manufacturers upgrading for export access. For New Entrants and Emerging Players: India's cryogenic calibration gap presents the most penetrable white-space target, with METI-funded hydrogen liquefaction projects requiring capabilities below -196°C that incumbent suppliers currently underserve. Wireless audit trail architectures offer a go-to-market angle for cloud-native calibration platforms targeting multi-site pharmaceutical operations. For Investors and Strategic Acquirers: Capital is best deployed toward precision sensor specialists with captive reference-grade manufacturing and established DAkkS accreditation pathways. Long-term viability hinges on software-enabled service revenue conversion rather than hardware transactional margins. Watch for CDSCO enforcement acceleration as the inflection signal indicating replacement cycle compression among Indian generic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Calibration Architecture Launch | Automated drift detection satisfies EMA GMP Annex 15 documentation intensity for Swiss biologics facilities. |
| Backward Integration into Platinum Sensors | In-house reference-grade wire production insulates margins from commodity swings affecting RTD-dependent competitors. |
| CDSCO Accreditation Investment | Indian generic manufacturers require export-certification-ready infrastructure as domestic GMP enforcement tightens. |
| Asset-as-a-Service Contracting | Per-calibration fee models convert fixed infrastructure costs to variable expenses for European chemical producers. |
| Cryogenic Capability Expansion | Hydrogen liquefaction projects below -196°C demand specialized temperature reference chains few suppliers currently maintain. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with calibration laboratory managers, pharmaceutical quality directors, and aftermarket service heads; and secondary validation against FDA warning letter databases, DAkkS accreditation registries, and customs trade flows for precision instrumentation. Bottom-up unit demand modeling across dry block, infrared, and contact calibrator categories triangulated against top-down market size estimates from equipment manufacturer revenue disclosures.
Forecast inputs considered technology replacement cycles, regulatory audit intensity across FDA, EMA, and CDSCO jurisdictions, and automotive battery testing expansion. Segmentation dimensions spanned product architecture, connectivity protocol, end-user precision tier, and application documentation requirements. CAGRs were derived from fitted growth curves anchored to observed replacement compression in pharmaceutical facilities and capacity buildout in South Korean battery formation operations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native calibration platforms or Chinese cost leaders would shift outcomes beyond modeled ranges. Quarterly review of CDSCO enforcement actions, METI hydrogen project funding allocations, and EMA audit calendar density is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
India Hydrological and Meteorological Equipment Market
Measuring Instruments
Global Process Instrumentation Market
Measuring Instruments
Global Data Acquisition (DAQ) System Market
Measuring Instruments
Network Diagnostic Tools Market
Measuring Instruments
Handheld Wind Anemometer Market
Measuring Instruments
Ultraviolet Data Logger Market
Measuring Instruments
Americas 3D Metrology Market
Measuring Instruments
Data Loggers Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
Monitoring Tools Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
North America Scientific Instruments Market
Measuring Instruments
Borescope Inspection Camera Market
Measuring Instruments
Global Dissolved Oxygen Meters and Controllers Market
Measuring Instruments
Digital Refrigeration Gauge Market