
 TDS Meter Market | 2026-2036
TDS Meter Market Size, Share, and Industry Trends Forecast 2026-2036
TDS Meter Market Outlook
Aquaculture is expanding as a TDS meter end-use vertical as shrimp farms and recirculating aquaculture systems adopt continuous salinity monitoring. Hanna Instruments leverages its Mediterranean manufacturing base to sustain European supply continuity. Thermo Fisher Scientific anchors North American laboratory demand through ISO 17025-certified calibration services. Myron L Company dominates handheld conductivity instrumentation for field technicians across agricultural irrigation districts.
A TDS meter measures total dissolved solids in aqueous solutions via electrical conductivity correlation, typically expressed in parts per million with temperature compensation between zero and fifty degrees Celsius. The device serves industrial water purification, environmental compliance, and food safety verification by quantifying ionic contamination. Handheld and portable segments lead volume shipments due to low capital requirements and minimal training demands. Online installations capture premium margins through SCADA integration and real-time alarm functionality for municipal treatment infrastructure.
EPA effluent guidelines and ISO 7888 conductivity standards shape product certification requirements for manufacturers seeking municipal procurement eligibility. India's BIS and China's MEE enforce parallel national calibration protocols that fragment test method harmonization. Stakeholders must monitor evolving PFAS monitoring mandates that expand TDS measurement scope into emerging contaminant matrices.
Market Dynamics
The transition from analog electrochemical sensors to solid-state digital conductivity modules is compressing calibration cycles and reshaping procurement criteria for municipal water authorities. This hardware shift favors manufacturers with captive semiconductor fabrication capabilities.
Growth Catalysts
- EPA effluent guideline tightening:US municipal treatment plants face expanded discharge monitoring requirements, mandating continuous TDS logging for permit compliance.
- Semiconductor ultrapure water specifications:Fabrication facilities in Taiwan and South Korea now require sub-ppb ionic contamination detection, driving high-precision meter upgrades.
- Recirculating aquaculture system expansion:Shrimp farms across Southeast Asia deploy continuous salinity monitoring to optimize growth rates and reduce mortality.
Market Restraints
- Sensor electrode platinum volatility:Precious metal cost swings in South African mining output directly impact conductivity cell manufacturing economics.
- Calibration standard supply concentration:Certified reference material production clusters in Germany and Japan, creating single-source vulnerability for traceable calibration chains.
- Optical TDS sensing substitution:UV-Vis spectroscopy approaches for organic carbon detection are capturing budget share in pharmaceutical quality control labs.
Strategic Opportunities
- India BIS mandatory certification expansion:The Bureau of Indian Standards is extending TDS meter compliance requirements to commercial food service equipment, opening a new equipment class.
- LoRaWAN-enabled remote monitoring:Low-power wide-area network integration allows agricultural irrigation districts to deploy distributed sensor grids without fiber infrastructure.
- PFAS co-monitoring protocol development:Emerging contaminant detection mandates are expanding TDS measurement scope into precursor ion tracking for regulatory defensibility.
Industry Challenges
- ISO 17025 calibration technician scarcity:Accredited laboratory capacity constraints are extending turnaround times for certified meter validation.
- Legacy SCADA protocol fragmentation:Municipal infrastructure operators face integration complexity bridging Modbus, Profibus, and emerging OPC-UA connectivity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TDS Meter Market |
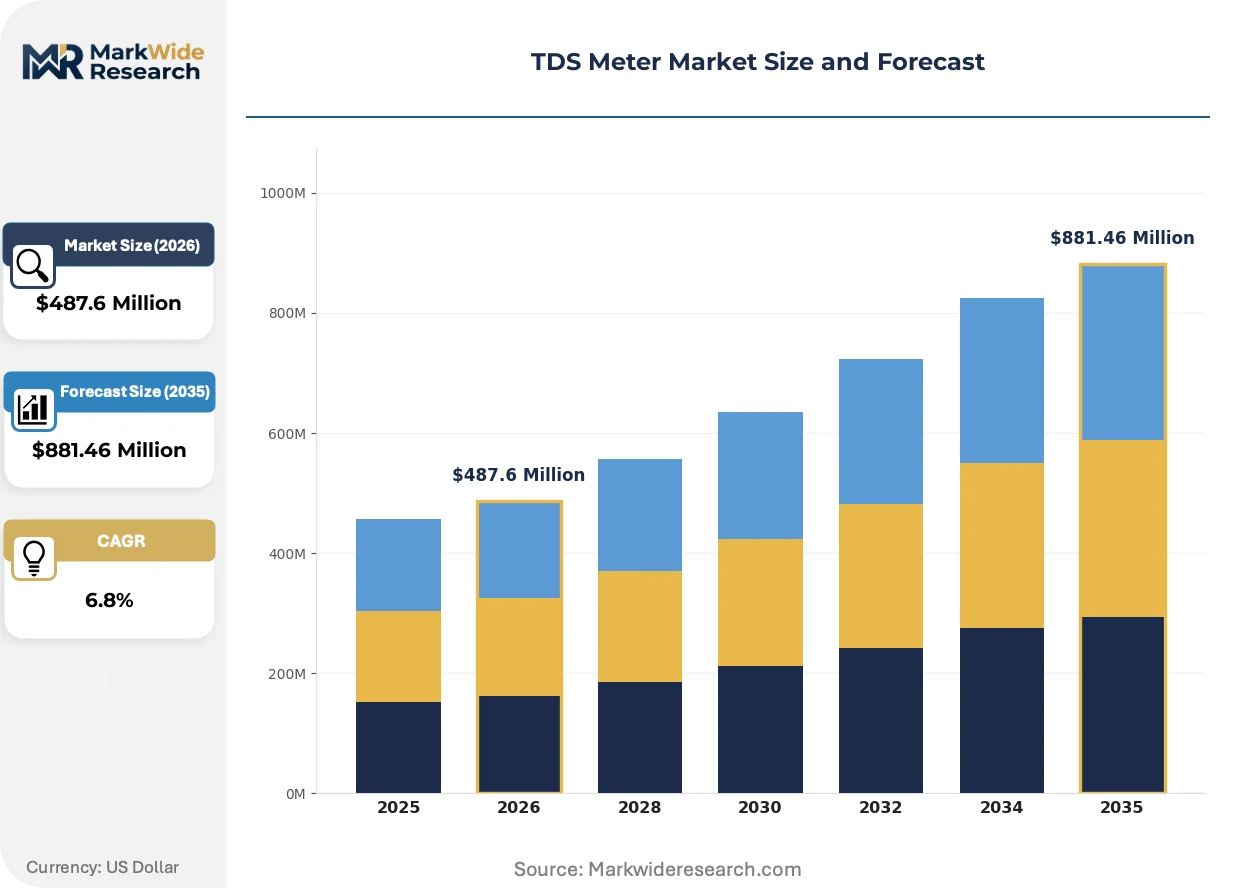
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Bench Top, Online, Portable Application: Water Quality Testing, Aquaculture, Hydroponics, Environmental Monitoring End User: Laboratories, Residential, Water Treatment Plants, Agriculture Distribution Channel: Online Retail, Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Hanna Instruments, OMEGA Engineering, Milwaukee Instruments, Hach, Apera Instruments, Thermo Fisher Scientific, Myron L Company, HM Digital, Eutech Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TDS Meter Market Strategic Shifts
Four-layer ceramic conductivity cell architecture is replacing traditional two-electrode designs, eliminating polarization errors in high-ionic-strength samples. This materials evolution is cascading through laboratory, industrial, and portable product tiers.
Solid-state ion-selective field-effect transistor arrays are rewriting accuracy benchmarks for low-conductivity measurements below one microsiemens per centimeter. Semiconductor fabs in Taiwan and South Korea are specifying these sensors for ultrapure water loops, compressing the viable performance gap between laboratory and process-grade instrumentation. The technology is rewriting supplier qualification criteria for tier-one chip manufacturers.
China's MEE is enforcing parallel national calibration protocols alongside ISO 7888, creating dual-certification requirements for imported equipment. This regulatory friction is forcing multinational manufacturers to establish domestic metrology partnerships or risk exclusion from state-owned utility procurement. The policy divergence most impacts handheld meter suppliers serving both export and domestic Chinese markets.
Equipment-as-a-service models are displacing capital purchase cycles in North American municipal water districts, unbundling hardware from calibration and data management subscriptions. Channel intermediaries face margin compression as manufacturers establish direct fleet management relationships with large utility authorities. The shift is most visible in California and Texas, where consolidation among water agencies is creating anchor tenants for multi-year service contracts.
TDS Meter Market Segmentation
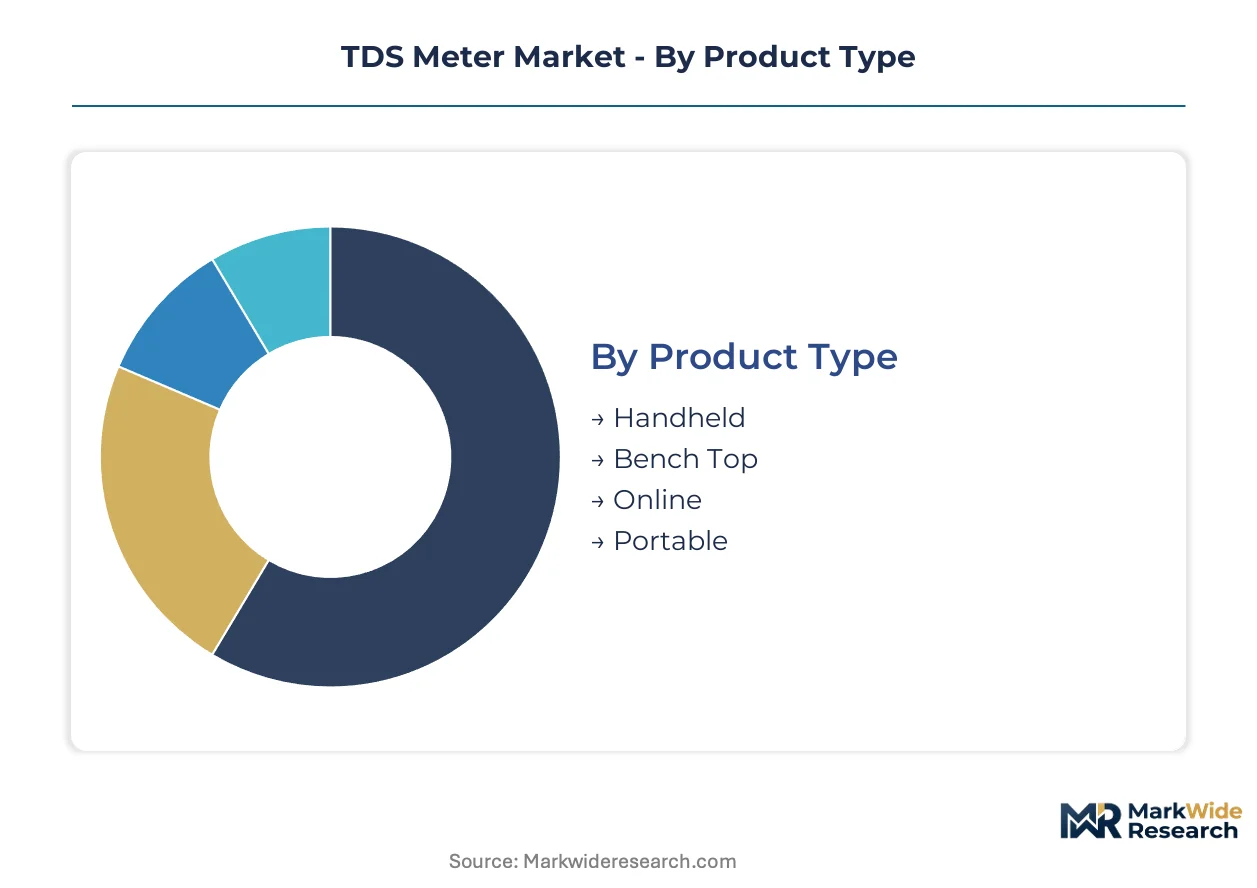
TDS meter procurement patterns diverge sharply across use contexts, with calibration protocols, connectivity requirements, and price sensitivity creating distinct product-tier boundaries. Upgrade cycles vary from annual replacement in field agriculture to decade-long depreciation in municipal infrastructure.
Product Type:
Replacement timelines compress as solid-state digital modules displace electrochemical cells, shortening amortization windows for high-precision applications.
- Handheld:Battery-operated units with temperature-compensated conductivity cells dominate agricultural irrigation districts and field environmental compliance. Demand clusters in India's agricultural belt where extension services distribute units to groundwater monitoring stations.
- Bench Top:Laboratory-grade instruments with four-electrode measurement cells and automated calibration routines serve ISO 17025-accredited facilities. Universities and third-party testing labs in Germany drive specification tightening for traceable uncertainty budgets.
- Online:Continuous monitoring installations integrate with SCADA networks through Modbus or OPC-UA protocols. Municipal treatment plants across China's industrial corridor cities specify these for effluent discharge compliance.
- Portable:Ruggedized cases with shock-resistant electrodes target environmental emergency response teams and mobile aquaculture technicians. Shrimp farms across Vietnam and Indonesia favor these for pond-to-pond salinity mapping.
Handheld meters sit at the top of the volume ranking, with online installations climbing the fastest as SCADA integration becomes mandatory for permit compliance.
Application:
End-use requirements fragment across precision thresholds, with semiconductor-grade specifications at one extreme and agricultural adequacy at the other.
- Water Quality Testing:Municipal utilities and bottled water facilities require traceable calibration chains to EPA or ISO 7888 standards. Taiwan's semiconductor fabs impose sub-ppb detection limits that reshape supplier qualification criteria.
- Aquaculture:Continuous salinity monitoring in recirculating systems demands drift-resistant electrodes capable of biofouling resistance. Southeast Asian shrimp farms are standardizing on four-electrode designs to eliminate polarization errors in brackish water.
- Hydroponics:Nutrient solution management in controlled-environment agriculture favors handheld units with direct nutrient concentration readouts. Commercial greenhouse operators in the Netherlands integrate these with climate control automation.
- Environmental Monitoring:Field-deployable instruments for surface water and groundwater surveillance emphasize battery longevity and data logging capacity. China's MEE enforcement campaigns are expanding procurement for river basin monitoring networks.
Water quality testing commands the largest revenue base, though aquaculture applications are expanding most quickly as intensive farming spreads across coastal zones.
End User:
Procurement authority concentrates differently across customer types, with centralized tender processes governing municipal purchases versus dispersed individual decisions in residential segments.
- Laboratories:Research and quality control facilities demand NIST-traceable calibration certificates and multi-parameter capability. Thermo Fisher Scientific anchors this segment through service contracts bundling hardware with accredited validation.
- Residential:Point-of-use testing for drinking water safety drives demand for sub-$50 pen-style meters with automatic temperature compensation. India's BIS certification expansion is filtering uncertified imports from e-commerce channels.
- Water Treatment Plants:Continuous monitoring infrastructure requires redundant sensor arrays with automated cleaning cycles. German utilities lead specification development for four-layer ceramic cell architectures.
- Agriculture:Irrigation district managers and individual farmers prioritize durability and intuitive operation over laboratory precision. California's Central Valley Water District deploys LoRaWAN-enabled distributed grids for real-time salinity mapping.
Agriculture generates the highest unit volumes, while laboratories sustain premium pricing through calibration service attachment.
Distribution Channel:
Channel economics shift as manufacturers bypass intermediaries for large utility contracts, compressing distributor margins in municipal segments.
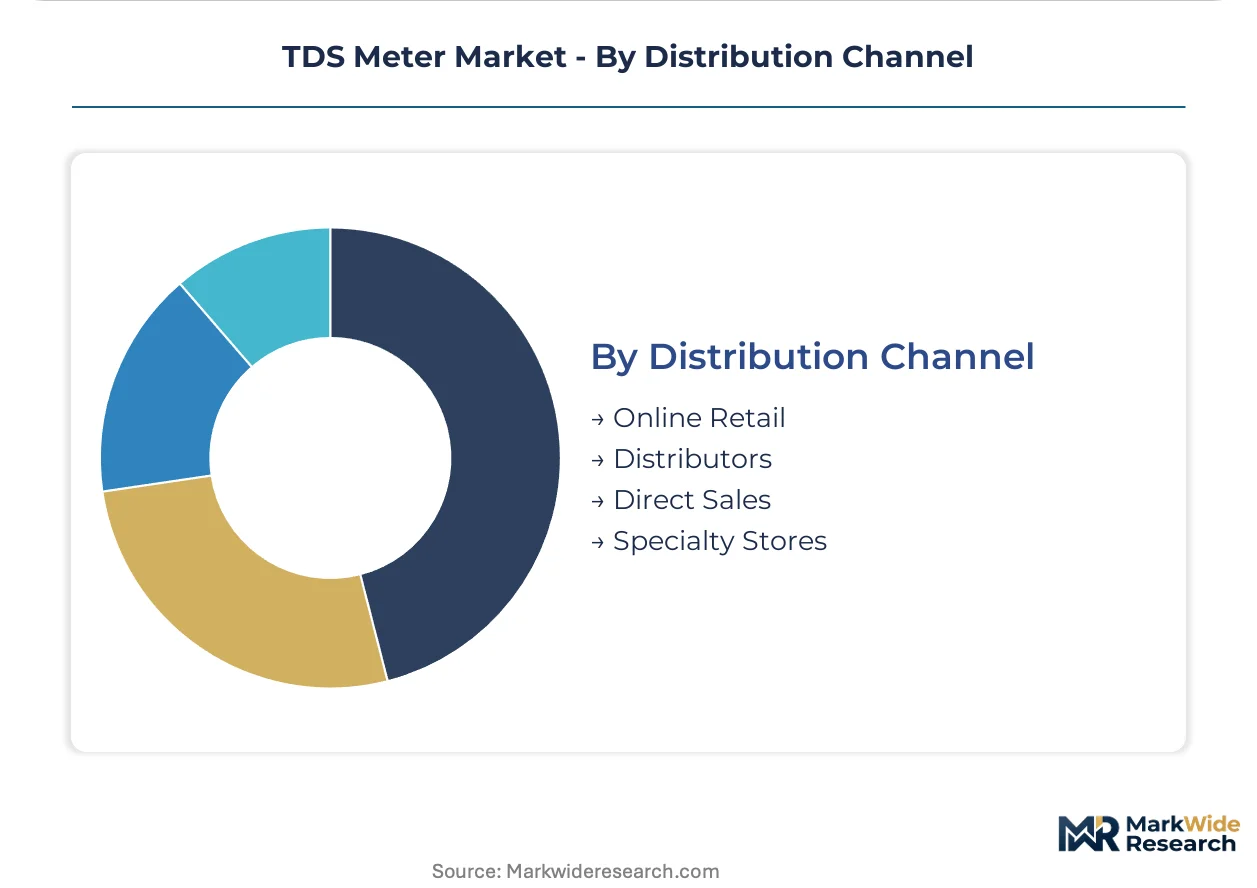
- Online Retail:E-commerce platforms dominate residential and small commercial procurement, with price transparency intensifying competition among unbranded imports. Amazon and Alibaba aggregate demand across fragmented geographies.
- Distributors:Industrial supply houses with local calibration capabilities serve maintenance-repair-operations procurement in manufacturing. Hanna Instruments leverages Mediterranean distribution hubs for European supply continuity.
- Direct Sales:Equipment-as-a-service models and multi-year fleet management contracts connect manufacturers with consolidated water authorities. California and Texas utilities anchor this channel through agency consolidation.
- Specialty Stores:Aquaculture and hydroponics supply retailers provide application expertise and immediate availability for grower emergencies. Bangkok and Ho Chi Minh City host dense clusters serving Southeast Asian shrimp farming.
Online retail captures the greatest transaction volume, with direct sales channels gaining share fastest as service bundling displaces capital purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial corridor cities concentrate semiconductor fab demand for ultrapure water monitoring. Germany's water treatment infrastructure drives four-layer ceramic cell adoption. India's agricultural belt expands handheld meter distribution through extension services.
United States
EPA effluent guideline tightening mandates continuous TDS logging for municipal discharge permits. California and Texas water agency consolidation is creating anchor tenants for multi-year equipment-as-a-service contracts. Semiconductor fabs in Arizona and Oregon specify sub-ppb ionic contamination detection thresholds.
Germany
Utilities lead specification development for four-layer ceramic cell architectures in continuous monitoring infrastructure. ISO 7888 conductivity standards and parallel national calibration protocols shape product certification requirements. Water treatment plants across Bavaria and North Rhine-Westphalia are scaling procurement to meet tightening effluent standards.
China
MEE enforcement campaigns are expanding procurement for river basin monitoring networks alongside dual-certification requirements for imported equipment. Semiconductor fabrication facilities in Shanghai and Shenzhen require ultrapure water monitoring specifications. State-owned utility procurement is forcing multinational manufacturers to establish domestic metrology partnerships.
India
BIS mandatory certification expansion is filtering uncertified imports from e-commerce channels and extending compliance requirements to commercial food service equipment. Agricultural extension services distribute handheld units to groundwater monitoring stations across Maharashtra and Gujarat. Shrimp farms in coastal Andhra Pradesh and Tamil Nadu deploy continuous salinity monitoring.
South Korea
Semiconductor fabs in Gyeonggi Province specify solid-state ion-selective field-effect transistor arrays for ultrapure water loops below one microsiemens per centimeter. METI-aligned quality protocols compress the performance gap between laboratory and process-grade instrumentation. Busan-Ulsan industrial complexes anchor high-precision meter upgrade demand.
TDS Meter Market Competitive Environment
Equipment-as-a-service bundling dominates the current landscape as manufacturers displace capital purchase cycles with calibration and data management subscriptions. The vendor base separates into three tiers: multinational laboratory specialists with accredited service networks, regional manufacturers with Mediterranean or Asian production bases, and price-competitive handheld suppliers serving agricultural and residential segments. Strategic archetypes include captive semiconductor fabrication capability holders, LoRaWAN-enabled distributed grid deployers, and ISO 17025-certified calibration service bundlers. Geographic expansion through domestic metrology partnerships and portfolio diversification into PFAS co-monitoring protocols represent the dominant competitive vectors.
Among Mediterranean-based manufacturers, Hanna Instruments exemplifies regional production continuity strategies. Thermo Fisher Scientific occupies a position within the laboratory-grade instrumentation tier through service contract bundling. Myron L Company represents the field-portable specialist archetype serving agricultural irrigation districts. These three anchors illustrate how competitive positioning fragments across precision thresholds, geographic proximity to demand clusters, and calibration service attachment models.
| Leading Market Players |
|---|
| Hanna Instruments |
| OMEGA Engineering |
| Milwaukee Instruments |
| Hach |
| Apera Instruments |
| Thermo Fisher Scientific |
| Myron L Company |
| HM Digital |
| Eutech Instruments |
| Others |
Value Chain & Pricing Dynamics
Laboratory-grade ISO 17025 certification against agricultural field adequacy creates a bifurcation that manifests in both three-tier pricing stratification and supply chain sourcing patterns. Premium bench-top instruments draw platinum electrode supply from South African mining output while economy handheld units source commodity conductivity cells from Chinese contract manufacturers.
Pricing Analysis
Platinum electrode volatility in South African mining output passes directly into conductivity cell manufacturing economics, compressing margins for high-precision laboratory tiers. Three-tier pricing structure across premium, standard, and economy levels separates NIST-traceable calibration bundles from unbranded pen-style imports. Pricing pressure stems from optical TDS sensing substitution in pharmaceutical quality control labs. Agricultural irrigation districts exhibit highest price sensitivity while semiconductor fabs accept premium positioning for sub-ppb detection capability.
Supply Chain Analysis
Single-source vulnerability sits with certified reference material production clustering in Germany and Japan, creating traceable calibration chain fragility. Manufacturing concentrates in China for economy handheld assembly, Romania for Hanna Instruments' Mediterranean hub production, and the United States for Thermo Fisher Scientific's laboratory-grade instrumentation. Critical inputs span platinum group metals for electrodes, four-layer ceramic substrates for cell architecture, and solid-state ion-selective field-effect transistor wafers. Tariff exposure on Chinese-manufactured sensor modules threatens cost structures for mid-tier suppliers. Distribution runs through industrial supply houses with local calibration capabilities serving maintenance-repair-operations procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunity concentrates between India's BIS mandatory certification expansion and China's MEE dual-certification requirements, where compliance cost differentials favor domestic metrology partnerships over import-dependent positioning.
For Market Incumbents: To counter optical TDS sensing substitution in pharmaceutical quality control, defend laboratory-grade positioning through ISO 17025 calibration service bundling and backward integration into four-layer ceramic cell manufacturing. Anchor municipal fleet management relationships in California and Texas water agency consolidation zones to lock out equipment-as-a-service competitors. For New Entrants and Emerging Players: Solid-state ion-selective field-effect transistor arrays offer a technology-first wedge into Taiwan and South Korea semiconductor fab qualification programs currently dominated by legacy electrochemical suppliers. Target Vietnam and Indonesia shrimp farm portable meter segments through aquaculture supply retailer partnerships in Bangkok and Ho Chi Minh City distribution clusters. For Investors and Strategic Acquirers: Asymmetric upside sits with captive semiconductor fabrication capability holders who can compress the laboratory-process instrumentation performance gap. Five-to-ten year viability favors manufacturers with LoRaWAN-enabled distributed grid deployment experience in agricultural irrigation districts. Watch India's BIS enforcement campaign intensity as inflection signal for commercial food service equipment certification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Metrology Partnership Formation | MEE dual-certification requirements in China force multinational manufacturers toward local calibration capability. |
| Equipment-as-a-Service Model Launch | California and Texas water agency consolidation creates anchor tenants for multi-year fleet management contracts. |
| Four-Layer Ceramic Cell Manufacturing Scale-Up | German utility specification leadership drives replacement of traditional two-electrode polarization-prone designs. |
| LoRaWAN-Enabled Sensor Grid Deployment | Agricultural irrigation districts in India's Maharashtra and Gujarat seek fiber-independent distributed monitoring. |
| PFAS Co-Monitoring Protocol Development | EPA emerging contaminant mandates expand TDS measurement scope into precursor ion tracking for regulatory defensibility. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with municipal water utility procurement officers, semiconductor fab facilities engineers, agricultural irrigation district managers, aquaculture system operators, and ISO 17025 calibration laboratory directors alongside secondary validation through EPA effluent guideline filings, BIS certification registries, MEE enforcement campaign disclosures, and semiconductor industry ultrapure water specification documents. Bottom-up sensor shipment aggregation and top-down end-use demand estimation provided cross-verification.
Segment-weighting across product type, application, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from install-base replacement cycle analysis, regulatory mandate timing, and technology substitution elasticity modeling. Industry-specific forecast inputs included platinum electrode price volatility indices and semiconductor fab capital expenditure pipelines for ultrapure water infrastructure.
The model holds under stable regulatory enforcement intensity and continuous SCADA integration mandates; deviation in MEE certification timeline acceleration or EPA effluent guideline relaxation would shift replacement cycle assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
India Hydrological and Meteorological Equipment Market
Measuring Instruments
Network Diagnostic Tools Market
Measuring Instruments
Temperature Calibrator Market
Measuring Instruments
Ultraviolet Data Logger Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
Americas 3D Metrology Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
Monitoring Tools Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
Communication Test Equipment (CTE) Market
Measuring Instruments
Global Data Acquisition (DAQ) System Market
Measuring Instruments
Global Dissolved Oxygen Meters and Controllers Market
Measuring Instruments
Global Dimensional Metrology Software Market
Measuring Instruments
Global Instrument Calibrator Market
Measuring Instruments
Global Container Weighing Systems Market