
 Global Instrument Calibrator Market | 2026-2036
Global Instrument Calibrator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Instrument Calibrator Market Foresight
Germany is reshaping competitive dynamics in precision instrumentation through expanded metrology institute capacity and industrial automation adoption. Fluke Corporation leverages its distributed service network to sustain aftermarket calibration revenue across North American manufacturing plants. Keysight Technologies anchors high-frequency electrical calibration through specialized signal integrity laboratories. Tektronix differentiates via integrated software-defined calibration platforms for oscilloscope verification workflows.
An instrument calibrator is a traceable reference device that generates or measures known physical quantities—pressure, temperature, electrical signals, or flow rates—with documented uncertainty budgets typically expressed in parts per million, enabling verification of industrial sensor accuracy against national metrology standards. Its primary purpose is ensuring measurement reliability in quality-critical processes where drift or deviation incurs regulatory non-compliance or production defects. Multifunction calibrators command margin concentration due to consolidated procurement preferences among calibration laboratories seeking reduced equipment counts. Wireless technology segments are displacing tethered configurations in field-based oilfield equipment servicing where mobility constraints dominate. Portable digital units dominate manufacturing plant deployments where line-side verification minimizes production interruption.
FDA 21 CFR Part 11 and EPA Method 21 protocols mandate documented calibration traceability for environmental monitoring and pharmaceutical manufacturing equipment, compelling end users to maintain accredited calibration intervals. ISO 17025 frameworks govern laboratory competence requirements across European and Asia-Pacific jurisdictions, creating barrier-to-entry effects for uncertified equipment suppliers. NIST-traceable standards in the United States and China GB calibration regulations further fragment approval pathways. Stakeholders must monitor evolving cybersecurity requirements for networked calibrator interfaces as industrial IoT architectures expand audit surface areas.
Market Dynamics
ISO 17025 accreditation tightening is forcing calibration laboratories worldwide to replace legacy analog equipment with traceable digital systems, compressing replacement cycles and elevating vendor qualification barriers.
Growth Catalysts
- Semiconductor fabrication expansion:South Korean and Taiwanese chip foundries require precision thermal and electrical calibration for EUV lithography equipment, driving demand for multifunction calibrators with sub-ppm uncertainty budgets.
- EPA Method 21 enforcement:US environmental monitoring mandates documented calibration traceability for fugitive emission detection systems, compelling petrochemical operators to maintain accredited calibration intervals.
- Wireless connectivity integration:Bluetooth-enabled calibrators are displacing tethered configurations in field-based oilfield equipment servicing where mobility constraints dominate technician workflows.
Market Restraints
- Metrology-grade sensor input costs:Precision reference sensors using platinum resistance thermometers and quartz pressure elements face supply concentration from Japanese and German component specialists.
- China GB calibration fragmentation:Divergent national standards from SAMR create approval pathway complexity for multinational vendors seeking unified product platforms.
- Software-enabled calibration substitution:Virtual reference models using AI-driven drift prediction threaten traditional hardware calibrator demand in stable process environments.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO enforcement of data integrity requirements creates first-time calibration infrastructure demand among domestic generic drug producers.
- Industrial IoT audit surface expansion:Cybersecurity requirements for networked calibrator interfaces create service attach opportunities around secure firmware validation.
- Cloud-based calibration management:SaaS platforms integrating asset tracking with automated scheduling are displacing paper-based systems in mid-sized contract laboratories.
Industry Challenges
- ISO 17025 assessor scarcity:Qualified metrology auditors are concentrating in German and US accreditation bodies, extending certification timelines for Asian laboratories.
- Legacy system integration friction:Digital calibrators with modern communication protocols face compatibility gaps with decades-old distributed control systems in established process plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Instrument Calibrator Market |
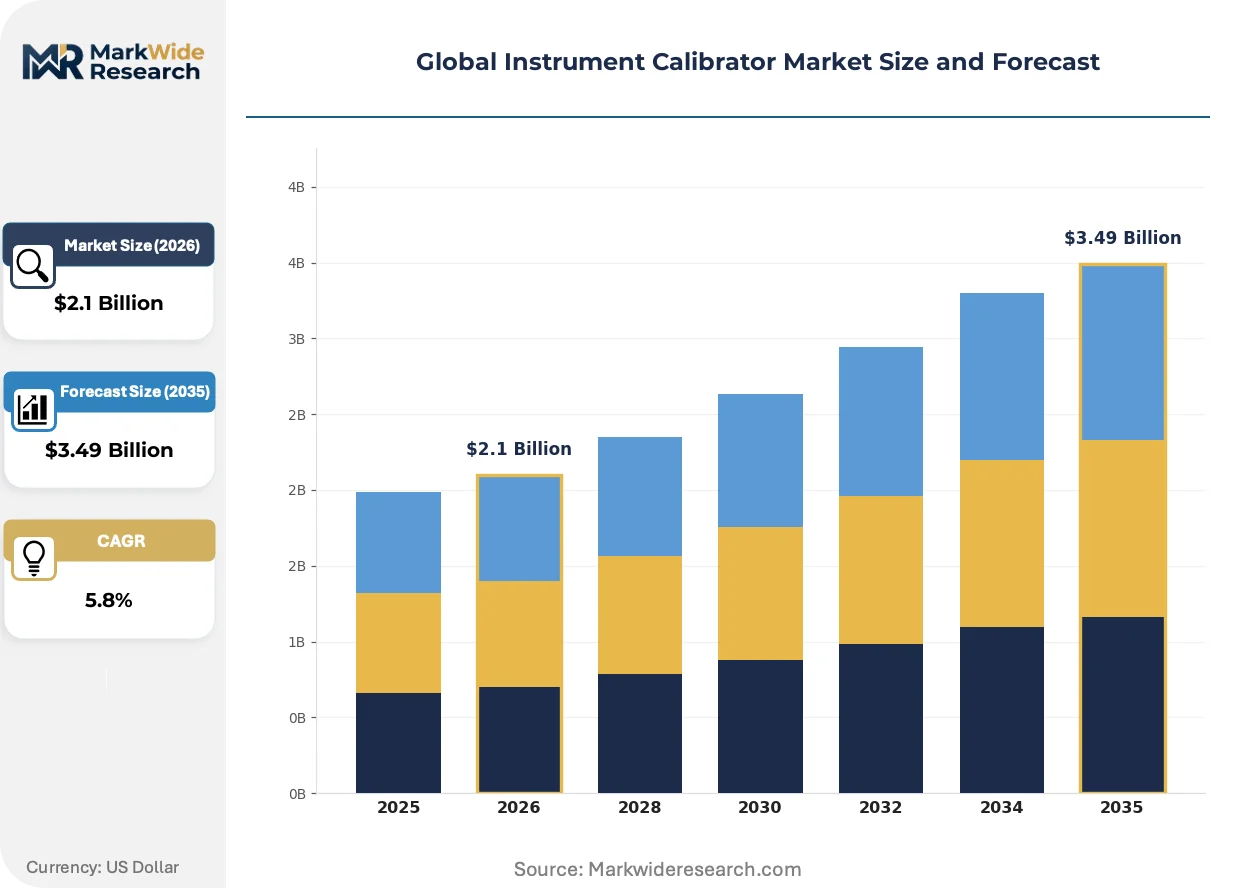
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Calibrators, Temperature Calibrators, Electrical Calibrators, Multifunction Calibrators, Flow Calibrators Technology: Analog, Digital, Portable, Wireless, USB Interface Application: Process Industry, Power Generation, Aerospace Testing, Oilfield Equipment, Telecommunication Systems End User: Manufacturing Plants, Calibration Laboratories, Research Facilities, Quality Control Departments |
| Companies Covered | Fluke Corporation, Keysight Technologies, Tektronix, Rohde & Schwarz, Hexagon AB, Agilent Technologies, National Instruments, Endress+Hauser, Mitutoyo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Instrument Calibrator Market Shifts & Advancements
Calibration workflows are converging around connected, software-defined platforms that compress verification cycles and embed compliance documentation directly into measurement operations.
Multifunction calibrators with embedded automation routines are digitizing oscilloscope verification workflows in aerospace testing facilities. Tektronix and Keysight customers in US defense contracting are adopting these platforms to reduce technician intervention during repetitive validation sequences. The technology is digitizing calibration throughput by collapsing multi-instrument procedures into single-device executions.
EU F-Gas Regulation phase-down mandates are forcing refrigeration and HVAC equipment manufacturers to adopt precision pressure-temperature calibration for alternative refrigerant systems. German automotive climate control suppliers are investing in mobile calibration rigs to verify sensor accuracy across R-1234yf and CO2-based architectures. The policy is accelerating demand for portable digital units with refrigerant-specific measurement modes.
Buyer concentration among consolidated calibration service providers is compressing vendor negotiation leverage. Large third-party laboratories in the United States are unbundling equipment procurement from aftermarket service contracts, forcing manufacturers to compete on per-verification pricing rather than bundled lifecycle value. This pattern is most visible in pharmaceutical manufacturing clusters around Boston and Research Triangle Park.
Global Instrument Calibrator Market Segmentation
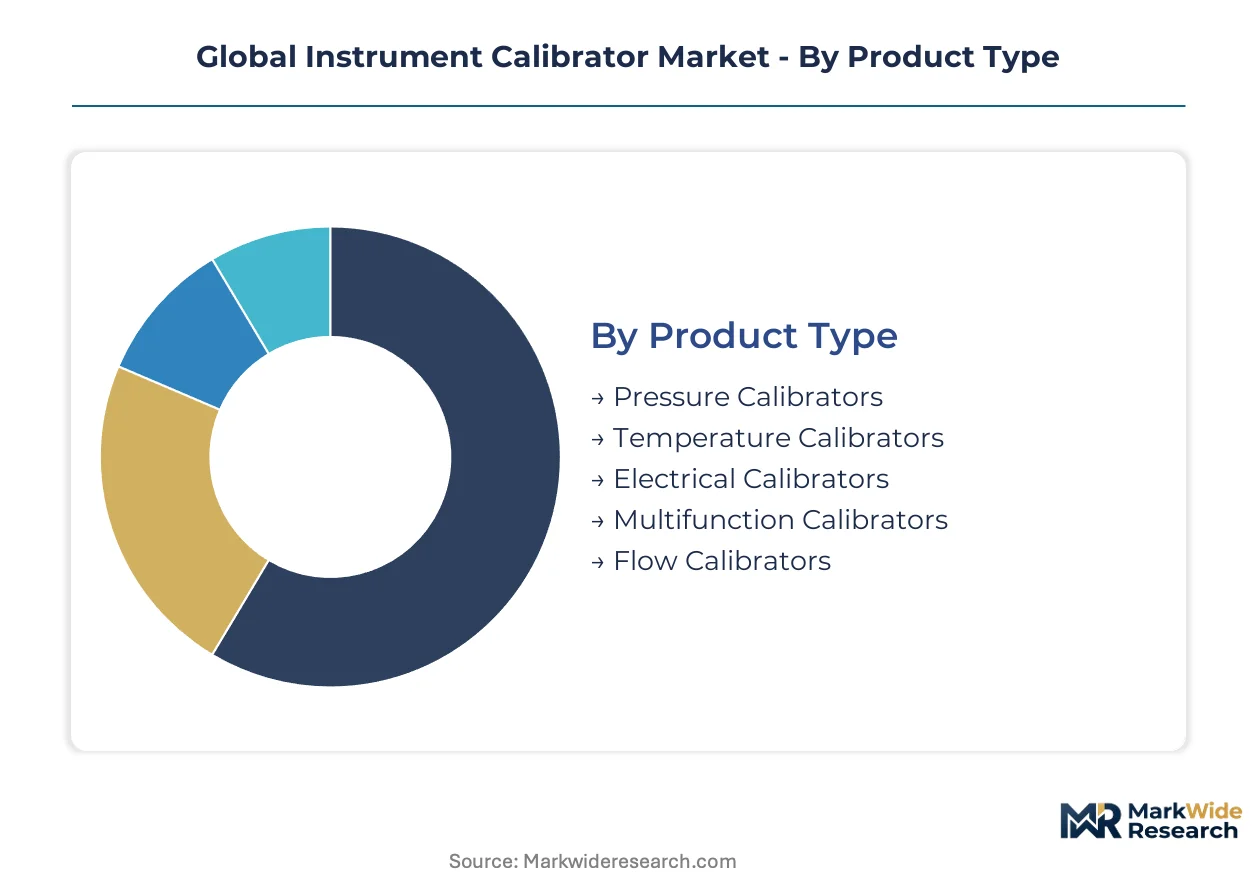
Segmentation in the instrument calibrator market reveals divergent replacement dynamics across product architectures, with digital platforms cycling faster than legacy analog systems due to ISO 17025 compliance pressure. Understanding these turnover patterns enables vendors to align R&D pipelines with the segments driving both volume stability and margin expansion.
Product Type:
Pressure calibrators and temperature calibrators exhibit the longest replacement cycles among reference-grade equipment, while multifunction and electrical variants turn over more rapidly as laboratories consolidate instrument counts.
- Multifunction Calibrators:Consolidated procurement preferences among ISO 17025-accredited laboratories are elevating demand for single-platform devices capable of pressure, temperature, and electrical signal generation. South Korean semiconductor fabrication facilities require sub-ppm uncertainty budgets for EUV lithography equipment verification, compressing replacement intervals to maintain traceability chains.
- Electrical Calibrators:High-frequency signal integrity laboratories anchor specialized demand for precision voltage, current, and resistance reference generation. Aerospace testing facilities in the United States are digitizing oscilloscope verification workflows through automated calibration routines, accelerating equipment refresh rates.
- Pressure Calibrators:Quartz pressure element reference standards face supply concentration from Japanese component specialists, extending procurement lead times for metrology-grade units.
- Temperature Calibrators:Platinum resistance thermometer-based systems dominate pharmaceutical manufacturing where FDA 21 CFR Part 11 mandates documented thermal sensor traceability.
- Flow Calibrators:Petrochemical operators under EPA Method 21 enforcement maintain accredited intervals for fugitive emission detection system verification.
Multifunction calibrators anchor the volume base while electrical calibrators gain share at the steepest rate among discrete product categories.
Technology:
Cost tier differentiation separates premium wireless platforms from economy analog configurations, with mid-market digital units capturing manufacturing plant deployments.
- Digital:Embedded automation routines and documented uncertainty budgets enable ISO 17025 compliance with reduced technician intervention. German automotive climate control suppliers are investing in mobile calibration rigs for R-1234yf refrigerant system verification.
- Wireless:Bluetooth-enabled architectures displace tethered configurations in field-based oilfield equipment servicing where technician mobility constraints dominate workflow efficiency.
- Portable:Line-side verification capabilities minimize production interruption in manufacturing plant deployments across Taiwan's electronics assembly clusters.
- Analog:Legacy distributed control system compatibility gaps in established process plants extend replacement timelines despite accreditation tightening.
- USB Interface:Direct PC connectivity supports cloud-based calibration management platforms displacing paper-based systems in mid-sized contract laboratories.
Digital technology commands the revenue concentration while wireless configurations expand most quickly among connectivity architectures.
Application:
Application segmentation reflects divergent certification requirements, with regulated industries mandating shorter calibration intervals than non-critical manufacturing environments.
- Process Industry:Continuous production environments require redundant calibration infrastructure to prevent unplanned shutdowns from measurement drift. German chemical manufacturers are expanding calibration protocols under tightened EU F-Gas Regulation phase-down mandates for alternative refrigerant systems.
- Aerospace Testing:Defense contracting workflows demand software-defined platforms with automated documentation for audit trail compliance. US facilities are collapsing multi-instrument procedures into single-device executions to compress verification cycles.
- Power Generation:Grid stability monitoring depends on synchronized phasor measurement unit calibration with national metrology institute traceability.
- Oilfield Equipment:Remote site accessibility drives demand for battery-operated portable units with extended temperature operating ranges.
- Telecommunication Systems:5G infrastructure deployment requires high-frequency electrical calibration for signal integrity verification.
Process industry applications generate the installed base volume while aerospace testing drives the steepest technology refresh trajectory.
End User:
Customer type segmentation reveals procurement pattern divergence between captive in-house calibration and outsourced third-party laboratory services.
- Calibration Laboratories:Third-party service providers are unbundling equipment procurement from aftermarket service contracts, forcing manufacturers toward per-verification pricing models. Large US laboratories around Boston pharmaceutical clusters are driving this pattern.
- Manufacturing Plants:Line-side verification requirements prioritize portable digital units with rapid stabilization times to minimize production interruption.
- Quality Control Departments:Data integrity enforcement under CDSCO regulations in India is creating first-time calibration infrastructure demand among domestic generic drug producers.
- Research Facilities:National metrology institutes anchor reference-grade procurement with multi-year capital planning cycles and specialized uncertainty budget requirements.
Calibration laboratories dominate procurement volume while quality control departments represent the steepest expansion trajectory among end-user categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and German component specialists concentrate supply for precision reference sensors, while end-use demand disperses across semiconductor fabrication clusters and pharmaceutical manufacturing hubs in multiple jurisdictions.
United States
Defense contracting workflows and pharmaceutical manufacturing anchor calibration demand. FDA 21 CFR Part 11 mandates documented traceability for thermal sensors in drug production equipment. Boston-area pharmaceutical clusters and Research Triangle Park facilities drive third-party laboratory procurement.
Germany
Automotive climate control suppliers and chemical manufacturers require mobile calibration rigs for alternative refrigerant systems. EU F-Gas Regulation phase-down mandates precision pressure-temperature verification. Industrial automation adoption across Bavaria and Baden-Württemberg reshapes metrology institute capacity expansion.
China
Semiconductor fabrication and power generation infrastructure drive electrical and thermal calibration procurement. SAMR-administered GB calibration regulations fragment approval pathways for multinational vendors. Yangtze River Delta manufacturing clusters face extended certification timelines due to assessor scarcity.
South Korea
EUV lithography equipment verification demands multifunction calibrators with sub-ppm uncertainty budgets. MFDS enforcement of data integrity requirements extends to pharmaceutical manufacturing calibration protocols. Seoul Capital Area chip foundries compress replacement intervals to maintain traceability chains.
India
Domestic generic drug producers build first-time calibration infrastructure under CDSCO data integrity enforcement. Quality control departments in Maharashtra and Gujarat pharmaceutical clusters represent steepest expansion trajectory among end-user categories. National metrology institute procurement follows multi-year capital planning cycles.
Global Instrument Calibrator Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in precision reference sensor supply. The vendor base stratifies between consolidated multinational instrument manufacturers and fragmented regional service providers. Three archetypes dominate: full-stack calibration platform vendors, specialized reference sensor suppliers, and third-party laboratory service consolidators. Competitive moves center on unbundling equipment procurement from service contracts and embedding automation routines to compress verification cycles.
Among US-based platform vendors, Fluke Corporation and Keysight Technologies exemplify the integrated calibration platform archetype. Tektronix occupies a position within the software-defined instrumentation tier. These companies represent varying approaches to sustaining aftermarket revenue across North American manufacturing plants and aerospace testing facilities.
| Leading Market Players |
|---|
| Fluke Corporation |
| Keysight Technologies |
| Tektronix |
| Rohde & Schwarz |
| Hexagon AB |
| Agilent Technologies |
| National Instruments |
| Endress+Hauser |
| Mitutoyo |
| Others |
Supply & Pricing Matrix
Undercapacity in Japanese quartz pressure element production is elevating procurement lead times for metrology-grade reference sensors, compressing vendor margins and forcing tiered pricing stratification across certification levels.
Pricing Analysis
ISO 17025 dictates the pricing tier structure across the instrument calibrator market, separating NIST-traceable premium units from standard digital configurations and economy analog alternatives. Price differentiation hinges on certification grade and after-sales service bundling, with accredited laboratories least sensitive to cost. Cost compression in the economy analog tier is intensifying because third-party laboratories are unbundling equipment procurement from service contracts.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for multinational calibration platform vendors. Component sourcing draws from Japan for quartz pressure elements, Germany for platinum resistance thermometers, and South Korea for precision electrical references. Single-source vulnerability concentrates in Japanese sensor specialists. Distribution runs through authorized service networks and direct OEM channels to calibration laboratories and manufacturing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The instrument calibrator market is entering a cyclical recovery phase as semiconductor fabrication capital expenditure rebounds and EUV lithography equipment deployment accelerates replacement demand.
For Market Incumbents: Harden ISO 17025 certification depth across Asian accreditation bodies to extend assessor scarcity into competitive moats. Deepen backward integration into platinum resistance thermometer production to offset Japanese component concentration. Anchor channel control through captive service networks against third-party laboratory procurement unbundling.
For New Entrants and Emerging Players: Pursue Indian pharmaceutical manufacturing clusters where CDSCO data integrity enforcement creates first-time calibration infrastructure demand. Target quality control departments in Maharashtra and Gujarat with portable digital units priced for domestic generic drug producers. Lead with cloud-based calibration management platforms to displace paper-based systems in mid-sized contract laboratories.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined calibration platforms as automation routines reduce technician labor content. Five-to-ten year viability favors vendors with embedded cybersecurity validation for industrial IoT interfaces. Target acquisition archetypes are regional service consolidators with accredited laboratory footprints. The signal to monitor is EPA Method 21 enforcement intensity affecting petrochemical operator replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Body Partnership | Secures assessor pipeline for ISO 17025 certification timelines in Asian markets. |
| Sensor Component Backward Integration | Reduces dependency on Japanese quartz pressure element supply concentration. |
| Cloud Platform Acquisition | Captures SaaS calibration management displacement of paper-based laboratory systems. |
| Cybersecurity Certification Program | Addresses industrial IoT audit surface expansion for networked calibrator interfaces. |
| Regional Service Network Expansion | Supports line-side verification demand in Taiwan electronics assembly clusters. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with calibration laboratory directors, metrology institute procurement officers, pharmaceutical quality control managers, and semiconductor facility maintenance engineers; and secondary validation against NIST technical publications, FDA 21 CFR Part 11 guidance documents, ISO 17025 accreditation records, and customs trade data for precision instrument flows. Bottom-up equipment shipment analysis and top-down end-use demand estimation were triangulated to constrain variance.
Forecast inputs considered product type, technology architecture, application vertical, and end-user procurement pattern across the projection horizon. CAGRs were derived from replacement cycle analysis and accreditation-driven compliance pressure modeling. Semiconductor fabrication capital expenditure trajectories and EPA enforcement intensity served as demand-side inflection indicators.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or environmental regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding ISO 17025 assessor availability and component supply lead times. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Global Container Weighing Systems Market
Measuring Instruments
Network Diagnostic Tools Market
Measuring Instruments
3D Metrology Market
Measuring Instruments
Communication Test and Measurement (Ctandm) Market
Measuring Instruments
Digital Refrigeration Gauge Market
Measuring Instruments
Communication Test Equipment (CTE) Market
Measuring Instruments
Ultraviolet Data Logger Market
Measuring Instruments
Handheld Wind Anemometer Market
Measuring Instruments
Global Data Acquisition (DAQ) System Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
Moisture Meter Market
Measuring Instruments
Global Process Instrumentation Market
Measuring Instruments
Air Velocity Meter Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
Global Dimensional Metrology Software Market