
 Selective Laser Sintering Market | 2026-2036
Selective Laser Sintering Market Size, Share, and Industry Trends Forecast 2026-2036
Selective Laser Sintering Market Intelligence
Software-defined build preparation and remote monitoring subscriptions is rebalancing how equipment vendors capture lifetime value from installed SLS systems. EOS GmbH Electro Optical Systems leverages its open-materials platform to sustain deep printer-material lock-in with industrial buyers. HP Inc. anchors high-throughput polymer production through its Multi Jet Fusion ecosystem, while Farsoon Technologies competes aggressively on system cost to extend its position in price-sensitive Asian manufacturing hubs.
Selective laser sintering fuses powdered thermoplastics, metals, or ceramics using a computer-guided CO2 or fiber laser, typically achieving layer thicknesses between 0.08 mm and 0.15 mm and producing parts with tensile strengths approaching injection-molded equivalents. The technology serves aerospace, automotive, and medical device sectors seeking geometrically complex components without tooling investment. Metal powder bed fusion systems command premium pricing and pull the highest margins, while plastic SLS platforms dominate unit shipments through prototyping and short-run production demand. Functional parts applications are outpacing pure prototyping as end users validate flight-ready and implant-grade components for regulatory submission.
FDA 21 CFR Part 820 quality system regulations govern medical device SLS manufacturing in the United States, while EMA and EU MDR frameworks impose biocompatibility and traceability standards across European healthcare applications. China's NMPA and GB standards for additive manufacturing medical devices are tightening material certification requirements, compressing market access timelines for non-domestic suppliers. Stakeholders must monitor evolving powder recyclability mandates and emissions thresholds that will reshape equipment design priorities and operational cost structures.
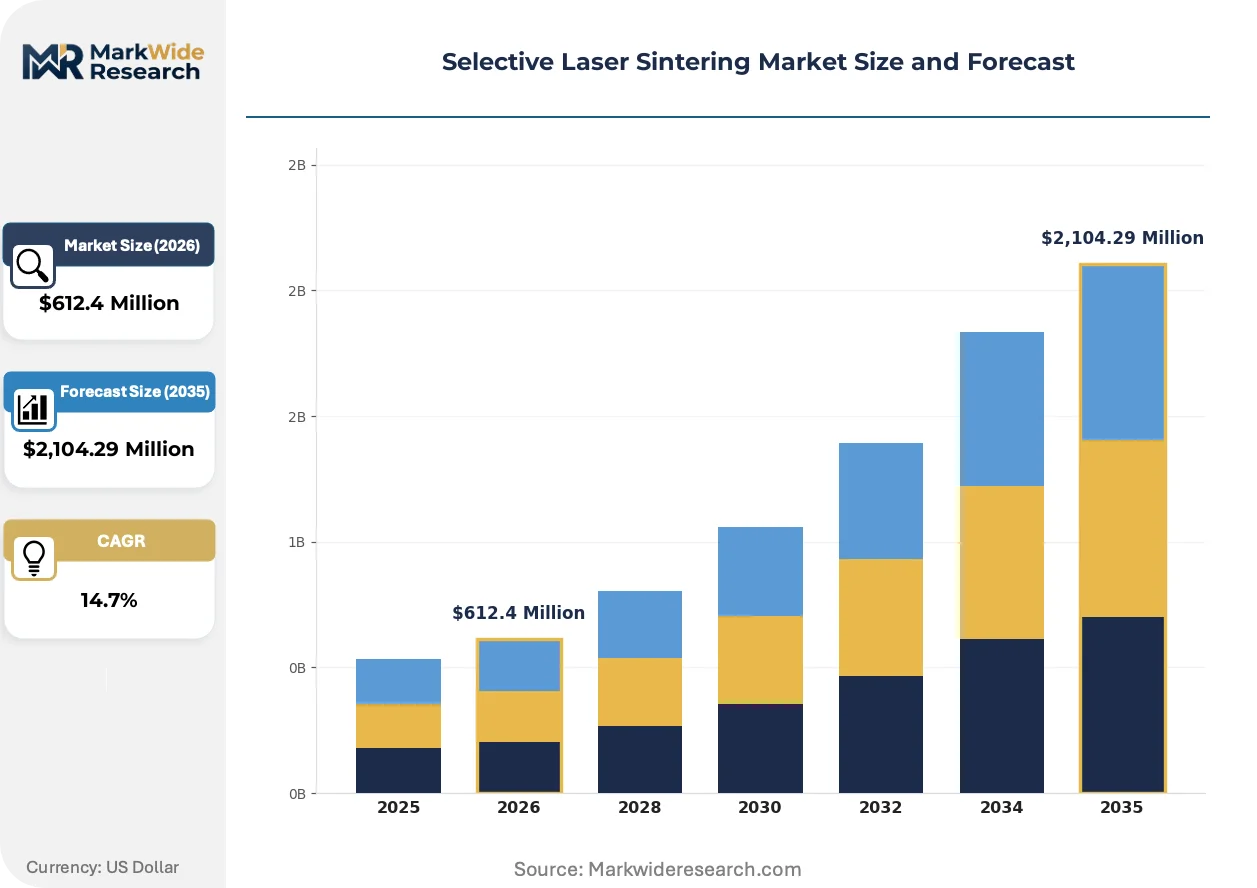
Market Dynamics
Software-defined build preparation and remote monitoring subscriptions are rebalancing how equipment vendors capture lifetime value from installed SLS systems, shifting revenue from hardware sales toward recurring service architectures.
Growth Catalysts
- FDA 21 CFR Part 820 Pathways:Medical device manufacturers in the United States are validating flight-ready and implant-grade components for regulatory submission, expanding functional parts production beyond prototyping.
- Carbon fiber-reinforced nylons:Aerospace tier-1 suppliers are adopting laser-sintered structural brackets and ducting to reduce tooling investment for low-volume airframe programs.
- German industrial clusters:Precision manufacturing ecosystems around Munich and Stuttgart are scaling polymer and metal powder bed fusion for automotive series production.
Market Restraints
- Metal powder cost volatility:Titanium and nickel superalloy feedstock prices fluctuate with aerospace OEM demand cycles, compressing margins for contract manufacturers.
- European REACH compliance:ECHA substance restrictions on recycled powder streams are tightening material qualification requirements and extending validation timelines.
- Build speed limitations:Layer-wise fusion physics cap throughput for large-format parts, constraining SLS competitiveness against injection molding above ten-thousand-unit runs.
Strategic Opportunities
- China NMPA medical device framework:Domestic certification pathways for additive manufacturing implants are opening access to hospital procurement networks in tier-1 cities.
- On-demand spare parts networks:Automotive aftermarket distributors are piloting distributed SLS cells to eliminate tooling inventory for obsolete components.
- Digital twin convergence:Real-time thermal monitoring and predictive defect detection are integrating with enterprise PLM systems to reduce first-article scrap rates.
Industry Challenges
- Process technician scarcity:Qualified operators capable of parameter optimization for new material grades command premium wages, constraining cell utilization rates.
- Multi-jurisdictional certification timelines:Parallel FDA, EMA, and NMPA submissions for implantable devices extend time-to-revenue by eighteen to thirty-six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Selective Laser Sintering Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,104.29 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Ceramic, Composite End User: Aerospace, Automotive, Healthcare, Consumer Electronics Application: Prototyping, Tooling, Functional Parts, Production Parts Technology: Powder Bed Fusion, Direct Metal Laser Sintering, Selective Laser Melting, Stereolithography |
| Companies Covered | 3D Systems Inc., EOS GmbH Electro Optical Systems, Farsoon Technologies, Prodways Group, Formlabs Inc., HP Inc., Sinterit, SLM Solutions, Renishaw, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Selective Laser Sintering Market Strategic Shifts & Innovations
Multi-laser architectures and in-situ process monitoring are compressing per-part economics while expanding the addressable application set for powder bed fusion technologies.
Multi-laser metal systems are consolidating competitive positioning in aerospace structural applications. Tier-1 suppliers at Boeing and Airbus are qualifying four-laser configurations for titanium bracket production. The technology is consolidating vendor market share around platforms capable of sub-thousand-dollar-per-kilogram fully burdened costs.
EU MDR biocompatibility traceability mandates are reshaping medical device SLS workflows. EMA requirements for powder lot genealogy and post-processing validation are forcing manufacturers to retrofit legacy equipment with automated material tracking. Implant-grade polyetheretherketone and titanium devices face the steepest compliance cost escalation.
After-sales service unbundling is disrupting traditional equipment vendor economics. Aerospace and medical device buyers are negotiating separate maintenance contracts with third-party metrology specialists rather than accepting bundled OEM service agreements. Germany and the United States show the highest penetration of independent calibration and recoater blade replacement networks.
Selective Laser Sintering Market Segmentation
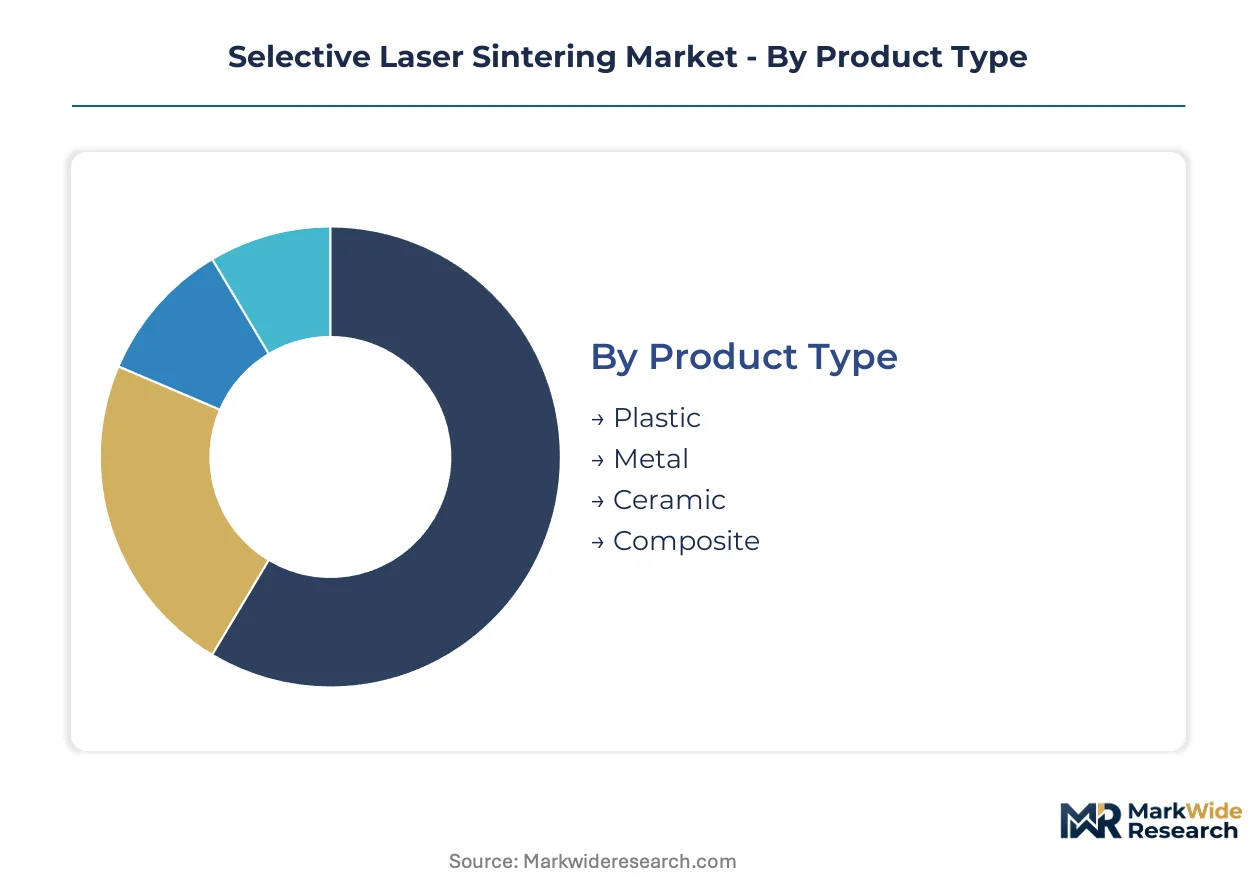
Segmentation in selective laser sintering reveals how material physics, regulatory pathways, and end-use performance requirements partition revenue and margin capture across equipment vendors and service bureaus. Understanding these divides exposes where capital deployment concentrates and where new entrants can displace incumbents.
Product Type:
Plastic systems dominate unit shipments while metal platforms command premium pricing and pull the highest equipment margins.
- Metal:Titanium and nickel superalloy powder bed fusion achieves tensile strengths approaching wrought equivalents for aerospace structural brackets and medical implants. Demand concentrates in Germany, China, and the United States where industrial clusters support precision manufacturing scale-up and FDA, EMA, and NMPA pathways validate flight-ready and implant-grade components.
- Plastic:Nylon and polyamide systems achieve layer thicknesses between 0.08 mm and 0.15 mm for geometrically complex components without tooling investment. Automotive series production and consumer electronics housings drive volume in German precision manufacturing ecosystems around Munich and Stuttgart.
- Ceramic:Oxide and non-oxide ceramic SLS serves high-temperature aerospace applications and biomedical scaffolds requiring biocompatibility traceability under EU MDR frameworks.
- Composite:Carbon fiber-reinforced nylons reduce tooling investment for low-volume airframe programs at Boeing and Airbus tier-1 suppliers.
Today's leader: Metal. Tomorrow's challenger: Composite.
End User:
Application maturity separates validation-heavy sectors from scale-sensitive manufacturing.
- Aerospace:Functional parts production is outpacing pure prototyping as end users validate flight-ready components for regulatory submission. Four-laser configurations are consolidating competitive positioning for titanium bracket production with sub-thousand-dollar-per-kilogram fully burdened costs.
- Healthcare:Implant-grade polyetheretherketone and titanium devices face the steepest compliance cost escalation under EU MDR biocompatibility traceability mandates and FDA 21 CFR Part 820 quality system regulations.
- Automotive:Aftermarket distributors pilot distributed SLS cells to eliminate tooling inventory for obsolete components.
- Consumer Electronics:Short-run production demand for geometrically complex housings concentrates in Asian manufacturing hubs competing aggressively on system cost.
Aerospace captures the premium tier. Healthcare expands most quickly as implant validation timelines compress.
Application:
Revenue architecture shifts from one-time hardware sales toward recurring service architectures as functional parts scale.
- Functional Parts:End users validate flight-ready and implant-grade components for regulatory submission, expanding beyond prototyping into production workflows. Real-time thermal monitoring and predictive defect detection integrate with enterprise PLM systems to reduce first-article scrap rates.
- Prototyping:Plastic SLS platforms dominate unit shipments through geometrically complex component iteration without tooling investment.
- Tooling:Laser-sintered mold inserts and fixtures reduce lead times for automotive series production.
- Production Parts:Layer-wise fusion physics cap throughput for large-format parts, constraining competitiveness against injection molding above ten-thousand-unit runs.
Prototyping holds installed base. Functional Parts gain share fastest as regulatory validation matures.
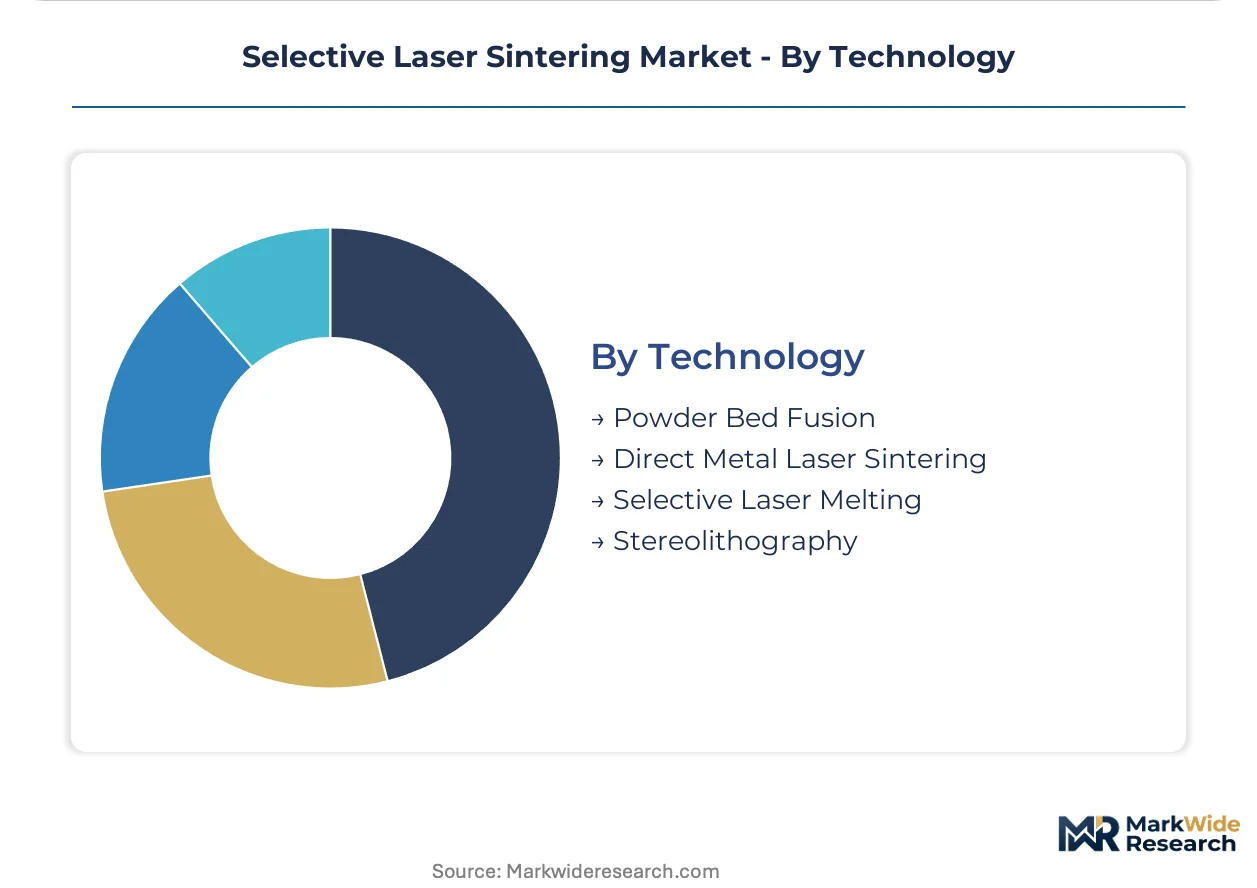
Technology:
Architecture differentiation determines powder recyclability mandates and emissions thresholds that reshape equipment design priorities.
- Powder Bed Fusion:The foundational SLS approach fusing powdered thermoplastics, metals, or ceramics using computer-guided CO2 or fiber lasers. ECHA substance restrictions on recycled powder streams tighten material qualification requirements and extend validation timelines.
- Direct Metal Laser Sintering:Metal-specific variant commanding premium pricing with the highest margins in aerospace structural applications.
- Selective Laser Melting:Full-density metal processing achieving tensile strengths approaching injection-molded equivalents for implant-grade devices.
- Stereolithography:Resin-based additive manufacturing distinct from powder bed approaches, serving prototyping and dental applications with different material certification pathways.
Powder Bed Fusion anchors current revenue. Selective Laser Melting climbs the fastest as medical device certification expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing clusters command premium SLS equipment density, while China's cost-optimized fabricators drive volume expansion through aggressive system pricing. The United States anchors medical device validation workflows, with regulatory pathways shaping regional competitive positioning.
Germany
Automotive series production and aerospace structural brackets sustain powder bed fusion demand across Baden-Württemberg and Bavaria. ECHA REACH substance restrictions tighten recycled powder qualification requirements, extending validation timelines for contract manufacturers. Munich and Stuttgart industrial clusters scale polymer and metal systems for tier-1 suppliers at BMW and Airbus.
United States
Medical device manufacturers validate implant-grade components for FDA 21 CFR Part 820 submission, expanding functional parts production beyond prototyping. FAA certification pathways for flight-ready aerospace components concentrate regulatory expertise in Greater Boston and Pacific Northwest manufacturing hubs. Boeing tier-1 suppliers qualify multi-laser titanium configurations for structural bracket programs.
China
Domestic certification under NMPA medical device frameworks opens hospital procurement networks in tier-1 cities for implantable SLS components. MIIT industrial additive manufacturing policies accelerate standardization of powder bed fusion equipment specifications. Pearl River Delta fabricators compete aggressively on system cost to capture price-sensitive consumer electronics and automotive aftermarket demand.
Japan
Precision medical device manufacturers pursue PMDA approval pathways for polyetheretherketone and titanium implants, compressing validation timelines through METI-supported standardization initiatives. Kanto region industrial clusters integrate SLS tooling with automotive lean production systems. Osaka-based fabricators specialize in ceramic powder bed fusion for high-temperature aerospace applications.
United Kingdom
Aerospace tier-1 suppliers at BAE Systems and Rolls-Royce validate laser-sintered ducting and structural brackets for regulatory submission under EASA frameworks. Midlands manufacturing clusters retrofit legacy equipment with automated material tracking to satisfy EU MDR biocompatibility traceability mandates. London-based service bureaus unbundle after-sales maintenance contracts with third-party metrology specialists.
Selective Laser Sintering Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with equipment vendors capturing lifetime value through software-defined service architectures. The vendor base concentrates around three strategic tiers: open-materials platform providers, high-throughput production ecosystem anchors, and cost-optimized system fabricators. Dominant competitive moves include unbundling after-sales service agreements and expanding multi-laser architecture portfolios.
Within the open-materials tier, EOS GmbH Electro Optical Systems exemplifies deep printer-material lock-in with industrial buyers through platform extensibility. HP Inc. anchors high-throughput polymer production ecosystems, while Farsoon Technologies occupies a position among cost-optimized Asian fabricators competing aggressively on system pricing. These three represent the dominant archetypes shaping competitive dynamics across medical device, aerospace, and automotive end-use segments.
| Leading Market Players |
|---|
| 3D Systems Inc. |
| EOS GmbH Electro Optical Systems |
| Farsoon Technologies |
| Prodways Group |
| Formlabs Inc. |
| HP Inc. |
| Sinterit |
| SLM Solutions |
| Renishaw |
| Others |
Cost & Logistics Intelligence
Captive powder production in Germany and China anchors both supply security and pricing power for tier-1 SLS equipment vendors, locking in margin capture through backward integration into titanium and nylon feedstock while forcing contract manufacturers to absorb spot-market volatility.
Pricing Analysis
Capacity additions in China are reshaping price floors for plastic powder bed fusion systems, compressing hardware margins for European and North American incumbents. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated metal platforms from uncertified prototyping units and refurbished industrial systems. Cost compression in entry-level plastic systems is intensifying because Farsoon Technologies and domestic Chinese fabricators compete aggressively on system cost. Automotive aftermarket distributors show the highest price sensitivity, while aerospace tier-1 suppliers prioritize certification pedigree over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Boeing and Airbus tier-1 suppliers mandate multi-supplier qualification for titanium and nickel superalloy powders, preventing single-source lock-in despite EOS GmbH's platform dominance. Feedstock supply concentrates in Germany, China, and the United States where gas-atomization capacity serves aerospace and medical device qualification pathways. Raw material dependencies rest on sponge titanium from Japan, nickel superalloy master alloys from the United States, and polymer resin feedstock from German chemical clusters. Single-source vulnerability runs through Ukrainian titanium sponge routes disrupted by conflict. Distribution runs through authorized equipment distributors in industrial clusters and direct OEM relationships for high-volume aerospace programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-compliant European powder qualification costs and China's accelerated NMPA certification timelines, rewarding players who can bridge regulatory compliance with cost-optimized production.
For Market Incumbents: To counter HP Inc.'s high-throughput polymer ecosystem expansion, EOS GmbH and SLM Solutions should deepen backward integration into gas-atomized powder production in Germany and the United States, securing captive supply of implant-grade titanium while extending validation timelines for non-integrated competitors. Certification investment in parallel FDA-EMA-NMPA submissions for multi-laser metal platforms remains the critical defensive lever against Asian cost leaders. For New Entrants and Emerging Players: Enter via ceramic powder bed fusion for high-temperature aerospace applications, a segment where oxide and non-oxide SLS faces limited specialized competition from incumbent metal and plastic platforms. Japan's METI-supported standardization initiatives and Osaka-based industrial clusters offer the most penetrable geography for niche ceramic qualification. A go-to-market angle targeting PMDA approval for dental and orthopedic scaffolds bypasses crowded titanium implant pathways. For Investors and Strategic Acquirers: Roll-up economics work for independent service bureaus with automated material tracking capabilities because EU MDR biocompatibility traceability mandates are forcing hospital procurement networks to consolidate supplier relationships around certified fabricators. Long-term viability hinges on software-defined recurring revenue capture from remote monitoring subscriptions rather than hardware shipment cyclicality. The signal to watch is unbundling of after-sales maintenance contracts with third-party metrology specialists, which indicates margin pressure on traditional OEM service architectures and creates acquisition opportunities for independent calibration networks.| Strategic Initiative | Industry Significance |
|---|---|
| Open-Materials Platform Expansion | EOS GmbH's platform extensibility sustains deep printer-material lock-in with industrial buyers across German automotive clusters. |
| Multi-Laser Architecture Portfolio | Four-laser configurations consolidate competitive positioning for Boeing and Airbus tier-1 titanium bracket production programs. |
| Backward Integration into Powder Production | Captive gas-atomization capacity insulates margin capture from titanium and nickel superalloy feedstock price volatility cycles. |
| Regulatory Parallel Submission Investment | Simultaneous FDA-EMA-NMPA pathways compress time-to-revenue for implant-grade polyetheretherketone and titanium devices. |
| Software-Defined Service Unbundling | Remote monitoring subscriptions rebalance lifetime value capture from installed SLS systems toward recurring revenue architectures. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with additive manufacturing equipment engineers, hospital procurement managers, aerospace tier-1 supplier quality directors, and contract manufacturer operations heads with secondary validation against FDA 510(k) filings, EMA medical device registrations, NMPA approval databases, and customs trade data for powder bed fusion equipment imports. Bottom-up sizing of installed base and utilization rates triangulated against top-down aerospace and medical device spending forecasts.
Segment-weighting approaches distributed revenue and volume across metal, plastic, ceramic, and composite product types, then further disaggregated by aerospace, healthcare, automotive, and consumer electronics end-use segments throughout the projection horizon. CAGRs were derived from regression analysis of historical equipment shipment data and forward projections of functional parts validation timelines. Industry-specific forecast inputs included powder recyclability mandate compliance costs and multi-jurisdictional certification timeline compression rates.
Inputs from equipment vendor shipment disclosures and regulatory filing databases were available through the study window; gaps in real-time utilization rates for installed SLS cells introduce uncertainty bands around service revenue projections. Forecasts reflect assumptions regarding FDA 21 CFR Part 820 pathway acceleration and ECHA REACH substance restriction enforcement timelines. Deviation in NMPA domestic certification prioritization for additive manufacturing implants would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Global 3D Printing in Medical Applications Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
US Additive Manufacturing Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Hybrid Additive Manufacturing Machine Market
3D Printing Technology
3D Printer Market