
 Global 3D Virtual Platform Market | 2026-2036
Global 3D Virtual Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Virtual Platform Market Foresight
The EU AI Act is shifting procurement criteria for European manufacturing firms evaluating immersive simulation vendors. PraxiLabs leverages its specialization in educational virtual laboratories to anchor demand across Middle Eastern universities. Spektra Systems LLC competes through hybrid deployment architectures that serve government agencies with strict data sovereignty requirements. Samaaro differentiates via event-centric 3D environments designed for enterprise marketing applications.
A 3D virtual platform constitutes a software infrastructure that renders persistent, navigable digital environments through real-time polygonal mesh processing, spatial audio encoding, and multi-user concurrency protocols. These systems enable industrial teams to manipulate digital twins, prototype physical assets, and conduct remote spatial collaboration without geographic constraints. Cloud-based deployment leads solution type distribution due to elastic compute scaling for concurrent immersive sessions, while simulation software captures concentrated R&D investment from automotive and aerospace engineering divisions. Training systems represent the fastest-growing use case as energy and healthcare sectors replace physical facility time with hazard-free virtual rehearsal environments.
The U.S. FCC governs spectrum allocation for untethered VR hardware that accesses platform content, while OSHA standards increasingly reference virtual environment safety protocols for industrial training substitution. Japan's METI promotes cross-sector digital twin adoption through standardized data interoperability frameworks that directly expand platform addressable markets. Stakeholders must monitor whether emerging EU CSRD disclosure rules will mandate virtual collaboration metrics as auditable sustainability credentials.
Market Dynamics
Cloud-native rendering pipelines are compressing deployment timelines for industrial 3D environments, forcing legacy on-premise vendors to rearchitect their compute stacks or cede automotive and aerospace accounts to elastic infrastructure providers.
Growth Catalysts
- EU AI Act compliance mandates:European manufacturing procurement teams now require algorithmic transparency documentation from immersive simulation vendors, accelerating platform standardization across German automotive design studios.
- Digital twin convergence:Industrial engineering divisions in Japan are fusing real-time sensor feeds with persistent virtual environments through METI-backed interoperability frameworks, expanding addressable use cases beyond static visualization.
- Healthcare hazard substitution:Energy sector operators and hospital systems are replacing physical facility training hours with consequence-free virtual rehearsal protocols, eliminating travel and equipment downtime costs.
Market Restraints
- GPU supply concentration:Foundry capacity for high-performance graphics processors remains bottlenecked at Taiwan Semiconductor Manufacturing, exposing platform vendors to allocation volatility and extended lead times.
- GDPR data residency friction:Cross-border immersive session hosting triggers complex territorial processing restrictions, forcing redundant infrastructure deployment and inflating operational overhead for multi-national deployments.
- Untethered hardware dependency:FCC spectrum allocation decisions for millimeter-wave VR headsets directly constrain wireless fidelity in industrial training environments, limiting mobility in large-scale simulation facilities.
Strategic Opportunities
- Middle Eastern educational infrastructure:Saudi and UAE government scholarship programs are funding virtual laboratory expansion at national universities, creating concentrated demand for STEM-focused 3D platforms.
- CSRD disclosure preparation:The EU Corporate Sustainability Reporting Directive may classify virtual collaboration metrics as auditable sustainability credentials, positioning platform vendors as compliance infrastructure providers.
- Edge-cloud hybrid architectures:Government agencies with strict data sovereignty requirements are driving demand for split-render systems that process sensitive geometry locally while streaming lightweight viewport data.
Industry Challenges
- Spatial computing talent scarcity:Real-time engine optimization and polygonal mesh streaming expertise remains concentrated among gaming industry veterans, forcing platform vendors to compete for limited specialized labor pools.
- Multi-standard certification complexity:Simultaneous ISO 27001, SOC 2 Type II, and sector-specific healthcare or defense accreditation timelines stretch 14-18 months, delaying enterprise sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Virtual Platform Market |
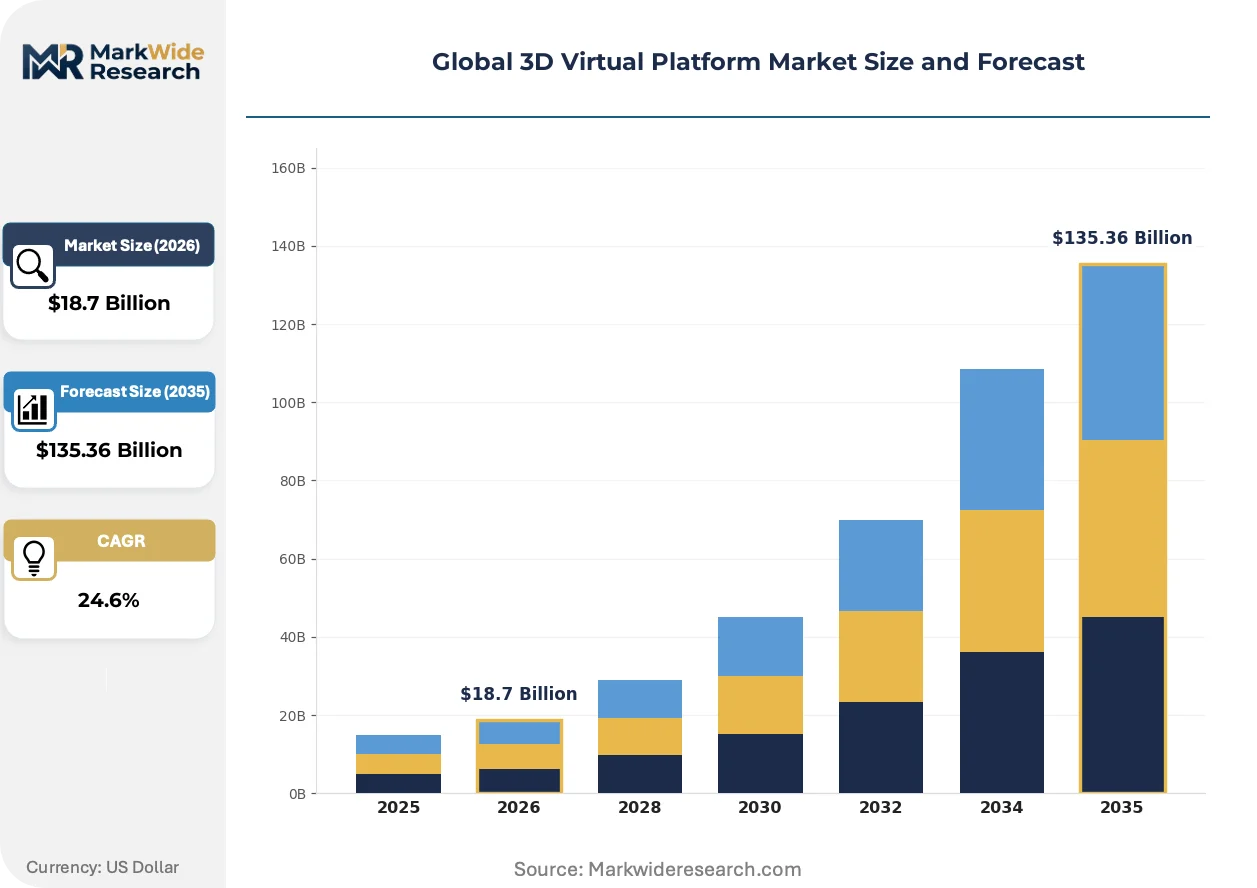
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Collaboration Platforms, Simulation Software, Training Systems, Visualization Tools, Product Design Suites Use Case: Remote Conferencing, Virtual Training, Digital Twin Modeling, Marketing & Engagement, Urban Planning End User: Manufacturing Firms, Architecture Firms, Entertainment Studios, Educational Institutions, Government Agencies |
| Companies Covered | PraxiLabs, Spektra Systems LLC, Samaaro, PandaMR, MootUp, 3D Bear, Outreal XR, Holo-SDK, Wevr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Virtual Platform Market Shifts & Advancements
Neural rendering techniques and physics-encoded generative models are collapsing the cost curve for photorealistic environment creation, redistributing competitive advantage from asset production scale toward real-time orchestration capabilities.
Gaussian splatting is overtaking traditional polygonal rasterization for static scene reconstruction in architectural visualization and heritage preservation workflows. Property developers in Singapore and Dubai are adopting light-field capture pipelines to generate explorable digital twins from drone photogrammetry within hours rather than weeks. This compression is overtaking conventional 3D modeling service contracts and forcing established visualization studios to retrain technical artists or exit the segment.
Japan's METI has issued standardized data interoperability guidelines that mandate open asset formats for cross-sector digital twin exchange. Industrial consortia in Osaka and Nagoya are now requiring FBX and USDZ compatibility certifications from platform vendors as table-stakes for consortium membership. Automotive suppliers without certified interoperability are losing bid eligibility for METI-subsidized smart factory transformation grants.
Energy sector buyers are unbundling perpetual licensing in favor of consumption-metered immersive training subscriptions tied to actual seat-hours rather than named user counts. North American utilities and European grid operators are piloting this model through specialized channel partners that aggregate demand across non-competing regional monopolies. The shift is most visible in German and Texan markets where deregulated energy trading desks compete aggressively on operational training sophistication.
Global 3D Virtual Platform Market Segmentation
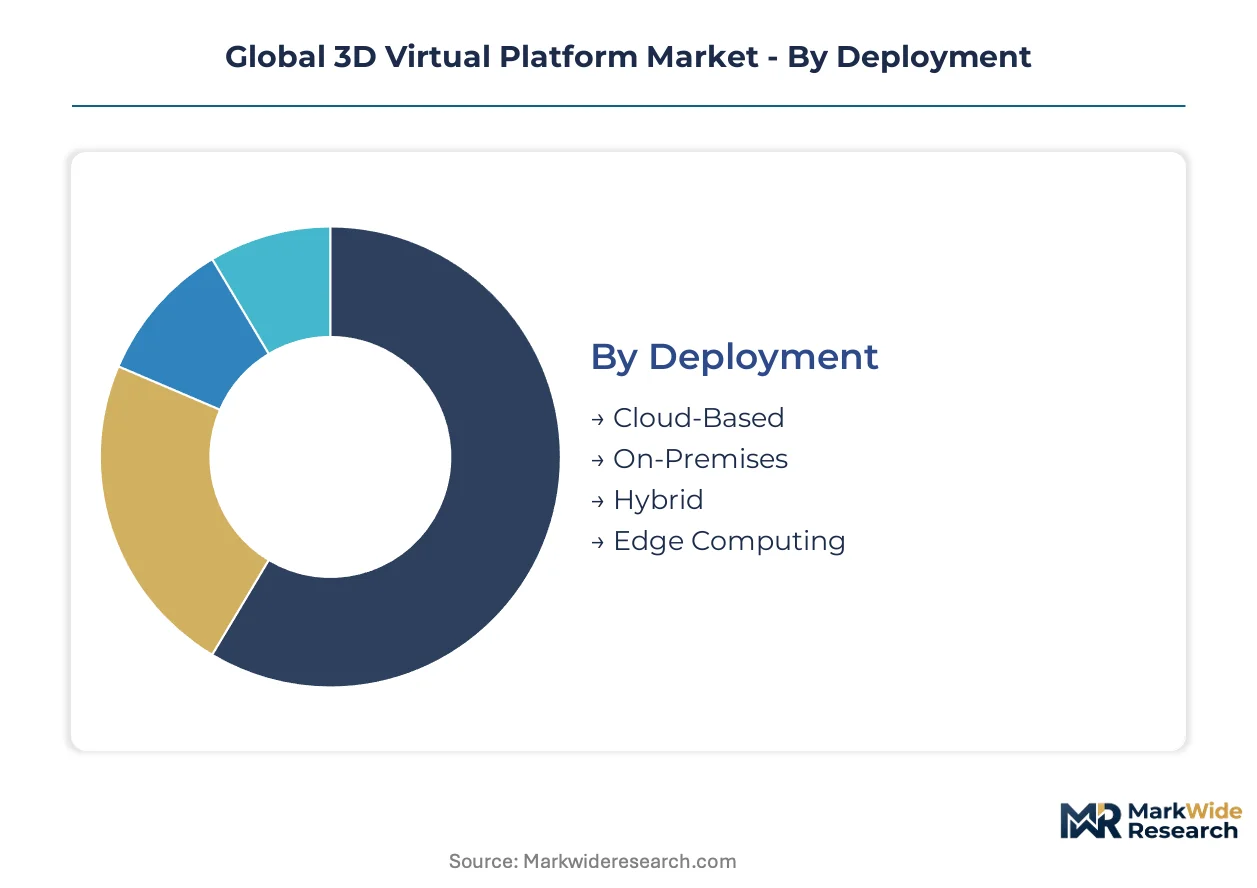
Segmentation reveals how 3D virtual platform architectures map to distinct procurement patterns across industrial, creative, and public sector buyers. Deployment topology, solution functionality, and end-user operational requirements collectively determine vendor selection criteria and pricing structures.
Deployment:
Elastic infrastructure scaling capabilities differentiate commercial-grade platforms from legacy installations.
- Cloud-Based:Multi-tenant architectures with GPU cluster orchestration support concurrent immersive sessions exceeding 500 simultaneous users. German automotive design studios and Japanese industrial consortia prioritize this model for distributed team coordination across supplier networks.
- On-Premises:Air-gapped server deployments process sensitive geometry within facility firewalls. Defense contractors and classified research facilities mandate this topology despite higher capital expenditure and 18-24 month refresh cycles.
- Hybrid:Split-render configurations stream lightweight viewport data from cloud edge nodes while retaining sensitive asset processing on local workstations. Government agencies with strict data sovereignty requirements drive specialized demand for this architecture.
- Edge Computing:Micro-datacenter deployments within 50 kilometers of industrial sites minimize motion-to-photon latency below 20 milliseconds for precision assembly simulations.
Mature deployment sits with Cloud-Based configurations. Newer deployment is concentrated in Edge Computing for latency-critical manufacturing applications.
Solution Type:
Functional specialization determines R&D allocation and partnership ecosystems across platform vendors.
- Simulation Software:Physics engines integrating finite element analysis with real-time mesh deformation enable automotive crash testing and aerospace stress modeling without physical prototypes. Boeing and Airbus engineering divisions anchor concentrated procurement in this segment.
- Training Systems:Hazard rehearsal environments replicate oil rig blowouts, surgical complications, and electrical substation failures with consequence-free repetition. Energy sector operators in Texas and North Sea jurisdictions are expanding seat-hour subscriptions fastest.
- Collaboration Platforms:Spatial audio encoding and persistent world state synchronization support multi-user design reviews across distributed engineering teams.
- Visualization Tools:Real-time ray-traced rendering pipelines serve architectural client presentations and property marketing workflows.
- Product Design Suites:Integrated CAD-to-VR workflows enable direct manipulation of parametric models within immersive environments.
Established revenue concentration favors Simulation Software. Steepest expansion trajectory belongs to Training Systems as physical facility substitution accelerates.
Use Case:
Operational integration depth separates experimental pilots from production-critical deployments.
- Digital Twin Modeling:Persistent virtual environments fused with live sensor feeds from physical assets enable predictive maintenance and operational optimization. METI-backed interoperability frameworks in Japan are standardizing data exchange protocols for cross-sector deployment.
- Virtual Training:Competency certification programs replace physical facility hours with tracked immersive rehearsal protocols. Healthcare systems in Germany and the United States measure outcomes through reduced medical error rates and accelerated onboarding timelines.
- Remote Conferencing:Spatial presence alternatives to video calls support design reviews and stakeholder alignment sessions.
- Marketing & Engagement:Branded virtual environments host product launches and customer experience demonstrations.
- Urban Planning:City-scale digital twins simulate traffic flows, emergency response routing, and infrastructure development impacts.
Production-critical adoption clusters in Digital Twin Modeling. Experimental pilot activity concentrates in Urban Planning as municipal budgets allocate to smart city initiatives.
End User:
Procurement sophistication and compliance requirements fragment vendor go-to-market strategies.
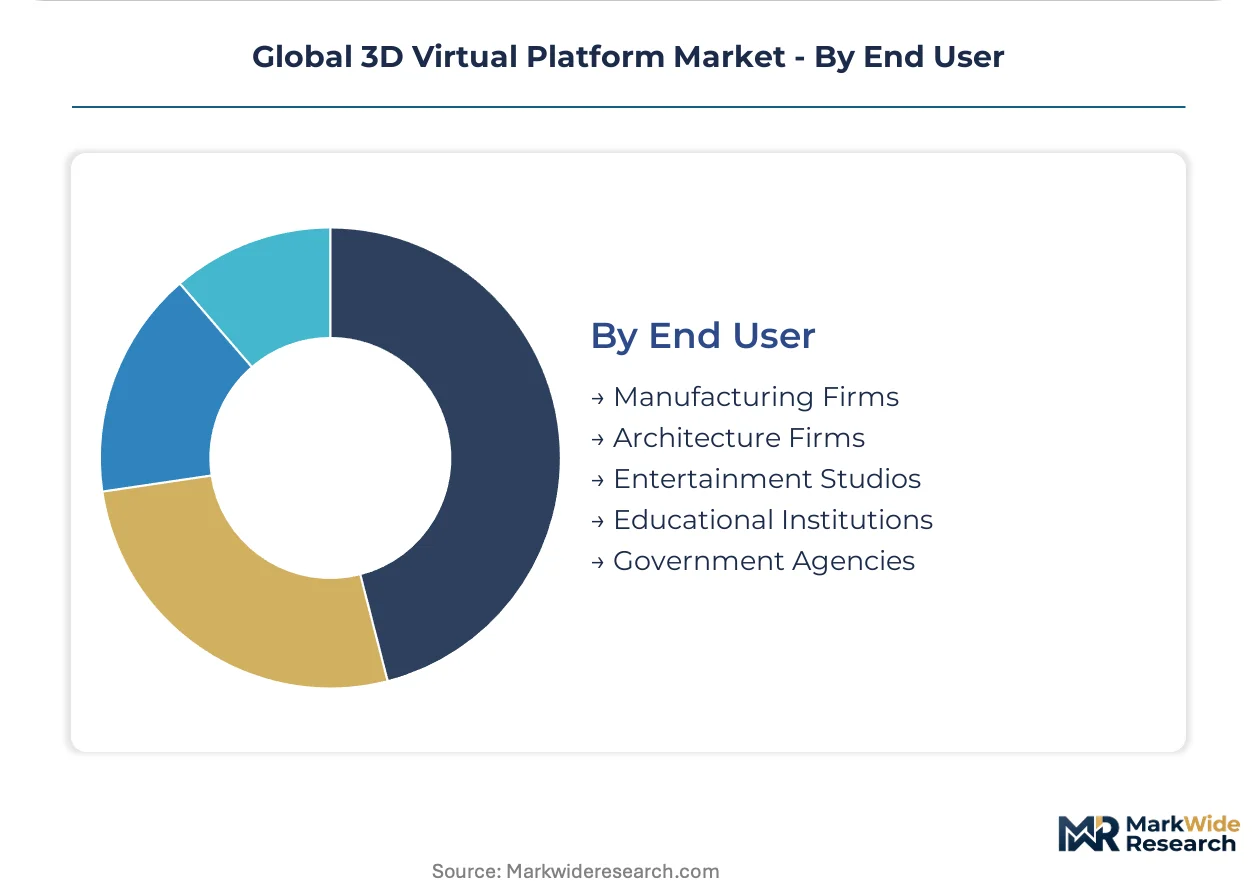
- Manufacturing Firms:Industrial engineering divisions demand ISO 27001 certification, SOC 2 Type II attestation, and sector-specific automotive or aerospace quality accreditation. German automotive suppliers and Japanese precision manufacturers represent the most technically demanding buyer cohort.
- Government Agencies:Defense, intelligence, and civilian infrastructure departments require FedRAMP, ITAR, or equivalent national security clearances with data residency guarantees. Procurement cycles extend 14-18 months but lock in multi-year enterprise agreements.
- Architecture Firms:Design visualization and client presentation workflows prioritize photorealistic rendering speed over simulation fidelity.
- Entertainment Studios:Virtual production stages and pre-visualization pipelines integrate game engine technology with traditional filmmaking workflows.
- Educational Institutions:Saudi and UAE national universities are expanding virtual laboratory infrastructure through government scholarship program funding.
Complex procurement maturity sits with Manufacturing Firms. Fastest budget expansion is concentrated in Educational Institutions across Middle Eastern markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform deployment concentrates where industrial digitization budgets intersect with regulatory clarity. Consumption clusters in Germany, Japan, and the United States, while cloud infrastructure provisioning spreads across Singapore, Ireland, and Netherlands data center corridors.
Germany
Automotive design studios in Stuttgart and Wolfsburg drive enterprise platform adoption for supplier network coordination. The EU AI Act mandates algorithmic transparency documentation from immersive simulation vendors, compressing procurement timelines for compliant providers. Bavarian industrial consortia now require FBX and USDZ interoperability certifications as bid prerequisites for smart factory transformation grants.
United States
Energy sector operators in Texas and North Sea-linked training providers expand seat-hour subscriptions for hazard rehearsal environments. The FCC governs spectrum allocation for millimeter-wave VR headsets, constraining wireless fidelity in large-scale simulation facilities. Houston utilities pilot consumption-metered immersive training tied to actual seat-hours rather than named user counts.
Japan
Precision manufacturers in Osaka and Nagoya fuse real-time sensor feeds with persistent virtual environments through METI-backed interoperability frameworks. METI standardized data exchange protocols mandate open asset formats for cross-sector digital twin exchange. Automotive suppliers without certified interoperability lose bid eligibility for subsidized smart factory grants in the Chubu industrial corridor.
Saudi Arabia
Government scholarship programs fund virtual laboratory expansion at national universities, creating concentrated demand for STEM-focused 3D platforms. The SFDA and national data sovereignty requirements shape procurement criteria for educational infrastructure. Riyadh and Jeddah campuses anchor Middle Eastern educational deployment for immersive science training.
Singapore
Property developers adopt light-field capture pipelines to generate explorable digital twins from drone photogrammetry within hours. The country's national data residency framework governs cross-border immersive session hosting for financial services clients. Marina Bay and Jurong Lake District projects showcase compressed visualization timelines overtaking conventional 3D modeling contracts.
Global 3D Virtual Platform Market Competitive Landscape
The competitive structure tilts toward specialization-driven differentiation rather than scale consolidation. Vendor density remains moderate, with clear stratification between cloud-native entrants and legacy on-premise incumbents rearchitecting compute stacks. Three archetypes dominate: educational laboratory specialists, hybrid deployment architects serving sovereign data requirements, and event-centric environment providers. Competitive moves concentrate on interoperability certification racing and edge-cloud hybrid architecture development.
Within the educational specialization tier, PraxiLabs anchors demand across Middle Eastern universities through virtual laboratory infrastructure. Spektra Systems LLC occupies a position among hybrid deployment architects addressing government agency data sovereignty requirements. Samaaro exemplifies the event-centric archetype with enterprise marketing environment differentiation. These three entities represent distinct competitive vectors rather than overlapping market contests.
| Leading Market Players |
|---|
| PraxiLabs |
| Spektra Systems LLC |
| Samaaro |
| PandaMR |
| MootUp |
| 3D Bear |
| Outreal XR |
| Holo-SDK |
| Wevr |
| Others |
Supply & Pricing Matrix
Captive GPU sourcing from Taiwan Semiconductor Manufacturing anchors vendor cost structures and compresses margin flexibility across deployment tiers. This upstream concentration forces platform providers to absorb allocation volatility or pass through silicon scarcity premiums to enterprise buyers locked into multi-year training contracts.
Pricing Analysis
Margin tightening in cloud-native tiers reflects foundry allocation bottlenecks and elastic compute scaling demands from German automotive studios. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 27001 certification grade and concurrent user concurrency. Cost compression in on-premise configurations accelerates because defense contractors demand air-gapped deployments with extended refresh cycles. Government agencies with FedRAMP requirements show least price sensitivity; educational institutions in Saudi Arabia exhibit highest elasticity to seat-hour metering.
Supply Chain Analysis
Spatial computing talent scarcity in the United States, Germany, and Japan constrains platform development velocity and inflates specialized labor premiums. High-performance GPU silicon, real-time engine middleware, and photogrammetry capture hardware feed from concentrated technology corridors. Single-source vulnerability at Taiwan Semiconductor Manufacturing exposes vendors to allocation rationing during demand surges. Distribution runs through hyperscaler marketplaces and specialized systems integrators serving defense and energy verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act erects a cost-of-compliance moat that favors incumbent vendors with existing algorithmic transparency documentation and accelerates attrition among undercapitalized entrants lacking certification infrastructure.
For Market Incumbents: Hedge against GPU supply volatility through multi-foundry qualification programs and strategic buffer inventory positions in edge computing hardware. Fortify certification moats by accelerating SOC 2 Type II and sector-specific healthcare accreditation timelines ahead of EU CSRD disclosure mandates. Channel control through exclusive systems integrator partnerships locks out emerging hybrid deployment specialists. For New Entrants and Emerging Players: Specialized channel partners in Middle Eastern educational infrastructure offer the most penetrable entry vector for STEM-focused virtual laboratory platforms. White-space concentration in Saudi and UAE government scholarship programs rewards localized Arabic-language content development and SFDA compliance pre-certification. Target consumption-metered seat-hour models rather than perpetual licensing to bypass incumbent procurement lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in platform integration acquisitions by hyperscalers seeking immersive collaboration capabilities. Long-term viability hinges on interoperability certification racing rather than raw rendering performance. Watch METI-backed digital twin standardization velocity as the inflection signal for Japanese market consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Racing | FBX and USDZ compatibility unlocks METI-subsidized smart factory grants in Japan's Chubu corridor. |
| Edge-Cloud Hybrid Architecture Development | Split-render configurations capture government agency demand with strict data sovereignty requirements. |
| Consumption-Metered Subscription Pivot | Seat-hour billing aligns with North American utility procurement shifts away from perpetual licensing. |
| Gaussian Splatting Pipeline Investment | Light-field capture compression displaces conventional 3D modeling contracts in Singapore property development. |
| Spatial Computing Talent Acquisition | Gaming industry veteran recruitment accelerates real-time engine optimization capabilities. |
Research Methodology
Independent corroboration across platform engineering directors, enterprise IT procurement officers, and hyperscaler partnership leads underwrites the qualitative findings. Primary fieldwork with automotive design studio technical architects, defense contractor simulation leads, and Middle Eastern university CIOs combined with secondary validation from SEC hyperscaler capex disclosures, METI standardization guidelines, and EU regulatory filings. Bottom-up deployment topology sizing triangulates against top-down industrial digitization budget forecasts.
Comparable-period anchoring to historical cloud infrastructure provisioning and immersive hardware shipment patterns established the forecast baseline across the analysis window. Segmentation modeling incorporated deployment topology, solution functionality, end-use operational integration depth, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves weighted by compliance mandate acceleration in European manufacturing and scholarship program funding velocity in Saudi Arabia.
Several conditions sit outside the modeled scope, including unannounced FCC spectrum reallocation decisions, TSMC foundry expansion delays, and emergent neural rendering technique disruption. Forecasts reflect documented assumptions about interoperability standardization timelines and GPU supply normalization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
APAC 3D 4D Technology Market
3D Technology
LAMEA Smartphone 3D Camera Market
3D Technology
North America 3D 4D Technology Market
3D Technology
3D CAD Market
3D Technology
3D Reconstruction Market
3D Technology
Molecular Modeling Market
3D Technology
UK 3D Rendering Services Market
3D Technology
Middle East and Africa 3D 4D Technology Market
3D Technology
3D Reconstruction Technology Market
3D Technology
Digital Holography Market
3D Technology
Spatial Computing Market
3D Technology
3D Mobile Mapping Market
3D Technology
3D Scanning Market
3D Technology
3D Scanner Market
3D Technology
Global Mobile 3D Sensing Market
3D Technology
Contactless 3D Laser Scanner Market