
 Latin America 3D 4D Technology Market | 2026-2036
Latin America 3D 4D Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America 3D 4D Technology Market Foresight
Specialized additive manufacturing technicians across Latin America is bifurcating the competitive landscape into firms that can secure talent and those that cannot. 3D Systems Corporation leverages its established dental and medical training programs to build regional technician pipelines. Stratasys anchors its position through polymer expertise and localized service networks in Mexico and Brazil. Materialise NV differentiates via software-to-hardware integration and patient-specific implant workflows.
Latin America 3D 4D Technology encompasses volumetric capture, additive fabrication, and time-variant visualization systems that render spatial data across physical and digital environments, typically operating through layer-by-layer deposition or light-field projection at resolutions down to 50 microns for industrial-grade printers. These systems serve primarily to compress product development cycles, enable patient-specific medical interventions, and generate immersive training environments across commercial and institutional settings. 3D Printers currently dominate hardware revenue flows due to industrial maintenance and medical device fabrication demand, while 4D Visualization Tools represent the fastest-expanding category as healthcare networks invest in surgical planning platforms. The Entertainment end-user segment sustains steady projector and holography uptake, though Healthcare applications command superior margin pools through regulatory-certified device sales.
Brazil's ANVISA governs medical device registration and clinical validation requirements, directly shaping market access timelines for 3D-printed implants and surgical guides. Mexico's COFEPRIS and Argentina's ANMAT maintain parallel device oversight frameworks that manufacturers must navigate for multi-country product rollouts. Stakeholders should monitor regulatory harmonization progress across Mercosur and Pacific Alliance trade blocs, as alignment would reduce redundant certification costs and accelerate cross-border technology deployment.
Market Dynamics
ANVISA's streamlined registration pathways for patient-specific implants are compressing approval timelines and redrawing competitive boundaries for 3D-printed medical devices across Brazil's hospital networks.
Growth Catalysts
- ANVISA Fast-Track Pathways:Brazil's medical device regulator accelerates market entry for 3D-printed implants through dedicated orthopedics and dental channels, reducing validation cycles for manufacturers targeting São Paulo's hospital clusters.
- Surgical Planning Visualization:Healthcare providers in Mexico and Brazil deploy 4D imaging platforms for pre-operative simulation, creating pull for volumetric capture hardware and software subscriptions.
- Polymer Expertise Localization:Regional service networks for industrial-grade polymer deposition systems shorten maintenance response times for automotive and aerospace tooling shops.
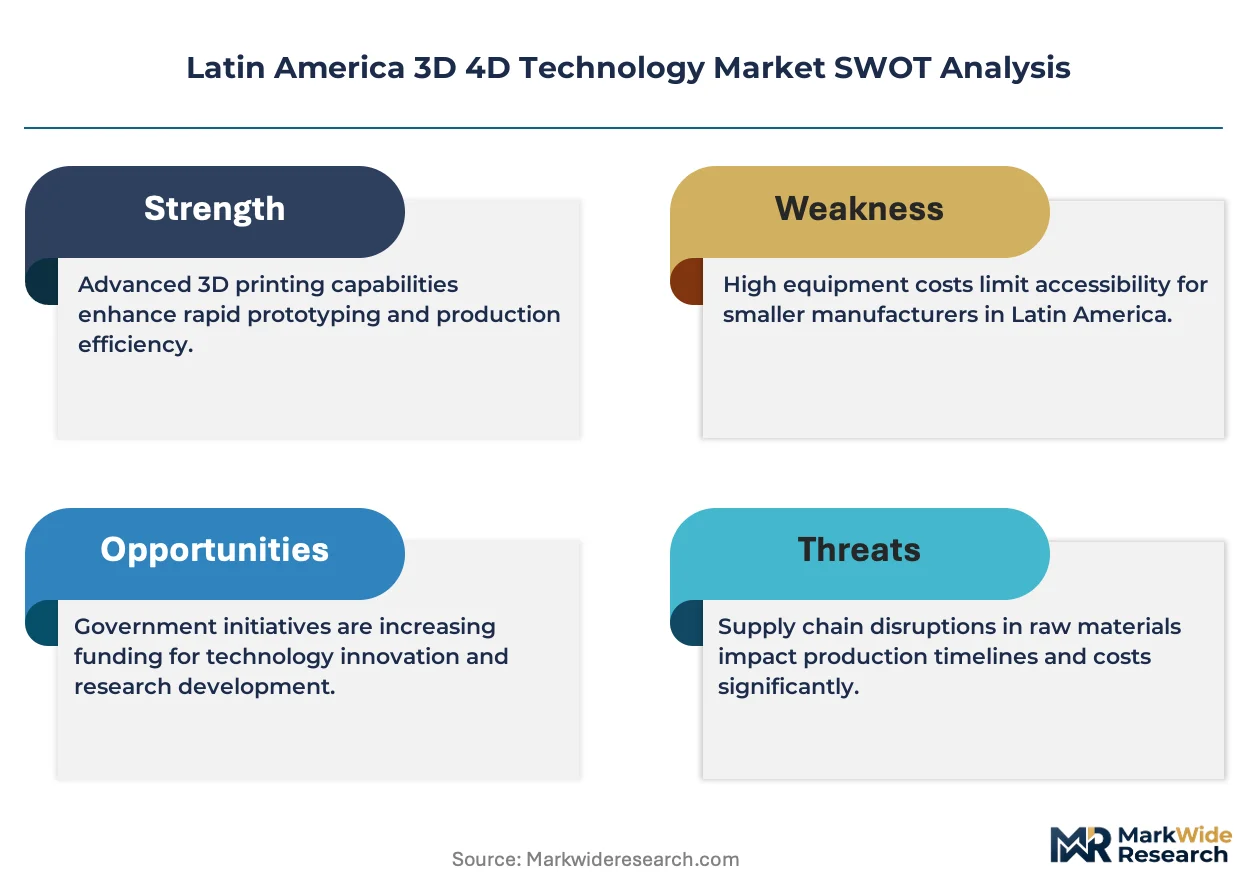
Market Restraints
- Specialized Technician Scarcity:Additive manufacturing certification programs produce insufficient qualified operators, constraining service expansion for medical device fabricators.
- Capital Equipment Intensity:Industrial-grade metal powder bed fusion systems require seven-figure USD investments, excluding mid-sized dental laboratories from in-house production.
- COFEPRIS Parallel Requirements:Mexico's pharmaceutical and medical device regulator maintains distinct clinical validation standards from ANVISA, forcing redundant testing for cross-border product rollouts.
Strategic Opportunities
- Argentina ANMAT Alignment:Regulatory harmonization discussions across Mercosur trade blocs could collapse redundant certification costs for manufacturers seeking access to Buenos Aires medical centers.
- 4D Visualization in Veterinary Care:Animal health clinics in São Paulo and Mexico City represent an untapped vertical for surgical planning software originally developed for human orthopedics.
- Remote Service Channel Expansion:Augmented reality troubleshooting tools enable equipment vendors to resolve printer downtime without dispatching technicians to Chilean mining equipment maintenance sites.
Industry Challenges
- Biocompatible Material Certification Lag:Novel titanium alloys and PEEK composites await ANVISA material master file approvals, freezing product pipeline advancement for cranial implant specialists.
- Legacy PACS Integration Friction:Hospital radiology departments struggle to route 3D volumetric data into existing picture archiving systems, delaying surgical planning workflow adoption.
- Cross-Border Spare Parts Logistics:Customs clearance variability for precision optical components disrupts SLA printer uptime guarantees for Brazilian dental laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America 3D 4D Technology Market |
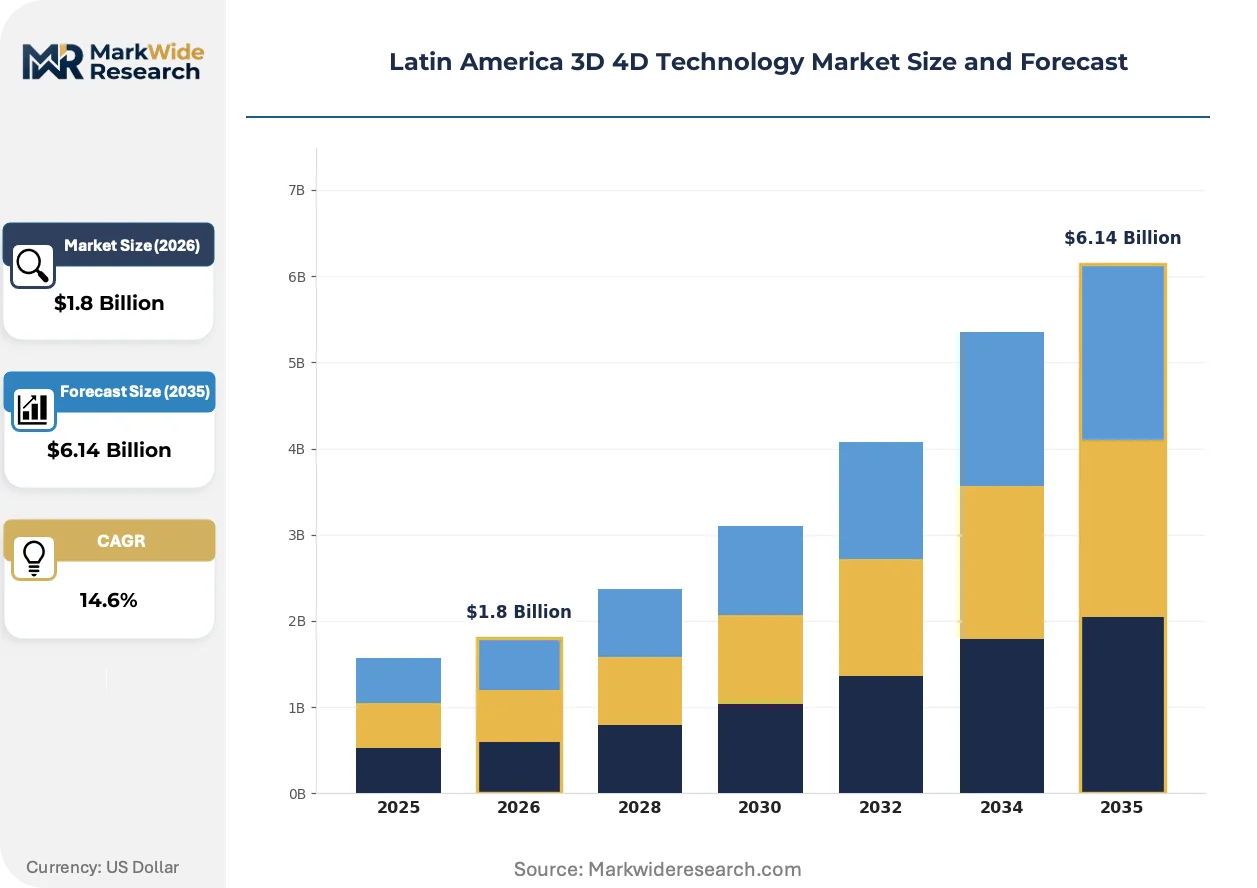
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Scanners, 4D Projectors, 3D Printers, 4D Visualization Tools End User: Entertainment, Education, Healthcare, Automotive Technology: Virtual Reality, Augmented Reality, Mixed Reality, Holography Application: Product Design, User Experience, Medical Imaging, Simulation |
| Companies Covered | Samsung Electronics Co., Ltd., Matterport, Inc., 3D Systems Corporation, Stratasys, Dassault Systèmes, Dolby Laboratories, Inc., Panasonic Corporation, Materialise NV, LG Electronics Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America 3D 4D Technology Market Shifts & Advancements
Digital light processing hardware is compressing production cycles for dental crown fabrication while regulatory pressure on biocompatible materials intensifies certification requirements across Latin American health systems.
Photopolymer vat polymerization is supplanting filament deposition in high-throughput dental laboratories across São Paulo and Mexico City. Prosthodontics specialists adopt sub-50-micron resolution printers for same-day crown production. This technology shift is supplanting traditional milling centers and compressing patient appointment cycles from weeks to single-visit workflows.
COFEPRIS and ANVISA are converging on ISO 13485 quality management requirements for custom medical device manufacturers. This regulatory alignment reduces documentation duplication for firms operating across the Mexico-Brazil corridor. Dental implant guide producers now maintain unified audit trails satisfying both regulators through centralized quality systems.
Hospital procurement committees in Brazil's southeast region now mandate software-to-hardware integration certifications before approving 3D imaging capital expenditures. This behavioral shift disadvantages standalone printer vendors and elevates vendors offering surgical planning platform bundles. São Paulo's largest private hospital network recently consolidated supplier relationships to three integrated workflow providers.
Latin America 3D 4D Technology Market Segmentation
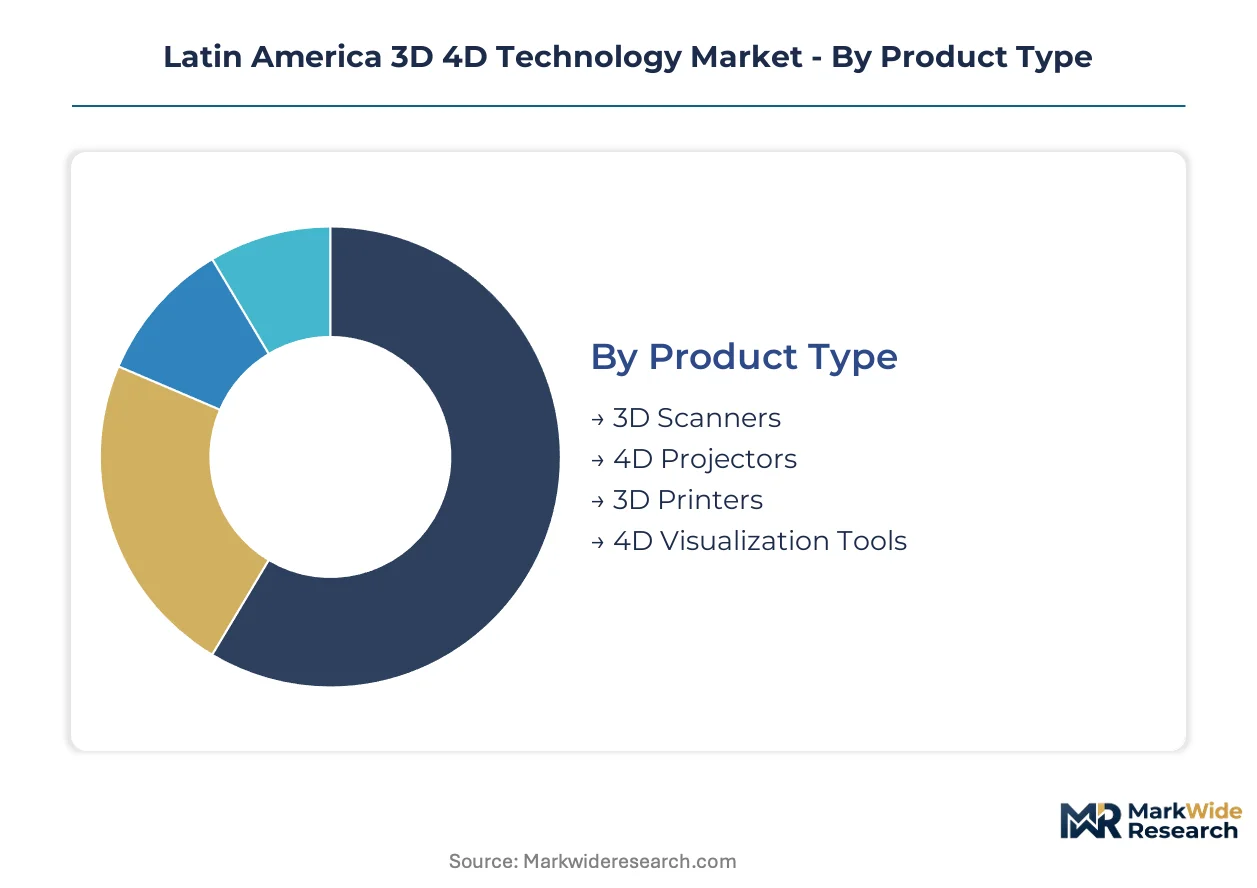
Technology substitution pressures are fragmenting demand across Latin America's 3D 4D landscape, with hardware categories facing divergent replacement cycles and software platforms capturing recurring revenue streams. Segmentation clarity enables vendors to align R&D investments with specific regulatory pathways and end-user procurement behaviors.
Product Type:
Photopolymer vat polymerization and metal powder bed fusion systems are displacing legacy filament deposition hardware in São Paulo dental laboratories, compressing equipment replacement cycles and redrawing vendor market share.
- 3D Printers:Industrial-grade systems utilizing stereolithography and selective laser sintering dominate hardware revenue through medical device fabrication and automotive tooling maintenance contracts. Demand concentrates in Brazil's São Paulo state where hospital networks and dental distributors cluster around ANVISA-registered implant producers.
- 4D Visualization Tools:Time-variant rendering platforms enable pre-operative surgical simulation and immersive training environments through volumetric capture and light-field projection. Mexican healthcare providers in Mexico City and Guadalajara are deploying these systems for orthopedic planning, creating pull for software subscription models.
- 3D Scanners:Structured light and laser triangulation systems serve reverse engineering and quality control workflows for aerospace maintenance shops.
- 4D Projectors:Holographic and volumetric display hardware sustains steady uptake in entertainment venues and museum installations across Buenos Aires and Rio de Janeiro.
3D Printers retain volume leadership; 4D Visualization Tools hold the steepest expansion curve.
End User:
Margin structures diverge sharply across customer categories, with regulatory-certified medical sales commanding premium pricing while entertainment deployments compete on equipment lease rates.
- Healthcare:Hospitals and specialized clinics deploy patient-specific implant fabrication and surgical planning platforms under ANVISA and COFEPRIS oversight. São Paulo's largest private hospital network recently consolidated supplier relationships to three integrated workflow providers, elevating vendors offering software-to-hardware bundles.
- Automotive:Tooling shops and OEM maintenance facilities utilize polymer deposition systems for jigs, fixtures, and end-use component production. Mexican maquiladora operations near the US border are localizing additive manufacturing to compress supply lead times for legacy vehicle part replacement.
- Entertainment:Cinema chains and live event producers sustain projector and holography hardware demand through equipment refresh cycles.
- Education:Universities and technical institutes adopt entry-level filament printers and basic visualization kits for engineering curriculum.
Healthcare commands the highest margin pool; Automotive offers the most scalable volume pathway.
Technology:
Hardware-software integration requirements are favoring platforms that combine spatial computing with existing enterprise IT infrastructure over standalone immersive devices.
- Augmented Reality:Overlay systems integrating 3D volumetric data into surgical workflows and maintenance procedures are gaining traction among Brazilian hospital procurement committees. These platforms require precise alignment with legacy PACS infrastructure, creating integration friction that advantages established medical IT vendors.
- Virtual Reality:Fully immersive headsets serve training simulation and design review applications where environmental control is feasible. Mexican automotive suppliers utilize VR for assembly line ergonomics studies prior to physical retooling investments.
- Mixed Reality:Passthrough camera systems enabling simultaneous physical and digital interaction remain nascent in Latin American deployments due to hardware cost and technician training requirements.
- Holography:Volumetric display technologies sustain niche adoption in medical education and museum exhibition contexts.
Augmented Reality captures the dominant deployment share; Virtual Reality maintains the broadest application range.
Application:
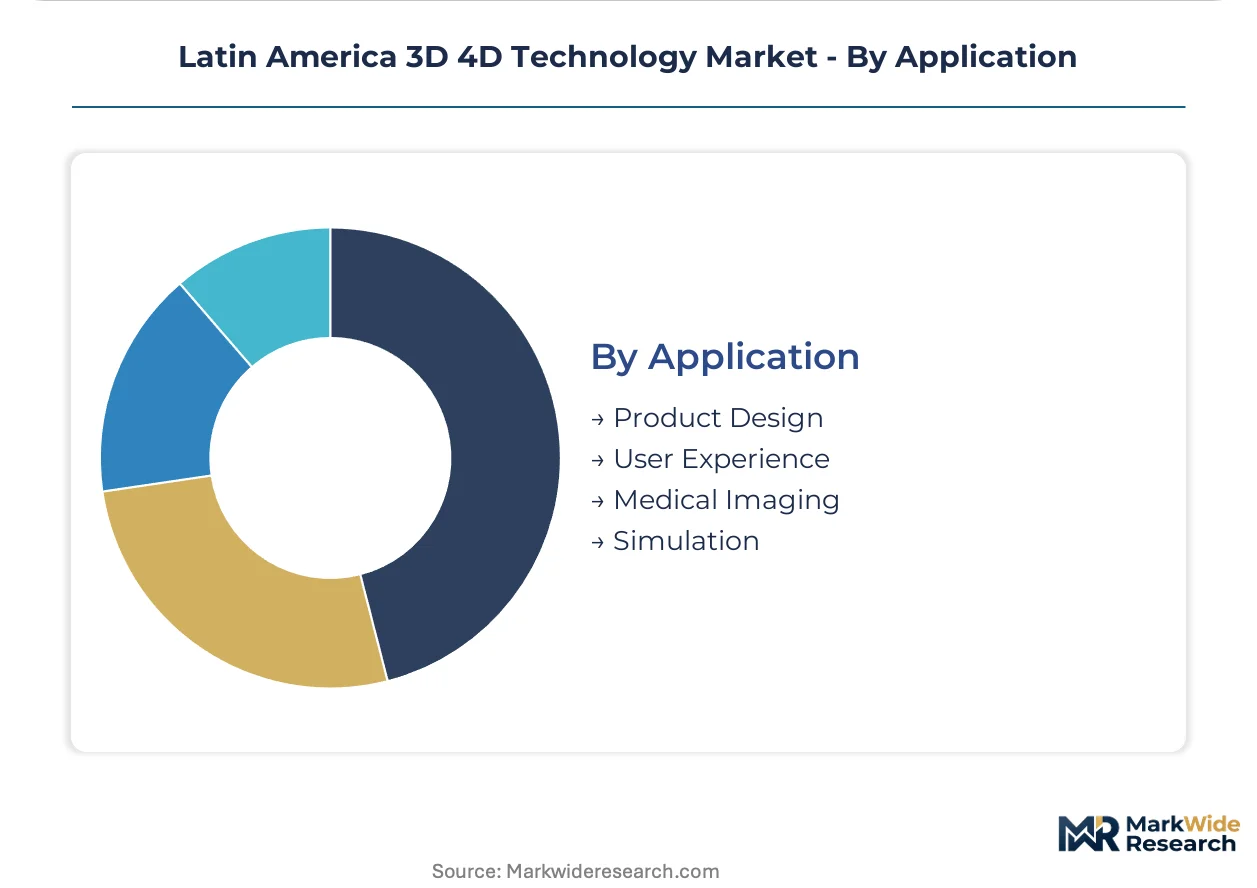
Workflow integration complexity varies dramatically across use cases, with regulated medical applications requiring extensive validation while product design tools face lighter adoption barriers.
- Medical Imaging:3D reconstruction from CT and MRI data enables patient-specific surgical planning and custom implant design under ANVISA material master file requirements. Brazilian cranial implant specialists await biocompatible titanium alloy and PEEK composite approvals, freezing pipeline advancement for novel material formulations.
- Product Design:Rapid prototyping and iterative development cycles compress time-to-market for consumer goods and industrial equipment. Argentine manufacturers in Buenos Aires utilize polymer deposition for fit-check prototypes prior to tooling commitment.
- Simulation:Physics-based modeling environments support training and operational planning across healthcare and industrial contexts.
- User Experience:Spatial interface prototyping serves software development and retail environment design applications.
Product Design retains the widest cross-industry footprint; Medical Imaging carries the highest regulatory barrier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA governs Brazil's medical device registration pathways, compressing approval timelines for patient-specific implants and anchoring regional demand concentration in São Paulo's hospital networks.
Brazil
Surgical planning visualization platforms drive hospital procurement in São Paulo state, where private networks consolidate supplier relationships. ANVISA's streamlined orthopedics and dental channels accelerate 3D-printed implant validations. São Paulo's medical device distributors cluster around ANVISA-registered producers, creating dense service ecosystems for additive manufacturing hardware.
Mexico
Maquiladora operations near the US border localize additive manufacturing for automotive tooling and legacy vehicle part replacement. COFEPRIS maintains distinct clinical validation standards from ANVISA, forcing redundant testing for cross-border medical device rollouts. Mexico City and Guadalajara healthcare providers deploy 4D imaging platforms for orthopedic surgical simulation.
Argentina
Buenos Aires manufacturers utilize polymer deposition systems for rapid prototyping of consumer goods and industrial equipment fit-checks. ANMAT oversees medical device oversight frameworks parallel to Brazilian and Mexican regulators. Regulatory harmonization discussions across Mercosur trade blocs could collapse redundant certification costs for implant producers targeting Argentine medical centers.
Chile
Mining equipment maintenance sites demand remote service capabilities for industrial-grade printer uptime. The country's national mining regulator shapes safety certification requirements for additive-manufactured replacement components. Santiago-based technical institutes adopt entry-level visualization kits for engineering curriculum expansion.
Colombia
Healthcare networks in Bogotá evaluate surgical planning software originally developed for human orthopedics for veterinary care applications. The national pharmaceutical and medical device regulator maintains distinct validation pathways from regional counterparts. Medellín's technical universities build additive manufacturing technician pipelines through specialized certification programs.
Latin America 3D 4D Technology Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with differentiation hinging on software-to-hardware bundling and regulatory certification depth. Market structure favors vendors offering surgical planning platform integrations over standalone printer manufacturers. Three archetypes dominate: integrated workflow providers, polymer expertise specialists, and software-centric platforms. Competitive moves center on technician training program expansion and localized service network densification.
Within the integrated workflow tier, 3D Systems Corporation and Stratasys exemplify contrasting geographic anchoring strategies, while Materialise NV occupies a position emphasizing software-to-hardware integration. Samsung Electronics Co., Ltd. and LG Electronics Inc. represent diversified electronics conglomerates with display and visualization hardware portfolios. Panasonic Corporation and Dolby Laboratories, Inc. anchor positions in audio-visual and projection technologies serving entertainment and simulation applications.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Matterport, Inc. |
| 3D Systems Corporation |
| Stratasys |
| Dassault Systèmes |
| Dolby Laboratories, Inc. |
| Panasonic Corporation |
| Materialise NV |
| LG Electronics Inc. |
| Others |
Supply & Pricing Matrix
Long-term service contracts with embedded capacity reservations lock in supply access for industrial-grade metal powder bed fusion systems while anchoring price visibility for Brazilian hospital procurement committees navigating ANVISA certification timelines. These arrangements bundle hardware, biocompatible material supply, and technician training into multi-year commitments that insulate buyers from spot market volatility in titanium alloy feedstocks.
Pricing Analysis
Brazil-Mexico price spreads for equivalent photopolymer vat polymerization systems run 15-25% above US reference levels due to import duties and distributor margin stacking. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-certified medical configurations from uncertified prototyping hardware and entry-level education units. Cost compression in standard-tier dental laboratory equipment is intensifying because Stratasys and 3D Systems are localizing polymer resin production near São Paulo. Mid-sized dental laboratories exhibit highest price sensitivity, while integrated hospital networks prioritize certification depth over unit economics.
Supply Chain Analysis
Precision optical component fabrication for stereolithography systems concentrates in Germany, Japan, and the United States, creating single-source vulnerability for Brazilian dental laboratories awaiting customs-cleared replacement parts. The regional supply chain draws from Chinese titanium powder producers, Belgian software development centers, and Mexican polymer compounding facilities. Tariff exposure runs through Mercosur extra-bloc sourcing for metal feedstocks. Distribution runs through São Paulo-based medical device distributors that maintain ANVISA-registered warehousing for implant-grade materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positions. ANVISA certification timelines and technician training pipelines erect switching costs that protect incumbent relationships.
For Market Incumbents: Consolidate service network density in São Paulo state to preempt emerging polymer specialists from securing maintenance contracts with hospital procurement committees. Deepen backward integration into biocompatible resin formulation to offset margin pressure from Chinese titanium powder suppliers. Defend against software-centric entrants by embedding surgical planning platforms into existing PACS infrastructure at Brazil's largest private hospital networks. For New Entrants and Emerging Players: Anchor in veterinary surgical planning applications across São Paulo and Mexico City, where regulatory barriers sit below human orthopedics thresholds. Target Colombia's Bogotá healthcare networks evaluating cross-species imaging platforms. Pursue equipment-as-a-service models with bundled technician training to circumvent capital intensity objections from mid-sized dental laboratories. For Investors and Strategic Acquirers: Capital is best deployed toward integrated workflow providers possessing ANVISA material master file portfolios and established hospital GPO relationships. Long-term viability hinges on regulatory certification depth rather than hardware performance specifications. Monitor ANMAT-COFEPRIS harmonization progress as the inflection signal for cross-border rollup opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Material Master File Expansion | Accelerates patient-specific implant approvals for cranial reconstruction specialists awaiting PEEK composite clearances. |
| Software-to-Hardware Bundling | Aligns with São Paulo hospital procurement mandates requiring integrated surgical planning platform certifications. |
| Technician Certification Pipeline Development | Addresses specialized operator scarcity constraining service expansion for medical device fabricators across Brazil. |
| Veterinary Application Extension | Opens white-space revenue in animal health clinics repurposing human orthopedics imaging platforms. |
| Remote AR Troubleshooting Deployment | Resolves printer downtime for Chilean mining equipment sites without dispatching field service engineers. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, dental laboratory proprietors, and ANVISA regulatory consultants anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, ANVISA registration databases, COFEPRIS device listings, and Mercosur trade flow records. Bottom-up equipment shipment estimates triangulated against top-down healthcare capital expenditure surveys.
Sensitivity analysis tested forecast robustness across alternative regulatory harmonization scenarios and titanium alloy price volatility assumptions. The analytical framework modeled segmentation dimensions including hardware technology tier, end-user vertical, software integration depth, and country-specific regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle compression trends. Key inputs encompassed ANVISA approval velocity indices and hospital procurement committee behavioral shifts toward bundled workflow providers.
Decision-makers should treat outputs as directional under sustained ANVISA fast-track pathway availability and stable Mercosur trade arrangements; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as COFEPRIS-ANVISA regulatory convergence and biocompatible material certification lag evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
UK 3D Rendering Services Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
Global 3D Architecture Software Market
3D Technology
3D Photogrammetry Software Market
3D Technology
3D Simulation Software Market
3D Technology
3D Geospatial Technologies Market
3D Technology
Glasses Free 3D Tvs Market
3D Technology
LAMEA Smartphone 3D Camera Market
3D Technology
3D Reconstruction Market
3D Technology
Smartphone 3D Camera Market
3D Technology
3D Scanning Market
3D Technology
APAC 3D Telepresence Market
3D Technology
Global 3D Rendering Service Market
3D Technology
Molecular Modeling Market
3D Technology
Contactless 3D Laser Scanner Market
3D Technology
3D Machine Vision Market